
 Influencer Marketing Platform Market | 2026-2036
Influencer Marketing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Influencer Marketing Platform Market Intelligence
Beauty and personal care is repositioning as the dominant end-use vertical for influencer marketing platforms, displacing traditional fashion-first spending patterns. CreatorIQ leverages predictive audience analytics to anchor enterprise relationships with multinational cosmetics conglomerates. LTK competes through proprietary shopping link technology that sustains commission-based creator monetization at scale.
An influencer marketing platform constitutes a software-as-a-service architecture that automates creator discovery, campaign orchestration, performance attribution, and payment settlement across social media channels, typically integrating APIs from Instagram, TikTok, and YouTube to ingest engagement metrics in near real time. Campaign management functionality dominates current revenue pools as brands prioritize workflow centralization, while artificial intelligence and machine learning segments within the technology dimension are capturing the fastest expansion as natural language processing and computer vision automate creator-brand matching and fake-follower detection. Subscription pricing models remain structurally entrenched among mid-market buyers, though performance-based arrangements are gaining traction where return-on-ad-spend verification is paramount.
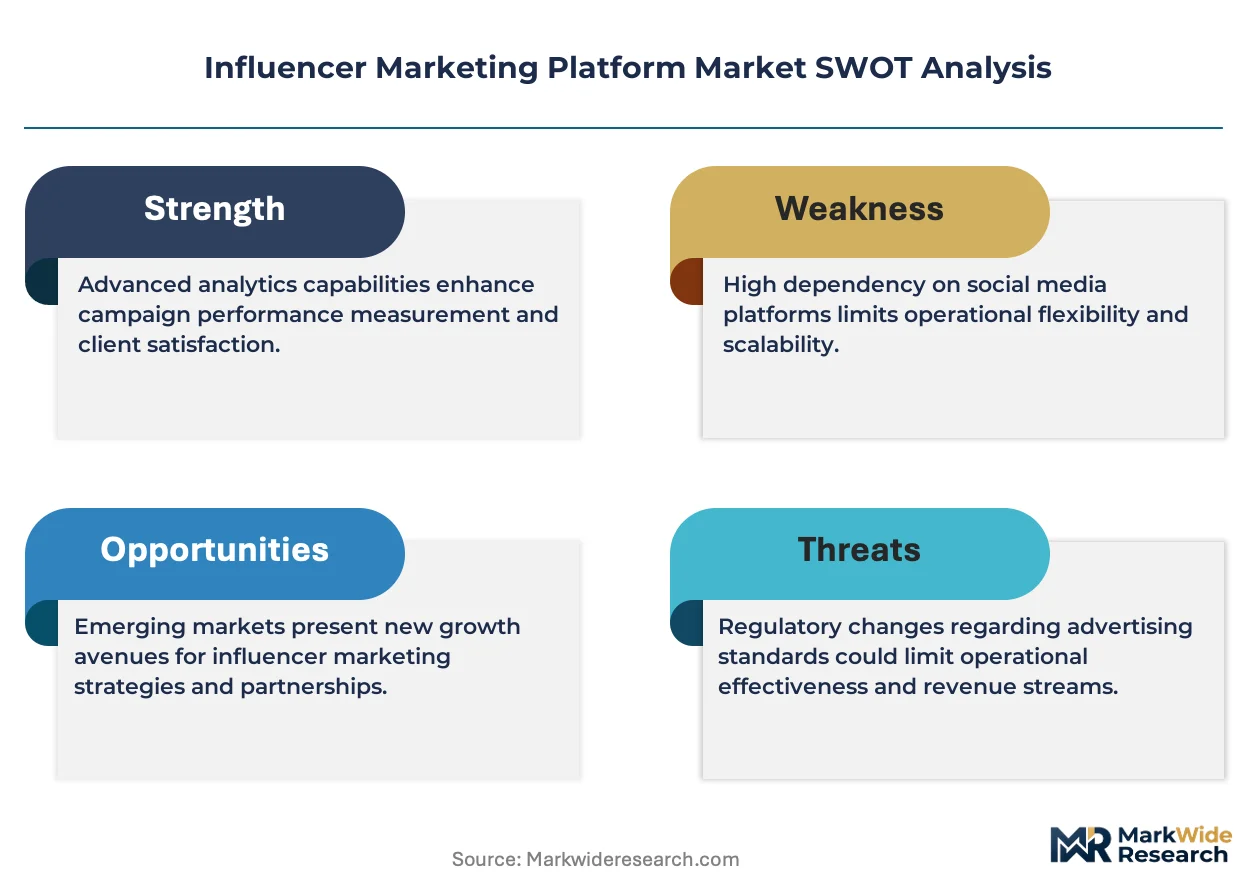
The Federal Trade Commission in the United States enforces endorsement disclosure guidelines that mandate clear labeling of paid partnerships, while the EU Digital Services Act imposes algorithmic transparency requirements on platforms hosting influencer content. India's Central Consumer Protection Authority has issued specific guidelines prohibiting misleading advertisements through virtual influencers, creating compliance complexity for platforms operating across jurisdictions. Stakeholders must monitor evolving platform liability frameworks as regulators increasingly assign accountability to intermediary software providers rather than solely to brands or individual creators.
Market Dynamics
Social commerce infrastructure is absorbing creator monetization workflows, compressing campaign execution timelines from weeks to hours as TikTok Shop and Instagram Reels commerce embed native checkout directly within discovery feeds.
Growth Catalysts
- EU Digital Services Act:Algorithmic transparency mandates for sponsored content are forcing platform upgrades that improve brand safety verification and expand enterprise software procurement.
- Beauty and personal care vertical:Cosmetics conglomerates are consolidating influencer spend onto centralized platforms as social commerce integrations deepen product-to-purchase attribution.
- Computer vision for fake-follower detection:Automated audience quality scoring is reducing fraud risk and accelerating enterprise adoption of performance-based pricing models.
Market Restraints
- API rate limits from Meta and ByteDance:Platform dependency on social network data feeds creates operational fragility when access terms tighten or pricing escalates.
- Cross-jurisdiction compliance costs:India's Central Consumer Protection Authority virtual influencer guidelines impose documentation burdens that scale with geographic expansion.
- Creator payment settlement complexity:Multi-currency, cross-border payment rails for distributed creator networks inflate back-office overhead and delay financial close cycles.
Strategic Opportunities
- Southeast Asia demand clusters:Indonesia, Vietnam, and Thailand exhibit underpenetrated platform adoption where TikTok Shop commerce infrastructure is accelerating faster than Western markets.
- Natural language processing convergence with predictive analytics:Automated creator-brand matching engines are opening white-space in mid-market segments previously served by manual agency processes.
- US FTC endorsement disclosure automation:Compliance-as-a-service modules represent a regulatory tailwind for platforms that embed disclosure workflows directly into campaign orchestration tools.
Industry Challenges
- Data science talent scarcity:Platforms struggle to hire machine learning engineers capable of building real-time engagement prediction models at enterprise scale.
- Legacy CRM integration friction:Marketing technology stacks at multinational brands require custom API development to synchronize influencer campaign data with existing customer data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influencer Marketing Platform Market |
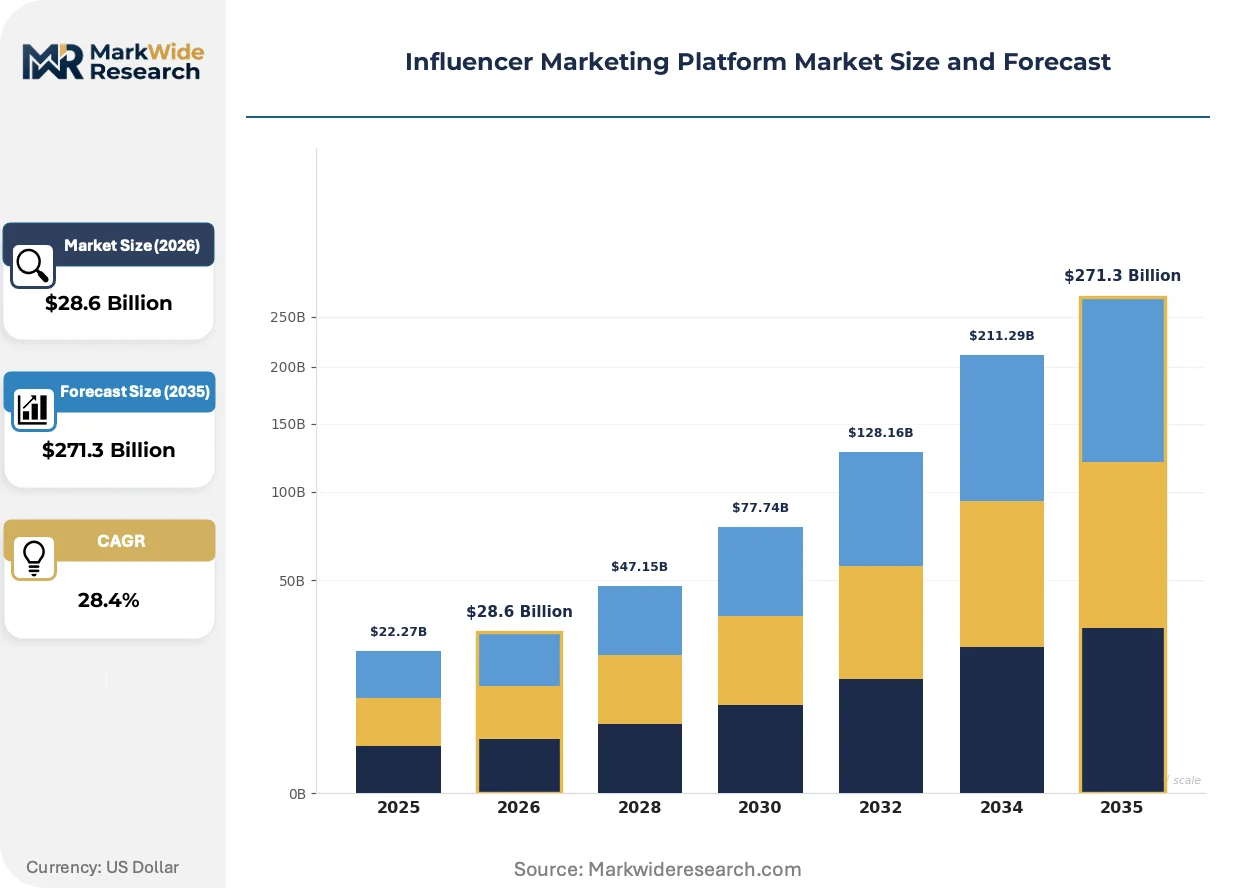
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $271.3 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Campaign Management, Analytics, Content Creation, Influencer Identification End User: Brands, Agencies, Publishers, Small Businesses Technology: Artificial Intelligence, Blockchain, Machine Learning, Big Data Pricing Model: Subscription, Pay-Per-Use, Tiered Pricing, Performance-Based |
| Companies Covered | Brandwatch, Influencity, Sprout Social Influencer Marketing, LTK, Modash, Upfluence, Aspire, Meltwater, CreatorIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influencer Marketing Platform Market Strategic Shifts & Innovations
Artificial intelligence is compressing the creator-brand matching cycle from manual search to algorithmic recommendation, while regulatory transparency mandates and shifting procurement patterns are redefining platform value propositions.
Generative AI content tools are absorbing routine creative production tasks for influencer campaigns. Mid-market beauty brands are adopting these tools fastest, deploying automated video editing and caption generation to reduce per-campaign creative costs. The technology is absorbing budget share previously allocated to creative agencies and freelance production teams.
The EU Digital Services Act imposes algorithmic transparency requirements on platforms hosting influencer content. This policy forces disclosure of recommendation system logic and sponsored content ranking factors. Enterprise influencer marketing platforms serving EU-based brands are responding by building audit trails and explainability dashboards that document content distribution mechanics.
Performance-based contracting is displacing pure subscription pricing among return-on-ad-spend-sensitive buyers. Direct-to-consumer brands with thin margins are leading this shift, negotiating platform fees tied to attributable revenue rather than seat licenses. This pattern is most visible in the United States where attribution technology maturity supports outcome verification at scale.
Influencer Marketing Platform Market Segmentation
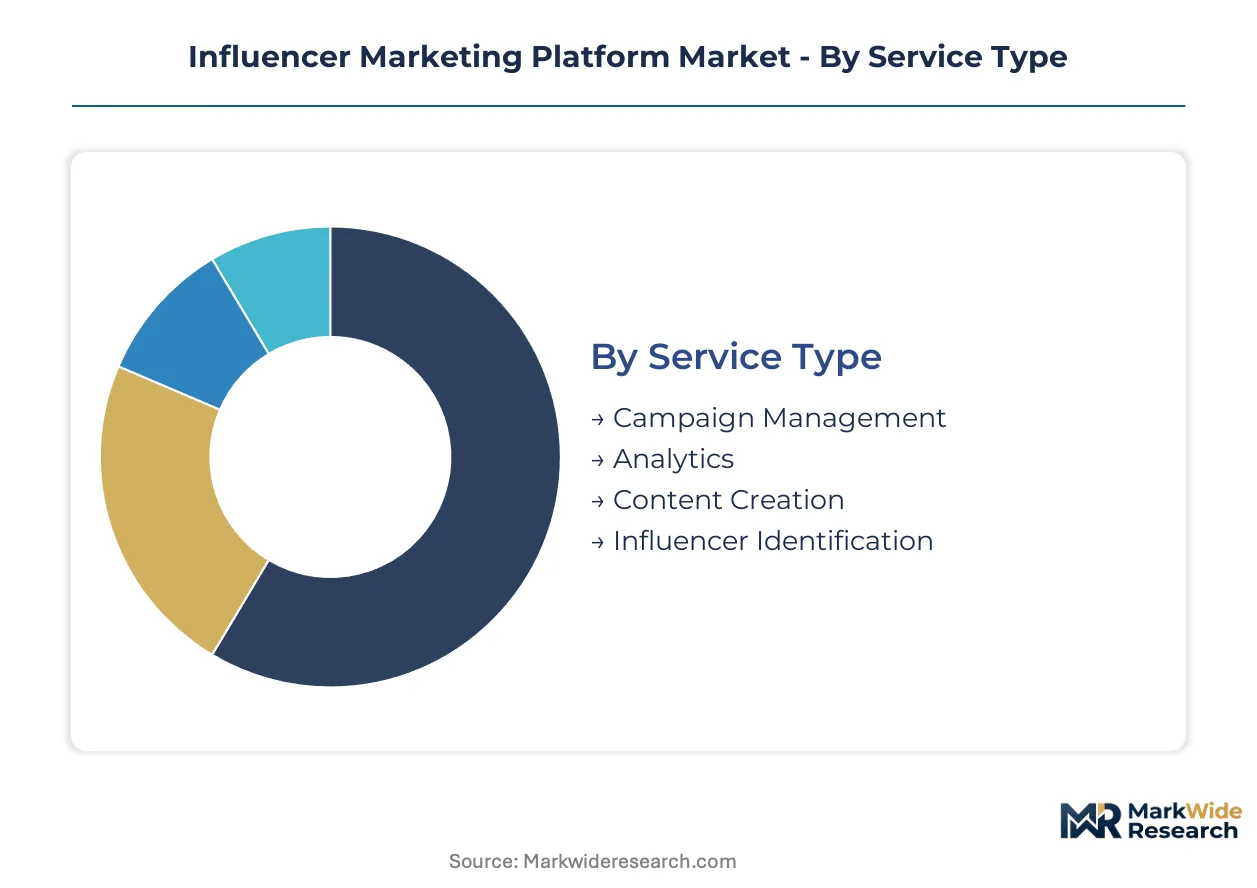
Segmentation in influencer marketing platforms reveals how procurement priorities diverge across buyer sophistication levels. Technology investments and pricing flexibility now determine competitive positioning more than feature breadth alone.
Service Type:
Upgrade cycles in this category accelerate as brands consolidate fragmented point solutions into unified orchestration suites.
- Campaign Management:Workflow automation engines coordinate creator outreach, contract execution, and content scheduling across Instagram, TikTok, and YouTube APIs. Enterprise cosmetics brands in France and Germany are consolidating spend here as social commerce integrations compress execution timelines.
- Analytics:Attribution dashboards ingest engagement metrics, audience demographics, and conversion events to calculate return-on-ad-spend. Direct-to-consumer brands in the United States with thin margins prioritize this segment for outcome verification.
- Content Creation:Generative AI tools automate video editing, caption generation, and thumbnail optimization for mid-market beauty brands.
- Influencer Identification:Discovery engines use natural language processing and computer vision to match brand requirements with creator audience profiles.
Campaign Management sits at the top of the volume ranking, with Analytics climbing the fastest.
End User:
Cost tier differentiation separates enterprise procurement patterns from self-serve adoption curves.
- Brands:Multinational cosmetics conglomerates and direct-to-consumer retailers operate the largest deployments, demanding custom API integrations with existing customer data platforms. Procurement concentrates among beauty and personal care verticals in the United States, Germany, and South Korea.
- Agencies:Creative and media buying firms white-label platform capabilities to manage creator portfolios across multiple client accounts.
- Publishers:Digital media companies leverage platforms to monetize editorial talent through sponsored content partnerships.
- Small Businesses:Self-serve interfaces with reduced feature sets serve merchants on TikTok Shop and Instagram Reels commerce in Indonesia and Vietnam.
Brands command the largest deployment scale, with Small Businesses expanding most quickly.
Technology:
Application maturity varies sharply between proven automation layers and experimental infrastructure.
- Artificial Intelligence:Natural language processing automates creator-brand matching and sentiment analysis, while computer vision detects fake followers through engagement pattern analysis. FTC disclosure automation and EU Digital Services Act compliance modules depend on this layer.
- Machine Learning:Predictive models forecast campaign performance and optimal posting windows based on historical engagement data.
- Big Data:Real-time ingestion pipelines process billions of social media interactions for audience quality scoring.
- Blockchain:Smart contract prototypes address creator payment settlement complexity across multi-currency, cross-border networks.
Artificial Intelligence leads current procurement volume, with Machine Learning gaining share fastest.
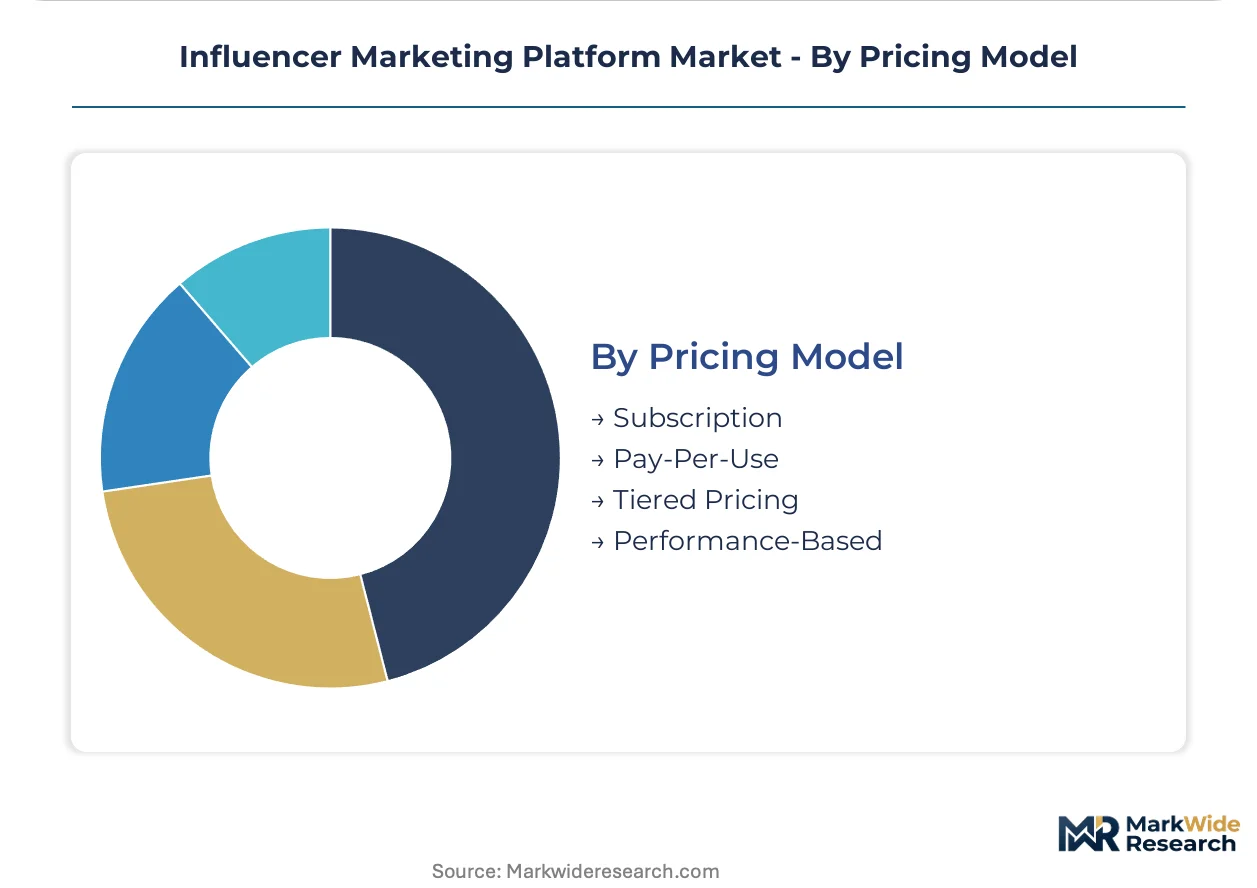
Pricing Model:
Customer type and margin sensitivity determine contract structure preferences across buyer segments.
- Subscription:Fixed monthly or annual fees for seat licenses dominate mid-market agency and publisher adoption. Structural entrenchment persists where budget predictability outweighs performance uncertainty.
- Performance-Based:Fees tied to attributable revenue or engagement metrics attract return-on-ad-spend-sensitive direct-to-consumer brands in the United States.
- Pay-Per-Use:Transactional pricing serves small business and occasional campaign needs without commitment overhead.
- Tiered Pricing:Feature-based differentiation separates premium enterprise functionality from standard and economy access levels.
Subscription retains the largest installed base, with Performance-Based contracts climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping platform procurement as beauty conglomerates migrate campaign operations toward jurisdictions with clearer compliance frameworks. The United States and Germany anchor enterprise software spending, while Southeast Asian markets absorb self-serve adoption curves.
United States
Direct-to-consumer beauty brands and cosmetics conglomerates drive enterprise platform deployment, prioritizing FTC endorsement disclosure automation. The Federal Trade Commission enforces strict paid partnership labeling requirements that embed directly into campaign orchestration workflows. New York and Los Angeles host dense creator economy clusters where predictive analytics vendors anchor relationships with multinational advertisers.
Germany
EU Digital Services Act compliance mandates are accelerating software procurement among Frankfurt and Munich-based cosmetics firms. Algorithmic transparency requirements for sponsored content ranking force platforms to build audit trail infrastructure. The country's federal data protection authority intersects with Brussels regulations to create layered documentation burdens that favor established enterprise vendors.
Indonesia
TikTok Shop commerce infrastructure is compressing campaign execution timelines for Jakarta and Surabaya-based merchants. The country's information and communications ministry monitors virtual influencer disclosure practices as social commerce penetration deepens. Creator monetization workflows are migrating onto self-serve platforms faster than Western regulatory environments permit.
South Korea
Beauty conglomerates in Seoul and Incheon are consolidating influencer spend onto centralized platforms with native social commerce integrations. The Korea Communications Commission enforces advertising disclosure standards that align with broader East Asian regulatory convergence. Computer vision-based fake-follower detection is penetrating faster here than in European markets due to concentrated cosmetics industry demand.
India
The Central Consumer Protection Authority's virtual influencer guidelines are imposing documentation burdens that scale with geographic expansion into Mumbai and Bangalore. Beauty and personal care brands are piloting performance-based platform contracts where attribution technology maturity supports outcome verification. Cross-border payment settlement complexity for distributed creator networks inflates back-office overhead in this market.
Influencer Marketing Platform Market Key Industry Players
Strategic partnership formation dominates the current landscape as platforms embed native checkout integrations with TikTok Shop and Instagram Reels commerce. The vendor base organizes around three tiers: enterprise orchestration suites serving multinational cosmetics conglomerates, mid-market workflow tools for direct-to-consumer brands, and self-serve interfaces targeting Southeast Asian merchants. Two archetypes anchor competitive positioning: predictive analytics specialists and proprietary shopping link technology providers. M&A activity and API integration expansion represent the dominant competitive vectors as platforms race to secure social network data feed access.
Within the enterprise orchestration tier, CreatorIQ and LTK exemplify divergent strategic anchors. CreatorIQ occupies a position aligned with predictive audience analytics and multinational cosmetics relationships. LTK sits within the commission-based monetization archetype, its proprietary shopping link technology sustaining creator revenue share models at scale. Upfluence represents the mid-market workflow consolidation vector, anchoring white-label capabilities for creative agencies managing multi-client creator portfolios. These three entities collectively illustrate how technology differentiation—analytics depth versus commerce integration versus agency enablement—determines competitive boundaries more than geographic presence alone.
| Leading Market Players |
|---|
| Brandwatch |
| Influencity |
| Sprout Social Influencer Marketing |
| LTK |
| Modash |
| Upfluence |
| Aspire |
| Meltwater |
| CreatorIQ |
| Others |
Cost & Logistics Intelligence
Machine learning engineer concentration in the San Francisco Bay Area and Bengaluru creates labor-cost differentials that spread pricing tiers across enterprise orchestration suites and self-serve interfaces. Platform providers anchored in high-salary markets charge premium subscriptions for predictive analytics modules, while engineering teams in lower-cost jurisdictions enable competitive mid-market pricing.
Pricing Analysis
Distributor margin layers in agency white-label arrangements compress platform net revenue by fifteen to twenty-five points before reaching end-brand buyers. Pricing stratifies across premium enterprise orchestration, standard mid-market workflow tools, and economy self-serve tiers, with differentiation driven by API integration depth and dedicated customer success staffing. Cost compression in the self-serve segment is intensifying as TikTok Shop and Instagram Reels commerce embed native checkout, reducing platform value-capture. Direct-to-consumer brands with thin margins exhibit highest price sensitivity, while multinational cosmetics conglomerates prioritize outcome verification over seat-license economics.
Supply Chain Analysis
Freight costs for creator merchandise fulfillment exert minimal direct pressure on platform economics, yet logistics infrastructure quality shapes geographic market prioritization. Platform engineering supply concentrates in the United States, India, and Estonia, with software development drawing from computer science graduate pipelines and venture capital clusters. Cloud compute and social network API access constitute critical input dependencies. Single-source vulnerability rests on Meta and ByteDance data feed terms, where rate limit changes or pricing escalation disrupt platform operations without warning. Distribution runs through direct enterprise sales, agency channel partnerships, and self-serve digital onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Digital Services Act compliance costs in Germany and France exceed Indonesia and Vietnam regulatory burdens by an order of magnitude, creating margin expansion opportunities for platforms with Southeast Asian operational footprints.
For Market Incumbents: Acquire computer vision talent pools to anchor fake-follower detection capabilities against emerging pure-play analytics entrants. Consolidate API access agreements with ByteDance and Meta through multi-year commitments that lock in data feed pricing before rate limit tightening accelerates. Expand compliance-as-a-service modules to capture FTC and EU Digital Services Act documentation burdens as recurring revenue streams.
For New Entrants and Emerging Players: Launch via TikTok Shop-integrated self-serve models targeting Jakarta and Surabaya merchants where platform penetration lags Western markets. Indonesia, Vietnam, and Thailand represent the most penetrable geographies given accelerating social commerce infrastructure and lighter regulatory frameworks. Prioritize natural language processing-based creator-brand matching engines to displace manual agency processes in mid-market beauty segments.
For Investors and Strategic Acquirers: Enterprise software conglomerates are the most active acquirer in this space, seeking predictive analytics capabilities to embed within broader marketing technology stacks. Long-term viability hinges on platforms demonstrating attributable revenue verification at scale rather than vanity engagement metrics. Monitor performance-based contract adoption rates among direct-to-consumer brands as the inflection indicator for pricing model durability.
| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Expansion | Secures social network data feed access before Meta and ByteDance tighten rate limits. |
| Compliance-as-a-Service Launch | Captures EU Digital Services Act and FTC disclosure automation as recurring revenue modules. |
| Southeast Asia Geographic Expansion | Exploits underpenetrated Indonesia and Vietnam markets where TikTok Shop infrastructure accelerates. |
| Performance-Based Pricing Pivot | Aligns platform economics with return-on-ad-spend verification demands from thin-margin direct-to-consumer brands. |
| Computer Vision Acquisition | Bolsters fake-follower detection capabilities against pure-play analytics specialists. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with influencer marketing platform executives, brand marketing officers at cosmetics conglomerates, creative agency account directors, social commerce operations leads, and regulatory compliance specialists. Secondary sources included SEC filings from publicly traded marketing technology vendors, EU Digital Services Act implementation guidance, FTC endorsement disclosure enforcement actions, and social network API documentation. Bottom-up estimates from individual platform deployments and top-down market sizing from advertising spend allocation data were triangulated to produce volume and value outputs.
Granularity-level framing applied service type, end user, technology layer, and pricing model dimensions at the segment level, with geographic regulatory clusters and social commerce integration maturity as cross-cutting variables. CAGRs were derived from trend extrapolation anchored to disclosed platform revenue growth rates and advertising spend shifts. Forecast inputs incorporated TikTok Shop and Instagram Reels commerce infrastructure deployment timelines, EU Digital Services Act compliance cost assumptions, and machine learning engineer hiring velocity across platform engineering hubs.
Several conditions sit outside the modeled scope, including sudden API access revocation by major social networks, cryptocurrency payment rail adoption for creator settlements, and generative AI content tools displacing platform-mediated creator-brand matching entirely. Forecasts reflect assumptions about regulatory enforcement intensity and social commerce penetration curves that may shift with platform policy changes or macroeconomic conditions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market