
 Metaverse Social Media Platforms Market | 2026-2036
Metaverse Social Media Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Metaverse Social Media Platforms Market Insights
Real-time spatial computing is rewriting how social platforms construct persistent virtual environments. Meta leverages its Reality Labs division to anchor hardware-software integration across VR headsets and horizon worlds. Roblox sustains a creator-driven economy where user-generated 3D experiences generate marketplace transactions at scale. ByteDance competes through short-form video-to-virtual-world pipelines that merge social content with immersive destinations.
Metaverse social media platforms comprise persistent, avatar-based digital environments where users interact through real-time rendering, spatial audio, and blockchain-verified asset ownership for commercial and social purposes. These systems rely on edge-compute architectures to deliver sub-50 millisecond latency for synchronous multi-user presence. Virtual Reality platforms dominate capital deployment due to headset ecosystem lock-in, while 3D Environments capture widening demand from enterprises seeking branded persistent spaces. Monetization through In-Game Purchases and Marketplace Sales concentrates margin pools where platform owners extract transaction fees from creator economies.
The Federal Trade Commission scrutinizes data collection practices across immersive environments where biometric gaze tracking raises novel privacy questions. The European Union's GDPR and Digital Services Act impose content moderation and algorithmic transparency obligations on platforms operating across member states. China's MIIT enforces real-name verification and content licensing for virtual social spaces under its cybersecurity framework. Stakeholders must monitor regulatory fragmentation between jurisdictions that treat avatar data as personal information versus behavioral telemetry.
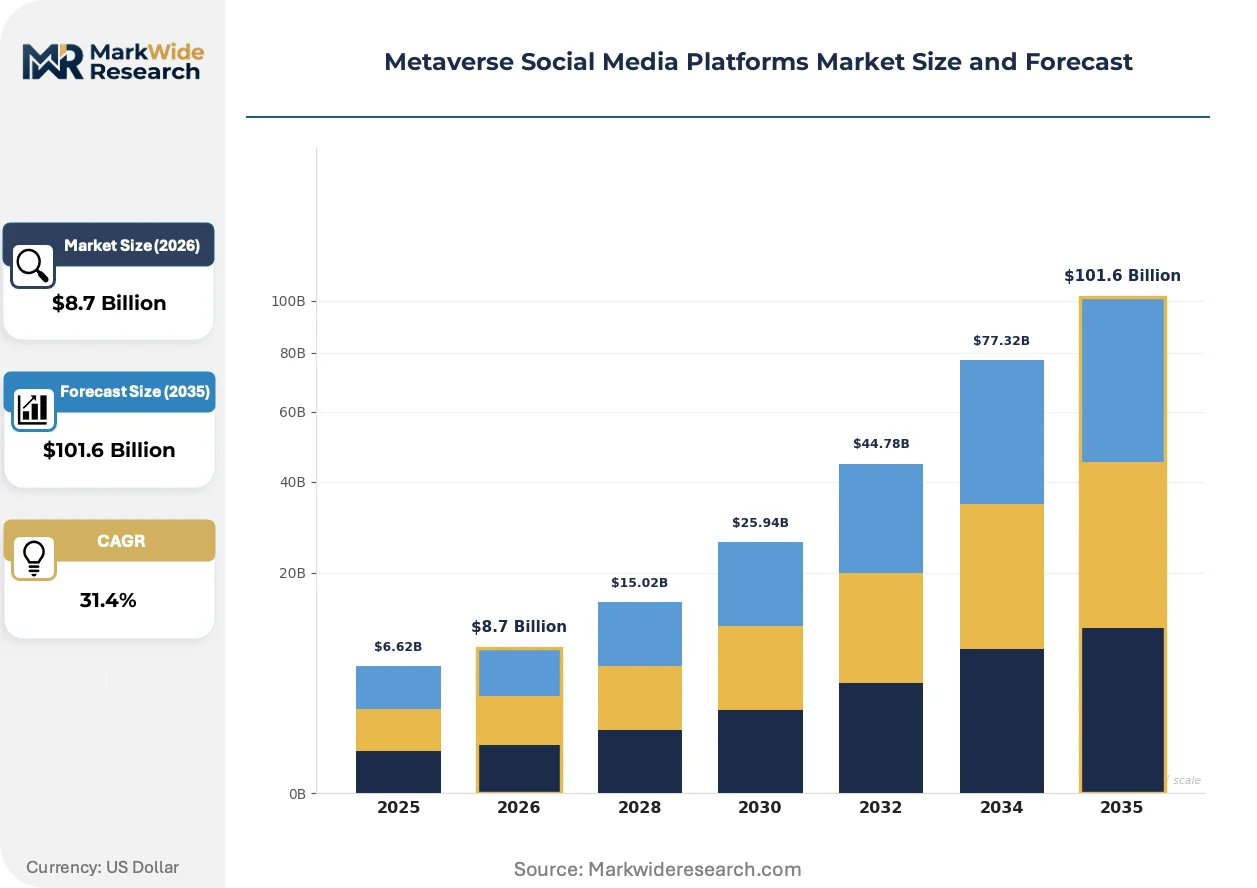
Market Dynamics
Real-time spatial computing is compressing the cost curve for persistent virtual environment creation, forcing platforms to restructure around edge-compute architectures and avatar-based interaction models that demand sub-50 millisecond latency guarantees.
Growth Catalysts
- GDPR and Digital Services Act compliance frameworks:European Union mandates for algorithmic transparency and content moderation are accelerating platform investment in trust-and-safety infrastructure that doubles as competitive differentiation for privacy-conscious users.
- Creator economy monetization pipelines:User-generated 3D experience marketplaces are generating transaction fee revenue pools that attract developer talent and sustain platform network effects through asset ownership verification.
- Enterprise pilot program concentration in the United States:Branded persistent space deployments by Fortune 500 companies are validating commercial use cases and driving infrastructure investment toward business-to-business service layers.
Market Restraints
- VR headset ecosystem lock-in costs:Hardware-software integration requirements concentrate capital deployment among vertically integrated platform owners, raising barriers for modular competitors.
- Biometric gaze tracking data sensitivity:Novel privacy questions surrounding physiological telemetry collection are triggering FTC scrutiny and compliance cost escalation.
- Edge-compute infrastructure capex intensity:Sub-50 millisecond latency requirements demand distributed server placement that strains balance sheets outside hyperscaler ecosystems.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic production incentives for hardware components could localize headset supply chains and reduce import dependency for platform operators.
- Short-form video-to-virtual-world pipeline convergence:Social content platforms with existing creator bases can leverage immersive destination integration to capture entertainment and gaming community migration.
- China's MIIT real-name verification frameworks:Cybersecurity compliance requirements for virtual social spaces create regulatory moats for platforms that achieve early licensing alignment.
Industry Challenges
- Spatial audio and real-time 3D rendering talent scarcity:Technical skill gaps in immersive environment engineering are compressing development timelines and inflating compensation costs.
- Blockchain-verified asset ownership integration complexity:Legacy platform architectures require substantial reengineering to accommodate decentralized identity and transaction systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metaverse Social Media Platforms Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Virtual Reality, Augmented Reality, Mixed Reality, 3D Environments User Engagement: Content Creation, Social Interaction, Gaming, Live Events Monetization Model: Subscription-Based, Advertising, In-Game Purchases, Marketplace Sales Target Audience: Gamers, Influencers, Businesses, Educators |
| Companies Covered | Meta, WeMeta, Roblox, ByteDance, HeadQuarters, IMVU, Topia, Appinventiv, Zepeto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metaverse Social Media Platforms Market Trends and Innovations
Generative AI tooling is collapsing production timelines for 3D asset creation while regulatory fragmentation forces platforms to architect jurisdiction-specific data governance layers.
Neural radiance fields (NeRF) and Gaussian splatting techniques are collapsing the traditional photogrammetry pipeline for environment reconstruction. Real estate and retail end-users are adopting these methods for virtual showroom deployment within compressed budget cycles. The structural consequence is collapsing cost barriers for mid-market enterprises seeking branded persistent spaces without custom engine development.
The European Union's AI Act imposes risk-tiered obligations on biometric inference systems deployed in immersive environments. Platforms must now document algorithmic decision pathways for avatar behavior prediction and emotion detection. Social VR applications with gaze-tracking features face the steepest compliance burden, driving engineering resources toward explainable AI architectures.
Enterprise procurement of metaverse social platforms is fragmenting from centralized IT mandates toward business-unit-led pilot programs. Marketing and HR departments are displacing traditional vendor selection processes with direct creator economy relationships. This pattern is most visible in United States technology and financial services verticals where brand experience budgets operate independently of core infrastructure procurement.
Metaverse Social Media Platforms Market Segmentation
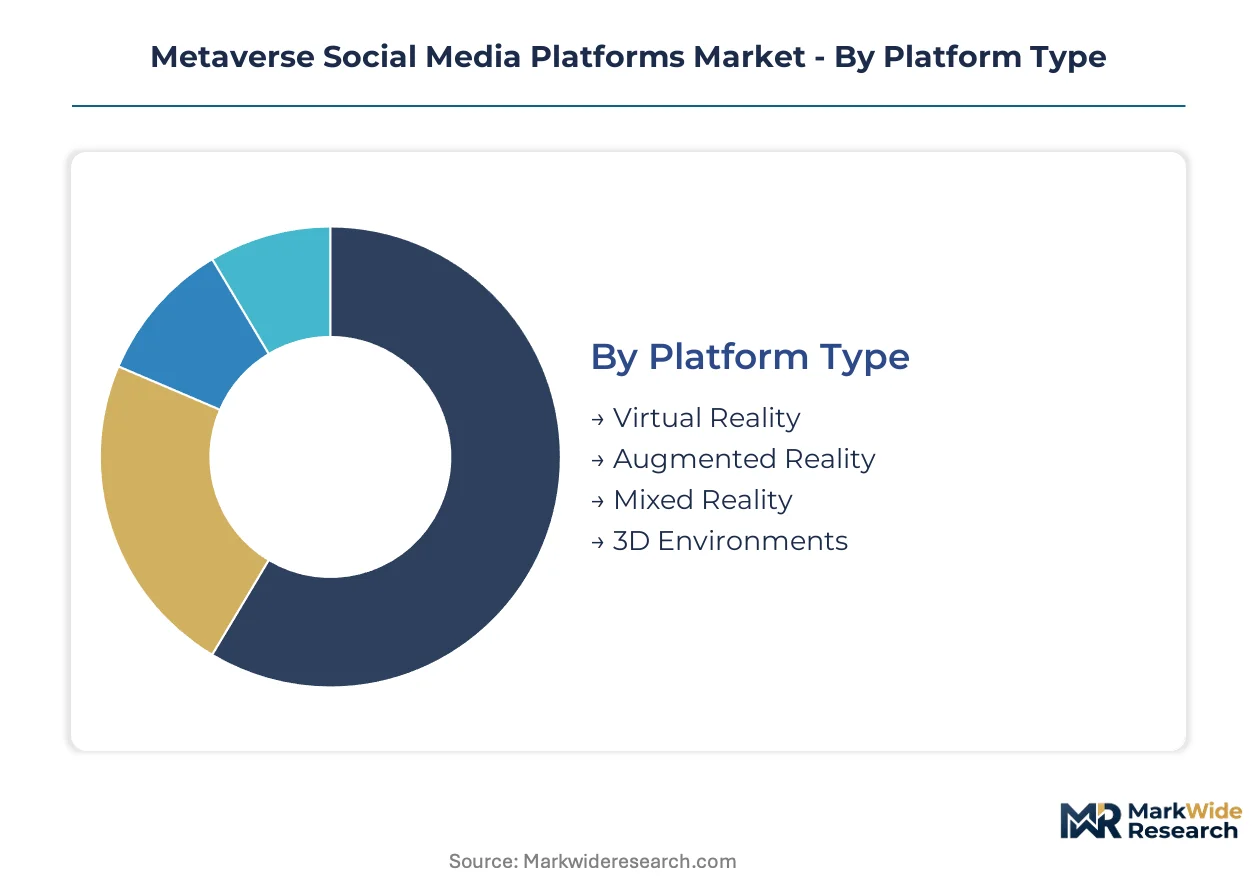
Platform architecture choices determine latency requirements and capital intensity for operators. User engagement patterns and monetization mechanics shape revenue durability across entertainment and enterprise use cases.
Platform Type:
Cost tier separates hardware-dependent deployments from software-native environments.
- Virtual Reality:Headset-centric ecosystems demand vertical integration between optics, tracking systems, and content distribution. Demand concentrates in the United States where enterprise pilot programs for training and collaboration validate hardware procurement at scale. Ecosystem lock-in extracts premium margins through proprietary controller and store architectures.
- 3D Environments:Browser-accessible persistent spaces run on cloud-rendered infrastructure without specialized hardware. Branded deployments by Fortune 500 companies in financial services and retail verticals are accelerating mid-market adoption through subscription SaaS models.
- Augmented Reality:Mobile-first spatial overlays leverage existing smartphone penetration for social content anchoring.
- Mixed Reality:Passthrough camera systems blend physical and digital presence for enterprise collaboration scenarios.
Virtual Reality holds installed capacity. 3D Environments is rotating up the share rankings.
User Engagement:
Application type determines session duration metrics and retention engineering priorities.
- Gaming:Competitive and cooperative mechanics drive the highest daily active user hours through achievement systems and clan structures. Entertainment communities in the United States and South Korea generate concentrated transaction volume for cosmetic asset marketplaces.
- Content Creation:User-generated 3D experience tools attract developer talent through revenue-sharing pipelines. The creator economy infrastructure maturing in the United States validates monetization for amateur and professional builders alike.
- Social Interaction:Avatar-based presence systems compete with legacy messaging platforms for communication frequency.
- Live Events:Synchronous virtual concerts and conferences monetize through ticketed access and sponsorship integration.
Gaming anchors current revenue pools. Content Creation is climbing the fastest in developer recruitment metrics.
Monetization Model:
Customer type and payment psychology segment recurring versus transactional revenue streams.
- In-Game Purchases:Microtransaction architectures for avatar customization and virtual goods sustain free-to-access platform economics. Entertainment and gaming communities in the United States demonstrate willingness-to-pay for limited-edition digital assets verified through blockchain records.
- Marketplace Sales:Transaction fee extraction from creator-to-consumer asset exchanges generates network effects through liquidity concentration. Platform owners in North American and Asian markets compete on revenue share percentages to attract high-volume sellers.
- Subscription-Based:Premium tier access for enhanced customization tools and exclusive spaces targets power users.
- Advertising:Immersive billboard and sponsored experience integration remains nascent amid privacy scrutiny over gaze tracking data.
In-Game Purchases holds installed capacity. Marketplace Sales is gaining share fastest in platform revenue mix.
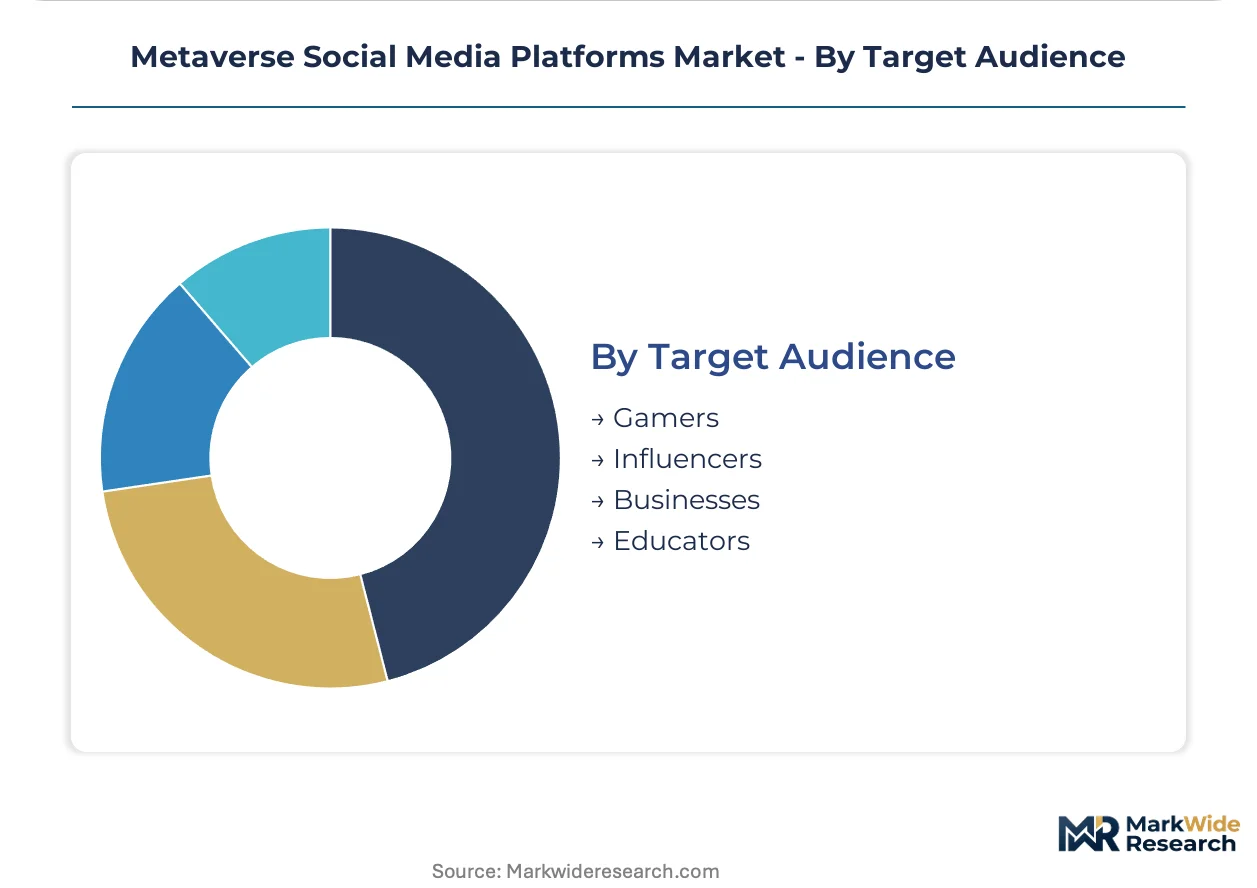
Target Audience:
Volume concentration and margin profile diverge across consumer and commercial user bases.
- Gamers:Core demographic for headset adoption and competitive social mechanics. United States and South Korean markets show highest per-user spending on virtual goods and seasonal battle pass structures.
- Businesses:Branded persistent space deployments for virtual headquarters and product showrooms command annual contract values an order of magnitude above consumer subscriptions.
- Influencers:Creator-led audience migration drives platform selection through exclusive content deals and fan engagement tools.
- Educators:Institutional procurement for immersive learning environments remains pilot-phase with extended sales cycles.
Gamers holds installed capacity. Businesses is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based platform operators export immersive social infrastructure to enterprise buyers across Germany, Japan, and South Korea, establishing a trans-Pacific trade corridor in virtual collaboration tools and creator economy middleware.
United States
Enterprise pilot programs for branded persistent spaces and creator economy infrastructure maturation drive domestic platform investment. The FTC scrutinizes biometric gaze tracking data collection practices under evolving consumer protection frameworks. Silicon Valley clusters anchor Reality Labs hardware-software integration and Horizon Worlds development pipelines.
China
Short-form video-to-virtual-world pipeline convergence attracts entertainment community migration at scale. MIIT enforces real-name verification and content licensing requirements for virtual social spaces under national cybersecurity frameworks. Beijing and Shenzhen clusters concentrate ByteDance's immersive destination development and domestic headset ecosystem partnerships.
South Korea
Gaming community spending on virtual goods and seasonal battle pass structures sustains high per-user revenue metrics. The country's national telecommunications regulator imposes latency quality standards on edge-compute deployments for synchronous multi-user presence. Seoul anchors Zepeto's avatar-based social platform development and K-pop virtual concert production pipelines.
Germany
Industrial metaverse applications for automotive and manufacturing training drive enterprise software procurement. The EU AI Act and GDPR impose risk-tiered obligations on biometric inference systems deployed in immersive environments. Bavaria and Baden-Württemberg clusters concentrate automotive virtual showroom deployments and industrial digital twin integration.
India
Domestic creator talent pools and mobile-first social interaction patterns position the market for platform localization. The PLI scheme for electronics manufacturing incentivizes headset component production and supply chain localization. Karnataka and Telangana clusters anchor Appinventiv's immersive application development services and engineering talent recruitment.
Metaverse Social Media Platforms Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware-software integration and creator economy middleware layers. The market structure concentrates around vertically integrated headset ecosystems and modular 3D environment platforms. Two strategic archetypes dominate: hardware-anchored platform owners extracting ecosystem lock-in premiums, and creator-driven economy operators monetizing user-generated asset marketplaces. Competitive moves center on strategic partnerships for edge-compute capacity and portfolio diversification into enterprise SaaS layers.
Within the hardware-anchored tier, Meta exemplifies vertical integration across Reality Labs optics and Horizon Worlds distribution. Among creator economy specialists, Roblox occupies a position defined by user-generated 3D experience monetization at scale. ByteDance represents the short-form video pipeline archetype, merging social content density with immersive destination migration.
| Leading Market Players |
|---|
| Meta |
| WeMeta |
| Roblox |
| ByteDance |
| HeadQuarters |
| IMVU |
| Topia |
| Appinventiv |
| Zepeto |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific fiber-optic cable capacity costs between Los Angeles and Tokyo anchor cloud-rendered infrastructure pricing, compressing margins for 3D environment platforms while concentrating supply-side leverage among hyperscalers operating edge-compute nodes. This corridor's bandwidth economics directly shape subscription tiering for enterprise SaaS deployments and transactional fee structures for creator marketplaces.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate headset procurement agreements, locking hardware-anchored platforms into margin volatility tied to Taiwan and South Korea foundry pricing. Three-tier pricing structure across premium, standard, and economy levels separates enterprise VR deployments from mid-market SaaS subscriptions and consumer freemium access. Pricing pressure stems from India's PLI scheme driving component localization and alternative supply sources. Enterprise buyers in the United States show lowest price sensitivity due to branded persistent space validation requirements, while individual creators in Southeast Asia exhibit highest sensitivity to marketplace transaction fees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for optical display components and LiDAR sensors. Manufacturing concentrates in China, Taiwan, and Vietnam for headset assembly, with South Korea and Japan supplying advanced memory and image processing chips. Raw material dependencies span rare earth elements for magnet systems, gallium arsenide for photonics, and high-purity silicon for chip fabrication. Distribution runs through direct-to-enterprise sales teams for Fortune 500 deployments and app-store architectures for consumer marketplace access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward enterprise procurement teams as Fortune 500 pilot programs fragment from centralized IT mandates toward business-unit-led vendor selection. This fragmentation concentrates negotiating leverage among marketing and HR departments with independent brand experience budgets.
For Market Incumbents:Pre-empt modular 3D environment competitors by deepening in-house production of spatial audio engines and real-time rendering middleware. Edge-compute capacity expansion in Germany and South Korea addresses latency quality standards imposed by national telecommunications regulators. Certification investment in EU AI Act compliance for biometric inference systems creates regulatory moats against non-compliant entrants.
For New Entrants and Emerging Players:India's underpenetrated creator economy infrastructure offers white-space entry through mobile-first 3D environment tools targeting domestic engineering talent pools. Browser-accessible persistent spaces bypass headset ecosystem lock-in costs that constrain vertically integrated incumbents. Channel partnerships with existing short-form video platforms accelerate user acquisition without proprietary hardware development.
For Investors and Strategic Acquirers:Creator economy middleware specialists with established revenue-sharing pipelines represent the most defensible acquisition archetype across the analysis window. Long-term viability hinges on platforms demonstrating sustained developer recruitment metrics and marketplace liquidity concentration. Watch for inflection signals in enterprise SaaS contract values exceeding consumer subscription multiples by an order of magnitude.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Compute Capacity Expansion | Distributed server placement in Germany and South Korea satisfies sub-50 millisecond latency requirements for synchronous multi-user presence. |
| Spatial Audio Engine Acquisition | Middleware control over immersive environment engineering addresses talent scarcity compressing development timelines. |
| Creator Revenue Share Restructuring | Competitive percentage adjustments attract high-volume sellers from North American and Asian marketplace rivals. |
| EU AI Act Compliance Certification | Documented algorithmic decision pathways for gaze-tracking features reduce regulatory burden on social VR applications. |
| Enterprise SaaS Tier Launch | Annual contract values for branded persistent spaces capture business-unit budgets independent of core infrastructure procurement. |
Research Methodology
Initial hypotheses were tested against primary input from platform engineering leads, creator economy monetization officers, enterprise procurement managers, and immersive experience designers and refined through secondary validation against SEC filings from hardware-anchored operators, hyperscaler capex disclosures, and national telecommunications regulator latency quality standards. Bottom-up triangulation across marketplace transaction volume estimates and top-down reconciliation against enterprise SaaS contract value aggregates produced convergent market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling platform type segmentation alongside user engagement patterns, monetization mechanics, and target audience concentration. CAGRs derived from installed capacity trajectories for Virtual Reality headsets and share rotation velocity for 3D Environments. Forecast inputs incorporated edge-compute infrastructure deployment timelines and creator economy developer recruitment metrics without year-specific milestones.
Practitioners should monitor regulatory fragmentation between GDPR jurisdictions and MIIT cybersecurity frameworks for early signals of compliance cost escalation that could revise platform economics. Forecasts reflect assumptions about sustained enterprise pilot program validation and consumer headset adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
Global Blogging Platforms Market