
 Global Player Tracking Market | 2026-2036
Global Player Tracking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Player Tracking Market Foresight
Australia is tilting toward player tracking manufacturing scale as Catapult Group International Limited anchors its domestic R&D footprint for wearable athlete monitors. STATSports Technologies Limited dominates the English Premier League supplier channel with GPS-integrated performance vests. KINEXON Sports & Media GmbH leverages its Munich engineering base to sustain precision indoor positioning systems for basketball and handball federations.
Player tracking encompasses sensor-based hardware and software systems that capture real-time kinematic and physiological data from athletes during competition and training, typically sampling positional coordinates at 10–20 Hz and heart rate at 1 Hz for load management protocols. The primary commercial purpose centers on reducing injury incidence while optimizing tactical decision-making for coaching staff. Ultra-Wideband deployments command premium pricing in indoor venue applications where GPS signals degrade, while RFID sustains volume leadership across budget-constrained amateur clubs. Cloud-based architectures are displacing on-premises installations as professional leagues mandate centralized data lakes for cross-team analytics.
FIFA's Quality Programme for EPTS devices shapes hardware certification pathways for vendors seeking access to World Cup and continental tournament deployments. The EU AI Act imposes algorithmic transparency requirements on automated talent scouting platforms that process biometric athlete data. Stakeholders must monitor how emerging data sovereignty rules across European national football associations fragment cloud hosting strategies.
Market Dynamics
FIFA's Quality Programme for EPTS devices is compressing vendor certification timelines while mandating algorithmic transparency standards that reshape hardware development roadmaps across wearable sensor suppliers.
Growth Catalysts
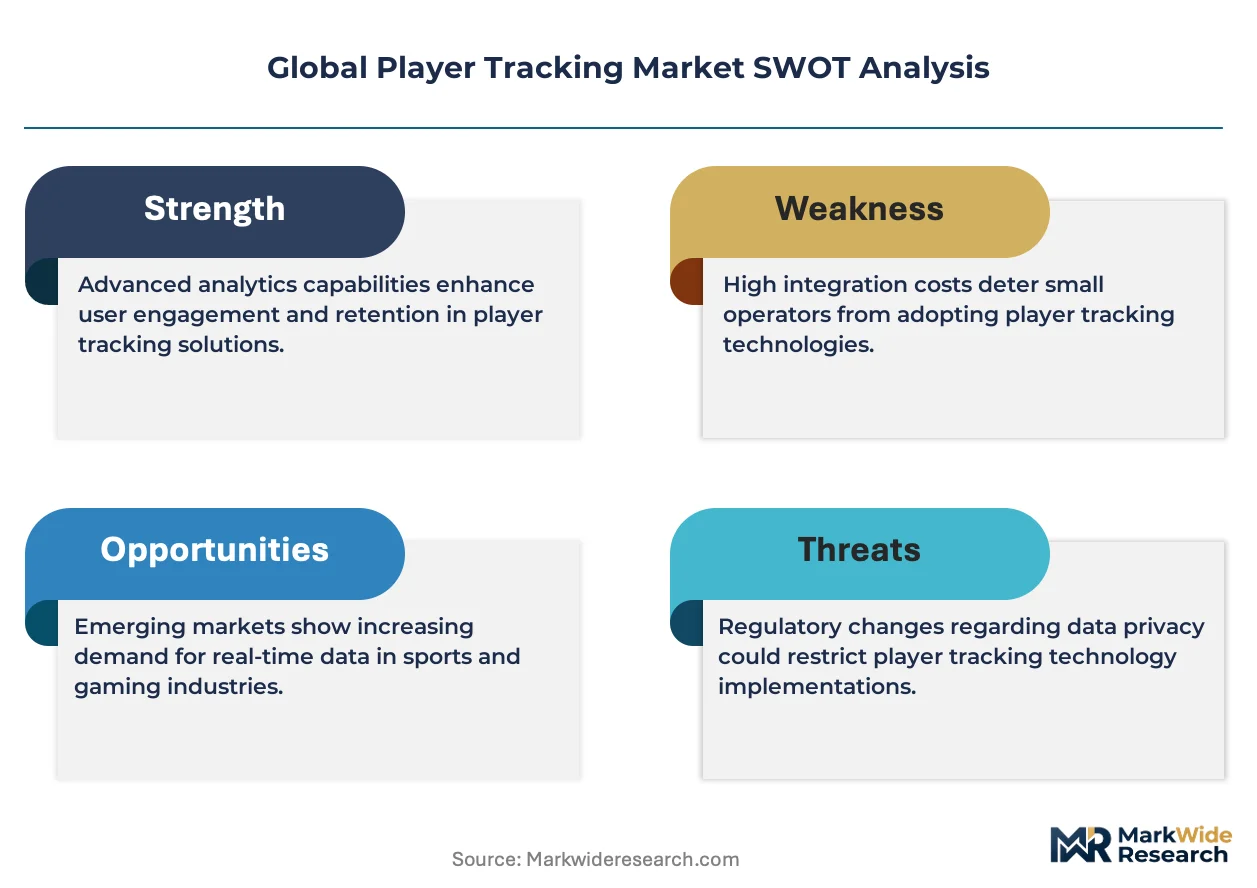
- EU AI Act compliance mandates:Automated talent scouting platforms processing biometric athlete data face new algorithmic transparency requirements, creating certified vendor preference among professional clubs.
- Ultra-Wideband indoor positioning:Basketball and handball federations are deploying precision tracking infrastructure where GPS signals degrade, opening premium pricing tiers for venue-specific hardware.
- Cloud-based data lake architectures:Professional leagues now mandate centralized analytics repositories, accelerating displacement of on-premises installations across franchise networks.
Market Restraints
- RFID component supply concentration:Budget-constrained amateur clubs depend on volume RFID systems where semiconductor sourcing bottlenecks in East Asian foundries create delivery volatility.
- Data sovereignty fragmentation:European national football associations are imposing divergent cloud hosting localization rules that complicate cross-border athlete data processing for multi-national leagues.
- GPS signal degradation thresholds:Indoor venue applications face hard technical limitations for satellite-based tracking, forcing parallel infrastructure investments for hybrid positioning systems.
Strategic Opportunities
- Underpenetrated Indian domestic leagues:Cricket and kabaddi federations lack standardized athlete monitoring protocols, presenting first-mover positioning for wearable sensor vendors establishing local certification partnerships.
- Convergence of computer vision and wearable sensors:Camera-based kinematic analysis integrated with vest-mounted IMUs enables contactless load management for sports with equipment restrictions.
- Subscription-based software distribution:Analytics platforms are bypassing perpetual license models through tiered SaaS offerings that reduce upfront capex barriers for mid-tier collegiate programs.
Industry Challenges
- Embedded firmware engineering scarcity:Vendors struggle to recruit specialists capable of optimizing 10–20 Hz sampling algorithms for battery-constrained wearable form factors.
- FIFA EPTS certification timelines:Hardware validation protocols for World Cup eligibility extend development cycles by 18–24 months, compressing revenue recognition windows for tournament-bound product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Player Tracking Market |
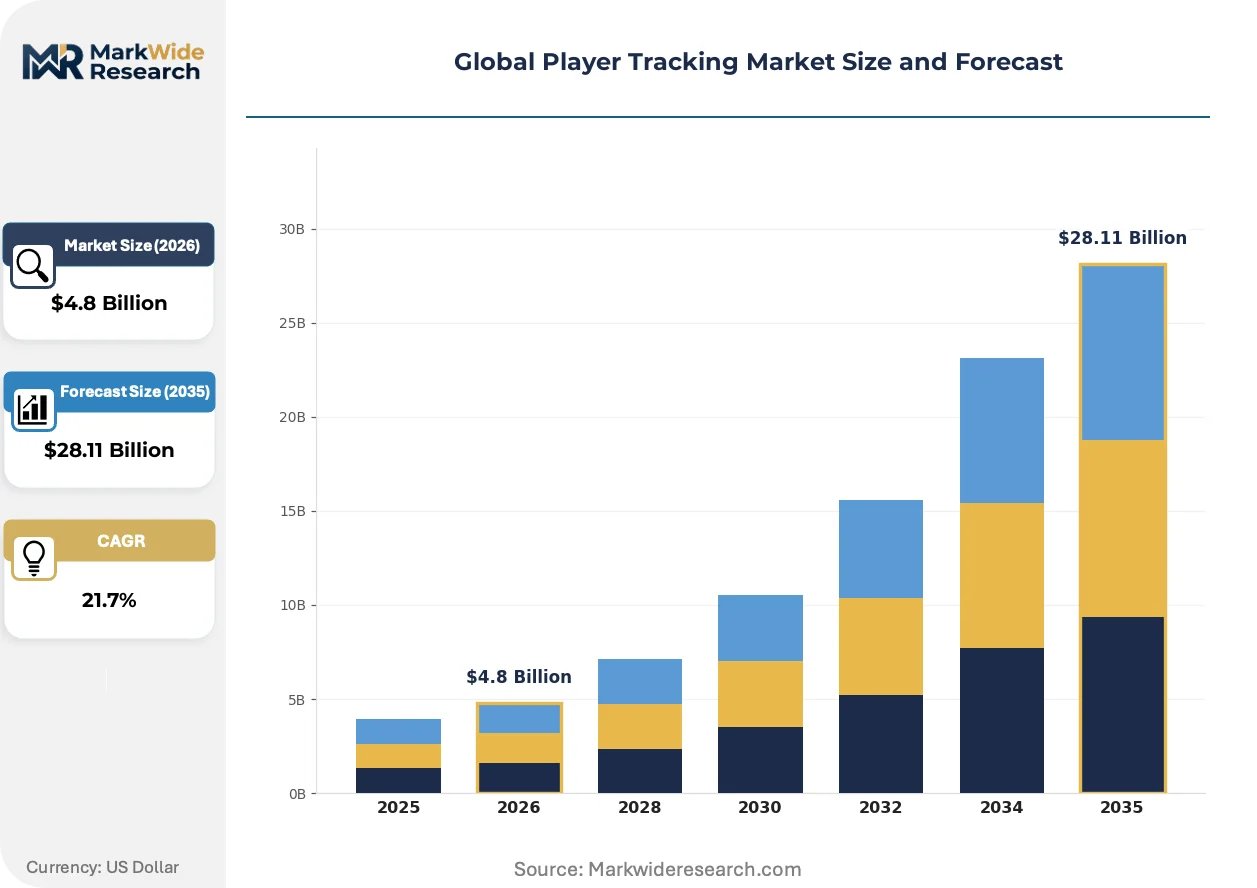
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $28.11 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Ultra-Wideband, GPS, Bluetooth Low Energy, Infrared Application: Sports Analytics, Fan Engagement, Venue Management, Talent Scouting, Training Optimization End User: Professional Leagues, Amateur Clubs, Event Organizers, Sports Academies, Governing Bodies Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | ChyronHego Corporation, Polar Electro Oy, Zebra Technologies Corporation, JOHAN Sports B.V, STATSports Technologies Limited, Catapult Group International Limited, KINEXON Sports & Media GmbH, Xampion Ltd, TrackMan A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Player Tracking Market Shifts & Advancements
Real-time athlete monitoring architectures are pivoting from retrospective analytics toward predictive injury prevention models that demand continuous physiological data streams and edge-computing capabilities.
Ultra-Wideband beacon networks are rendering obsolete legacy RFID-based indoor positioning for high-frequency motion capture in basketball arenas and handball halls. NCAA Division I programs and EuroLeague franchises are deploying sub-10-centimeter accuracy systems for tactical spacing analysis. This precision tier is rendering obsolete coarse-grain proximity sensors that failed to resolve player collisions and acceleration vectors.
The EU AI Act imposes explainability requirements on automated talent identification algorithms that process heart rate variability and sprint biomechanics. Vendors must now document decision pathways for scouting recommendations derived from wearable data. English Premier League academies and German Bundesliga youth systems are most affected, with several clubs pausing AI-driven recruitment tools pending compliance audits.
After-sales service unbundling is fragmenting traditional hardware-software bundles as athletic departments seek modular analytics subscriptions separate from sensor procurement. Collegiate athletic conferences in the United States are negotiating enterprise SaaS licenses that decouple data platform access from specific device manufacturers. This purchasing autonomy is most visible across Power Five conference members seeking vendor-agnostic data portability.
Global Player Tracking Market Segmentation
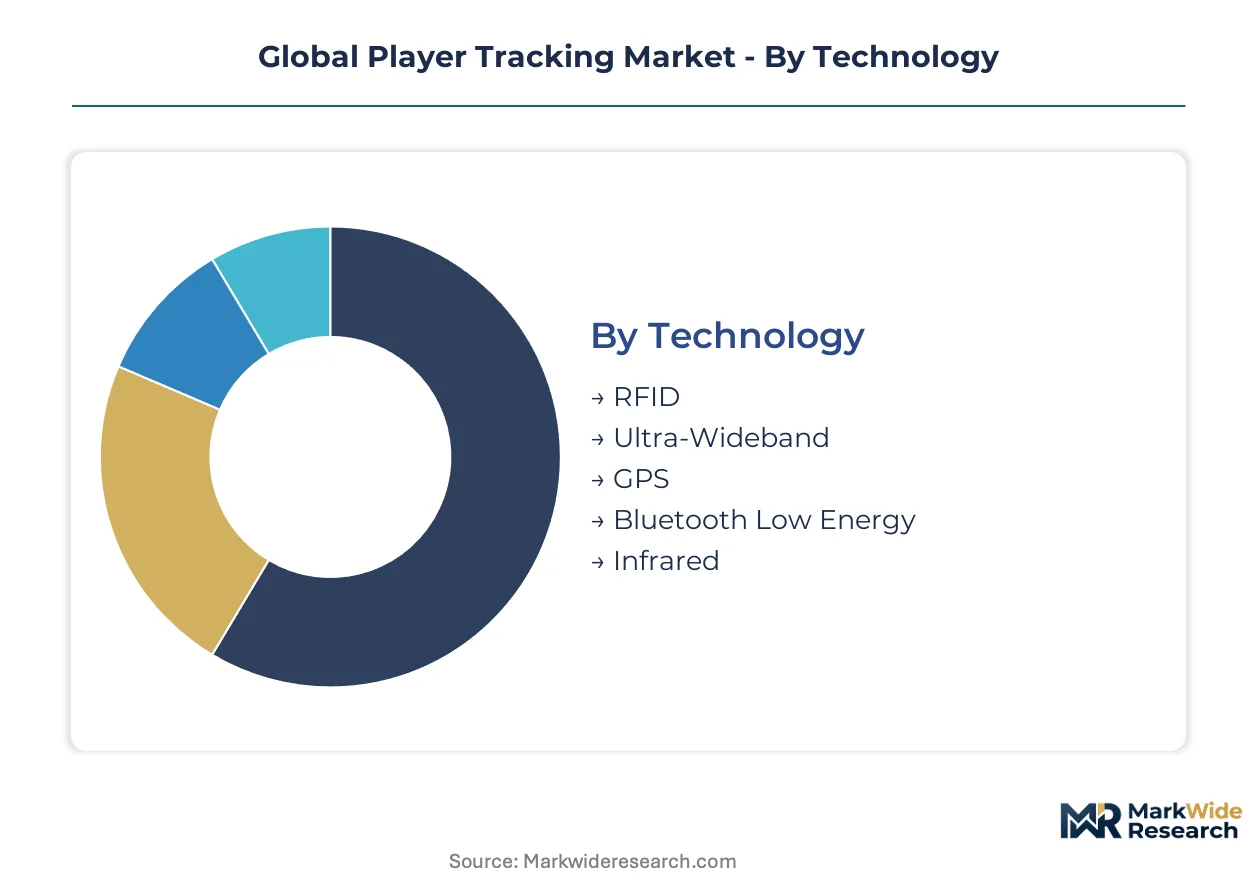
Player tracking architectures diverge sharply across price-performance tiers, with indoor venue requirements and data sovereignty mandates forcing distinct procurement patterns. Technology selection cascades through deployment topology, application priority, and end-user sophistication in ways that reshape vendor go-to-market economics.
Technology:
Use-case spectrum spans budget-constrained outdoor training grounds through precision-demanding indoor arenas, with signal propagation characteristics dictating hardware selection.
- Ultra-Wideband:Sub-10-centimeter positioning accuracy enables tactical spacing analysis in basketball arenas and handball halls where GPS signals degrade. NCAA Division I programs and EuroLeague franchises anchor demand as hybrid positioning investments accelerate.
- RFID:Passive and active radio-frequency systems sustain volume leadership across amateur clubs through lower per-unit hardware costs. Semiconductor sourcing bottlenecks in East Asian foundries inject delivery volatility into budget-tier procurement cycles.
- GPS:Satellite-dependent tracking dominates outdoor training protocols for football and rugby federations. Signal occlusion thresholds in stadium environments force complementary infrastructure spending.
- Bluetooth Low Energy:Proximity-based athlete monitoring suits mid-tier collegiate programs seeking wearable integration without venue-scale beacon networks. Battery efficiency extends deployment windows for multi-day tournament coverage.
- Infrared:Line-of-sight dependent optical positioning persists in legacy ice hockey and speed skating installations. Limited penetration outside Nordic and North American winter sports clusters constrains vendor R&D prioritization.
The dominant share belongs to RFID, while Ultra-Wideband is closing the gap fastest.
Application:
Cost tier stratification separates perpetual-license analytics platforms from modular SaaS subscriptions as athletic departments seek procurement flexibility.
- Sports Analytics:Real-time kinematic and physiological data streams feed predictive injury prevention models and tactical decision support. FIFA's EPTS certification requirements compress vendor development timelines for World Cup-eligible deployments.
- Training Optimization:Load management protocols sample heart rate at 1 Hz and positional coordinates at 10–20 Hz to quantify athlete exertion. Professional leagues mandate centralized data lakes that displace retrospective analytics architectures.
- Fan Engagement:Second-screen experiences and augmented reality overlays leverage player tracking feeds for broadcast enhancement. Rights-holder negotiations fragment data licensing revenue across league, team, and venue stakeholders.
- Talent Scouting:Automated biometric processing faces EU AI Act algorithmic transparency mandates that reshape scouting platform compliance roadmaps. English Premier League academies and German Bundesliga youth systems pause AI-driven recruitment pending audit completion.
- Venue Management:Crowd flow optimization and safety monitoring extend tracking infrastructure beyond athlete-facing applications. Multi-purpose arena operators seek sensor reuse across sporting and entertainment event calendars.
Sports Analytics commands the largest revenue pool, though Training Optimization exhibits the steepest expansion trajectory as predictive models displace retrospective reporting.
End User:
Customer type heterogeneity stretches from centralized league procurement through fragmented amateur club purchasing, with certification requirements filtering vendor access.
- Professional Leagues:NFL and NBA franchises operate the largest installed bases of Ultra-Wideband and GPS tracking infrastructure. Collective bargaining agreements increasingly mandate player data privacy protections that complicate vendor contracts.
- Sports Academies:Developmental programs prioritize longitudinal athlete monitoring across multi-year training cycles. Subscription-based software distribution reduces upfront capex barriers for mid-tier collegiate programs.
- Governing Bodies:FIFA's Quality Programme for EPTS devices shapes hardware certification pathways for tournament eligibility. Standardization mandates cascade through continental confederation procurement specifications.
- Amateur Clubs:Budget constraints sustain RFID volume leadership despite accuracy limitations. Cloud-based architectures displace on-premises installations as federations subsidize centralized analytics access.
- Event Organizers:Temporary infrastructure deployments for single-tournament coverage favor rental and managed service models. Logistics complexity limits penetration outside Olympic and World Cup-scale competitions.
Professional Leagues retain the deepest wallet share, while Sports Academies gain purchasing velocity fastest through conference-level enterprise SaaS negotiations.
Deployment:
Geography of data hosting fragments as European national football associations impose divergent cloud localization rules.
- Cloud-Based:Centralized data lakes enable cross-team analytics and league-wide benchmarking previously impossible with siloed installations. Data sovereignty fragmentation complicates multi-national league processing architectures.
- Hybrid:Edge-computing nodes handle real-time inference while cloud repositories retain longitudinal training history. This topology balances latency-sensitive tactical alerts against archival scalability.
- On-Premises:Legacy franchise networks resist migration where existing IT infrastructure amortization cycles extend. Security-conscious military academies and certain European clubs cite biometric data control priorities.
- Edge Computing:Local inference engines process 10–20 Hz sampling streams without round-trip latency to distant data centers. Battery-constrained wearable form factors demand firmware optimization scarce in current labor markets.
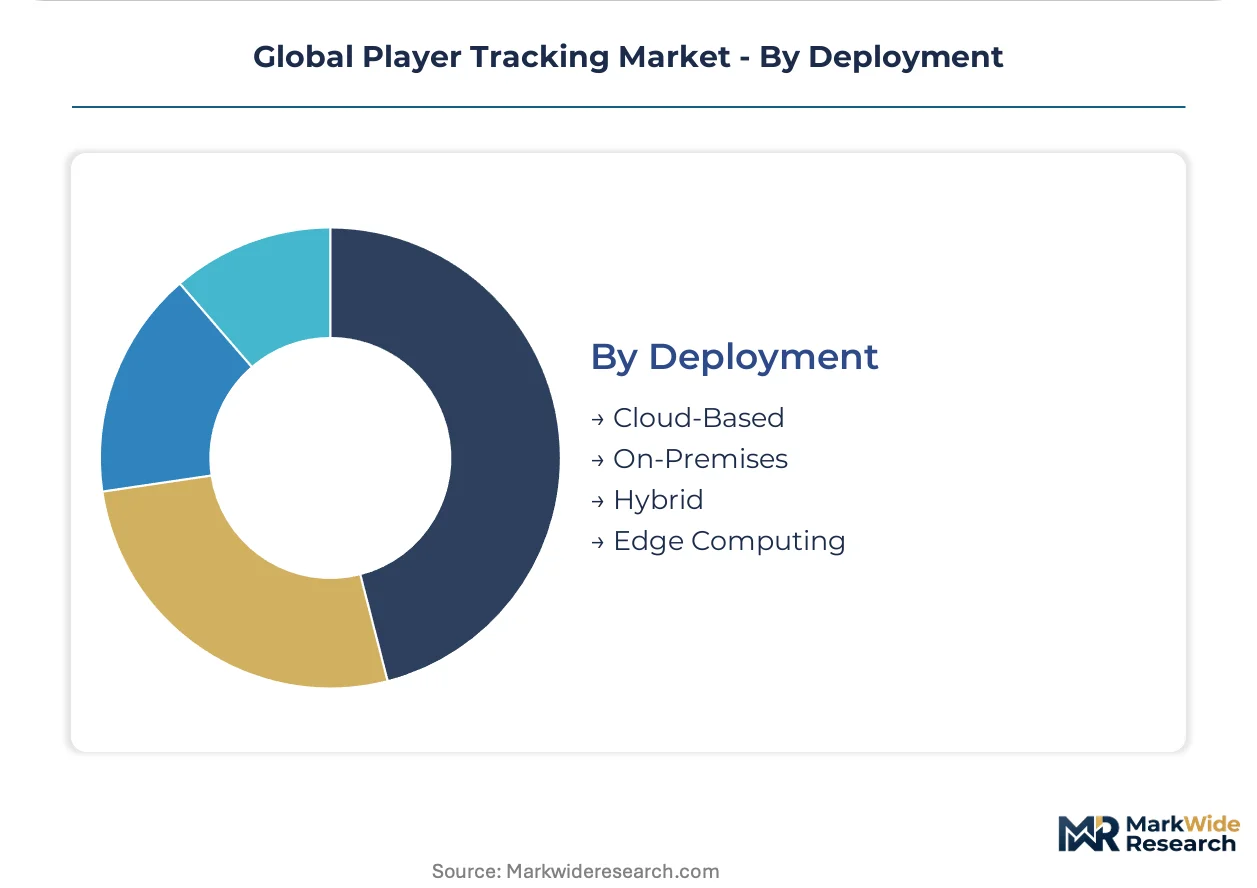
Cloud-Based deployments hold established share leadership, though Hybrid architectures climb fastest as latency requirements harden for real-time coaching dashboards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States hosts the densest Ultra-Wideband beacon infrastructure, with NFL and NBA franchises operating venue-scale networks that process 10–20 Hz athlete sampling streams. Germany's Munich engineering corridor anchors precision indoor positioning R&D for basketball and handball federations. Australia's domestic manufacturing base concentrates wearable sensor production for Asia-Pacific export markets.
United States
NFL and NBA franchises operate the largest installed bases of Ultra-Wideband and GPS tracking infrastructure, driving demand for real-time athlete monitoring systems. FCC spectrum allocations for 6 GHz UWB operations enable sub-10-centimeter positioning accuracy in indoor arenas. The Greater Boston corridor hosts edge-computing startups optimizing battery-constrained firmware for wearable form factors.
Germany
Bundesliga youth systems and EuroLeague franchises deploy precision indoor positioning where GPS signals degrade, creating premium-tier hardware demand. The EU AI Act imposes algorithmic transparency requirements on automated talent scouting platforms processing biometric athlete data. Munich-based engineering clusters sustain R&D for hybrid positioning systems serving handball and basketball federations.
United Kingdom
English Premier League academies anchor GPS-integrated performance vest deployments across professional and developmental tiers. GDPR compliance mandates reshape cloud hosting strategies for cross-border athlete data processing in multi-national leagues. London's broadcast technology corridor drives second-screen fan engagement applications leveraging real-time tracking feeds.
Australia
Catapult Group International Limited anchors domestic R&D and manufacturing scale for wearable athlete monitors serving export markets. The country's national sports technology regulator coordinates certification alignment with FIFA's Quality Programme for EPTS devices. Melbourne's sports science cluster concentrates load management protocol development for cricket and Australian rules football.
India
Cricket and kabaddi federations lack standardized athlete monitoring protocols, presenting first-mover positioning for wearable sensor vendors. BIS certification requirements for electronic performance tracking systems are tightening as domestic leagues professionalize. Bangalore's hardware startup ecosystem incubates low-cost Bluetooth Low Energy solutions for budget-constrained amateur clubs.
Global Player Tracking Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and beacon hardware. The vendor base spans three distinct tiers: full-stack analytics platforms, precision positioning hardware manufacturers, and modular software subscription providers. Two strategic archetypes dominate competitive maneuvering: venue-scale infrastructure deployers pursuing league-wide certification, and SaaS-native entrants decoupling analytics from hardware procurement. M&A activity concentrates on firmware engineering talent acquisition, while geographic expansion targets underpenetrated cricket and kabaddi markets in South Asia.
Among precision positioning specialists, KINEXON Sports & Media GmbH and STATSports Technologies Limited exemplify the venue-scale deployment archetype, while Catapult Group International Limited represents the integrated hardware-software platform model. Zebra Technologies Corporation occupies a position bridging enterprise RFID infrastructure into athletic applications. These three anchors illustrate divergent go-to-market economics: Munich-based engineering for indoor federations, English Premier League supplier channel dominance, and Australian manufacturing scale for Asia-Pacific export markets respectively.
| Leading Market Players |
|---|
| ChyronHego Corporation |
| Polar Electro Oy |
| Zebra Technologies Corporation |
| JOHAN Sports B.V |
| STATSports Technologies Limited |
| Catapult Group International Limited |
| KINEXON Sports & Media GmbH |
| Xampion Ltd |
| TrackMan A/S |
| Others |
Supply & Pricing Matrix
Semiconductor sourcing bottlenecks in East Asian foundries cascade through both pricing tier spreads and supply chain configuration, compressing margins for volume RFID suppliers while elevating premium positioning for UWB vendors with captive component access.
Pricing Analysis
Volume-discount tiering structures separate enterprise SaaS subscriptions for Power Five conferences from perpetual-license analytics platforms for mid-tier collegiate programs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FIFA's EPTS Quality Programme, with World Cup-eligible hardware commanding substantial premiums. Cost compression in the economy tier intensifies as amateur clubs consolidate procurement through federation-subsidized cloud access. Amateur clubs exhibit highest price sensitivity, while NFL and NBA franchises prioritize accuracy specifications over unit economics.
Supply Chain Analysis
Upstream feedstock for UWB beacon networks and GPS-integrated performance vests draws from Taiwan and South Korea for RF semiconductor components, with China anchoring battery cell and PCB assembly capacity. Foundry capacity constraints for precision positioning chipsets and lithium-polymer power cells create single-source vulnerability where alternative qualification cycles extend 18–24 months. Distribution runs through direct sales teams for professional league deployments and federated purchasing cooperatives for amateur club networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collective bargaining agreements across North American professional leagues are consolidating buyer power, shifting procurement leverage toward franchise networks and away from individual vendor relationships.
For Market Incumbents: Build certification moats by accelerating FIFA EPTS pre-qualification for next-tournament hardware cycles before compliance timelines compress further. Deepen backward integration into UWB chipset sourcing through strategic foundry partnerships in Taiwan, insulating premium tier margins from RF semiconductor volatility. Channel control through exclusive league data platform partnerships defends against SaaS-native entrants decoupling analytics from sensor procurement. For New Entrants and Emerging Players: Underpenetrated cricket and kabaddi federations in India represent the most penetrable entry point for wearable sensor vendors establishing BIS certification partnerships ahead of domestic league professionalization. Bluetooth Low Energy solutions for budget-constrained amateur clubs offer a second white-space target where incumbent hardware bundles prove cost-prohibitive. A modular SaaS go-to-market angle bypasses upfront capex barriers that stall perpetual-license conversions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors firmware engineering specialists with proven 10–20 Hz sampling optimization capabilities. Long-term viability hinges on edge-computing talent acquisition as real-time predictive models displace retrospective analytics architectures. The signal to watch is NCAA Division I conference-level enterprise SaaS negotiations decoupling data platform access from specific device manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FIFA EPTS Certification Investment | World Cup eligibility requirements compress hardware development timelines and reshape vendor competitive positioning. |
| Edge-Computing Firmware Acquisition | Battery-constrained wearable form factors demand scarce embedded engineering talent for real-time inference optimization. |
| Cloud Data Lake Partnership | League-mandated centralized analytics repositories displace on-premises installations and fragment traditional hardware-software bundles. |
| Hybrid Positioning System Development | Indoor venue GPS degradation thresholds force complementary UWB infrastructure investments for basketball and handball federations. |
| India Market Certification Entry | BIS alignment for electronic performance tracking systems captures first-mover positioning in professionalizing cricket and kabaddi leagues. |
Research Methodology
Operator-level perspectives from professional league performance directors, collegiate athletic conference technology officers, wearable sensor firmware engineers, and federation procurement managers anchored the qualitative base. Primary interview findings combined with secondary validation against FIFA Quality Programme certification records, FCC spectrum allocation filings for 6 GHz UWB operations, and EU AI Act implementation guidance. Bottom-up vendor revenue triangulation against top-down league infrastructure spending estimates calibrated segmentation-level outputs.
Scenario-bracketing around regulatory compliance timelines and semiconductor supply volatility shaped the analytical framework across the projection horizon. Technology, application, end user, and deployment topology dimensions were modeled with geographic regulatory cluster overlays. CAGRs were derived from installed base expansion curves and replacement cycle dynamics, with inputs from NCAA Division I program adoption rates and Bundesliga youth system longitudinal monitoring investments.
Practitioners should monitor FIFA EPTS certification timeline shifts and EU national football association data sovereignty rule divergence for early signals of forecast revision. Cross-checking against professional league collective bargaining agreement data privacy provisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Daily Fantasy Sports Market
Sports Analytics
Sports Analytics Market
Sports Analytics
India Fantasy Sports Market
Sports Analytics
Youth Sports Software Market
Sports Analytics
Player Tracking System Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Fantasy Sports Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
North America Fantasy Sports Market