
 Sports Analytics Market | 2026-2036
Sports Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Analytics Market Analysis
Platform licensing revenue is narrowing as vendors bundle analytics tools with broader enterprise software suites. Oracle Corporation leverages its cloud infrastructure to integrate performance databases with customer relationship management systems. Sportsradar AG anchors its position through exclusive data distribution agreements with major sports leagues. SAS Institute Inc competes on statistical computing depth, sustaining R&D intensity in predictive modeling for injury risk.
Sports analytics encompasses the systematic collection, processing, and interpretation of athlete, team, and competition data using statistical methods, machine learning algorithms, and sensor-based tracking systems operating at sub-meter positional accuracy and millisecond temporal resolution. The discipline serves to optimize competitive outcomes, reduce injury incidence, and monetize fan attention through personalized content delivery. Cloud-based delivery models now capture the fastest expansion as franchises abandon on-premises server maintenance for elastic compute resources. Player tracking solutions concentrate margin pools through proprietary hardware-software integration, while fan engagement platforms mature into subscription-based recurring revenue architectures.
FCC guidelines on wireless spectrum allocation shape wearable device connectivity standards for real-time biometric transmission in US stadiums. GDPR and the EU AI Act impose consent-layer requirements on athlete data processing, forcing platform redesigns for cross-border team operations. ISO 27001 certification has become a de facto prerequisite for vendor selection among privacy-sensitive European football clubs. Stakeholders must weigh interoperability investments against the fragmentation risk of league-specific data formats that threaten platform scalability.
Market Dynamics
Cloud migration is collapsing the traditional on-premises infrastructure model across professional sports franchises, forcing vendors to rearchitect delivery mechanisms around elastic compute and API-first data exchange protocols.
Growth Catalysts
- Collegiate athletic procurement:United States university athletic departments now mandate integrated performance management suites for recruitment and injury prevention, creating institutional demand pull.
- GDPR Article 9 athlete consent frameworks:European football clubs have operationalized granular biometric data consent layers, enabling cross-border player transfers with compliant data portability.
- Sub-meter positional tracking:Ultra-wideband and computer vision fusion delivers millisecond-resolution athlete telemetry, embedding analytics into live tactical decision-making.
Market Restraints
- Proprietary hardware-software lock-in:Player tracking vendors maintain closed ecosystems, fragmenting data formats and inflating total cost of ownership for multi-vendor deployments.
- EU AI Act high-risk system classification:Automated injury prediction algorithms face mandatory conformity assessments, extending deployment timelines for European teams.
- Biometric sensor supply concentration:MEMS accelerometer and gyroscope fabrication clusters in East Asian foundries expose franchises to geopolitical supply disruption.
Strategic Opportunities
- German Bundesliga second-tier clubs:Mid-market European football operations remain underpenetrated by enterprise-grade analytics, presenting SaaS entry points below top-flight pricing tiers.
- Wearable-to-broadcast latency compression:5G edge computing convergence enables real-time fan-facing biometric visualizations, unlocking subscription revenue streams.
- ISO 27001 certification arbitrage:Privacy-sensitive clubs in Switzerland and Scandinavia prioritize certified vendors, creating competitive moats for compliant platforms.
Industry Challenges
- Interoperable data ontology development:League-specific event coding schemes prevent seamless analytics portability when athletes transfer between competitions.
- Biomechanist and data scientist compensation inflation:Talent scarcity in sports-specific machine learning and kinesiology functions strains franchise operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Analytics Market |
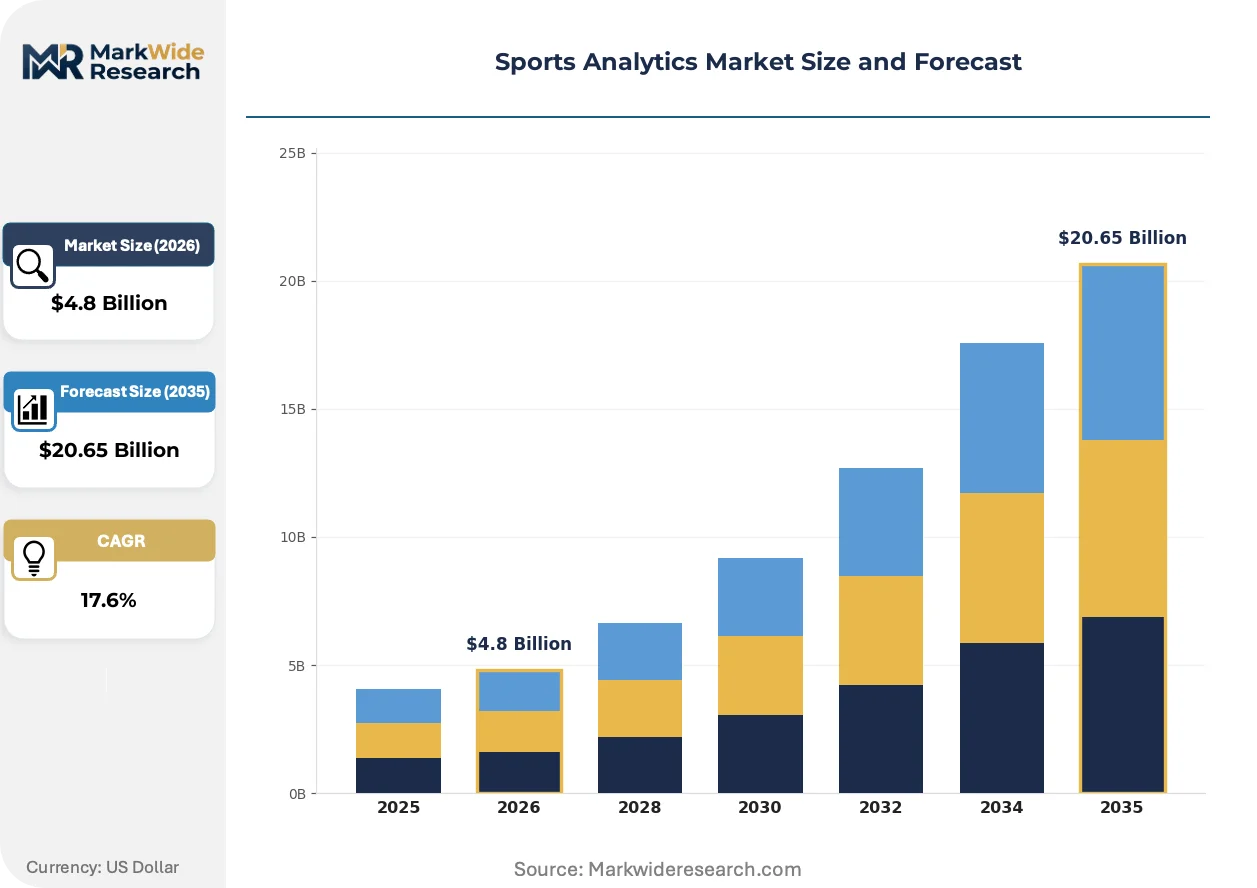
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Performance Analysis, Fan Engagement, Player Tracking, Video Analysis End User: Teams, Coaches, Sports Leagues, Analysts Delivery Model: On-Premises, Cloud-Based, Hybrid, Software as a Service Application: Training Optimization, Game Strategy, Injury Prevention, Talent Scouting |
| Companies Covered | Oracle Corporation, Sportsradar AG, SAS Institute Inc, Genius Sports Group, Stats Perform, Catapult Group International Ltd, SAP SE, Hudl, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Analytics Market Emerging Trajectories
Real-time data infrastructure is compressing decision cycles from post-match review to in-play tactical adjustment, while regulatory frameworks force architectural investments in consent management and algorithmic transparency.
Computer vision-based tracking is collapsing the hardware dependency of athlete monitoring systems. Premier League and NBA franchises now deploy camera-only solutions eliminating wearable device procurement and maintenance burdens. This shift reduces physiological data granularity but enables retrospective analysis of historical match footage without sensor retrofits.
GDPR and the EU AI Act impose layered consent requirements on automated athlete performance scoring. European clubs must maintain auditable trails for algorithmic processing of biometric data, with high-risk injury prediction systems facing mandatory human-in-the-loop review. German and French football federations have established certification pre-approval workflows extending vendor sales cycles.
Franchise procurement departments now unbundle analytics software from bundled hardware-service contracts. Athletic directors in the United States negotiate separate SaaS licenses for visualization platforms, data lake storage, and predictive modeling modules. This disaggregation pressures vendors to demonstrate standalone value, particularly in mid-market collegiate athletic departments with constrained capital allocation authority.
Sports Analytics Market Segmentation
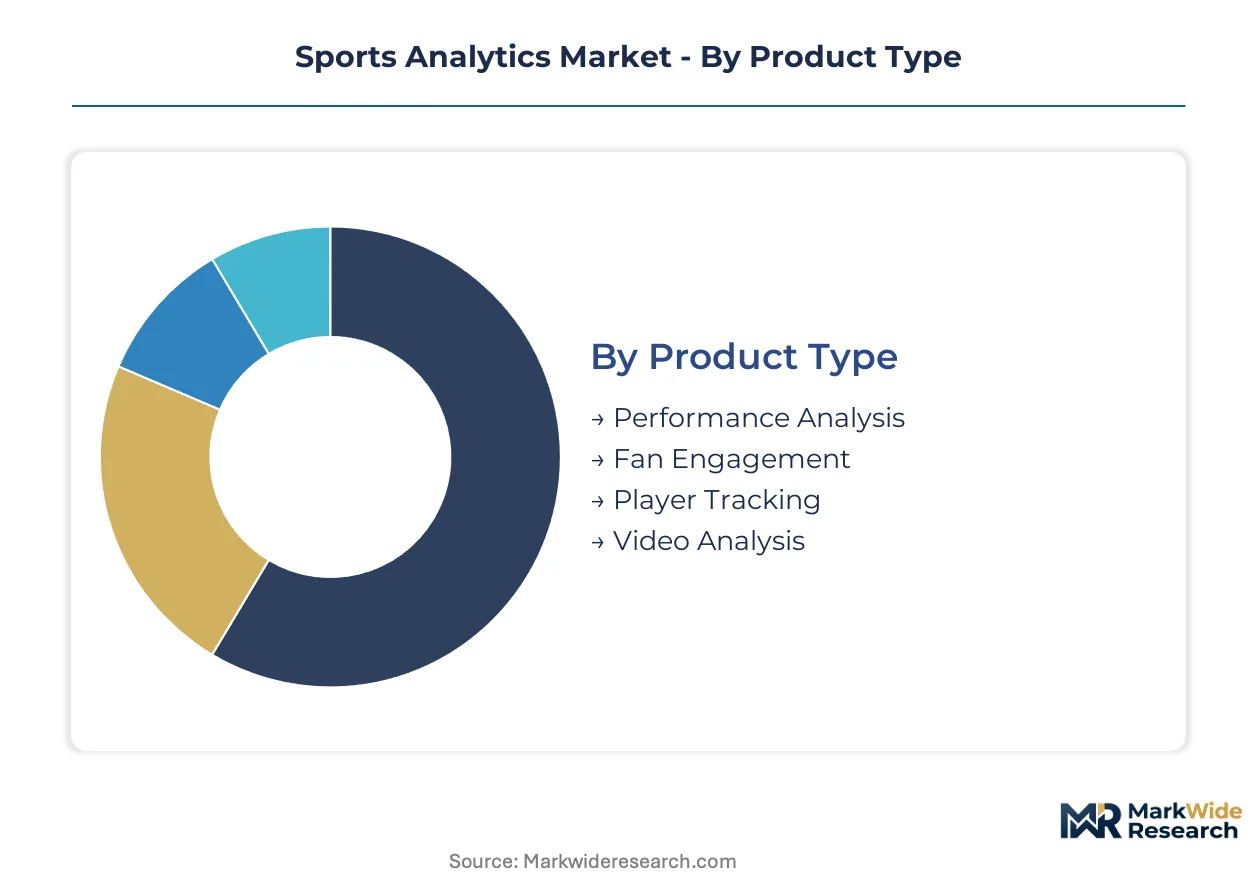
Segmentation in sports analytics reveals how technology investments fragment across operational priorities. Procurement patterns diverge sharply between franchises seeking competitive advantage and those monetizing audience attention.
Product Type:
Use-case spectrum spans real-time tactical decision-making to long-term fan relationship management, with hardware-software integration intensity varying dramatically.
- Performance Analysis:Statistical computing platforms process historical match data and opponent scouting reports through machine learning pipelines. English Premier League clubs deploy these systems for weekly tactical preparation, driven by coaching staff demands for predictive opponent modeling.
- Fan Engagement:Personalization engines deliver targeted content, betting integrations, and subscription services through mobile applications. United States collegiate athletic departments and professional franchises prioritize this segment for revenue diversification beyond ticket sales.
- Player Tracking:Ultra-wideband and computer vision systems capture sub-meter positional data at millisecond resolution.
- Video Analysis:Automated tagging and retrieval systems enable retrospective tactical review without manual annotation.
The dominant share belongs to Performance Analysis, while Fan Engagement is closing the gap fastest.
End User:
Customer type determines pricing tolerance and implementation complexity, with institutional buyers demanding enterprise-grade governance.
- Teams:Franchise operations integrate analytics across training, medical, and scouting departments, requiring cross-functional data governance.
- Coaches:Tactical staff consume visualization dashboards and predictive models for lineup optimization and in-game adjustments.
- Sports Leagues:Governing bodies mandate standardized data formats and distribute official statistics to broadcast partners and betting operators.
- Analysts:Independent consultants and media organizations license aggregated datasets for content production and wagering insights.
Teams command the largest procurement volumes, though Sports Leagues are expanding their platform mandates most aggressively.
Delivery Model:
Cost tier structures separate capital-intensive infrastructure from operational expenditure models, reshaping vendor competitive dynamics.
- On-Premises:Dedicated server installations with full data sovereignty remain prevalent among privacy-sensitive European football clubs navigating GDPR Article 9 requirements.
- Cloud-Based:Elastic compute resources enable seasonal scaling for event-driven analytics workloads. United States franchises are migrating fastest, abandoning server maintenance for API-first architectures.
- Hybrid:Sensitive biometric data resides locally while fan-facing applications leverage public cloud scalability.
- Software as a Service:Subscription licensing reduces upfront capital requirements for mid-market collegiate athletic departments with constrained procurement authority.
On-Premises retains share among compliance-driven buyers, yet Cloud-Based deployments are climbing the fastest as franchises prioritize operational flexibility.
Application:
Functional maturity varies across the athlete lifecycle, with injury prevention commanding premium pricing for risk mitigation value.
- Training Optimization:Load management algorithms balance performance gains against overuse injury risk using wearable-derived biomechanical data.
- Game Strategy:Real-time tactical recommendations during matches require sub-second latency from tracking systems to sideline tablets.
- Injury Prevention:Predictive models flag elevated risk profiles for soft-tissue injuries, though EU AI Act high-risk system classification extends deployment timelines in Europe.
- Talent Scouting:Automated performance scoring of prospective athletes combines statistical output with biometric potential indicators.
Training Optimization holds established share, while Talent Scouting is gaining traction fastest as recruitment costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States collegiate athletic departments absorb premium pricing for integrated performance suites, while mid-tier European football clubs force vendors toward modular SaaS offerings. Procurement authority concentrates in athletic directors with capital allocation autonomy.
United States
NCAA Division I athletic departments and NFL franchises drive enterprise software procurement through centralized technology budgets. FCC spectrum allocation guidelines for 5G stadium connectivity accelerate real-time biometric transmission deployments. The Dallas-Fort Worth metroplex hosts concentrated vendor development operations serving southwestern collegiate conferences.
Germany
Bundesliga clubs and second-tier 2. Bundesliga operations present divergent pricing tolerances for analytics platforms. The EU AI Act high-risk system classification mandates conformity assessments for automated injury prediction algorithms, extending vendor sales cycles. Munich and Dortmund anchor vendor service hubs supporting Rhine-Ruhr industrial cluster athletic operations.
United Kingdom
Premier League franchises embed real-time player tracking into weekly training cycles with substantial operational expenditure commitments. GDPR Article 9 athlete consent frameworks require granular biometric data audit trails for cross-border player transfers. London concentrates vendor headquarters and broadcast technology integration centers serving English Football League pyramid structures.
Australia
Australian Football League and National Rugby League franchises prioritize computer vision-based tracking over wearable hardware to reduce maintenance burdens. The country's national privacy regulator enforces athlete data processing standards aligned with GDPR-equivalent principles. Melbourne and Sydney host specialized biomechanist talent pools supporting Asia-Pacific franchise deployments.
Japan
Nippon Professional Baseball and J.League clubs demonstrate conservative procurement patterns favoring proven vendor relationships over emerging platform entrants. METI industrial digitization programs subsidize sensor technology adoption for Olympic training centers. The Kanto region around Tokyo concentrates domestic software development partnerships with European tracking vendors.
Sports Analytics Market Vendor Landscape
Capability concentration sits with specialized tracking hardware vendors; scale advantage sits with cloud infrastructure incumbents bundling analytics modules. The vendor base separates into three functional tiers: proprietary sensor-software integrators, statistical computing specialists, and enterprise platform bundlers. Dominant competitive moves include exclusive data distribution agreements with major sports leagues and API-first architecture investments collapsing on-premises infrastructure margins.
Within the enterprise bundling tier, Oracle Corporation and SAP SE exemplify cloud infrastructure leverage for integrated performance database deployment. Sportsradar AG occupies a position anchoring exclusive league data partnerships. Among specialized analytics providers, SAS Institute Inc represents statistical computing depth sustained through predictive modeling R&D intensity. Catapult Group International Ltd sits within the hardware-software integration archetype maintaining closed ecosystem architectures.
| Leading Market Players |
|---|
| Oracle Corporation |
| Sportsradar AG |
| SAS Institute Inc |
| Genius Sports Group |
| Stats Perform |
| Catapult Group International Ltd |
| SAP SE |
| Hudl |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
MEMS sensor fabrication concentration in East Asian foundries exposes analytics vendors to tariff volatility and single-source dependency, compressing margin pools at the hardware tier while forcing SaaS providers to absorb component cost spikes through subscription pricing.
Pricing Analysis
After-sales service contracts and extended platform maintenance agreements drive lifetime value for enterprise analytics vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by data governance requirements and integration complexity. Price differentiation rests on ISO 27001 certification status and customization depth for league-specific data formats. Cost compression in the mid-market SaaS tier is intensifying because collegiate athletic departments negotiate unbundled module licensing. Franchise operations demonstrate lowest price sensitivity; second-tier European football clubs exhibit highest.
Supply Chain Analysis
Extended payment terms from Bundesliga and Premier League franchises strain vendor working capital, accelerating supply-chain finance facility adoption among tracking hardware manufacturers. Component sourcing centers on Taiwan for MEMS sensors, South Korea for precision optics, and Germany for industrial-grade computing enclosures. Raw material dependencies span lithium-ion cells for wearable power systems, rare earth elements for magnetometer calibration, and specialized polymers for device housings. Single-source vulnerability concentrates in UWB chipset fabrication. Distribution runs through direct enterprise sales teams serving top-tier leagues, with channel partners penetrating mid-market collegiate and second-tier club segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time tactical decision-making infrastructure represents high-growth disruption, with 5G edge computing convergence compressing wearable-to-broadcast latency below one second.
For Market Incumbents: Insulate proprietary data format ecosystems through exclusive league distribution agreements that lock out multi-vendor interoperability. Deepen backward integration into sensor hardware production to offset MEMS foundry concentration risk. Prioritize ISO 27001 certification investment for Swiss and Scandinavian club procurement preference.
For New Entrants and Emerging Players: German 2. Bundesliga mid-market operations present underpenetrated demand for modular SaaS analytics below top-flight pricing thresholds. Target computer vision-only tracking solutions eliminating wearable procurement burdens for Australian Football League franchises. Deploy API-first architectures enabling rapid collegiate athletic department procurement cycles.
For Investors and Strategic Acquirers: EU AI Act high-risk system classification for automated injury prediction reshapes the acquisition landscape toward compliant algorithm vendors with established conformity assessment workflows. Long-term viability favors platforms with demonstrated cross-border data portability architectures. Monitor GDPR Article 9 consent-layer implementation depth as inflection indicator for European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Oracle Corporation bundles performance databases with CRM systems through cloud infrastructure leverage. |
| Exclusive Data Partnership | Sportsradar AG anchors market position through major league distribution agreements. |
| Certification Pre-Approval Workflow | German and French football federations extend vendor sales cycles for AI Act compliance. |
| Computer Vision Transition | Premier League franchises eliminate wearable maintenance through camera-only tracking deployment. |
| Geographic Expansion | Mid-market European football operations force SaaS entry points below enterprise pricing tiers. |
Methodological Framework
A standing panel of athletic directors, head coaches, performance analysts, and league technology officers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC vendor filings, hyperscaler cloud infrastructure disclosures, European football federation procurement databases, and ISO certification registries. Bottom-up segmentation modeling triangulated against top-down league technology budget aggregates.
Scenario-bracketing framed demand projections across the analysis window, with CAGRs derived from elasticity modeling against collegiate athletic expenditure patterns and professional franchise operational technology commitments. Segmentation dimensions spanned deployment model, organization tier, application function, and regional regulatory cluster. Forecast inputs incorporated 5G stadium infrastructure rollout timelines and EU AI Act implementation phase transitions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud infrastructure providers would shift outcomes. Macroeconomic deviation in collegiate athletic funding, regulatory acceleration in biometric data processing restrictions, or breakthrough computer vision accuracy improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Fantasy Sports Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Player Tracking System Market
Sports Analytics
Youth Sports Software Market
Sports Analytics
Daily Fantasy Sports Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
India Fantasy Sports Market