
 Youth Sports Software Market | 2026-2036
Youth Sports Software Market Size, Share, and Industry Trends Forecast 2026-2036
Youth Sports Software Market Insights
Capital-intensity divergence between venture-backed platforms and bootstrapped specialists is redrawing competitive boundaries in youth sports software. Stack Sports leverages its multi-sport federation partnerships to sustain enterprise-grade infrastructure across state-level governing bodies. TeamSnap anchors the parent-coach communication layer with freemium conversion mechanics that dominate smaller leagues. SportsEngine competes through deep integration with US Olympic and Paralympic Committee pipelines, controlling elite youth athlete pathways.
Youth sports software encompasses cloud-native and on-premise applications that automate league operations, athlete development tracking, and stakeholder communication through web portals and native mobile interfaces. These platforms consolidate scheduling algorithms, payment processing, and roster management into unified dashboards that reduce administrative overhead for volunteer-run organizations. Scheduling and registration modules command the largest revenue share because municipal parks departments and school athletic directors require centralized capacity management across fragmented seasonal calendars. Performance tracking and analytics services represent the fastest-expanding margin pool as biometric wearables and video analysis tools migrate from elite academies to suburban travel teams.
US-based providers navigate COPPA compliance constraints enforced by the FTC, while European deployments face GDPR consent architectures that complicate minor athlete data collection. The EU AI Act introduces additional scrutiny for automated coaching recommendations and predictive injury algorithms. Stakeholders must monitor how state-level biometric privacy statutes in Illinois and Texas reshape permissible data capture for athlete development platforms.
Market Dynamics
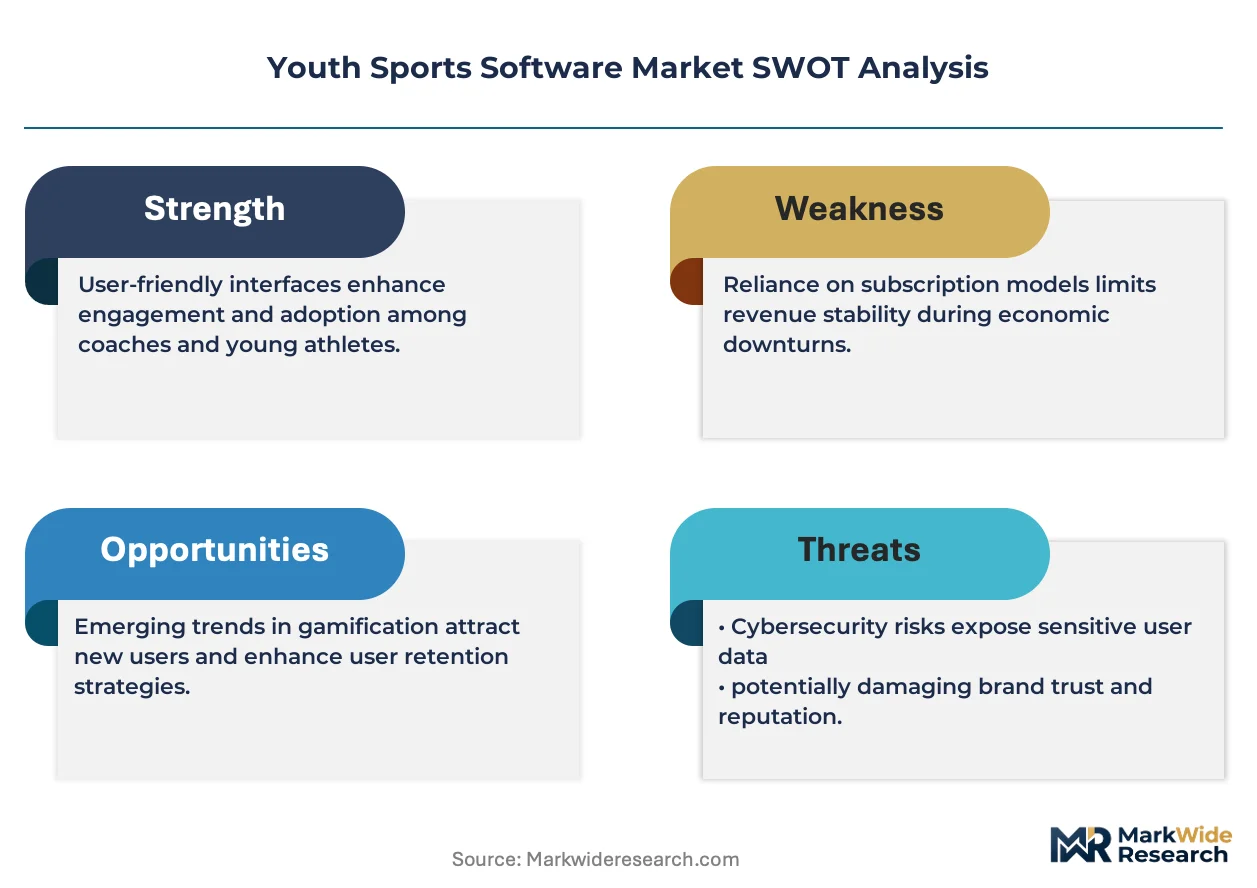
Cloud-native architectures are consolidating volunteer-run league operations onto centralized platforms, compressing procurement cycles for municipal recreation departments and eroding the viability of legacy on-premise installations.
Growth Catalysts
- FTC COPPA enforcement:Federal compliance mandates compel leagues to adopt purpose-built software with verifiable parental consent workflows, disqualifying general-purpose CRM tools from youth athlete data management.
- Biometric wearable integration:Suburban travel teams now demand athlete development platforms that ingest heart-rate variability and GPS tracking data, expanding addressable spend per roster slot.
- Illinois BIPA and Texas biometric statutes:State-level privacy litigation risk accelerates platform upgrades to consent-management modules with audit trails, forcing replacement of paper-based waiver systems.
Market Restraints
- GDPR minor consent architectures:European deployments require granular parental authorization layers that fragment user experience and extend implementation timelines for multi-country federations.
- Payment processor concentration:Dependency on Stripe and PayPal for subscription billing exposes smaller vendors to rate hikes that compress already-thin margins in the freemium tier.
- Volunteer technical literacy gaps:League administrators averaging 55+ years resist dashboard complexity, capping feature utilization rates and slowing upgrade adoption.
Strategic Opportunities
- EU AI Act compliance services:Automated coaching recommendation engines face new algorithmic transparency requirements, creating advisory revenue streams for audit-ready platform configurations.
- Video analysis convergence:Integration of computer-vision stroke mechanics with mobile capture apps opens amateur baseball and tennis academies previously served only by elite-tier tools.
- School district consolidation:Procurement centralization across county athletic director offices favors vendors with FERPA-compliant student information system connectors.
Industry Challenges
- Salesforce-to-platform API fragility:Custom integrations with legacy district ERP systems require dedicated engineering resources that strain mid-tier vendor capacity.
- Seasonal cash flow compression:Annual registration spikes followed by nine-month dormancy complicate SaaS metric reporting and investor diligence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Youth Sports Software Market |
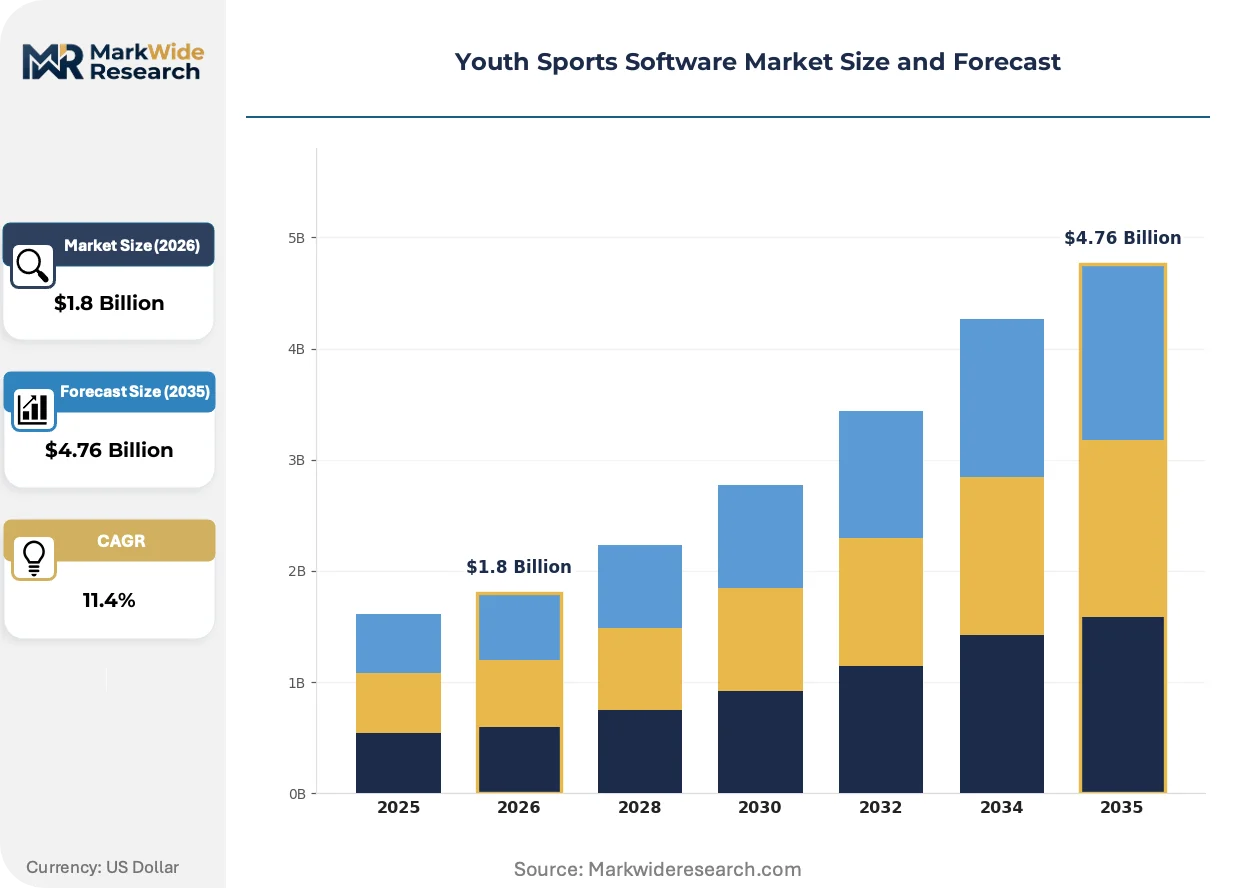
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling, Team Management, Performance Tracking, Registration Service Type: Coaching, Analytics, Event Management, Communication End User: Coaches, Parents, Players, Organizations Integration Level: Cloud-Based, On-Premise, Hybrid, Mobile-Optimized |
| Companies Covered | Jonas Club Software, Stack Sports, TeamSnap, Sprocket, Jersey Watch, SportsEngine, PlayMetrics, Mojo Sport, LeagueApps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Youth Sports Software Market Trends and Innovations
Native mobile-first architectures are compressing the functionality gap between enterprise league management platforms and consumer-grade communication tools, reshaping vendor competitive moats around data portability rather than feature depth.
Artificial intelligence-powered injury risk scoring is supplanting static load-management spreadsheets in travel soccer and basketball programs. Elite youth academies in Southern California and Texas now mandate predictive algorithms that flag overuse patterns before tissue damage manifests. This capability compression is forcing mid-market vendors to license third-party biomechanics APIs or cede the performance analytics segment entirely.
The EU AI Act's risk classification framework for automated decision-making systems now governs coaching recommendation engines deployed in German and French youth federations. Platforms must document training data provenance and maintain human-in-the-loop override protocols. Vendors serving continental European markets are reengineering algorithmic transparency dashboards ahead of enforcement deadlines.
Parent-coach communication preferences have shifted from email threading to asynchronous video updates and automated push notifications. This channel migration pressures legacy platforms built around desktop-optimized scheduling grids. Municipal recreation departments in Florida and Arizona now prioritize mobile-native registration flows that mirror consumer app expectations.
Youth Sports Software Market Segmentation
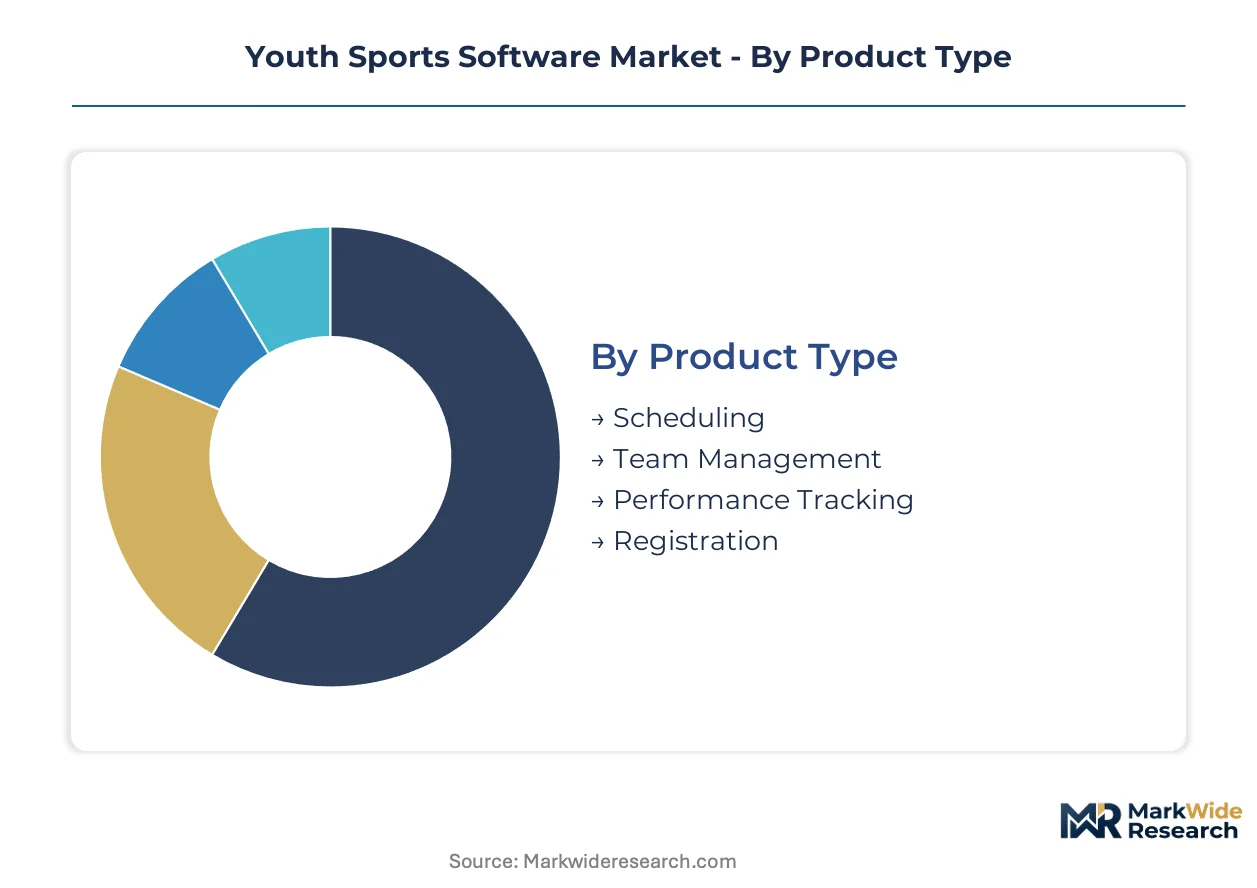
Youth sports software procurement follows distinct purchasing logic across product categories, with volunteer-run leagues prioritizing administrative relief while travel programs invest in athlete development capabilities. Understanding segment substitution pressures reveals where specialized vendors face displacement from adjacent platform categories.
Product Type:
Scheduling modules face the strongest substitution threat from general-purpose calendaring tools, forcing vendors to embed payment processing and roster management as defensive differentiators.
- Scheduling:Algorithms optimize field utilization across fragmented seasonal calendars for municipal parks departments. School athletic directors in Texas and Florida drive consolidation onto platforms with real-time rainout notifications and automated reschedule propagation.
- Team Management:Consolidates roster administration, parent communication, and volunteer coordination into unified dashboards. Suburban travel baseball and soccer programs in Southern California anchor demand for mobile-first architectures that compress administrative overhead.
- Performance Tracking:Ingests biometric wearable data and video analysis for athlete development pathways.
- Registration:Handles payment processing, medical waiver collection, and COPPA-compliant parental consent workflows.
Scheduling anchors the volume base while Performance Tracking gains share at the steepest rate.
Service Type:
Cost tier stratification separates premium analytics subscriptions from commoditized communication features, with mid-market vendors struggling to defend pricing in the coaching advisory layer.
- Coaching:Delivers drill libraries, practice planning tools, and certification tracking for volunteer and paid instructors. State-level governing bodies in Illinois and Ohio mandate platform integration with mandatory safety training modules.
- Analytics:Transforms GPS tracking and heart-rate variability data into actionable load-management recommendations. Elite youth academies expanding most quickly demand predictive injury algorithms that flag overuse patterns before tissue damage manifests.
- Event Management:Supports tournament bracket generation, referee assignment, and spectator communications.
- Communication:Provides asynchronous video updates and push notifications replacing email threading.
Communication services anchor the volume base while Analytics climbs the fastest as biometric integration penetrates suburban travel programs.
End User:
Application intensity varies sharply across user types, with organizations capturing the highest per-seat value while parents drive freemium conversion mechanics.
- Organizations:Leagues, clubs, and municipal recreation departments require enterprise-grade compliance architectures. Multi-sport federations in the United States prioritize platforms with FERPA-compliant student information system connectors.
- Coaches:Volunteer and professional instructors need mobile-optimized practice planning and athlete feedback tools. Technical literacy gaps among administrators averaging 55+ years constrain feature utilization rates.
- Parents:Demand simplified registration flows and real-time schedule updates through native mobile interfaces.
- Players:Access development tracking and team communication features through guardian-mediated accounts.
Organizations anchor the volume base while Coaches show the steepest expansion trajectory as platform vendors target the volunteer administrator segment.
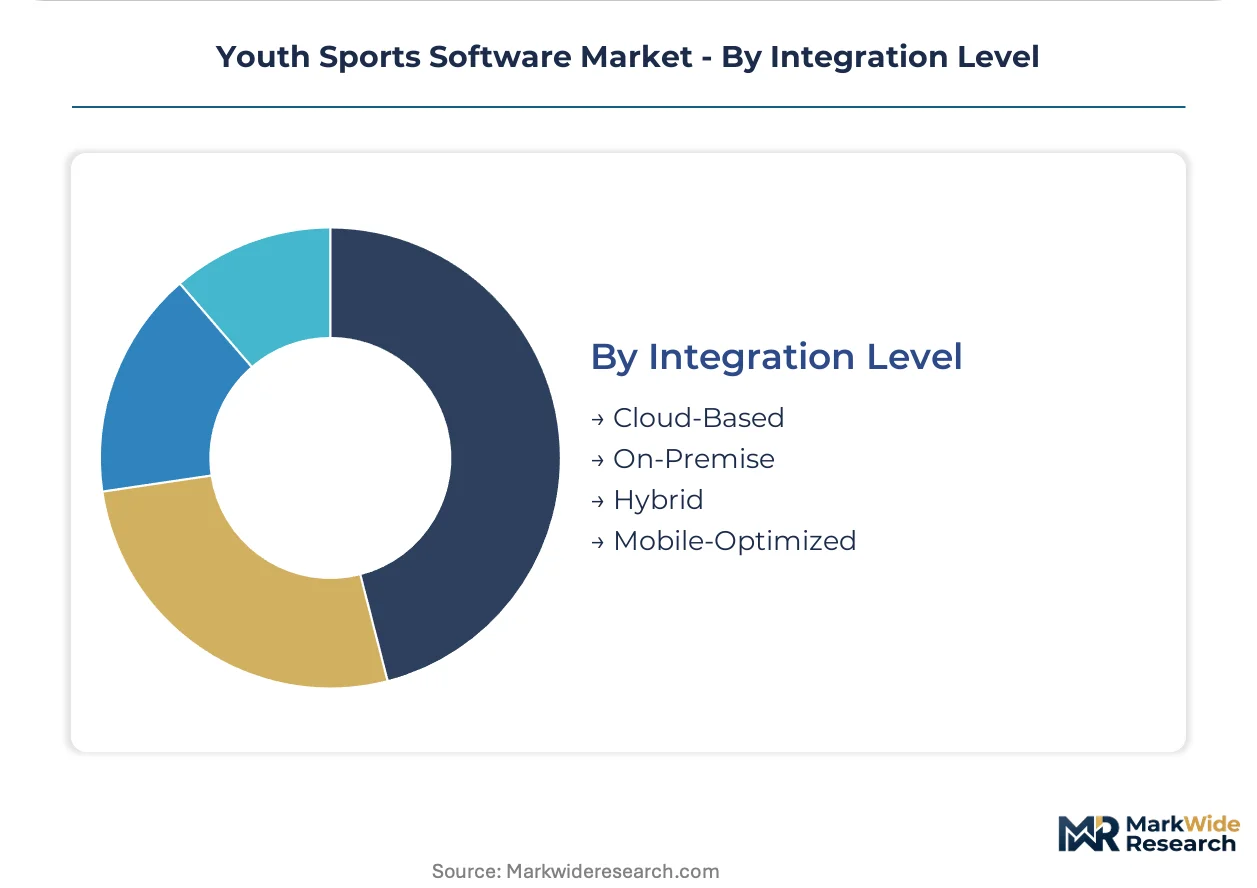
Integration Level:
Customer type migration from on-premise legacy systems to cloud-native architectures is compressing procurement cycles and eroding maintenance revenue streams for installed-base vendors.
- Cloud-Based:Centralized infrastructure enables automatic updates and multi-tenant cost efficiency. Municipal recreation departments prioritize this deployment model for seasonal capacity scaling.
- Mobile-Optimized:Native iOS and Android architectures mirror consumer app expectations for registration and communication. Arizona and Florida districts now mandate mobile-first procurement specifications.
- Hybrid:Combines cloud accessibility with on-premise data residency for sensitive athlete records.
- On-Premise:Legacy installations persist in districts with restrictive IT procurement policies.
Cloud-Based deployments anchor the volume base while Mobile-Optimized configurations gain share fastest as parent-coach communication preferences shift to asynchronous channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Municipal recreation departments in the United States absorb premium pricing for compliance-heavy platforms, while volunteer leagues in Southern Europe prioritize low-cost scheduling modules over integrated suites.
United States
School districts and municipal parks departments drive platform consolidation across fragmented seasonal calendars. FTC COPPA enforcement compels leagues to adopt purpose-built software with verifiable parental consent workflows. Southern California and Texas host elite youth academies that mandate predictive injury algorithms for athlete development pathways.
Germany
State-level sports federations prioritize EU AI Act compliance for automated coaching recommendation engines. The country's national data protection regulator enforces granular parental authorization layers that extend implementation timelines. Bavarian youth football clubs anchor demand for algorithmic transparency dashboards ahead of enforcement deadlines.
United Kingdom
County-level athletic associations consolidate procurement across multi-sport programs. GDPR minor consent architectures complicate biometric data collection for wearable-integrated platforms. Greater London and the Southeast concentrate travel team demand for mobile-native registration flows.
France
Municipal sports offices prioritize FERPA-equivalent student data protection in school district deployments. The country's national data protection regulator scrutinizes automated decision-making systems under EU AI Act risk classifications. The Île-de-France region concentrates federation-level platform upgrades for audit-ready configurations.
Canada
Provincial recreation departments migrate from legacy on-premise installations to cloud-native architectures. Health Canada guidelines influence medical waiver collection modules for youth athlete platforms. Ontario and British Columbia lead procurement centralization across county athletic director offices.
Youth Sports Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with venture-backed platforms sustaining enterprise-grade infrastructure while bootstrapped vendors dominate single-function niches. The market structure compresses procurement cycles as municipal buyers favor unified suites over point solutions. Three archetypes prevail: federation-anchored enterprise vendors, freemium communication specialists, and biometric analytics integrators. Dominant competitive moves include strategic partnerships with state governing bodies and technology licensing for third-party biomechanics APIs.
Within the federation-anchored tier, Stack Sports and SportsEngine exemplify platform consolidation through multi-sport governing body relationships. TeamSnap occupies a position in the parent-coach communication layer with conversion mechanics targeting smaller leagues. These three vendors represent divergent capital-intensity strategies reshaping competitive boundaries across North American and European deployments.
| Leading Market Players |
|---|
| Jonas Club Software |
| Stack Sports |
| TeamSnap |
| Sprocket |
| Jersey Watch |
| SportsEngine |
| PlayMetrics |
| Mojo Sport |
| LeagueApps |
| Others |
Pricing and Supply Chain Analysis
Mobile-first platform architectures replacing legacy desktop installations are redrawing supplier geography toward cloud infrastructure hubs and compressing pricing power for on-premise vendors. This substitution simultaneously concentrates compute procurement in United States and European data center regions while forcing established players to absorb margin erosion from freemium conversion mechanics.
Pricing Analysis
Analytics subscription renewals and biometric API licensing now drive lifetime value beyond initial SaaS deployment. Three-tier pricing structure across premium, standard, and economy levels segments by compliance depth and integration complexity. Pricing pressure stems from Stripe and PayPal rate exposure that squeezes freemium-tier margins. Municipal recreation departments show lowest price sensitivity for COPPA-compliant suites, while volunteer-run leagues resist premium upsells.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure provisioning for North American and European deployments respectively. Compute capacity draws from hyperscaler data centers, biometric sensor hardware sources from East Asian manufacturing, and third-party biomechanics APIs feed from specialized sports science laboratories. Single-source vulnerability concentrates in payment processor dependencies. Distribution runs through direct sales to federations and self-serve onboarding for smaller leagues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Youth sports software represents a high-growth disruption as EU AI Act enforcement reclassifies automated coaching engines as high-risk systems requiring algorithmic transparency. This regulatory inflection compresses vendor timelines for compliance architecture and creates first-mover advantages for audit-ready platforms.
For Market Incumbents: Consolidate federation partnerships into exclusive multi-year agreements before state governing bodies complete procurement centralization. Acquire specialized biometric analytics firms to close capability gaps against elite academy demands. Vertical integration into third-party biomechanics APIs defends margin position as licensing costs escalate. For New Entrants and Emerging Players: Lead with mobile-native registration flows targeting Arizona and Florida municipal districts with explicit mobile-first procurement mandates. White-space concentrates in Illinois and Texas biometric consent-management modules where state litigation risk forces paper-system replacement. Freemium conversion mechanics anchored on parent communication features penetrate suburban travel baseball leagues with lowest incumbent saturation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed platforms that have exhausted Series C runway without path to profitability. Five-to-ten year viability hinges on FERPA-compliant student information system connector penetration in consolidated school districts. Watch for FTC COPPA enforcement acceleration as signal for compliance-heavy platform valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Architecture | Algorithmic transparency dashboards satisfy Bavarian youth federation audit requirements ahead of enforcement. |
| Biometric API Licensing | Third-party biomechanics partnerships close capability gaps for suburban travel team predictive injury algorithms. |
| Federation Partnership Consolidation | Exclusive state governing body agreements block competitor access to procurement centralization pipelines. |
| Mobile-First Platform Migration | Native iOS and Android architectures match Arizona and Florida municipal procurement specifications. |
| Payment Processor Diversification | Multi-gateway billing infrastructure reduces Stripe and PayPal rate exposure for freemium-tier margins. |
Research Methodology
A standing panel of municipal recreation directors, youth league administrators, platform CTOs, and state federation technology officers provided ongoing calibration throughout data collection. Primary interviews with these stakeholders combined with secondary validation against FTC enforcement records, GDPR implementation guidance, EU AI Act regulatory texts, and hyperscaler infrastructure disclosure filings. Bottom-up league penetration modeling triangulated against top-down addressable spend estimates across volunteer-run and travel program segments.
Consistency checks validated volume and value outputs against external benchmarks including federation procurement databases and municipal IT budget disclosures. The analytical framework segmented by deployment model, organization size, sport vertical, integration complexity, and regional regulatory cluster across the analysis window. CAGRs derived from logistic adoption curves calibrated to cloud migration timelines and mobile-native replacement cycles. Forecast inputs incorporated seasonal cash flow compression patterns and volunteer administrator technical literacy constraints.
Forecasts assume regulatory continuity in FTC COPPA enforcement, GDPR minor consent architectures, and EU AI Act risk classifications; material policy shifts would require re-modeling. Specific risks include state-level biometric privacy statute expansion beyond Illinois and Texas, payment processor rate volatility, and hyperscaler infrastructure pricing adjustments. Recalibration cycles align with material shifts in federation procurement centralization and seasonal registration pattern disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Fantasy Sports Market
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
Player Tracking System Market
Sports Analytics
India Fantasy Sports Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Daily Fantasy Sports Market