
 India Fantasy Sports Market | 2026-2036
India Fantasy Sports Market Size, Share, and Industry Trends Forecast 2026-2036
India Fantasy Sports Market Insights
User concentration across India's fantasy sports landscape is pivoting from metro-centric professional players toward fragmented casual gamers in tier-2 and tier-3 cities. Dream Sports Group leverages its cricket-first portfolio to dominate premium pay-to-play contests. Mobile Premier League sustains multi-sport engagement across kabaddi and football formats. My11Circle competes through celebrity-endorsed user acquisition campaigns targeting mass-market smartphone owners.
India fantasy sports constitute digital skill-based gaming platforms where participants assemble virtual teams using real athlete performance data and compete for cash prizes based on statistical outcomes. These platforms operate on real-time data pipelines integrating live match feeds, player injury updates, and weather variables to calculate dynamic scoring. Daily fantasy formats command the highest engagement frequency among casual gamers seeking immediate gratification, while season-long leagues anchor retention among cricket devotees tracking IPL and international calendars. Mobile apps capture the dominant share of platform access as Jio-enabled data penetration extends into rural districts, though social media-embedded mini-games emerge as a low-friction acquisition channel for first-time users.
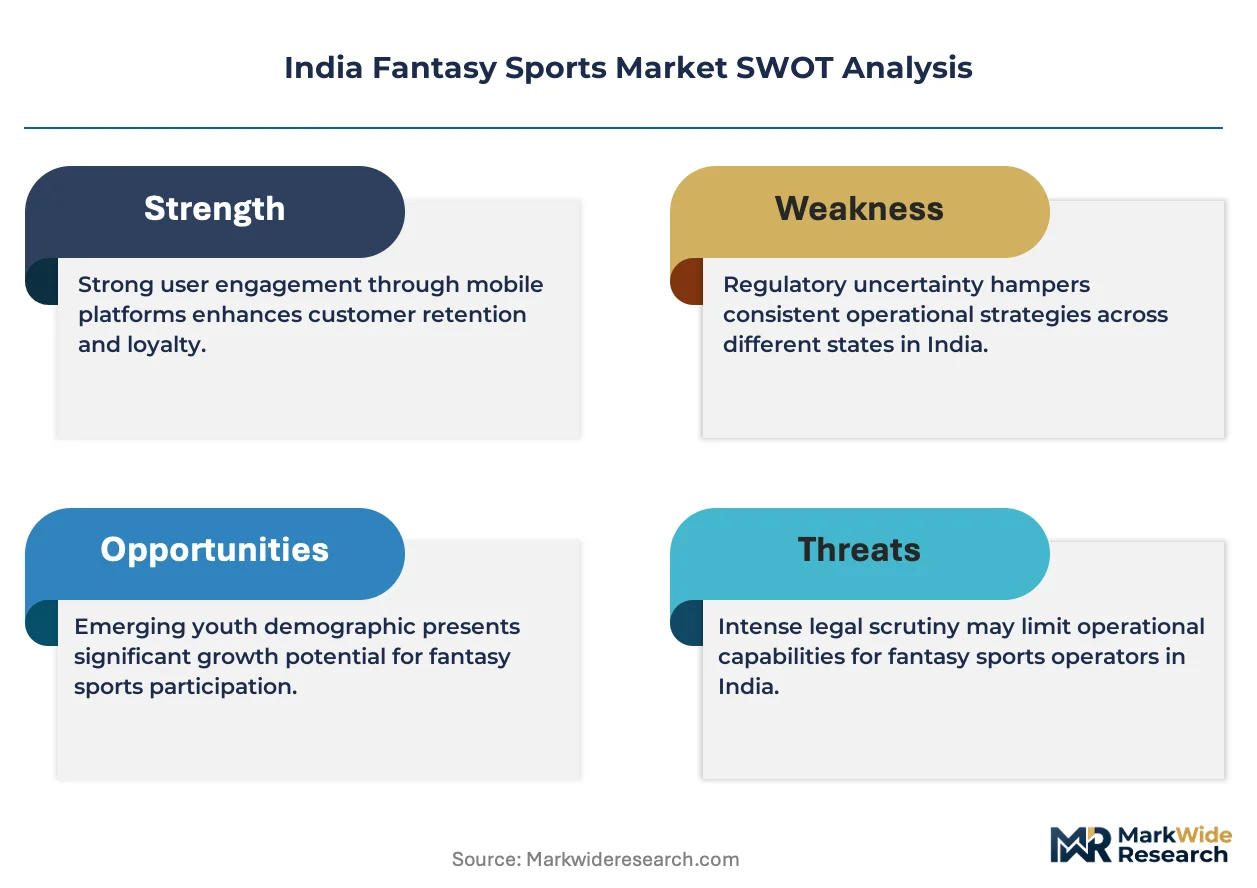
BIS data localization mandates and RBI's payment aggregator guidelines shape platform architecture by requiring domestic server infrastructure and compliant escrow mechanisms for user deposits. The Ministry of Electronics and Information Technology's draft online gaming rules and state-level gambling prohibitions create a patchwork compliance environment that operators must navigate across Maharashtra, Karnataka, and Telangana. Stakeholders should monitor judicial interpretations of skill versus chance distinctions as these rulings determine market access across India's federal regulatory landscape.
Market Dynamics
The GST Council's 28% tax levy on full-face-value gaming deposits is compressing operator margins and forcing platform architecture redesigns around escrow mechanics and user retention systems.
Growth Catalysts
- Jio-enabled rural data penetration:Reliance Jio's network expansion into tier-2 and tier-3 districts is converting first-time smartphone owners into fantasy sports participants through low-cost data plans.
- PLI scheme for digital infrastructure:India's production-linked incentive scheme subsidizes domestic data center buildouts, reducing latency for real-time scoring engines and live match integrations.
- Cricket calendar density:The Indian Premier League's compressed tournament format and year-round international fixtures sustain daily engagement frequency among casual gamers seeking immediate contest resolution.
Market Restraints
- GST rate structure:The 28% levy applied to full deposit value rather than platform fees creates a structural cost burden that operators cannot fully pass to price-sensitive mass-market users.
- State-level gambling prohibitions:Maharashtra, Karnataka, and Telangana maintain distinct legal interpretations of skill-versus-chance distinctions, fragmenting compliance architecture across India's federal system.
- Payment aggregator concentration:RBI's escrow mandates concentrate deposit flows through licensed payment aggregators, creating single-point vulnerabilities in user fund management.
Strategic Opportunities
- Tier-2 city expansion:Gujarat and Tamil Nadu's cricket-devoted populations remain underpenetrated by season-long league formats that anchor retention and reduce customer acquisition costs.
- Social media mini-games:WhatsApp and Instagram-embedded low-friction contests bypass app store friction for first-time user acquisition in data-conscious rural segments.
- BIS data localization:Domestic server mandates create competitive moats for operators with compliant infrastructure against foreign platforms lacking India-specific architecture.
Industry Challenges
- Judicial uncertainty on skill classification:Pending high court rulings on whether daily fantasy formats constitute gambling or skill gaming create licensing timeline unpredictability across state jurisdictions.
- Real-time data pipeline costs:Integrating live match feeds, player injury updates, and weather variables requires capital-intensive partnerships with sports data providers and broadcast rights holders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Fantasy Sports Market |
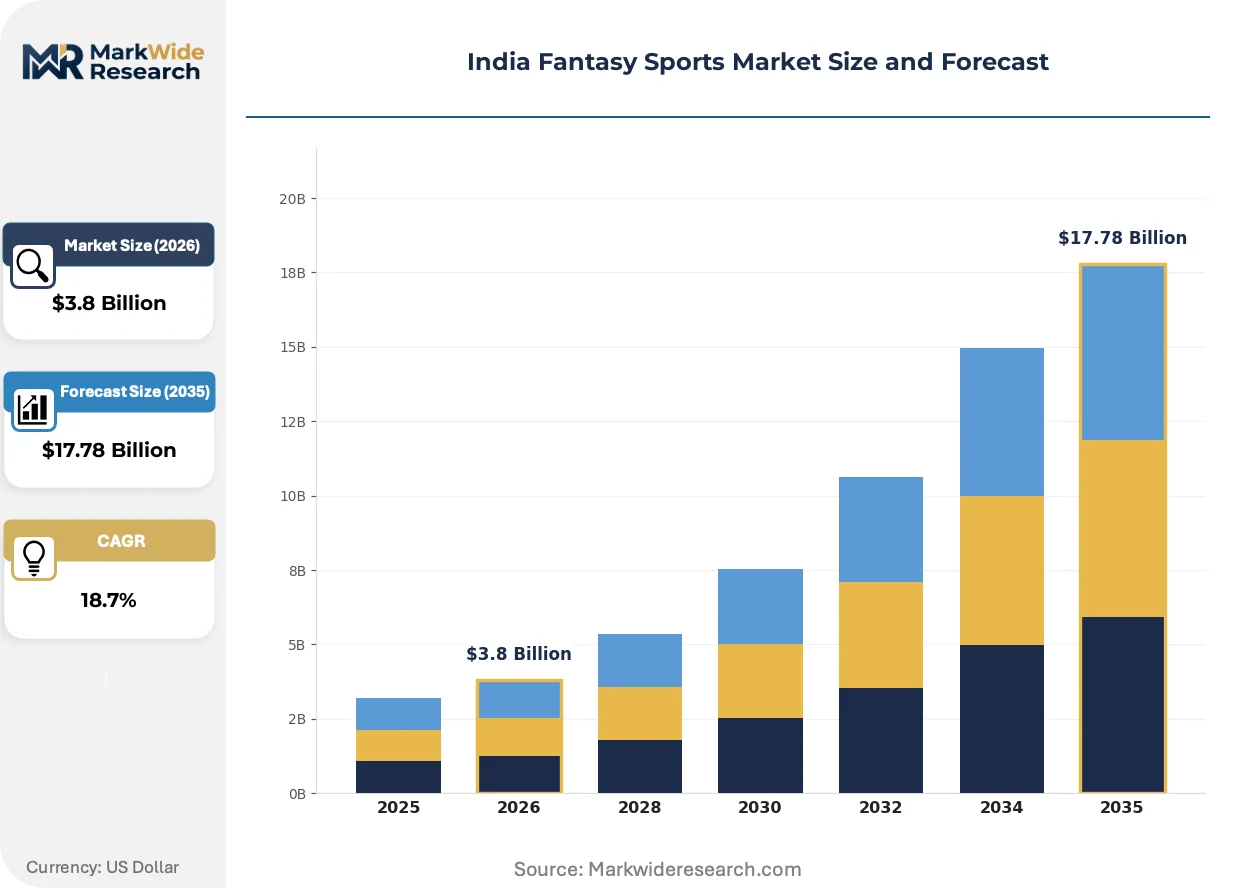
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daily Fantasy, Season-long Fantasy, Free-to-play, Pay-to-play End User: Casual Gamers, Professional Players, Sports Enthusiasts, Social Players Platform: Mobile Apps, Websites, Social Media, Desktop Applications Sport Type: Cricket, Football, Basketball, Kabaddi |
| Companies Covered | Dream Sports Group, Mobile Premier League, 11 Wickets.com, BalleBaazi, MyTeam11, My11Circle, Games24x7, Vision11, Paytm First Games, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Fantasy Sports Market Trends and Innovations
Platform economics are pivoting from deposit-volume maximization toward engagement-duration optimization as tax structures and user acquisition costs reshape unit economics.
Microservices-based scoring engines are modularizing fantasy platform architecture. Tier-1 operators are adopting containerized real-time calculation systems that separate player statistics ingestion from contest resolution logic. This modularization enables faster deployment of sport-specific scoring variants without core platform rebuilds, compressing time-to-market for kabaddi and football format extensions.
MeitY's draft online gaming rules are mandating self-regulatory body registration and know-your-customer protocols for all platforms above defined user thresholds. The industrial consequence is forced consolidation of compliance functions across smaller operators unable to sustain dedicated legal and verification teams. Maharashtra-based platforms are responding by pooling KYC infrastructure through third-party identity verification APIs.
Acquisition patterns are rotating from performance marketing toward influencer-embedded content. Cricket-focused YouTube creators and Instagram meme accounts are displacing traditional digital ad spend as the primary channel for reaching mass-market smartphone owners in tier-2 cities. This shift is most visible in Telangana and Karnataka, where platform marketing budgets now concentrate on regional-language creator partnerships rather than pan-India broadcast media.
India Fantasy Sports Market Segmentation
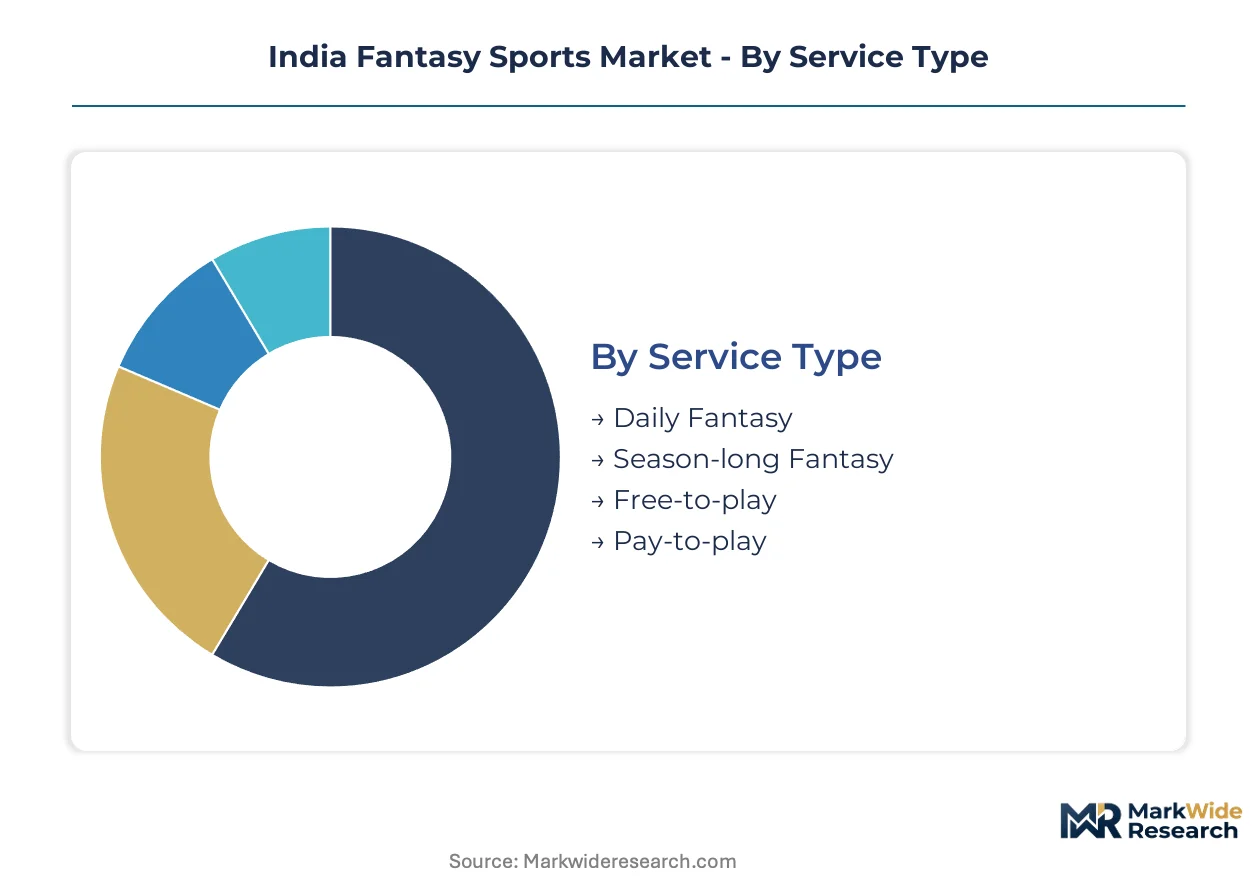
India's fantasy sports market fragments across four distinct dimensions that determine platform architecture, user acquisition costs, and regulatory exposure. Each segment carries unique margin profiles and compliance burdens shaped by GST Council rulings and state-level gambling interpretations.
Service Type:
Daily formats prioritize immediate gratification and high-frequency engagement, while season-long structures anchor retention through extended tournament calendars.
- Daily Fantasy:Compressed contest windows resolve within 24 hours using real-time player performance data. Maharashtra and Karnataka's casual gamer concentrations drive volume through IPL match days and international fixtures.
- Season-long Fantasy:Extended-duration leagues span entire tournament cycles with roster management across multiple gameweeks. Gujarat's cricket-devoted populations sustain participation through domestic league calendars.
- Free-to-play:Zero-deposit entry models bypass GST levy complications while building user bases for conversion to paid formats.
- Pay-to-play:Cash prize structures trigger full 28% tax exposure on deposits, compressing operator margins in Telangana's contested market.
Leading the category by volume: Daily Fantasy. Expanding most quickly: Pay-to-play as platforms optimize escrow mechanics around tax-efficient deposit structures.
End User:
User sophistication determines monetization depth, with professional cohorts extracting value through statistical modeling while mass-market segments respond to celebrity-endorsed acquisition campaigns.
- Casual Gamers:Smartphone-first participants in tier-2 and tier-3 districts seeking low-friction entertainment. Jio-enabled data penetration converts first-time owners into fantasy participants through compressed contest formats.
- Professional Players:Algorithm-assisted entrants deploying predictive models across multiple platform accounts. This segment concentrates in Mumbai and Bangalore's tech-corridor clusters.
- Sports Enthusiasts:Cricket-calendar followers tracking IPL and international fixtures with high platform loyalty and season-long engagement persistence.
- Social Players:Peer-network-driven participants entering private contests through WhatsApp group invitations and Instagram story shares.
Highest revenue per user: Professional Players. Fastest user base expansion: Casual Gamers as rural smartphone penetration deepens.
Platform:
Access modality shapes customer acquisition economics, with native applications commanding higher development overhead against lower-friction web and social alternatives.
- Mobile Apps:Dominant access channel capturing tier-1 city professionals and mass-market smartphone owners through push-notification engagement and biometric payment flows.
- Websites:Browser-based participation serving desktop-professional users and regulatory-conscious segments avoiding app store dependency.
- Social Media:WhatsApp and Instagram-embedded mini-games reduce download friction for first-time user acquisition in data-conscious rural Tamil Nadu districts.
- Desktop Applications:Legacy access mode retaining professional player segments requiring multi-screen statistical monitoring during live match windows.
Platform concentration: Mobile Apps. Steepest expansion trajectory: Social Media as influencer-embedded content displaces performance marketing.
Sport Type:
Athlete data availability and broadcast rights density determine scoring engine complexity and real-time pipeline costs across each discipline.
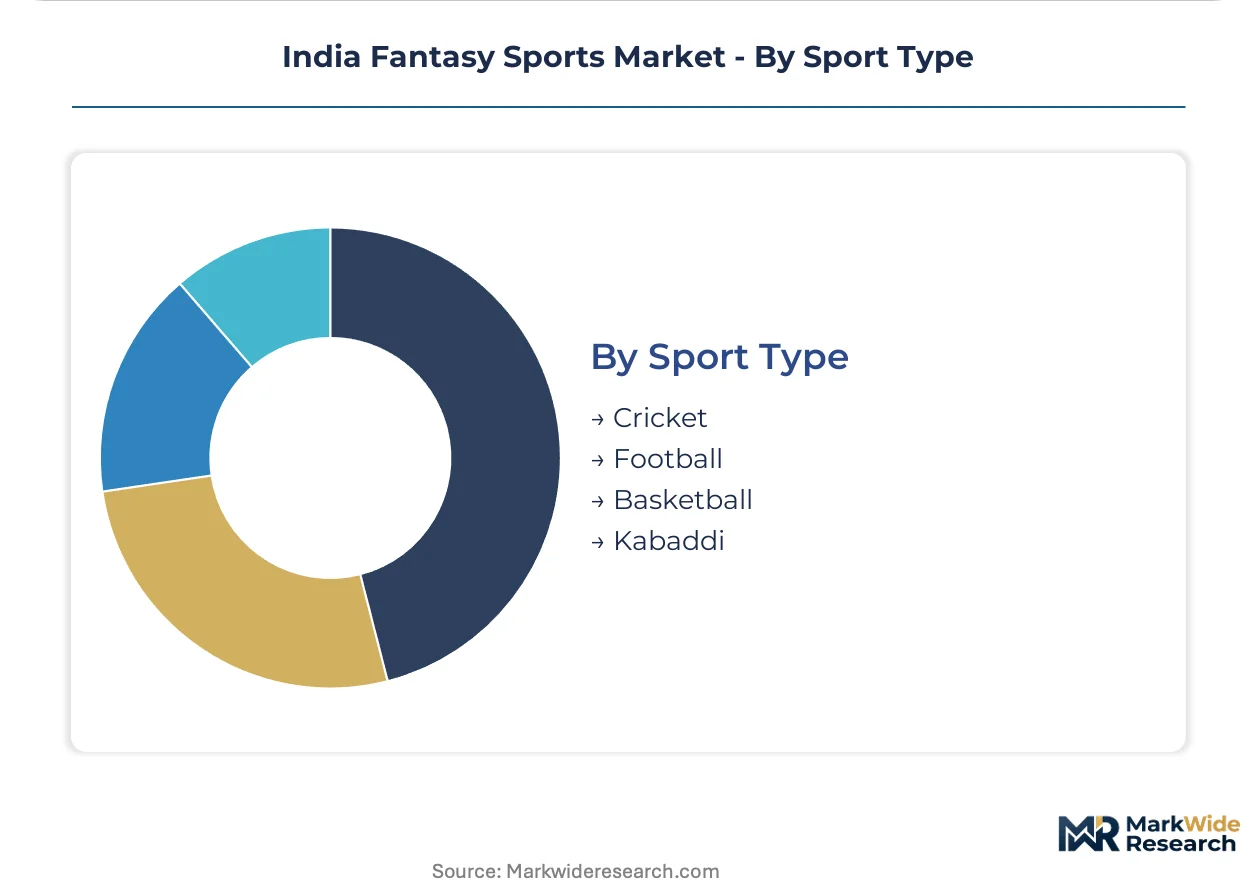
- Cricket:IPL and international calendar density sustains year-round engagement with established data provider partnerships and granular player statistics infrastructure.
- Football:European league following in Kerala and West Bengal creates seasonal demand spikes requiring cross-border data feed integration.
- Basketball:NBA-focused participation emerging among urban youth segments with overnight contest resolution aligned to North American broadcast schedules.
- Kabaddi:Pro Kabaddi League format adoption leverages domestic broadcast rights and regional language commentary penetration in Maharashtra and Telangana.
Revenue concentration: Cricket. Gaining share fastest: Kabaddi as indigenous sport positioning differentiates against cricket-saturated competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fantasy sports in India clusters around cricket-devoted populations in western and southern states, with platform economics shaped by state-level gambling interpretations and Jio-enabled rural data penetration converting first-time smartphone owners into participants.
Maharashtra
Mumbai's professional player clusters drive high-frequency daily fantasy participation through IPL match days and international fixtures. The state's distinct legal interpretation of skill-versus-chance distinctions creates compliance complexity for operators navigating Mumbai's contested market. Pune's tech corridor anchors algorithm-assisted professional segments deploying predictive models across multiple platform accounts.
Karnataka
Bangalore's smartphone-first casual gamers concentrate demand for compressed contest formats seeking immediate gratification. The state's gambling prohibition framework forces platform architecture redesigns around escrow mechanics and user verification systems. The city's influencer-embedded content ecosystem displaces traditional digital ad spend through regional-language creator partnerships.
Telangana
Hyderabad's cricket-calendar followers sustain year-round engagement through domestic league participation and Pro Kabaddi League format adoption. The state's regulatory environment concentrates deposit flows through RBI-mandated licensed payment aggregators, creating single-point vulnerabilities in user fund management. Platform marketing budgets here concentrate on WhatsApp group invitations and Instagram story shares for peer-network-driven acquisition.
Gujarat
Ahmedabad's underpenetrated cricket-devoted populations offer expansion opportunity for season-long league formats that anchor retention and reduce customer acquisition costs. The state's PLI scheme beneficiaries subsidize domestic data center buildouts, reducing latency for real-time scoring engines. Surat's mass-market smartphone owners respond to celebrity-endorsed user acquisition campaigns targeting low-friction entertainment seekers.
Tamil Nadu
Chennai's data-conscious rural districts emerge as testing grounds for social media-embedded mini-games that bypass app store friction. The state's BIS data localization mandates require domestic server infrastructure, creating competitive moats for compliant operators. Coimbatore's sports enthusiasts demonstrate high platform loyalty and season-long engagement persistence tracking international cricket calendars.
India Fantasy Sports Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue social media-embedded acquisition channels and tier-2 city expansion. The vendor base clusters around cricket-first portfolios, multi-sport engagement platforms, and celebrity-endorsed mass-market challengers. Three archetypes dominate: data-intensive scoring engine operators, influencer-driven user acquisition specialists, and compliance-heavy escrow infrastructure builders. Competitive moves concentrate on M&A for regional player bases and strategic partnerships with sports data providers for real-time pipeline access.
Within the cricket-first tier, Dream Sports Group and My11Circle exemplify divergent positioning archetypes. Dream Sports Group anchors premium pay-to-play contest economics through its established data infrastructure and professional player retention systems. My11Circle occupies the mass-market acquisition vector, leveraging celebrity endorsement patterns visible in its naming convention to reach smartphone-first casual gamers. Mobile Premier League represents the multi-sport diversification archetype, sustaining engagement across kabaddi and football formats beyond cricket saturation.
| Leading Market Players |
|---|
| Dream Sports Group |
| Mobile Premier League |
| 11 Wickets.com |
| BalleBaazi |
| MyTeam11 |
| My11Circle |
| Games24x7 |
| Vision11 |
| Paytm First Games |
| Others |
Pricing and Supply Chain Analysis
Captive integration into domestic data center infrastructure anchors both supply positioning and pricing power for tier-1 operators. The PLI scheme subsidization of server buildouts creates cost advantages that translate into competitive deposit structures, while RBI-mandated escrow mechanics force smaller platforms toward third-party infrastructure dependencies that compress their margin flexibility.
Pricing Analysis
Volume concentration in daily fantasy formats splits from margin capture in season-long leagues. Three-tier pricing structure across premium, standard, and economy levels segments users by engagement frequency and deposit size. Price differentiation rests on KYC verification tier and withdrawal velocity guarantees. Pricing pressure stems from GST Council's 28% levy on full-face-value deposits, forcing cost absorption that hits mass-market casual gamers hardest while professional players in Mumbai and Bangalore demonstrate lowest price sensitivity.
Supply Chain Analysis
Certification gating through BIS data localization mandates and MeitY's draft online gaming rules restricts infrastructure choices to domestic server deployments. Supply draws from India-specific data center operators, licensed payment aggregators, and sports data providers with broadcast rights partnerships. Raw material dependencies center on real-time match feed APIs, player injury databases, and weather data streams. Single-source vulnerability concentrates in payment aggregator licensing, where RBI escrow mandates create chokepoints. Distribution runs through mobile app stores, direct APK downloads, and social media-embedded mini-games.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-heavy operators capable of absorbing GST-driven margin compression. MeitY's KYC and self-regulatory body registration requirements force sub-scale platforms toward exit or acquisition.
For Market Incumbents: Anchor retention through season-long league formats that reduce customer acquisition costs in Gujarat and Tamil Nadu. Deepen backward integration into proprietary scoring engines to cut real-time data pipeline costs. Defend against influencer-driven challengers by locking exclusive regional-language creator partnerships in Telangana and Karnataka. For New Entrants and Emerging Players: The price-point gap between premium pay-to-play and free-to-play conversion funnels offers white-space entry. Target data-conscious rural districts in Tamil Nadu with WhatsApp-embedded mini-games that bypass app store friction. Pursue Pro Kabaddi League format specialization as the most penetrable sport vertical outside cricket saturation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by tier-1 operators seeking regional user bases and compliant infrastructure. Long-term viability favors platforms with captive data center assets and diversified sport portfolios beyond cricket dependence. Watch judicial rulings on skill-versus-chance classifications across Maharashtra, Karnataka, and Telangana as the inflection signal for licensing timeline predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Buildout | PLI scheme subsidies reduce latency for real-time scoring engines in tier-2 cities. |
| Social Media Mini-Game Launch | WhatsApp and Instagram embedding bypasses app store friction for rural acquisition. |
| Multi-Sport Format Extension | Kabaddi and football diversification reduces cricket-calendar dependency risk. |
| Third-Party KYC Infrastructure Pooling | Shared verification APIs cut compliance costs for sub-scale operators. |
| Regional Creator Partnership Lockups | Exclusive influencer contracts displace performance marketing in tier-2 expansion. |
Research Methodology
Regulatory filings from MeitY, RBI circulars, and GST Council rulings formed the secondary backbone for compliance architecture mapping. Primary interviews with platform CTOs, payment aggregator compliance officers, sports data provider account managers, and state-level gaming commission legal counsel combined with secondary validation. Bottom-up user base estimates across Maharashtra, Karnataka, Telangana, Gujarat, and Tamil Nadu triangulated against top-down market sizing from operator revenue disclosures and deposit volume proxies.
Historical trendline analysis of fantasy sports participation rates, IPL viewership correlations, and Jio-enabled smartphone penetration patterns established baseline growth assumptions. The analytical framework modeled service type, end user sophistication, platform access modality, and sport type dimensions across the projection horizon. CAGRs derived from segment-level growth rate differentials applied to base year estimates, with cricket calendar density and regulatory ruling timelines as key forecast inputs.
Inputs from BIS certification databases and state high court dockets were available through the study window; gaps in pending judicial interpretations of skill-versus-chance distinctions introduce uncertainty bands around licensing timeline assumptions. Forecasts reflect documented assumptions on GST rate stability and PLI scheme continuity. A model refresh is warranted upon material change in MeitY's final online gaming rules or adverse judicial classification of daily fantasy formats.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Player Tracking System Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Daily Fantasy Sports Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Youth Sports Software Market
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
Fantasy Sports Market