
 Global Hotel Reservation Software Market | 2026-2036
Global Hotel Reservation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hotel Reservation Software Market Foresight
The independent hotel segment is broadening its share of reservation software spending as smaller properties abandon legacy systems. Amadeus leverages its global distribution network to sustain dominance across enterprise chains. Cloudbeds anchors its position through specialized tools for boutique operators. SiteMinder competes aggressively on channel connectivity breadth.
Hotel reservation software encompasses cloud-based, on-premise, hybrid, and SaaS platforms that centralize inventory, pricing, and booking workflows through real-time synchronization with online travel agencies and direct channels. The primary commercial purpose is maximizing occupancy yield while minimizing manual intervention across fragmented distribution points. Cloud-based deployment leads the product type mix due to lower capital requirements and faster implementation cycles. Channel management applications capture disproportionate margin pools as hotels prioritize rate parity enforcement across Expedia, Booking.com, and direct web portals. API integration deployment is accelerating fastest where property groups demand bespoke connectivity to loyalty programs and ancillary service vendors.
GDPR in Europe, PCI-DSS globally, and state-level data privacy laws in California shape product development roadmaps by mandating encrypted payment tokenization and guest data localization. The EU AI Act introduces emerging compliance obligations for automated pricing algorithms deployed by major platforms. Stakeholders must monitor regulatory divergence between jurisdictions to avoid architecture fragmentation that inflates engineering costs.
Market Dynamics
Cloud migration is compressing implementation timelines from months to weeks, forcing vendors to rearchitect deployment models around API-first connectivity rather than monolithic legacy stacks.
Growth Catalysts
- PCI-DSS Mandates:Payment card security standards are compelling independent properties to abandon spreadsheet-based booking systems for certified platforms that encrypt tokenized transactions.
- OTA Synchronization:Real-time inventory parity across Booking.com, Expedia, and direct channels prevents overbooking penalties and rate arbitrage losses.
- Japan Infrastructure Modernization:Aging on-premise property management systems in Tokyo and Osaka hotel clusters are reaching end-of-life, triggering replacement cycles.
Market Restraints
- GDPR Compliance Costs:Guest data localization requirements in Europe force redundant server architecture that inflates operational overhead for mid-size operators.
- Input Concentration:Cloud infrastructure dependency on hyperscale providers in the United States creates single-point-of-failure risk for global platform uptime.
- Technical Debt:Hybrid deployments bridging legacy on-premise hardware with cloud interfaces introduce synchronization latency that degrades real-time availability accuracy.
Strategic Opportunities
- India Boutique Expansion:Underpenetrated tier-two cities like Jaipur and Kochi present whitespace for mobile-first reservation tools targeting owner-operated properties.
- EU AI Act Positioning:Automated pricing algorithm transparency mandates create competitive opening for vendors offering explainable rate-optimization engines.
- Voice-API Convergence:Integration of conversational AI with property management interfaces enables hands-free front-desk operations for limited-service hotels.
Industry Challenges
- Integration Complexity:Middleware development for 1990s-era property management systems consumes engineering resources that could advance core platform features.
- Cybersecurity Talent Scarcity:Shortage of hospitality-focused security engineers delays penetration testing and vulnerability patching cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hotel Reservation Software Market |
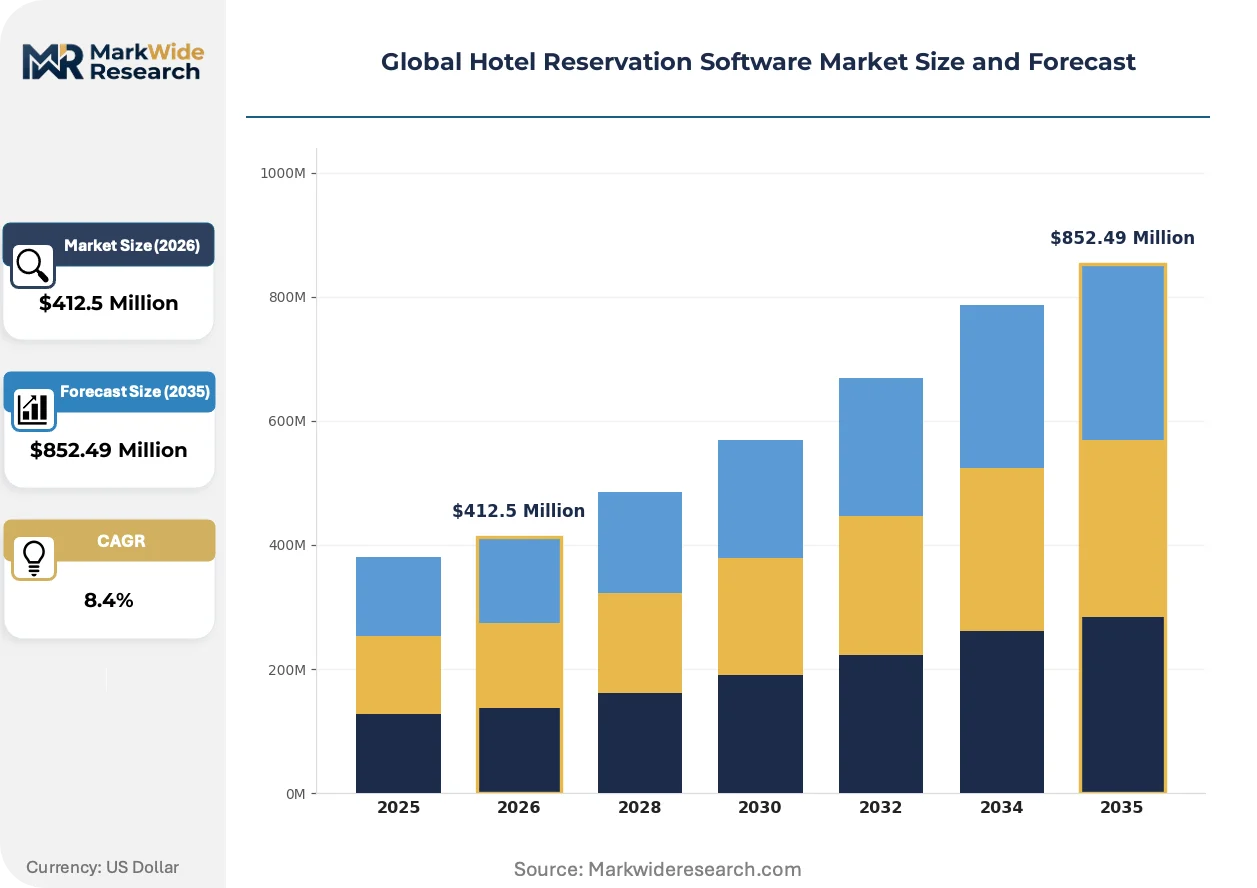
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, SaaS Deployment: Mobile, Desktop, Web Portal, API Integration Application: Guest Management, Channel Management, Booking Engine, Payment Processing, Analytics End User: Independent Hotels, Boutique Inns, Serviced Apartments, Resort Chains |
| Companies Covered | Amadeus, Sabre SynXis, Cloudbeds, Oracle Hospitality, Hotelogix, Mews, eZee Technosys, SiteMinder, ResNexus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hotel Reservation Software Market Shifts & Advancements
Native API architecture is overtaking plugin-based connectivity as the dominant integration paradigm, compressing deployment friction and enabling modular service stacking.
Serverless computing is overtaking provisioned cloud instances for reservation workload processing. Mid-scale hotel groups in Germany are adopting function-as-a-service models to eliminate idle capacity costs during low-occupancy periods. This shift is overtaking traditional three-year infrastructure planning cycles with consumption-based scaling that aligns technology spend directly to booking volume volatility.
REACH chemical substance restrictions in Europe are mandating supply chain disclosure for hardware components in on-premise server installations. Hotel operators deploying physical property management infrastructure must now certify compliance with restricted substance lists for circuit boards and cooling systems. German engineering teams are responding by pre-qualifying component vendors against SVHC candidate lists before procurement authorization.
Direct booking preference is displacing OTA-dependent acquisition strategies among lifestyle hotel brands. Properties in California are investing in loyalty program integration and rate-parity enforcement tools to reduce commission exposure. This behavioral pivot is most visible in urban leisure destinations where brand recognition reduces reliance on third-party discovery platforms.
Global Hotel Reservation Software Market Segmentation
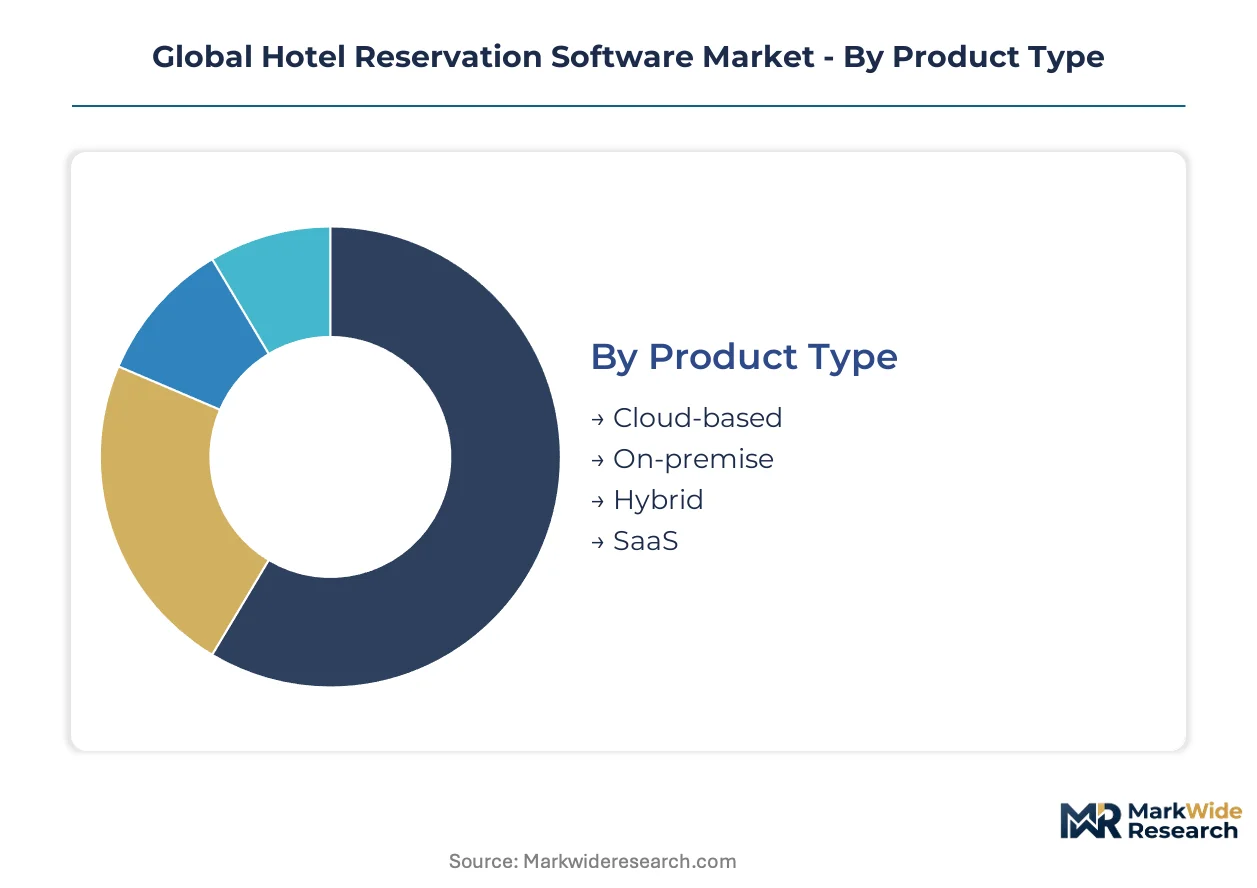
Hotel reservation software segments reflect divergent infrastructure maturity across property types. Technology choices determine capital intensity, compliance exposure, and integration complexity for operators scaling distribution across fragmented booking channels.
Product Type:
Architecture decisions hinge on data sovereignty requirements and legacy system entanglement.
- Cloud-based:Multi-tenant infrastructure eliminates server procurement and shifts expenditure to operational budgets. German boutique chains favor this model to satisfy GDPR data localization through EU-region hosting without capital deployment.
- SaaS:Subscription pricing aligns technology spend with occupancy volatility, attracting independent properties in Japan modernizing from spreadsheet-based systems. Vendors bundle channel management and payment tokenization into tiered service levels.
- Hybrid:Bridging on-premise property management cores with cloud distribution layers preserves legacy investments while enabling OTA connectivity. Synchronization latency between environments degrades real-time availability accuracy.
- On-premise:Physical server installations persist in Tokyo and Osaka clusters where aging JIS-compliant hardware reaches end-of-life. REACH chemical substance restrictions now mandate supply chain disclosure for circuit board components.
Cloud-based leads on scale; SaaS leads on momentum.
Deployment:
Interface modality shapes staff training costs and guest self-service penetration.
- API Integration:Native connectivity enables bespoke loyalty program linkages and ancillary service orchestration. Resort chains in California deploy this layer to enforce rate parity across direct and third-party channels without manual intervention.
- Web Portal:Browser-based dashboards dominate mid-scale operator adoption due to minimal installation friction. Properties in Jaipur and Kochi prioritize mobile-responsive interfaces over dedicated applications.
- Mobile:Smartphone-native interfaces support front-desk mobility and owner-operator oversight for limited-service properties. Battery optimization and offline synchronization remain engineering priorities.
- Desktop:Thick-client installations concentrate in legacy-dependent environments where local processing resilience outweighs cloud dependency risks.
Web Portal captures volume concentration; API Integration climbs the fastest.
Application:
Functional modules compete for budget priority based on commission pressure and operational pain points.
- Channel Management:Real-time inventory parity enforcement prevents overbooking penalties and rate arbitrage losses. This module captures disproportionate margin pools as properties prioritize Expedia and Booking.com synchronization.
- Payment Processing:PCI-DSS certified tokenization replaces spreadsheet-based card handling. Independent hotels abandon manual entry to eliminate breach liability and qualify for processor rate tiers.
- Booking Engine:Direct reservation capture reduces OTA commission exposure for lifestyle brands with established recognition. Conversion optimization focuses on mobile checkout flow compression.
- Guest Management:Profile centralization supports personalized service delivery and marketing automation. GDPR compliance mandates encrypted storage and deletion workflow documentation.
- Analytics:Occupancy forecasting and rate optimization algorithms face emerging EU AI Act transparency requirements for automated pricing decisions.
Channel Management leads on scale; Payment Processing leads on momentum.
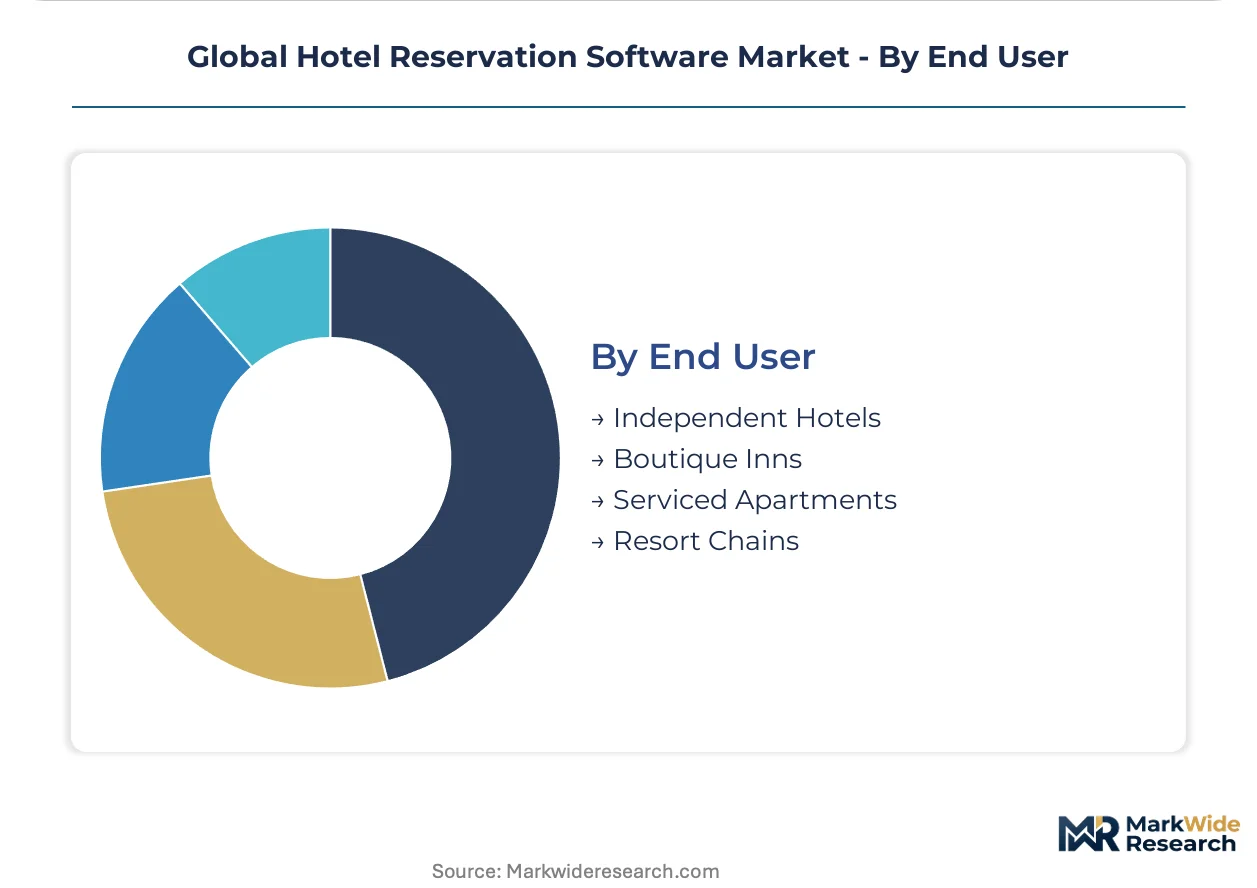
End User:
Property scale and ownership structure dictate integration complexity and vendor selection criteria.
- Independent Hotels:Owner-operated properties prioritize rapid deployment and minimal technical staffing. Cloud-based SaaS bundles displace legacy systems as PCI-DSS deadlines approach.
- Boutique Inns:Design-focused properties demand customization flexibility for brand differentiation. Specialized tools support direct booking preference and loyalty program integration.
- Resort Chains:Multi-property groups require enterprise-grade uptime guarantees and centralized revenue management. API-first architecture enables standardization across heterogeneous local infrastructures.
- Serviced Apartments:Extended-stay operators need extended booking windows and corporate billing workflows. Integration with expense management platforms differentiates vendor suitability.
Independent Hotels lead on scale; Boutique Inns lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment strategies as GDPR compliance costs in Europe push mid-size operators toward cloud-hosted alternatives with EU-region data residency. This compliance-cost differential concentrates platform development investment in jurisdictions offering streamlined certification pathways while preserving data sovereignty guarantees.
United States
Independent hotel chains in California and Florida are accelerating legacy system replacement as PCI-DSS enforcement deadlines approach. The FTC monitors payment security compliance while state-level privacy laws in California impose additional data handling requirements. Phoenix and Austin hotel clusters are driving demand for API-first reservation platforms that integrate with loyalty programs.
Germany
Boutique hotel operators in Berlin and Munich favor SaaS deployments to satisfy GDPR localization mandates without capital-intensive server procurement. ECHA chemical substance tracking through REACH affects hardware procurement for remaining on-premise installations. The Bavarian hospitality corridor is standardizing on cloud-native channel management to enforce rate parity across Booking.com and direct channels.
Japan
Aging JIS-compliant property management systems in Tokyo and Osaka are reaching end-of-life, triggering replacement demand for certified cloud alternatives. METI guidelines encourage digital infrastructure modernization across small and medium enterprises. The Kansai region's resort clusters are adopting hybrid deployments to bridge legacy hardware with cloud distribution layers.
India
Owner-operated properties in Jaipur and Kochi represent underpenetrated whitespace for mobile-first reservation tools. BIS standards for data security are emerging as baseline procurement criteria for tier-two city operators. The Maharashtra hospitality corridor around Mumbai is consolidating on web-portal interfaces that minimize technical staffing requirements.
United Kingdom
London's lifestyle hotel brands are investing in direct booking engines to reduce OTA commission exposure. The Information Commissioner's Office enforces GDPR compliance across guest data management workflows. Edinburgh and Manchester boutique clusters are prioritizing payment tokenization modules that qualify for processor rate tier improvements.
Global Hotel Reservation Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade platform vendors commanding premium positioning while modular tool providers capture the independent property tier. The vendor base concentrates around three strategic archetypes: global distribution network operators, boutique-specialized SaaS providers, and channel connectivity aggregators. M&A activity targets API-first technology assets, while geographic expansion focuses on tier-two city penetration in underpenetrated Asian markets.
Among global distribution network operators, Amadeus and Sabre SynXis exemplify the enterprise-chain archetype through their established airline-hospitality convergence platforms. Cloudbeds and SiteMinder occupy positions within the boutique-specialized tier, with the former representing the integrated-tool approach and the latter anchoring the channel-connectivity-focused segment. These four names illustrate the competitive spectrum from legacy enterprise systems to modular cloud-native alternatives.
| Leading Market Players |
|---|
| Amadeus |
| Sabre SynXis |
| Cloudbeds |
| Oracle Hospitality |
| Hotelogix |
| Mews |
| eZee Technosys |
| SiteMinder |
| ResNexus |
| Others |
Supply & Pricing Matrix
Cloud-native engineering talent concentration in Berlin and Bangalore compresses labor-cost differentials between premium enterprise platforms and mid-market SaaS tiers, widening pricing spreads as vendors arbitrage regional development costs against PCI-DSS certification premiums.
Pricing Analysis
Direct-to-hotel SaaS subscriptions bypass distributor markups entirely, compressing channel-margin layers that historically absorbed 15-25 points in legacy on-premise deployments. Three-tier pricing structure across enterprise, professional, and basic levels stratifies by API call volume and channel connectivity breadth, with PCI-DSS certification tier acting as the primary quality-grade separator. Pricing pressure stems from open-source booking engine alternatives commoditizing entry-level functionality. Independent owner-operators exhibit highest price sensitivity, while resort chains prioritize uptime guarantees over per-seat cost.
Supply Chain Analysis
GDPR and PCI-DSS qualification gating restricts viable hosting infrastructure to certified hyperscale providers in Ireland, Germany, and Virginia, concentrating compute supply within regulatory-compliant zones. Software development draws from specialized hospitality-technology labor pools in India, Poland, and Portugal, with API engineering expertise commanding scarcity premiums. Single-source vulnerability concentrates in payment processor tokenization services, where certified vendor lists remain narrow. Distribution runs through direct vendor sales organizations and hospitality-technology consultants serving property clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where direct-booking preference among lifestyle brands elevates rate-parity enforcement and loyalty integration to premium specifications worth pricing premiums.
For Market Incumbents: Anchor enterprise positioning through exclusive METI certification pathways in Japan, defending against modular disruptors by deepening API-first architecture investments that hybrid deployments cannot replicate. Channel control through direct property relationships remains the critical lever against connectivity-aggregator encroachment. For New Entrants and Emerging Players: EU AI Act transparency mandates in Germany open a window for explainable pricing-algorithm specialists to capture boutique-inn demand abandoned by opaque legacy optimization engines. Tier-two Indian cities represent the most penetrable geography, with mobile-first deployment as the essential go-to-market angle against web-portal incumbents. For Investors and Strategic Acquirers: Private-equity firms with hospitality-technology portfolios are the most active acquirer in this space, targeting API-first assets with modular service-stacking capabilities. Long-term viability hinges on cloud-native architecture displacement of hybrid technical debt. The signal to watch is acceleration in serverless-computing adoption among German mid-scale operators as inflection indicator for consumption-model preference shift.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Native connectivity architectures displace plugin-based middleware across California resort chains. |
| PCI-DSS Certification Investment | Payment security credentials qualify vendors for processor rate tiers that independent properties demand. |
| Geographic Expansion to Tier-Two Cities | Jaipur and Kochi owner-operators represent whitespace for mobile-first reservation tools. |
| Strategic Partnership with Hyperscale Hosts | EU-region data residency partnerships satisfy GDPR localization without capital-intensive server procurement. |
| Acquisition of Channel Connectivity Specialist | OTA synchronization breadth remains the decisive procurement criterion for boutique hotel operators. |
Research Methodology
Direct dialogue with hotel technology officers, revenue management directors, channel partnership leads, and property management system integration specialists combined with secondary validation from SEC filings, hospitality-technology trade publications, and METI digitalization reports. Bottom-up property-count modeling and top-down vendor revenue triangulation anchored segmentation splits across deployment models and end-user tiers.
Market sizing outputs reflect segment-level extrapolation across cloud-based, SaaS, hybrid, and on-premise architectures, with growth trajectories derived from replacement-cycle timing in Japan and compliance-deadline clustering in Europe. Forecast inputs incorporated OTA commission-rate pressure, GDPR enforcement intensity, and API standardization velocity as industry-specific demand shapers.
Revisions become necessary when regulatory divergence between jurisdictions accelerates architecture fragmentation costs, or when hyperscale provider consolidation eliminates multi-vendor hosting options. A model refresh is warranted upon material change in EU AI Act implementation timelines affecting automated pricing algorithm deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Travel Management Software Market