
 Airline Reservation Software Market | 2026-2036
Airline Reservation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Airline Reservation Software Market Outlook
India is reshaping competitive dynamics in airline reservation software as domestic carriers invest in next-generation passenger service systems. Amadeus IT Group leverages its global distribution footprint to anchor premium carrier relationships across multiple continents. Sabre competes through specialized retailing and merchandising modules that extend beyond basic inventory control. IBS Software dominates the low-cost carrier segment with purpose-built platforms for high-frequency scheduling environments.
Airline reservation software comprises integrated systems that manage seat inventory, fare construction, booking workflows, and passenger data across global distribution networks, typically operating through real-time messaging protocols like AIRIMP or XML-based NDC standards. The primary commercial purpose centers on maximizing yield per available seat mile while maintaining interoperability with hundreds of partner airlines and travel intermediaries. Cloud-based deployment now leads product type adoption as carriers seek elastic capacity during seasonal demand spikes, while SaaS models capture the fastest growth by converting capital expenditure into operational budgets. Booking management functionality retains the deepest margin pools due to its direct linkage to ancillary revenue streams including seat selection, baggage fees, and loyalty program integration.
India's Ministry of Civil Aviation and the Directorate General of Civil Aviation shape domestic compliance requirements for passenger data handling and fare transparency, while IATA's NDC standards create cross-border technical obligations for system interoperability. The EU's GDPR and the US Department of Transportation's consumer protection rules impose additional data governance and refund policy constraints on reservation platforms serving those markets. Stakeholders must monitor how biometric identity verification mandates from aviation security agencies will force architectural changes to passenger data flows and check-in system integration.
Market Dynamics
IATA's New Distribution Capability standards are forcing carriers to dismantle decades-old EDIFACT messaging infrastructure and rebuild reservation architectures around XML-based retailing protocols. This technical mandate is compressing upgrade timelines and redistributing competitive advantage toward vendors with modular, API-first platforms.
Growth Catalysts
- NDC Mandate Compliance:IATA's certification requirements for Level 3 and Level 4 capability are compelling full-service carriers to replace legacy passenger service systems with retailing-native platforms that support dynamic pricing and personalized offers.
- Cloud Migration:Low-cost carriers across Southeast Asia are deploying elastic infrastructure to manage volatile seat inventory during peak travel seasons without stranded capital in fixed data center capacity.
- Biometric Integration:Aviation security agencies in the United States, Singapore, and the United Arab Emirates are piloting facial recognition at check-in, driving demand for reservation systems with native identity verification APIs.
Market Restraints
- Legacy System Entrenchment:Major network carriers operate passenger service systems with thirty-plus years of customized business rules, creating switching costs that exceed the capital cost of new software acquisition.
- Talent Scarcity:Expertise in AIRIMP messaging protocols and proprietary mainframe environments concentrates among a shrinking cohort of specialists approaching retirement age.
- Interoperability Complexity:Each bilateral codeshare agreement requires bespoke mapping between distinct reservation architectures, multiplying integration overhead as airline alliances expand.
Strategic Opportunities
- Ancillary Revenue Optimization:Next-generation merchandising engines enable real-time bundling of seats, baggage, and loyalty perks across direct and indirect channels, capturing margin pools that legacy systems cannot access.
- India Market Expansion:IndiGo and Air India are modernizing core platforms simultaneously, creating a concentrated demand window for vendors capable of handling high-frequency domestic scheduling at scale.
- Intermodal Retailing:Rail-air integration mandates in the European Union are creating demand for reservation systems that can inventory and ticket multimodal journeys through single transaction workflows.
Industry Challenges
- Data Sovereignty Fragmentation:Passenger name record regulations vary across India, the European Union, and the United States, forcing vendors to maintain jurisdiction-specific data residency architectures.
- Real-Time Inventory Synchronization:Seat maps must reconcile across global distribution systems, airline direct channels, and partner carrier platforms within sub-second latency windows to prevent double-booking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline Reservation Software Market |
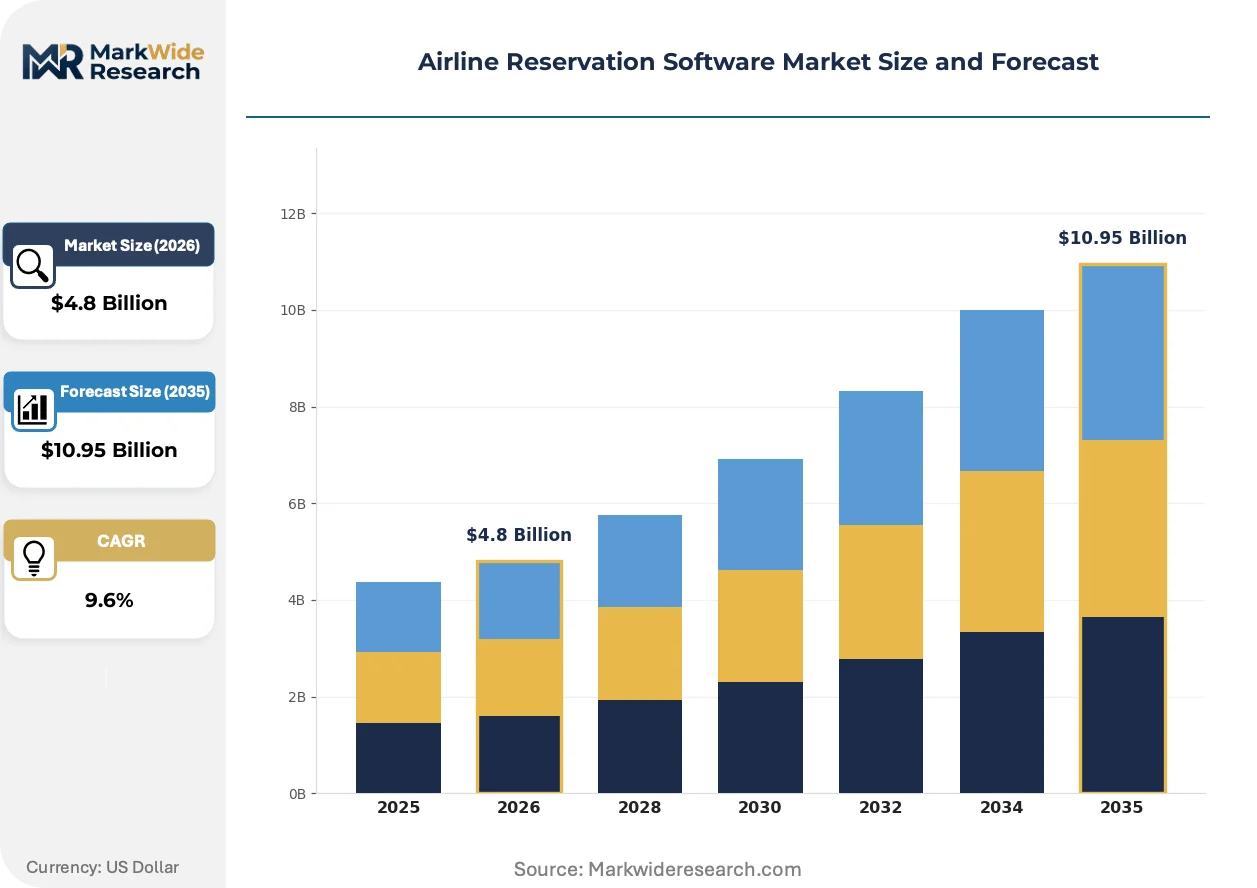
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile Application End User: Airlines, Travel Agencies, Online Booking Platforms, Corporate Travel Managers Functionality: Inventory Management, Booking Management, Payment Processing, Customer Relationship Management Deployment Model: Public Cloud, Private Cloud, SaaS, Traditional Software |
| Companies Covered | Amadeus IT Group, Sabre, Navitaire, Travelport Worldwide, IBS Software, Datalex, SITA, Farelogix, Radixx International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline Reservation Software Market Strategic Shifts
Artificial intelligence is embedding into core reservation workflows, compressing the gap between inventory availability and pricing optimization while shifting competitive advantage toward carriers with superior data infrastructure. These developments are restructuring how seats are sold, regulated, and consumed.
Machine learning revenue management systems are digitizing demand forecasting by ingesting search behavior, competitive pricing, and macroeconomic signals to adjust fares in fifteen-minute intervals. Low-cost carriers in Southeast Asia are deploying these tools fastest, eroding the yield advantage that network carriers historically held through superior market data. The technology is digitizing pricing authority, moving it from human analysts to algorithmic systems that respond to demand fluctuations before competitors can manual adjust.
The European Union's Digital Markets Act is imposing interoperability obligations on dominant global distribution systems, requiring them to expose reservation data through standardized APIs to competing retail platforms. This regulatory intervention is fragmenting distribution control and enabling new entrant travel sellers to access inventory previously gated by bilateral agreements. Full-service carriers operating in European markets are responding by accelerating direct channel investments to reduce dependency on intermediary platforms.
Corporate travel procurement is consolidating around managed travel platforms that aggregate booking, expense, and duty-of-care functions into unified workflows. Multinational enterprises in Germany and the United Kingdom are mandating these integrated tools, displacing traditional travel management company relationships. This buyer-side consolidation is visible most acutely in financial services and professional services verticals, where procurement teams are extracting volume commitments in exchange for exclusive platform adoption.
Airline Reservation Software Market Segmentation
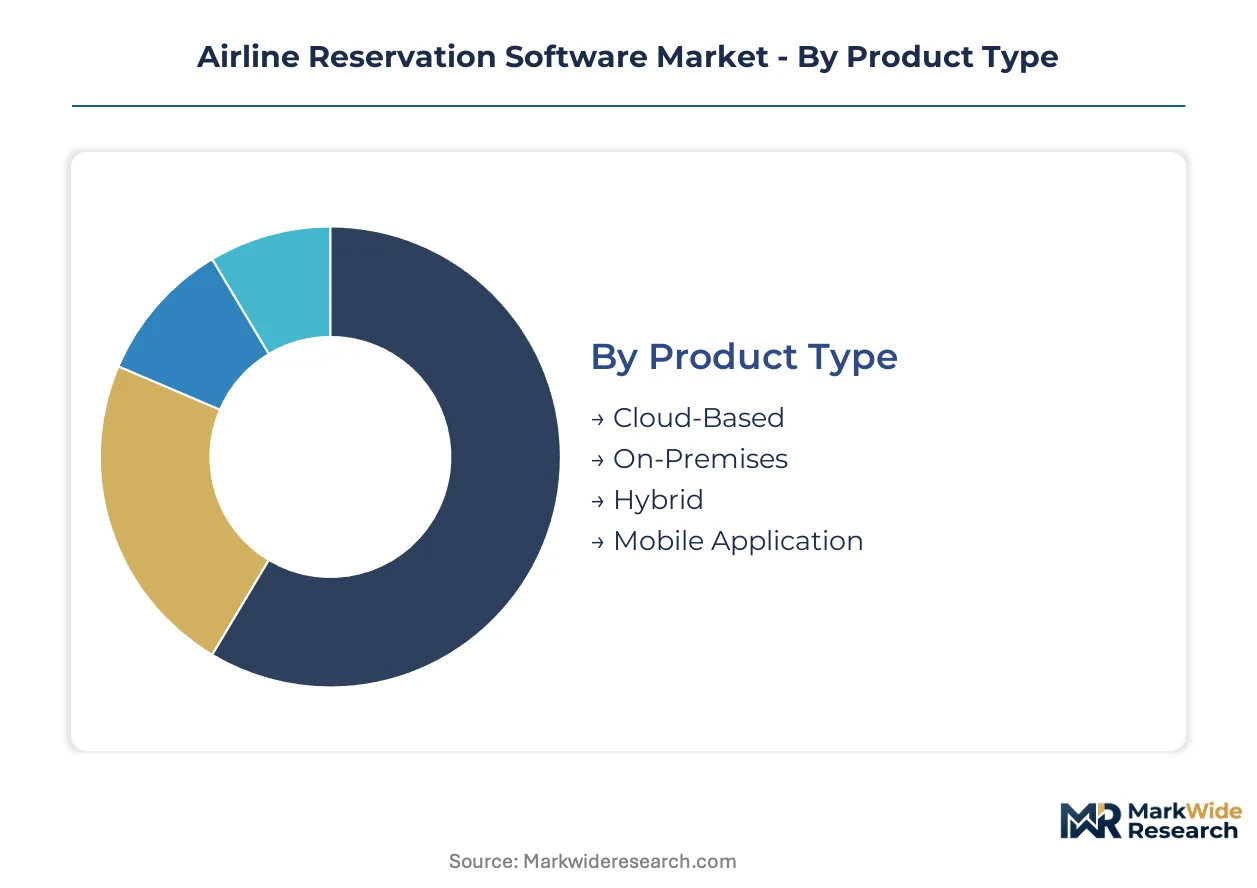
Segmentation in airline reservation software reveals how deployment architecture, user workflows, and commercial models intersect. Vendors configure platform modules differently for low-cost carriers managing high-frequency domestic schedules versus global network carriers operating complex codeshare agreements.
Product Type:
Deployment architecture spans the spectrum from elastic cloud infrastructure to captive data center installations, with each configuration matching specific operational risk tolerances and capital constraints.
- Cloud-Based:Multi-tenant architectures deliver elastic compute capacity during seasonal demand spikes. Southeast Asian low-cost carriers favor this model to avoid stranded capital in fixed infrastructure during off-peak periods.
- On-Premises:Dedicated hardware installations in carrier-controlled facilities support customized business rules and data residency mandates. Full-service network carriers in Germany and Japan maintain these deployments to satisfy national aviation security protocols.
- Hybrid:Split architectures reserve sensitive passenger data on local servers while pushing transactional workloads to public cloud. This configuration addresses India's data localization requirements for passenger name records.
- Mobile Application:Native iOS and Android interfaces for crew scheduling, disruption management, and passenger self-service. Ground staff at Dubai International Airport use these tools for real-time gate reassignments.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
End User:
Customer archetypes range from asset-heavy carriers to intermediary platforms, each extracting distinct value from reservation infrastructure.
- Airlines:Core operators of passenger service systems requiring inventory control, departure control, and loyalty integration. IndiGo and Air India are simultaneously modernizing these platforms, creating concentrated demand in the Indian market.
- Travel Agencies:Intermediary access to global distribution systems and NDC-enabled direct connect. Traditional agencies in France face margin compression as corporate procurement shifts to managed travel platforms.
- Online Booking Platforms:Aggregator engines consuming multiple content sources through API integrations. These platforms in the United Kingdom must now comply with EU Digital Markets Act interoperability mandates.
- Corporate Travel Managers:Enterprise procurement functions consolidating booking, expense, and duty-of-care into unified workflows. Financial services firms in Germany mandate these integrated tools exclusively.
Procurement consolidation is displacing traditional agency relationships fastest among corporate travel managers.
Functionality:
Core modules map to distinct margin pools, with direct booking workflows capturing ancillary revenue streams that inventory control alone cannot access.
- Inventory Management:Real-time seat map synchronization across global distribution systems, direct channels, and partner platforms. Sub-second latency requirements prevent double-booking on high-demand routes.
- Booking Management:End-to-end reservation workflows encompassing seat selection, baggage fees, and loyalty redemption. This module retains the deepest margin pools through ancillary revenue integration.
- Payment Processing:Multi-currency transaction handling with fraud detection and regulatory compliance. India's RBI mandates specific data handling protocols for cross-border passenger payments.
- Customer Relationship Management:Unified passenger profiles spanning booking history, preferences, and service recovery. GDPR constraints in the European Union limit data retention periods for these systems.
Booking Management commands premium positioning; Inventory Management faces commoditization pressure from standardized NDC protocols.
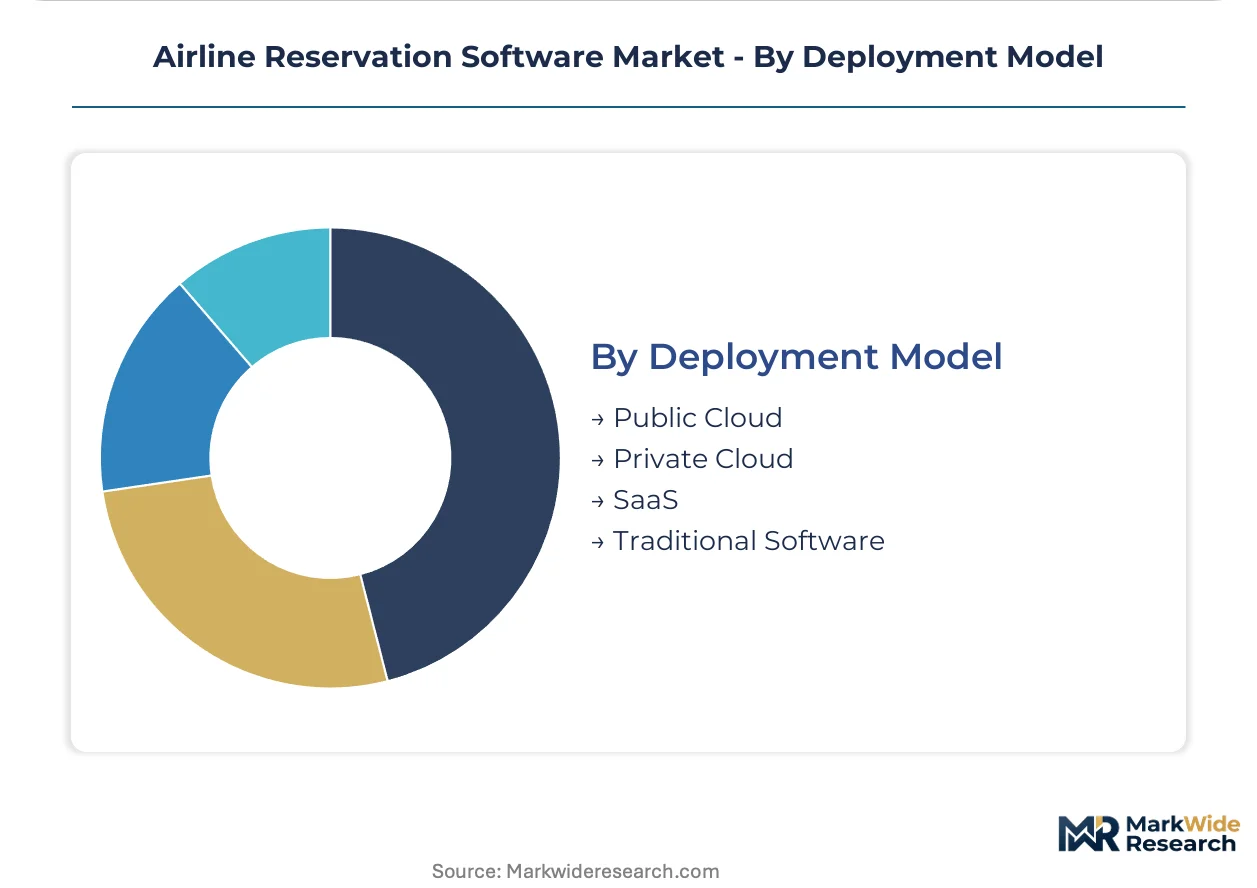
Deployment Model:
Commercial structures range from capital-intensive perpetual licenses to operational expenditure models, with SaaS conversion accelerating among budget-constrained carriers.
- Public Cloud:Shared infrastructure with metered consumption pricing. Southeast Asian carriers deploy this model to match infrastructure costs to volatile load factors.
- Private Cloud:Single-tenant environments with dedicated resource pools. UAE-based carriers favor this configuration for biometric identity verification workloads requiring isolated processing.
- SaaS:Subscription-based access to reservation platforms with vendor-managed maintenance. This model climbs the fastest by converting capital expenditure to operational budgets for low-cost carriers.
- Traditional Software:Perpetual licenses with annual maintenance fees and on-site customization. Legacy entrenchment sustains this model among network carriers with decades of customized business rules.
SaaS is gaining share fastest among new platform adoptions; Traditional Software retains largest installed base through switching cost barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Civil Aviation anchors the dominant geography through simultaneous modernization mandates at IndiGo and Air India, compressing procurement timelines for next-generation passenger service systems.
United States
Network carriers operate thirty-year-old mainframe environments with customized business rules, creating switching costs that exceed new software acquisition capital. The FAA mandates biometric identity verification pilots at major hubs, forcing architectural changes to passenger data flows. Atlanta and Dallas-Fort Worth anchor the largest concentration of legacy system maintenance specialists.
Germany
Lufthansa Group drives demand for retailing-native platforms supporting dynamic pricing across Star Alliance codeshares. The EU Digital Markets Act imposes interoperability obligations on global distribution systems, requiring standardized API exposure. Frankfurt and Munich cluster the deepest concentration of corporate travel procurement consolidation in financial services.
United Arab Emirates
Emirates and Etihad anchor demand for private cloud deployments handling biometric verification workloads with isolated processing. The General Civil Aviation Authority pilots facial recognition integration at Dubai International Airport. Dubai's aviation free zone concentrates the region's largest reservation system implementation teams.
Singapore
Changi Airport Group and low-cost carriers deploy elastic cloud infrastructure to match compute capacity to volatile Southeast Asian load factors. The Civil Aviation Authority of Singapore mandates NDC Level 4 capability for all scheduled operators by 2026. The city-state hosts the regional headquarters for three major reservation software vendors serving ASEAN markets.
Airline Reservation Software Market Competitive Environment
Capability concentration sits with modular API-first vendors; scale advantage sits with legacy platform operators with decades of installed base entrenchment. The market structure is consolidating around two tiers: retailing-native specialists capturing new NDC-mandate deployments, and incumbent global distribution systems defending through bilateral content agreements. Dominant archetypes include cloud-native low-cost carrier specialists, full-service passenger service system integrators, and merchandising engine pure-plays. Competitive moves center on strategic partnerships with biometric identity providers and geographic expansion into India's concentrated demand window.
Within the full-service integrator tier, Amadeus IT Group and Sabre occupy positions defined by global distribution footprint and specialized retailing modules respectively. IBS Software exemplifies the low-cost carrier specialist archetype with purpose-built platforms for high-frequency scheduling environments. These three entities collectively represent the competitive vectors shaping procurement decisions across carrier types and deployment models.
| Leading Market Players |
|---|
| Amadeus IT Group |
| Sabre |
| Navitaire |
| Travelport Worldwide |
| IBS Software |
| Datalex |
| SITA |
| Farelogix |
| Radixx International |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on legacy mainframe expertise concentrates pricing power among incumbent vendors while compressing margins for carriers locked into decades-old customized environments. This structural chokepoint determines both the wide spreads between SaaS-tiered subscription models and captive on-premises installations, and the geographic clustering of implementation teams around aviation hubs in India, Germany, and the United Arab Emirates.
Pricing Analysis
Geographic price spreads run widest between North American network carriers maintaining thirty-year mainframe contracts and Southeast Asian low-cost carriers adopting metered cloud consumption. Three-tier pricing structure across premium, standard, and economy levels separates full-service passenger service system integrators from modular retailing engines and basic inventory control modules. Pricing pressure stems from IATA's NDC mandate compressing upgrade timelines and forcing competitive rebidding. Corporate travel managers exhibit highest price sensitivity as procurement consolidation extracts volume discounts, while Emirates and Etihad in the UAE show lowest sensitivity due to biometric verification requirements mandating isolated private cloud deployments.
Supply Chain Analysis
Upstream feedstock for reservation software draws from specialized labor pools rather than physical commodities, with expertise concentrated in India, Ireland, and the United States where AIRIMP protocol specialists and mainframe engineers cluster around legacy carrier headquarters. Core inputs encompass proprietary messaging protocols, biometric identity verification APIs, and elastic cloud compute capacity from hyperscaler providers. Single-source vulnerability sits with the shrinking cohort of AIRIMP specialists approaching retirement age, creating talent scarcity that threatens implementation timelines. Distribution runs through direct vendor-carrier relationships for large network operators, while SaaS platforms reach low-cost carriers through regional implementation partners anchored in Singapore and Dubai aviation free zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate travel procurement consolidation in Germany and the United Kingdom, where financial services firms mandate exclusive platform adoption and displace traditional agency relationships.
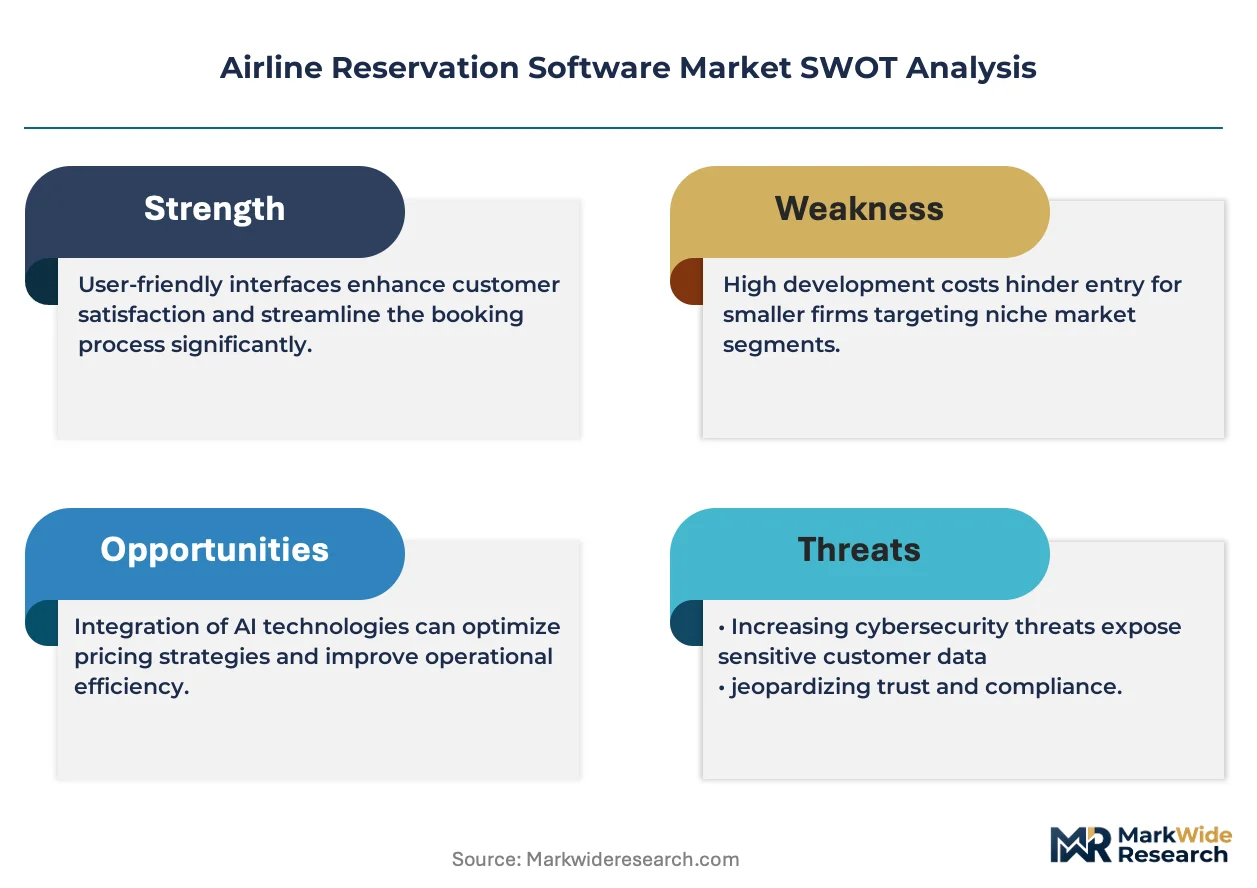
For Market Incumbents: Build switching-cost moats through deep customization of departure control modules that embed carrier-specific business rules irreplaceable by standardized platforms. Defend against modular API-first challengers by accelerating NDC Level 4 certification timelines to capture upgrade budgets before retailing-native specialists penetrate full-service accounts. Anchor capacity addition in India's aviation corridor to service simultaneous IndiGo and Air India modernizations. For New Entrants and Emerging Players: Build out intermodal retailing capabilities addressing EU rail-air integration mandates, where established vendors lack multimodal journey ticketing workflows. Target India's concentrated demand window as the most penetrable geography, where legacy system fatigue at domestic carriers creates procurement openness absent in entrenched North American markets. Lead go-to-market through biometric identity verification partnerships with aviation security agencies piloting facial recognition in Singapore and the UAE. For Investors and Strategic Acquirers: IATA's NDC Level 4 certification deadline reshapes the acquisition landscape by valuing modular retailing engines over legacy inventory control platforms. Long-term viability favors vendors with API-first architectures capable of spanning both full-service and low-cost carrier segments without parallel codebases. Target acquisition archetypes include merchandising engine pure-plays with dynamic pricing algorithms and established low-cost carrier specialist firms. Monitor biometric integration pilot outcomes at Dubai International Airport and Changi as early signals of which reservation architectures will capture next-generation security-mandated upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| NDC Level 4 Certification Acceleration | Captures upgrade budgets from full-service carriers dismantling EDIFACT infrastructure before IATA deadlines. |
| Biometric Identity API Integration | Aligns reservation architectures with FAA and Singapore CA facial recognition mandates at major hubs. |
| India Market Implementation Capacity | Positions vendors to service simultaneous IndiGo and Air India passenger service system modernizations. |
| Intermodal Retailing Platform Development | Addresses EU rail-air integration requirements that legacy systems cannot satisfy through single transaction workflows. |
| SaaS Subscription Model Conversion | Converts capital expenditure to operational budgets for Southeast Asian low-cost carriers managing volatile load factors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with airline CIOs, passenger service system procurement leads, global distribution system integration specialists, and aviation regulatory affairs directors; and secondary validation through IATA NDC certification registries, EU Digital Markets Act compliance disclosures, SEC filings from listed reservation software vendors, and customs data on software services trade flows. Bottom-up triangulation aggregated carrier-specific procurement timelines while top-down cross-checks validated aggregate market sizing against disclosed vendor revenue concentrations.
Forecast inputs encompassed deployment model adoption curves, NDC mandate compliance schedules, biometric integration pilot expansions, and cloud migration patterns across low-cost and full-service carrier segments. Segmentation dimensions modeled included product type, end user archetype, functionality module, and deployment model complexity across the projection horizon. CAGRs derived from carrier modernization cycle analysis and vendor booking backlog trajectories. Industry-specific inputs incorporated IATA certification tier progression rates and data localization requirement enforcement intensity from India's DGCA and RBI.
Practitioners should monitor NDC implementation delays, biometric mandate scope expansions, and mainframe specialist retirement waves for early signals requiring forecast revision. Cross-checking against disclosed vendor implementation backlogs and carrier earnings call commentary on passenger service system spending is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Global Festival Management Software Market