
 Travelport GDS Systems Market | 2026-2036
Travelport GDS Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Travelport GDS Systems Market Analytics
Market Context
Airline distribution channels is fragmenting as carriers deploy direct-connect strategies alongside traditional GDS pipes. Sabre Corporation anchors North American airline IT infrastructure with legacy host systems and emerging NDC-enabled retail platforms. Amadeus IT Group dominates European carrier connectivity while extending its Altéa suite into hotel and rail content aggregation. TravelSky Technology Limited controls domestic Chinese airline distribution, leveraging state-backed infrastructure to process the world's second-largest aviation market's booking volume.
Technical Definition and Segment Structure
Travelport GDS Systems constitute computerized reservation networks that aggregate flight schedules, fare rules, seat inventory, and ancillary product catalogs from multiple airlines into a unified query-response architecture operating on EDIFACT and XML messaging protocols. The primary commercial purpose centers on enabling travel intermediaries to search, compare, and ticket complex multi-segment itineraries across competing carriers through a single terminal interface. Airline Reservations generates the dominant revenue stream within Service Type segmentation, though Travel Insurance exhibits the fastest expansion as carriers bundle cancellation coverage and medical protection at point of sale. Cloud-Based deployment models capture growing enterprise preference as travel agencies retire on-premises mainframe terminals, while API Integration technology leads R&D allocation as distributors rebuild connectivity layers for NDC-compliant airline retailing.
Regulatory Environment and Outlook
IATA governs technical standards through NDC and ONE Order initiatives that mandate XML-based merchandising protocols across member airlines. The US Department of Transportation enforces full-content display rules requiring GDS platforms to present all publicly available fares without carrier discrimination. EU antitrust authorities monitor GDS access fees and parity clauses under competition law frameworks. Stakeholders must track regulatory divergence between US market-access rules and EU platform neutrality investigations as airlines accelerate direct distribution investments.
Market Dynamics
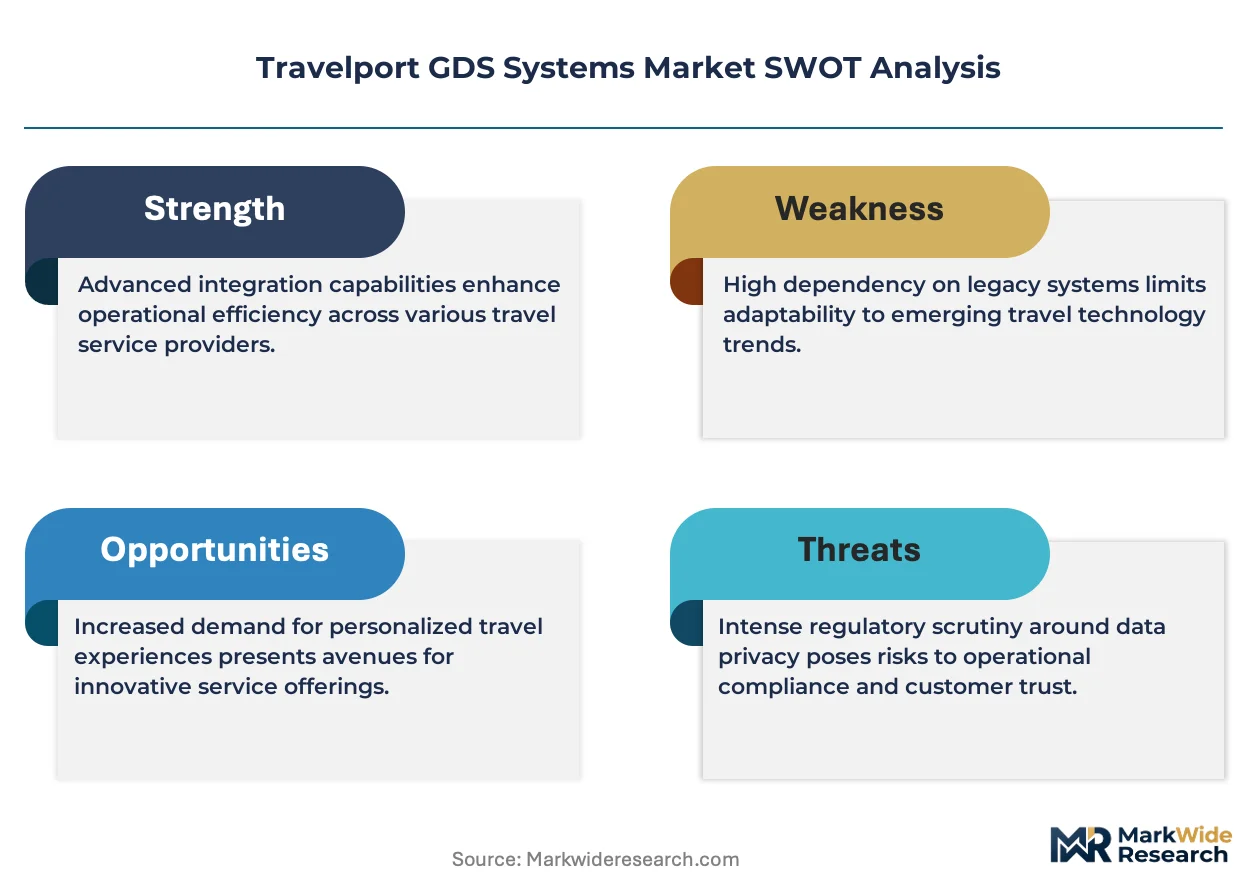
IATA's NDC (New Distribution Capability) standard is forcing GDS operators to rebuild core messaging infrastructure from EDIFACT to XML protocols, compressing legacy connectivity margins while opening airline retailing revenue streams.
Growth Catalysts
- Corporate Travel Management Modernization:Multinational enterprises are consolidating fragmented booking tools into unified platforms that require real-time GDS connectivity for duty-of-care compliance and spend analytics.
- REACH and CSRD Disclosure Mandates:European corporate travel buyers now require granular carbon footprint data at point of sale, driving GDS investment in emissions calculation APIs integrated with booking workflows.
- Ancillary Merchandising Technology:Airlines are unbundling fares into component products—seat selection, baggage, lounge access—creating transaction volume expansion for GDS platforms with retail-ready display capabilities.
Market Restraints
- Direct-Connect Infrastructure Costs:Carriers like Lufthansa and American Airlines have deployed proprietary API connections that bypass traditional GDS fee structures, eroding per-transaction revenue for distributors.
- Cloud Migration Capital Intensity:Travel agencies retiring on-premises mainframe terminals face substantial switching costs for SaaS-based GDS interfaces, slowing platform refresh cycles among smaller intermediaries.
- Data Localization Requirements:China's Cybersecurity Law and Russia's data sovereignty rules force GDS operators to maintain separate in-country server infrastructure, fragmenting global architecture economics.
Strategic Opportunities
- India's Aviation Market Expansion:The country's PLI scheme for aircraft components and airport privatization is creating demand for domestic GDS connectivity as low-cost carriers scale international routes.
- Rail-Flight Intermodal Retailing:European rail operators are opening inventory to GDS platforms under EU multimodal transport directives, enabling cross-border itinerary construction that combines high-speed rail with short-haul flights.
- Travel Insurance Embedded Distribution:Regulatory frameworks in Germany and France now permit point-of-sale cancellation coverage bundling, creating high-margin ancillary revenue streams for GDS-integrated agencies.
Industry Challenges
- Legacy System Integration Complexity:Travel management companies must maintain parallel EDIFACT and XML messaging stacks during multi-year NDC transition periods, doubling technical debt and QA overhead.
- Specialized NDC Developer Scarcity:The shallow talent pool for IATA-certified XML schema engineers is extending implementation timelines for airline retailing projects at mid-sized GDS distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travelport GDS Systems Market |
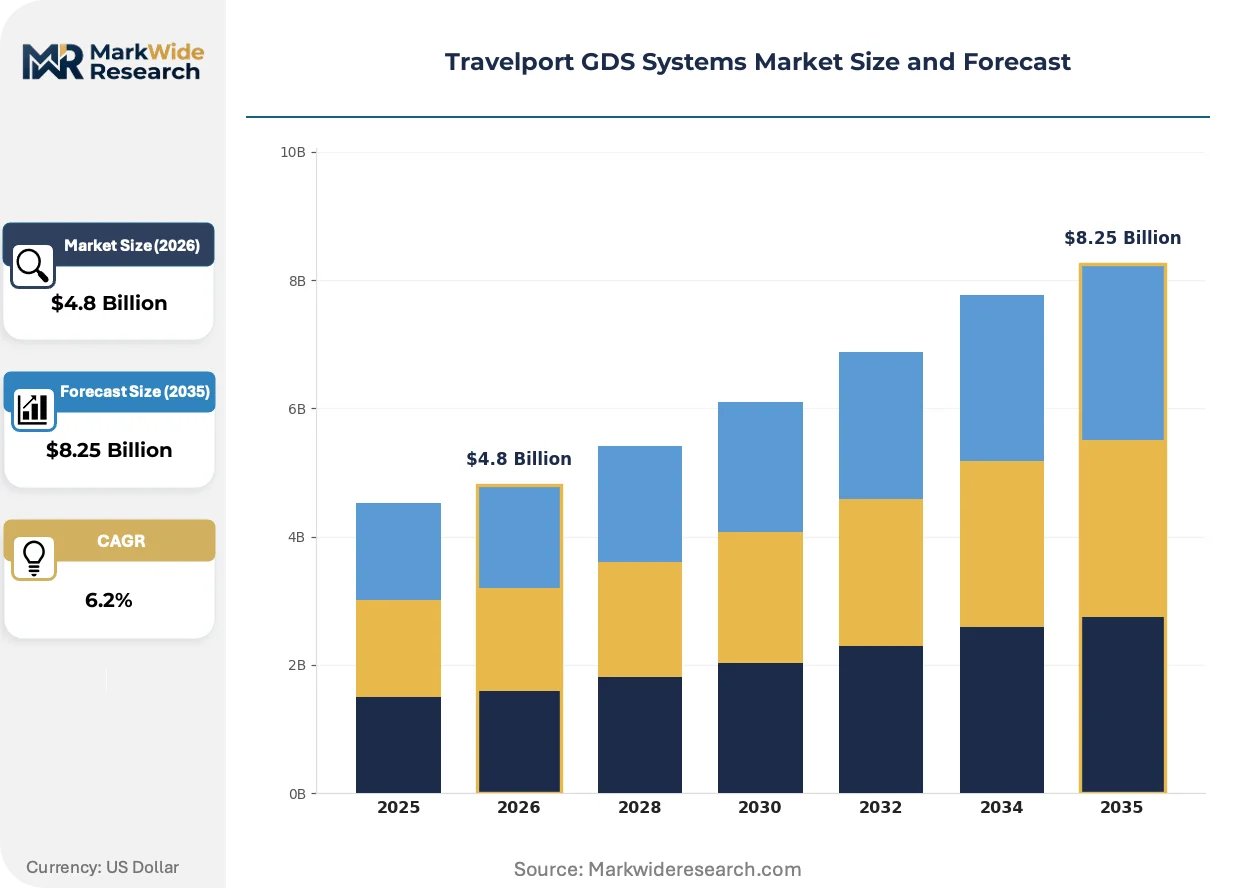
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airline Reservations, Hotel Bookings, Car Rentals, Travel Insurance Customer Type: Travel Agencies, Corporates, Tour Operators, Online Travel Agents Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS Technology: API Integration, Mobile Application, AI-Powered Solutions, Data Analytics |
| Companies Covered | Expedia Group, CWT (Carlson Wagonlit Travel), Amadeus IT Group, Virtuoso, WEX Inc., Sabre Corporation, Lufthansa Systems, TravelSky Technology Limited, Travelport Worldwide Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travelport GDS Systems Market Evolving Landscape
Airline distribution architecture is bifurcating between legacy pipe maintenance and retail-centric merchandising platforms, with technical investment clustering around real-time personalization engines and carbon-aware booking interfaces.
NDC-enabled dynamic pricing engines are rendering obsolete static filed-fare databases that GDS platforms have operated since the 1980s. Full-service carriers in Europe and North America are deploying these engines to push personalized ancillary bundles at search time. The shift is compressing the value of traditional GDS neutral displays while rewarding platforms with direct airline API relationships.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on automated fare recommendation systems deployed by GDS platforms and online travel agencies. Systems that personalize flight options based on traveler history must now document decision logic for regulatory audit. German and French corporate travel buyers are already demanding vendor compliance attestations as procurement preconditions.
Corporate procurement departments are consolidating travel spend under managed travel programs with mandatory GDS booking compliance, displacing unmanaged direct-to-airline reservations. This concentration is most visible among Fortune 500 headquarters clusters in Texas, Illinois, and California, where travel management companies are winning multi-year sole-source contracts tied to NDC-ready platform guarantees.
Travelport GDS Systems Market Segmentation
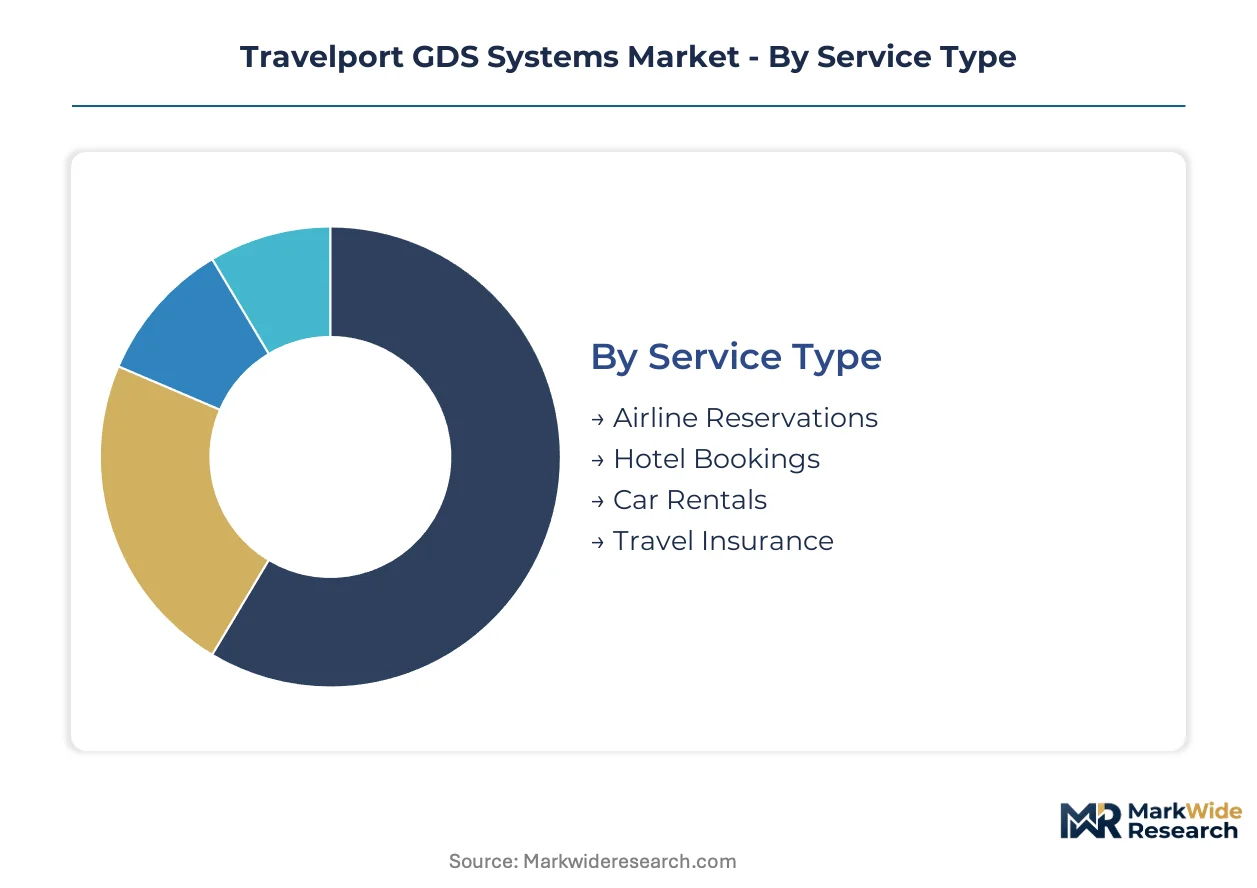
Travelport GDS Systems serve heterogeneous buyer workflows with divergent technical requirements and contract renewal cycles. Segment boundaries are blurring as cloud deployment enables hybrid service bundles and API-first architectures reshape traditional customer categories.
Service Type:
Booking transaction velocity varies dramatically across service lines, with airline inventory turning in milliseconds while insurance products cycle through annual policy renewals.
- Airline Reservations:Core flight search, booking, and ticketing functionality operating on EDIFACT and XML messaging protocols. Demand concentrates among United States-based corporate travel management companies modernizing legacy host connections for NDC compliance. Sabre Corporation and Amadeus IT Group anchor this segment with carrier-direct API investments.
- Travel Insurance:Point-of-sale cancellation coverage and medical protection bundled at booking checkout. Germany and France regulatory frameworks now permit embedded distribution, driving GDS platform integration among European online travel agents seeking ancillary revenue expansion.
- Hotel Bookings:Property inventory aggregation with rate parity management and real-time availability feeds.
- Car Rentals:Fleet inventory distribution with pickup location logistics and corporate rate code administration.
Airline Reservations dominates installed base. Travel Insurance is where expansion concentrates.
Customer Type:
Procurement sophistication separates enterprise buyers with dedicated sourcing teams from fragmented intermediary networks operating on thin commission spreads.
- Corporates:Multinational enterprises with managed travel programs requiring duty-of-care compliance, spend analytics, and mandatory GDS booking channels. Fortune 500 headquarters clusters in Texas, Illinois, and California are consolidating fragmented tools into unified platforms with NDC-ready guarantees.
- Online Travel Agents:Digital-native distributors with direct consumer acquisition and dynamic packaging capabilities. REACH and CSRD disclosure mandates from EU regulators are forcing these platforms to integrate carbon footprint APIs at point of sale.
- Travel Agencies:Traditional storefront and home-based intermediaries with established airline commission structures.
- Tour Operators:Package holiday assemblers with block inventory commitments and charter flight contracting.
Corporates command platform roadmap prioritization. Online Travel Agents are climbing the fastest on API integration investment.
Deployment Model:
Capital intensity and data residency requirements create divergent migration timelines across buyer segments.
- Cloud-Based:Scalable infrastructure with subscription economics and automatic protocol updates. China's Cybersecurity Law and Russia's data sovereignty rules fragment global architecture economics for operators serving these markets.
- SaaS:Browser-accessible terminals with per-seat licensing and reduced on-site hardware maintenance. European travel agencies are retiring mainframe terminals fastest here, though switching costs delay refresh cycles among smaller intermediaries.
- On-Premises:Dedicated server installations with full operational control and legacy system compatibility.
- Hybrid:Mixed architecture preserving sensitive data locally while leveraging cloud scalability for search workloads.
On-Premises retains legacy lock-in. Cloud-Based is gaining share fastest as NDC transition accelerates.
Technology:
Development resource allocation tracks regulatory pressure and airline retailing roadmap priorities.
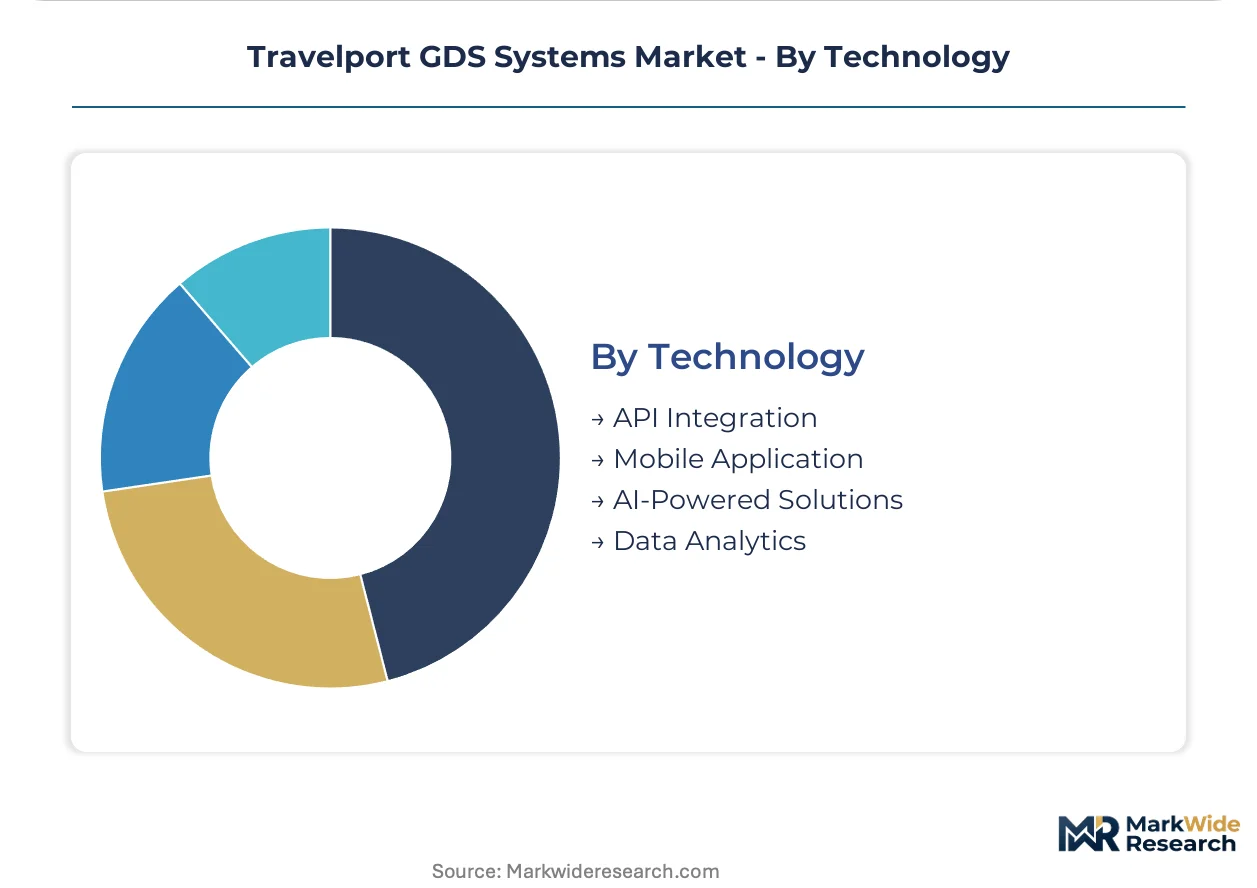
- API Integration:Direct airline connectivity bypassing traditional GDS pipes, enabling dynamic pricing and ancillary merchandising. IATA's NDC standard is compressing legacy connectivity margins while opening retailing revenue streams for platforms with certified XML schema capabilities.
- AI-Powered Solutions:Personalized fare recommendation engines with algorithmic transparency requirements under EU AI Act risk classification frameworks. German and French corporate buyers now demand vendor compliance attestations as procurement preconditions.
- Data Analytics:Travel spend visualization and predictive booking pattern identification.
- Mobile Application:Agent-facing and traveler-facing interfaces for itinerary management and disruption handling.
API Integration absorbs dominant R&D allocation. AI-Powered Solutions represent the steepest expansion trajectory on regulatory compliance investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets fragment under divergent regulatory pressures. German corporate buyers extract steeper discounts through consolidated procurement pools. Chinese state-backed infrastructure locks foreign competitors behind data localization walls.
United States
Corporate travel management companies in Texas, Illinois, and California drive platform modernization spending through multi-year sole-source contracts. The Department of Transportation enforces full-content display rules requiring GDS platforms to present all publicly available fares without carrier discrimination. Dallas-Fort Worth and Chicago headquarters clusters anchor demand for NDC-ready connectivity layers.
Germany
Lufthansa's direct-connect API investments bypass traditional GDS fee structures, compressing distributor margins. REACH and CSRD disclosure mandates force platforms to integrate carbon footprint APIs at point of sale. Frankfurt and Munich corporate procurement departments demand vendor compliance attestations under EU AI Act risk classification frameworks.
China
TravelSky Technology Limited processes domestic airline booking volume through state-backed infrastructure. The Cybersecurity Law forces GDS operators to maintain separate in-country server infrastructure, fragmenting global architecture economics. Beijing and Shanghai aviation hubs concentrate demand for domestic connectivity as low-cost carriers scale international routes.
United Kingdom
Post-Brexit regulatory divergence complicates EU platform neutrality compliance for London-based travel management companies. The Competition and Markets Authority monitors GDS access fees under national competition law frameworks. London City and Canary Wharf financial districts sustain demand for duty-of-care compliant booking channels.
India
The PLI scheme for aircraft components and airport privatization creates demand for domestic GDS connectivity. Low-cost carriers scaling international routes require real-time inventory aggregation. Mumbai and Delhi-NCR aviation hubs concentrate procurement modernization among multinational enterprise regional headquarters.
Travelport GDS Systems Market Competitive Landscape
Legacy GDS incumbents and airline-owned technology divisions split the market between neutral distribution platforms and carrier-direct retailing systems. Three archetypes dominate: full-service global distributors with multi-modal content aggregation, regional specialists leveraging state-protected domestic infrastructure, and airline-owned technology subsidiaries pursuing vertical control over distribution economics. Competitive moves cluster around NDC certification races and carbon calculation API partnerships.
Within the legacy distributor tier, Sabre Corporation and Amadeus IT Group occupy positions defined by carrier-direct API investments and Altéa suite extensions. Among state-protected regional specialists, TravelSky Technology Limited exemplifies the architecture economics of data localization mandates. These three entities represent the strategic spectrum from open retailing platforms to closed domestic ecosystems.
| Leading Market Players |
|---|
| Expedia Group |
| CWT (Carlson Wagonlit Travel) |
| Amadeus IT Group |
| Virtuoso |
| WEX Inc. |
| Sabre Corporation |
| Lufthansa Systems |
| TravelSky Technology Limited |
| Travelport Worldwide Ltd. |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure concentration in the United States and European Union concentrates margin capture among hyperscale providers serving GDS operators, while downstream pricing power fragments across transactional SaaS tiers and legacy per-seat licensing models still anchoring smaller agency networks.
Pricing Analysis
Configured-to-order API integration packages command substantial premiums over standard EDIFACT terminal access, with pricing stratifying across premium, standard, and economy tiers based on NDC certification level and real-time ancillary merchandising depth. Price differentiation hinges on XML schema compliance tier and geographic delivery cost for data residency-compliant hosting. Cost compression in the standard tier is intensifying because airline direct-connect investments bypass traditional GDS fee structures. Online travel agents exhibit highest price sensitivity due to thin commission spreads, while Fortune 500 corporate procurement departments prioritize NDC-ready guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from airline customers now stretch GDS operator working capital cycles, with supply-chain finance facilities emerging as critical liquidity bridges. Geographic supply concentration centers on United States, Ireland, and Singapore for primary data center infrastructure, while software development draws from India and Poland for XML engineering talent. Raw material dependencies include server-grade semiconductors, fiber optic transmission equipment, and cybersecurity certification services. Single-source vulnerability in NDC-certified developer pools threatens implementation timelines. Distribution runs through direct enterprise sales teams for corporate accounts and channel partners for mid-market agency penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NDC protocol fragmentation creates white-space niches for specialized connectivity providers, as airline retailing roadmaps diverge across IATA member carriers and direct-connect API specifications multiply.
For Market Incumbents: Insulate core EDIFACT revenue streams through long-term sole-source contracts with corporate travel management companies while accelerating NDC certification investments to capture airline retailing margins. Threat from Lufthansa Systems and other carrier-owned technology divisions intensifies as vertical integration into proprietary distribution platforms accelerates. Channel control through exclusive GDS booking mandates in managed travel programs remains the critical defensive lever. For New Entrants and Emerging Players: Build out carbon calculation API layers for European online travel agents facing REACH and CSRD disclosure mandates, the most penetrable segment given regulatory enforcement timelines and incumbent platform refresh cycles. India's aviation market expansion offers secondary geography entry, with Mumbai and Delhi-NCR regional headquarters requiring domestic connectivity as low-cost carriers internationalize. Go-to-market through embedded insurance bundling partnerships exploits regulatory openings in Germany and France. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed travel technology platforms that consolidated agency software tools through the pandemic period and now require NDC connectivity layer investment for exit positioning. Long-term viability hinges on five-to-ten year airline retailing protocol standardization trajectories. Acquisition targets with certified IATA NDC Level 3 or 4 capabilities and existing airline direct API relationships command strategic premiums. The signal to watch is American Airlines and other major carrier direct-connect fee renegotiation announcements, which would accelerate GDS margin compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| NDC Certification Investment | IATA Level 3 or 4 certification unlocks airline ancillary merchandising revenue streams for GDS platforms. |
| Carbon Calculation API Development | REACH and CSRD compliance integration captures European corporate travel procurement modernization budgets. |
| Direct Airline API Partnership | Bypassing traditional GDS pipes enables dynamic pricing and personalized retailing capability deployment. |
| India Market Infrastructure Buildout | PLI scheme and airport privatization create domestic GDS connectivity demand from scaling low-cost carriers. |
| Rail-Flight Intermodal Integration | EU multimodal transport directives enable cross-border itinerary construction combining high-speed rail with short-haul flights. |
Research Methodology
The analysis maps airline reservation systems, travel insurance platforms, hotel inventory aggregation, and car rental distribution networks, each validated through travel technology executives, airline distribution strategists, corporate travel procurement officers, and IATA standards committee participants. Primary interview findings triangulate against IATA NDC implementation white papers, SEC 10-K filings from publicly traded GDS operators, EU regulatory disclosure databases tracking REACH and CSRD compliance, and customs data on aviation IT services trade flows. Bottom-up segment sizing and top-down macroeconomic validation ensure cross-verified output reliability.
Assumption sets held airline retailing adoption curves and NDC protocol maturity pathways fixed while varying corporate travel recovery trajectories and regulatory enforcement intensity across the analysis window. Segmentation dimensions modeled include service type, customer archetype, deployment model, and technology layer, with regional adoption patterns as an industry-specific overlay. CAGRs derive from installed base turnover rates and new capability penetration curves. Forecast inputs incorporate airline direct-connect investment disclosures and corporate travel management company contract renewal timelines.
The forecast holds incumbent behavior within observed patterns; aggressive direct-connect expansion by full-service carriers or accelerated EU AI Act enforcement would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Travel Technology Market