
 Restaurant Reservations Software Market | 2026-2036
Restaurant Reservations Software Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Reservations Software Market Analytics
Platform licensing revenue is reshaping competitive economics in restaurant technology, as vendors shift from per-cover fees to subscription-based models. OpenTable leverages its two-decade diner network to sustain high switching costs for enterprise accounts. SevenRooms specializes in CRM-integrated hospitality workflows that differentiate it from transaction-focused rivals. Resy anchors its position among independent restaurants through direct POS partnerships that reduce operational friction.
Restaurant reservations software comprises digital systems that manage table inventory, guest seating, and diner communications through real-time availability engines synchronized with kitchen capacity and service pacing. These platforms process booking requests across web, mobile, and voice channels while capturing guest preference data to optimize floor plans and reduce no-show rates. Cloud-based deployment leads the solution type category by enabling instant scalability without on-site server maintenance, while fine-dining customer types command premium pricing due to complex seating protocols and pre-arrival coordination requirements. Multi-location deployment models are expanding fastest as regional restaurant groups standardize operations across properties, and integration with payment systems captures the deepest margin pools by enabling deposit collection and pre-paid tasting menu transactions.
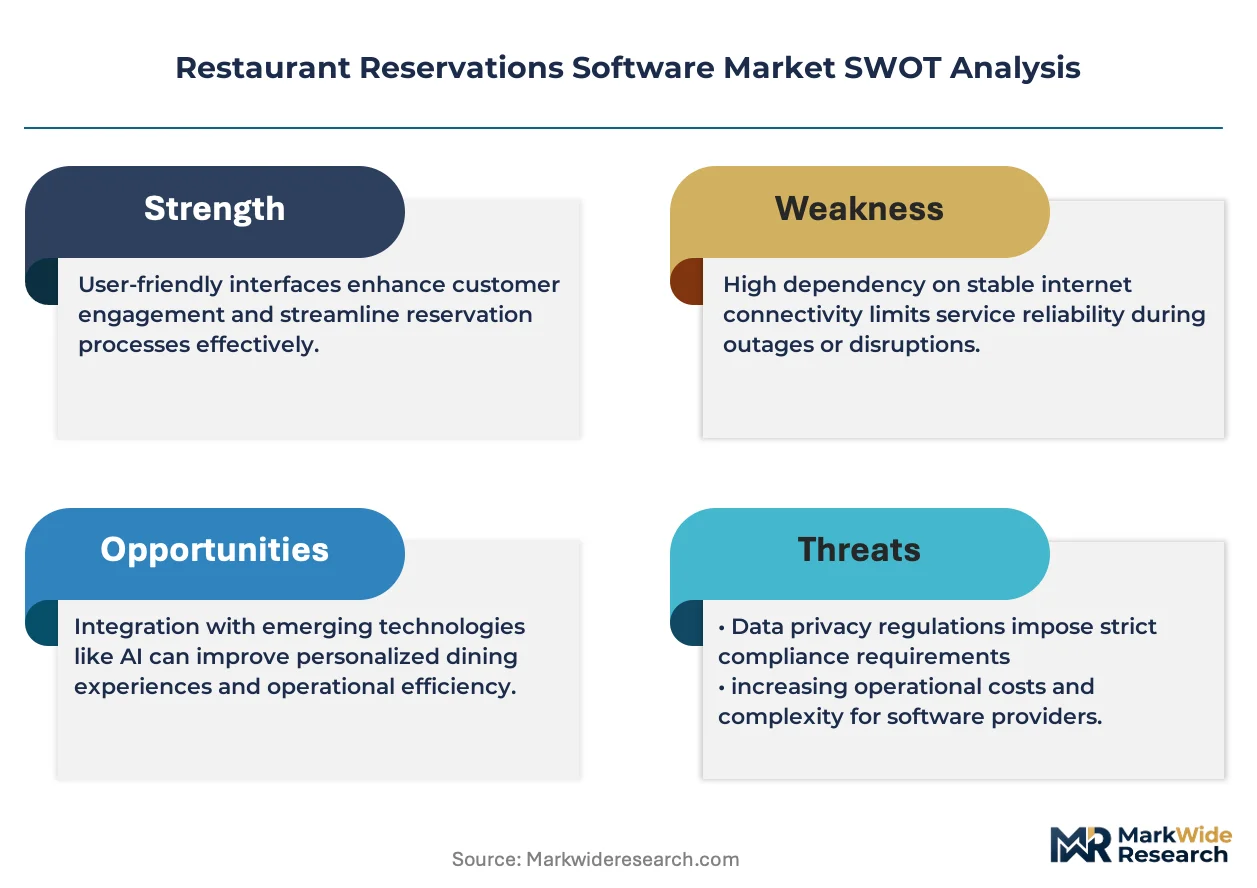
The Federal Trade Commission monitors subscription billing practices in restaurant SaaS, while PCI-DSS standards govern payment data handling across all deployment models, and the California Consumer Privacy Act imposes guest data management obligations on operators serving that state. These frameworks elevate compliance costs for new entrants but also create defensible positions for established vendors with certified security architectures. Stakeholders must monitor how artificial intelligence-driven dynamic pricing tools alter diner expectations and platform selection criteria.
Market Dynamics
Platform economics in restaurant reservations software are pivoting toward subscription-based recurring revenue, compressing per-transaction margins while elevating customer lifetime value calculations for vendor strategy.
Growth Catalysts
- PCI-DSS compliance mandates:Payment card security standards in North America and Europe are disqualifying non-compliant booking systems from enterprise procurement shortlists.
- Cloud-native architecture:Elimination of on-premise server maintenance is accelerating replacement cycles among independent restaurant operators.
- Multi-location standardization:Regional restaurant groups in the United States are consolidating fragmented property-level systems onto unified platforms.
Market Restraints
- GDPR data localization costs:European Union privacy rules impose expensive guest data residency infrastructure on vendors serving cross-border operators.
- POS integration fragmentation:Proprietary API standards across legacy restaurant management systems create technical debt for platform developers.
- High switching costs:Historical diner preference data locked in incumbent platforms deters restaurant migration to competing solutions.
Strategic Opportunities
- Voice-channel booking expansion:Natural language processing integration with phone systems captures reservation volume outside digital-native demographics.
- Kitchen capacity synchronization:Real-time coordination between reservation engines and culinary throughput enables dynamic seating optimization.
- Pre-arrival payment capture:Deposit collection for tasting menus and special events reduces no-show revenue loss for fine-dining establishments.
Industry Challenges
- Hospitality workflow integration:Front-of-house staff require extensive retraining when migrating from legacy paper-based reservation systems.
- California Consumer Privacy Act compliance:Guest data deletion requests and portability requirements strain operational workflows for operators serving that state.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Reservations Software Market |
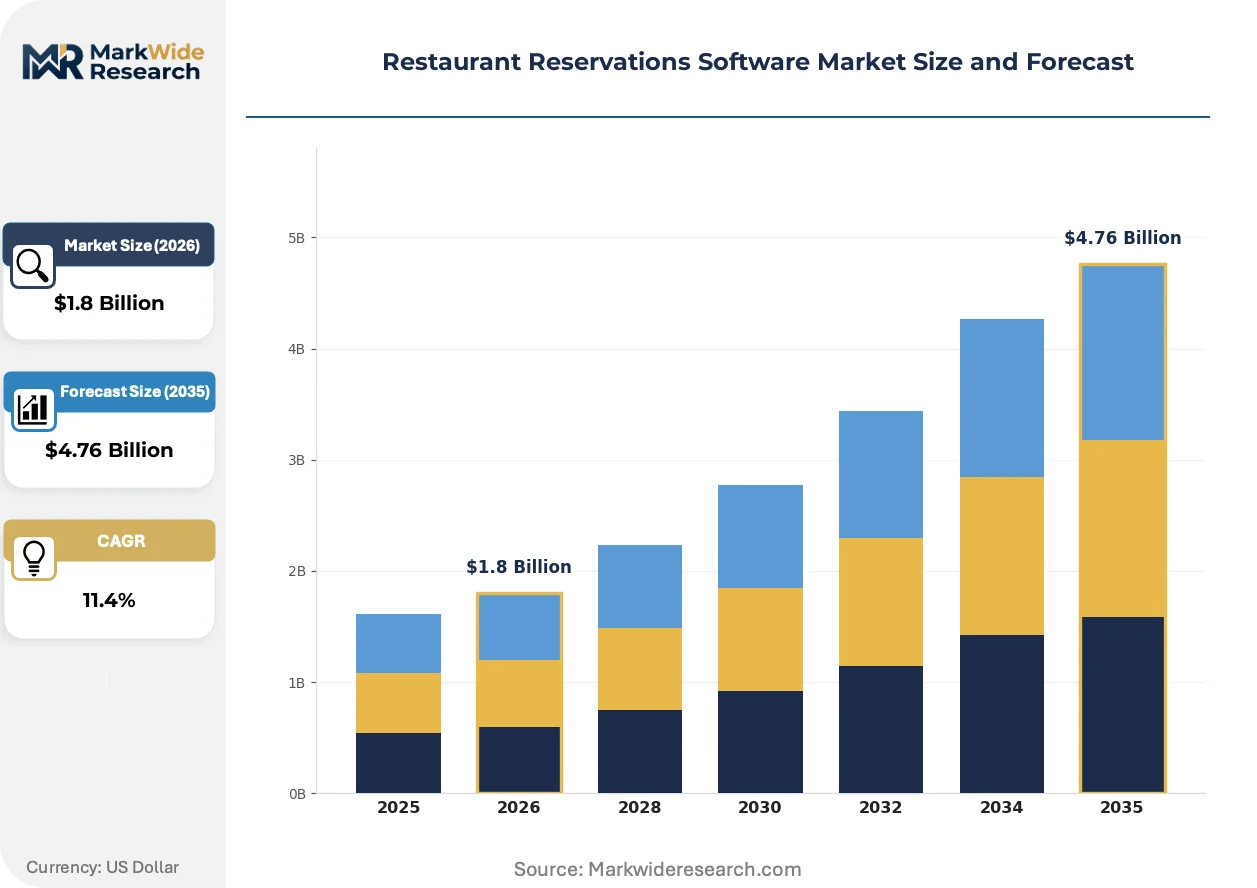
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premise, Hybrid, Mobile App Customer Type: Fine Dining, Casual Dining, Cafés, Fast Food Deployment Model: Single-Location, Multi-Location, Franchise, Independent Integration Level: Payment Systems, CRM Tools, POS Systems, Others |
| Companies Covered | Tock, Yelp Guest Manager, OpenTable, TouchBistro, Eat App, Resy, SevenRooms, The Fork, Resos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Reservations Software Market Evolving Landscape
Artificial intelligence is penetrating reservation platforms through predictive demand modeling and automated guest communication, altering how restaurants manage table inventory and diner relationships.
Dynamic pricing engines are migrating from airline and hospitality revenue management into fine-dining reservation systems. Premium establishments in New York and San Francisco are adopting demand-based cover charges for peak seating windows. This technology is compressing traditional fixed-menu pricing structures while capturing previously unrealized revenue from high-demand time slots.
GDPR enforcement across European Union member states is mandating granular consent management for guest data collection. Reservation platforms must now implement explicit opt-in workflows for marketing communications and preference tracking. Fine-dining operators in France and Germany are responding by deploying localized data residency architectures to satisfy national regulator interpretations of cross-border transfer restrictions.
Direct booking channels are displacing third-party marketplace dependency among independent restaurants. Proprietary websites and mobile applications now capture reservation volume previously routed through aggregator platforms. This behavioral shift is most visible in the United States, where operator margins improve through elimination of per-cover commission fees.
Restaurant Reservations Software Market Segmentation
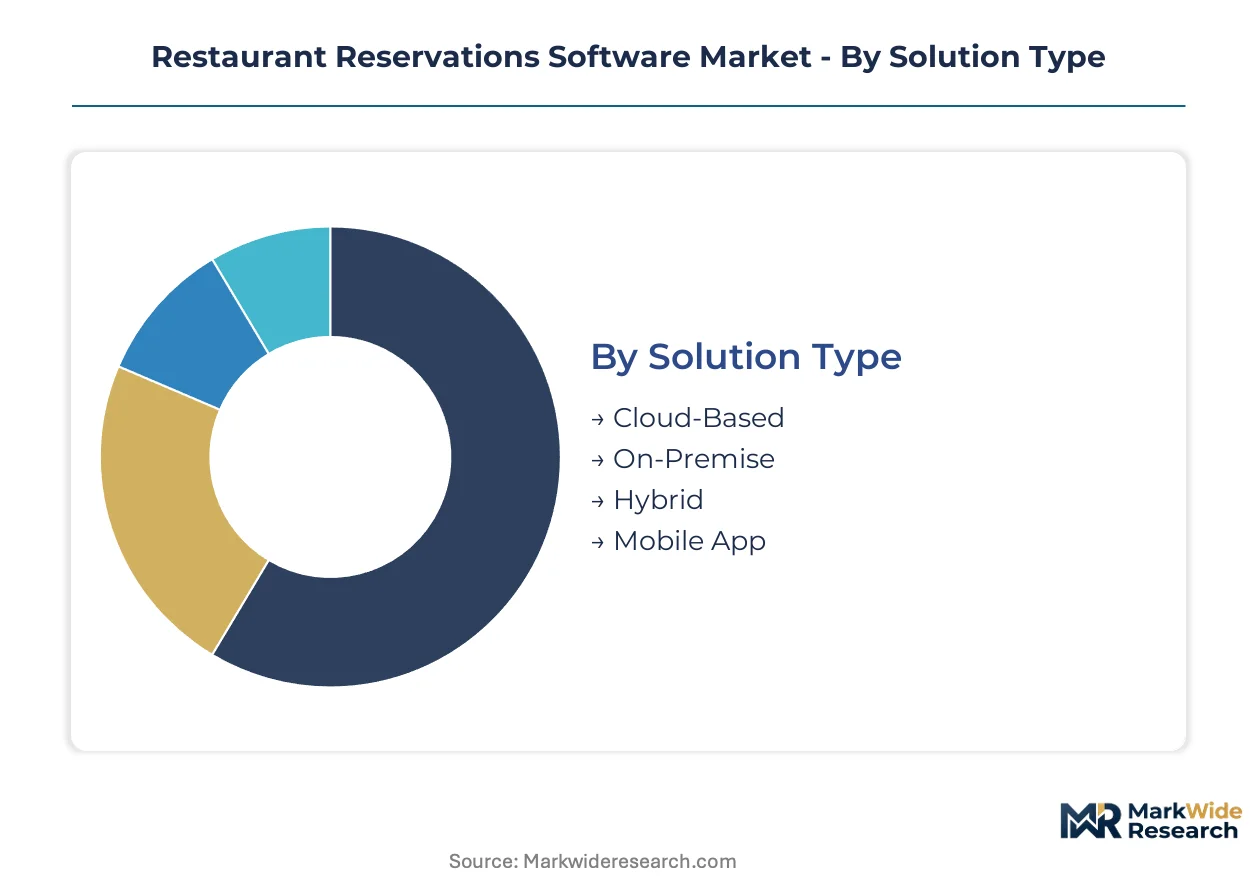
Restaurant reservations software segments reflect divergent operational maturity across operator types and technical infrastructure requirements. Cloud-native architectures now dominate new procurement decisions while legacy on-premise systems persist in enterprise accounts with specialized compliance needs. Understanding these segment boundaries clarifies where platform vendors can capture pricing power versus where commoditization pressures concentrate.
Solution Type:
Mature deployment models coexist with emerging delivery mechanisms across the solution spectrum, creating tiered competitive dynamics based on infrastructure ownership and scalability profiles.
- Cloud-Based:Browser-accessible platforms eliminate server maintenance burdens through vendor-managed hosting. United States independent operators in New York and San Francisco are consolidating onto these systems to enable instant scaling during peak dining seasons without capital expenditure. PCI-DSS compliance certification from cloud providers accelerates enterprise procurement cycles.
- On-Premise:Locally installed software maintains guest data within operator-controlled servers. European fine-dining establishments in France and Germany favor this architecture to satisfy GDPR data residency interpretations from CNIL and national regulators. Higher upfront licensing costs trade against perpetual data sovereignty.
- Hybrid:Split architectures synchronize core reservation functions through cloud connectivity while retaining sensitive payment processing on local infrastructure. This configuration addresses PCI-DSS segmentation requirements for operators handling high-volume card transactions.
- Mobile App:Native smartphone applications deliver booking interfaces optimized for guest self-service. Casual dining chains deploy these to reduce call center dependency and capture younger demographic segments.
Cloud-Based handles the majority of throughput; Mobile App is expanding most quickly on share.
Customer Type:
Margin structures diverge sharply across dining formats, with pre-arrival coordination complexity determining platform pricing tiers and integration depth requirements.
- Fine Dining:Multi-course tasting menu operations require sophisticated table pacing algorithms synchronized with kitchen capacity. United States establishments in Manhattan and Napa Valley command premium software pricing due to complex seating protocols and deposit collection workflows. FTC subscription billing oversight affects SaaS procurement terms in this high-value segment.
- Casual Dining:Mid-market restaurants prioritize throughput optimization over guest preference tracking. Regional chains standardize on unified platforms to manage party sizes and waitlist automation across properties.
- Cafés:Limited-service operators leverage lightweight reservation modules primarily for special events and large party bookings rather than daily table management.
- Fast Food:Quick-service concepts deploy queue management functionality rather than traditional reservation systems, integrating with mobile ordering platforms for pickup timing coordination.
Fine Dining commands the steepest pricing; Casual Dining shows the steepest expansion trajectory.
Deployment Model:
Organizational scale dictates platform architecture requirements, with distributed operations demanding centralized data visibility that single-location systems cannot provide.
- Single-Location:Standalone installations serve individual restaurants with property-specific table maps and staff permissions. Independent operators favor these for simplified onboarding and minimal IT overhead.
- Multi-Location:Enterprise-grade platforms synchronize reservation data across regional restaurant groups. United States-based hospitality companies consolidate fragmented property-level systems to enable corporate revenue management and standardized guest experience.
- Franchise:Franchisor-controlled deployments enforce brand consistency while allowing franchisee operational autonomy. Master agreements negotiate bulk licensing terms across network locations.
- Independent:Owner-operator configurations emphasize direct guest relationships over corporate reporting requirements, driving demand for CRM-integrated workflows.
Multi-Location deployments are gaining share fastest; Single-Location retains the largest installed base.
Integration Level:
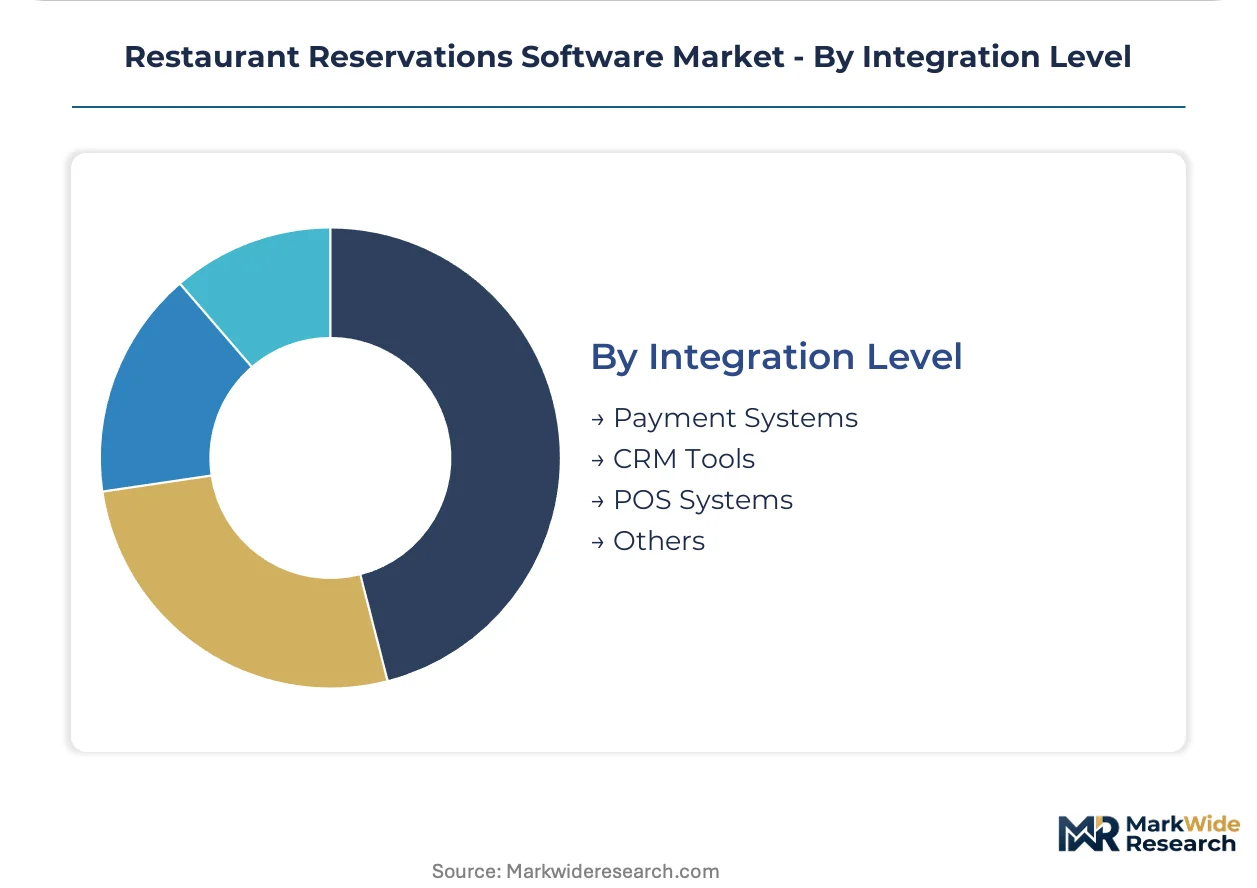
Revenue capture depth correlates with payment system connectivity, as deposit collection and pre-arrival transactions require seamless financial data flows.
- Payment Systems:Direct card processing integration enables no-show protection through authorized holds and tasting menu prepayment. PCI-DSS compliance mandates disqualify non-certified platforms from enterprise shortlists in North America.
- CRM Tools:Guest preference databases drive personalized service delivery and targeted marketing automation. Fine-dining operators leverage historical dining data to optimize floor plans and anticipate dietary restrictions.
- POS Systems:Real-time synchronization between reservation engines and point-of-sale terminals closes the loop on table turnover analytics and revenue per available seat hour calculations.
- Others:Supplementary connections span kitchen display systems, inventory management platforms, and workforce scheduling tools to coordinate front-of-house and back-of-house operations.
Payment Systems integration captures the deepest margin pools; CRM Tools integration is climbing the fastest on vendor roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States operators prioritize cloud-native platforms with payment integration, while European establishments emphasize GDPR-compliant data sovereignty. Asian markets favor mobile-first booking interfaces adapted to dense urban dining cultures.
United States
Fine-dining establishments in Manhattan and San Francisco drive premium platform adoption through complex seating protocols and deposit collection workflows. FTC subscription billing oversight shapes SaaS procurement terms for high-value accounts. New York Metro operators consolidate fragmented property-level systems onto unified cloud platforms to enable corporate revenue management.
Germany
Fine-dining operators in Munich and Hamburg favor on-premise architectures to satisfy GDPR data residency interpretations from national regulators. The country's central data protection authority enforces granular consent management for guest preference tracking. Berlin-Brandenburg restaurant groups deploy localized data residency infrastructure to satisfy cross-border transfer restrictions.
France
Parisian fine-dining establishments command premium software pricing due to multi-course tasting menu operations requiring sophisticated table pacing algorithms. CNIL mandates explicit opt-in workflows for marketing communications and preference tracking. Provence-Alpes-Côte d'Azur operators deploy hybrid architectures retaining sensitive payment processing on local infrastructure.
United Kingdom
London-based hospitality companies accelerate replacement cycles of legacy systems through vendor-managed cloud hosting. The Information Commissioner's Office enforces guest data deletion requests and portability requirements under UK GDPR. Southeast England regional restaurant groups standardize operations across properties through multi-location deployment models.
Japan
Tokyo metropolitan area restaurants integrate voice-channel booking systems to capture reservation volume outside digital-native demographics. METI guidelines influence platform security standards for payment data handling. Osaka-Kansai operators deploy mobile-first interfaces optimized for guest self-service among younger demographic segments.
Restaurant Reservations Software Market Competitive Landscape
Capability concentration sits with specialized CRM-integrated vendors; scale advantage sits with established diner network platforms. The market structures around three tiers: legacy enterprise providers with two-decade diner databases, cloud-native challengers with direct POS partnerships, and hospitality workflow specialists with differentiated guest preference tracking. Dominant competitive moves include strategic partnerships with payment processors and geographic expansion through localized data residency architectures.
Within the enterprise network tier, OpenTable leverages its established diner database to sustain high switching costs for premium accounts. SevenRooms occupies a position among CRM-integrated hospitality workflow specialists, differentiating through guest preference data optimization. Resy anchors the independent restaurant segment through direct POS partnerships that reduce operational friction for owner-operators.
| Leading Market Players |
|---|
| Tock |
| Yelp Guest Manager |
| OpenTable |
| TouchBistro |
| Eat App |
| Resy |
| SevenRooms |
| The Fork |
| Resos |
| Others |
Value Network & Pricing Analysis
PCI-DSS compliance certification bottlenecks determine both tier spreads between certified and non-certified platforms and supply chain concentration among vendors with audit-ready security architectures. Restaurant operators in the United States face procurement disqualification for non-compliant systems, compressing margins for uncertified challengers while elevating pricing power for established vendors with pre-certified cloud infrastructure.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement in fine-dining segments, while independent operators favor month-to-month SaaS tiers with per-location caps. Three-tier pricing structure across premium, standard, and economy levels separates PCI-DSS-certified enterprise platforms from lightweight independent solutions and freemium entry products. Cost compression in the standard tier is intensifying because cloud-native challengers are undercutting legacy per-cover fee models. Regional restaurant groups show highest price sensitivity due to multi-location licensing scale, while Manhattan fine-dining establishments absorb premium pricing for deposit collection and kitchen synchronization features.
Supply Chain Analysis
Extended payment terms from cloud hyperscalers enable vendor cash flow management as platform providers negotiate 90-day cycles with AWS, Azure, and Google Cloud infrastructure partners. Software development concentrates in the United States, Ireland, and India, with engineering talent clusters in San Francisco, Dublin, and Bangalore anchoring product roadmaps. Raw material dependencies span server hardware from Taiwan, payment processing chips from South Korea, and customer support labor from the Philippines. Single-source vulnerability runs through AWS dominance in North American cloud hosting for reservation platforms. Distribution runs through direct sales teams for enterprise accounts and self-service onboarding portals for independent restaurants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States regional restaurant groups consolidating fragmented property-level systems, shifting negotiation leverage toward multi-location operators with unified procurement authority.
For Market Incumbents: Insulate enterprise accounts through deeper POS integration partnerships that increase switching costs for fine-dining establishments with historical diner preference data locked in proprietary CRM architectures. Invest in GDPR-compliant data residency infrastructure for European expansion before CNIL enforcement hardens cross-border transfer restrictions. Vertical integration into payment processing captures deposit collection margins that third-party processors currently extract. For New Entrants and Emerging Players: Build out voice-channel booking capabilities targeting Japanese and aging demographic segments where natural language processing reduces call center dependency for Tokyo metropolitan operators. Target casual dining chains in the United Kingdom with lightweight cloud-native platforms that undercut legacy on-premise replacement cycles. Lead with mobile-first self-service interfaces to capture younger demographic adoption before incumbents retrofit aging architectures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors CRM-integrated hospitality workflow specialists over transaction-focused legacy platforms with deteriorating per-cover economics. Long-term viability hinges on AI-driven dynamic pricing adoption across fine-dining segments and kitchen capacity synchronization penetration. Target acquisition archetypes include cloud-native challengers with direct POS partnerships in the independent restaurant segment. Watch PCI-DSS certification timelines as an inflection indicator for vendor disqualification rates in enterprise procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Direct POS partnerships with Toast and Square reduce operational friction for United States independent operators. |
| Geographic Expansion | Localized data residency architectures satisfy CNIL and German regulator interpretations of GDPR cross-border restrictions. |
| Product Launch | Voice-channel booking systems capture reservation volume outside digital-native demographics in Tokyo and Osaka. |
| Strategic Partnership | Payment processor alliances enable PCI-DSS-compliant deposit collection for fine-dining tasting menu prepayment. |
| Acquisition of Specialist Firm | CRM-integrated workflow capabilities differentiate hospitality-focused vendors from transaction-centric rivals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC SaaS company filings, App Annie mobile platform analytics, and hyperscaler infrastructure capex disclosures. Interviews with restaurant technology CTOs, IT procurement officers at regional hospitality groups, platform integration specialists, and front-of-house operations directors informed demand-side validation. Bottom-up sizing of vendor-reported subscription revenue and top-down triangulation against total addressable restaurant operator counts anchored market estimates.
Forecast inputs include deployment model adoption curves, integration complexity tiers, and regional regulatory compliance requirements across the projection horizon. Segmentation dimensions modeled span solution type, customer dining format, organizational scale, and payment system connectivity depth. CAGRs were derived from analyst assessments of replacement cycle acceleration and cloud migration penetration. AI-driven dynamic pricing adoption rates and kitchen capacity synchronization deployment timelines served as industry-specific forecast modifiers.
Stress conditions across PCI-DSS enforcement intensity, GDPR data localization cost inflation, and regional restaurant group consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cloud-native architecture replacement cycles and mobile-first booking preference shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Global Reservations Software Market