
 Smart Travel Sector Market | 2026-2036
Smart Travel Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Travel Sector Market Analytics
Online travel agency distribution is fragmenting as platform economics shift toward direct supplier connectivity and embedded fintech services. Booking Holdings sustains its position through proprietary property inventory and loyalty currency systems across multiple continental markets. Expedia Group competes by leveraging its B2B white-label infrastructure and corporate travel subsidiary. Google dominates metasearch discovery layers, capturing query intent upstream of transaction decisions.
Smart travel encompasses digitally orchestrated mobility, accommodation, and experience procurement systems that integrate real-time data streams, predictive algorithms, and multimodal booking engines to optimize traveler utility and supplier yield. The technology stack relies on API-first architectures, cloud-native reservation protocols, and sub-second latency requirements for dynamic pricing and inventory synchronization. Artificial Intelligence segments command structural attention as natural language interfaces and generative trip planning reshape search-to-booking funnels, while Mobile Payment Solutions segments in Asia-Pacific markets demonstrate the fastest behavioral adoption curves among younger traveler cohorts. Online Booking remains the mature revenue core, though margin compression from supplier direct-channel incentives demands continuous platform differentiation.
FDA oversight of biometric identity verification systems for aviation security, FCC regulations governing in-flight connectivity spectrum allocation, and EU GDPR data-localization mandates collectively shape product architecture and market access conditions for cross-border service providers. The EU AI Act introduces additional compliance layers for algorithmic recommendation engines used in personalized itinerary generation and dynamic fare presentation. Stakeholders must monitor evolving interoperability standards between national digital identity frameworks and private travel credentials, as regulatory fragmentation threatens seamless cross-border service delivery.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing travel platforms to reengineer recommendation engines and dynamic pricing systems, while China's urban mobility corridors concentrate demand for multimodal transit integration.
Growth Catalysts
- Generative trip planning interfaces:Natural language processing capabilities are collapsing search-to-booking friction, pulling younger traveler cohorts toward conversational booking experiences.
- EU AI Act compliance architectures:Regulatory pressure for explainable algorithms is accelerating investment in auditable machine learning pipelines for personalized itinerary generation.
- China's smart transit corridors:Urban mobility integration in Beijing, Shanghai, and Shenzhen is driving demand for real-time multimodal booking engines that synchronize rail, ride-hail, and micro-mobility.
Market Restraints
- GDPR data-localization mandates:Cross-border passenger data flows face structural friction from EU storage requirements, fragmenting cloud infrastructure deployments.
- Aviation biometric certification timelines:FDA-equivalent oversight of facial recognition systems for airport security creates multi-year validation cycles for identity verification vendors.
- Supplier direct-channel incentives:Hotel chains and airlines are compressing OTA margins through loyalty program exclusivity and rate parity enforcement.
Strategic Opportunities
- Embedded fintech services:Buy-now-pay-later integration and travel insurance APIs represent white space for platforms to capture ancillary revenue streams.
- India's digital payment infrastructure:UPI rails and mobile wallet penetration in tier-2 and tier-3 cities create underpenetrated booking volume for localized platforms.
- CSRD sustainability reporting:Corporate travel management platforms can capture ESG-mandated demand by embedding carbon accounting into expense workflows.
Industry Challenges
- API interoperability fragmentation:National digital identity frameworks lack standardized protocols, forcing platforms to maintain parallel credential verification systems.
- Sub-second latency engineering:Dynamic pricing synchronization across distributed inventory systems demands specialized cloud architecture talent that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Travel Sector Market |
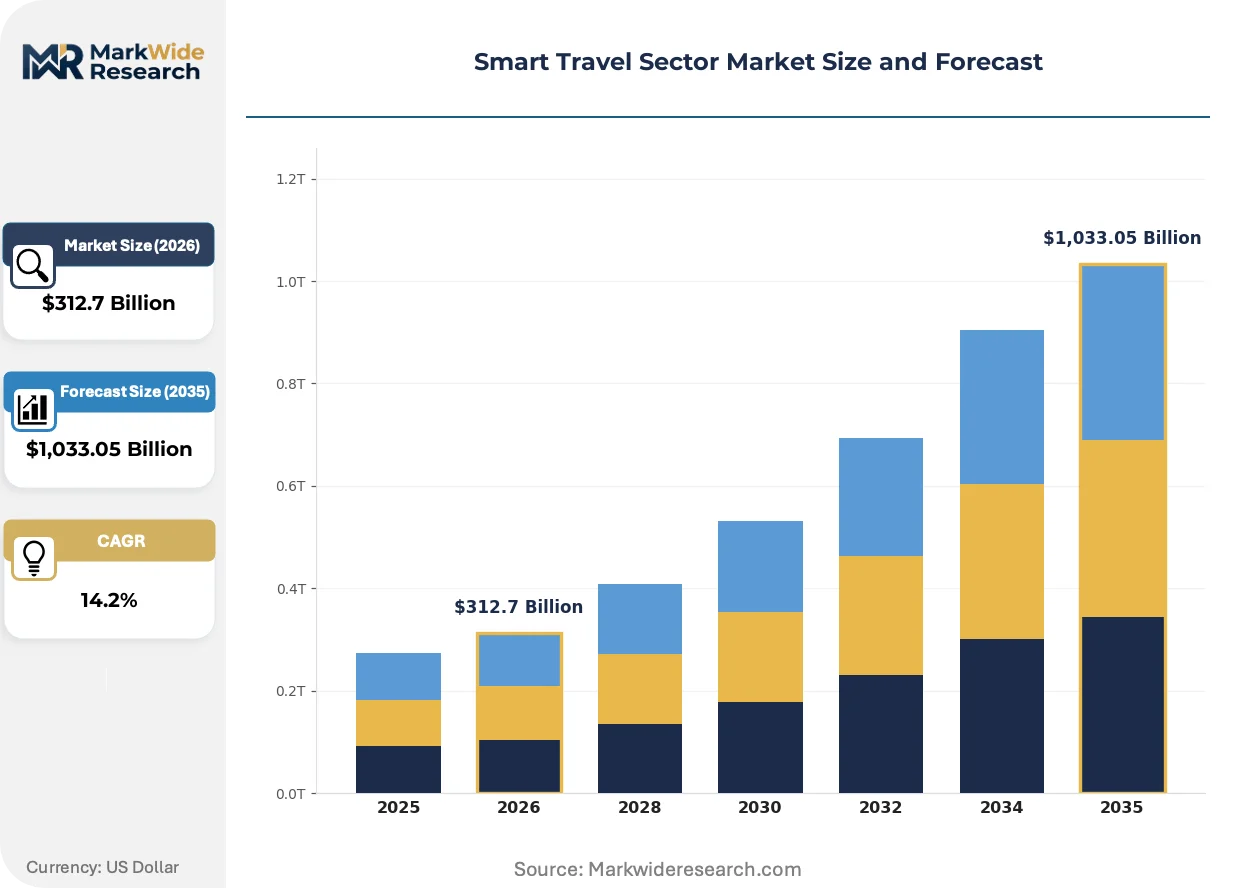
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,033.05 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Apps, Online Booking, Travel Insurance, Personalized Itineraries Customer Type: Business Travelers, Leisure Tourists, Senior Travelers, Backpackers Technology: Artificial Intelligence, Augmented Reality, Mobile Payment Solutions, Internet of Things Application: Trip Planning, Real-Time Updates, Location-Based Services, Loyalty Programs |
| Companies Covered | Google, Expedia Group, Booking Holdings, Sabre Corporation, Amadeus IT Group, Airbnb, Travelport, Cubic Transportation Systems, China TravelSky Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Travel Sector Market Evolving Landscape
Real-time data orchestration and predictive algorithms are collapsing traditional booking funnel architectures, while regulatory mandates reshape platform data governance and multimodal integration redefines traveler utility.
Generative artificial intelligence is collapsing the traditional search-to-booking funnel by enabling conversational trip planning that interprets vague traveler intent and assembles complete itineraries without manual filtering. Younger traveler cohorts in Asia-Pacific markets are adopting these interfaces fastest, abandoning keyword-based search for natural language discovery. This compression is forcing established platforms to reengineer their front-end architectures or cede upstream query capture to AI-native entrants.
The EU AI Act's risk-based classification system is imposing algorithmic audit requirements on personalized recommendation engines used for dynamic fare presentation and itinerary generation. Travel platforms must now maintain technical documentation proving their models avoid manipulative pattern exploitation, particularly for price discrimination sensitive to traveler urgency signals. This regulatory layer is concentrating compliance investment among mid-tier platforms while accelerating partnership strategies with specialized AI governance vendors.
Corporate procurement of travel management services is fragmenting as distributed workforces demand consumer-grade booking experiences within enterprise policy guardrails. Traditional TMC relationships are yielding to platform-agnostic expense tools that embed policy enforcement through API-connected booking rather than pre-approval workflows. This behavioral shift is most pronounced in North American technology and professional services verticals where talent retention depends on traveler autonomy.
Smart Travel Sector Market Segmentation
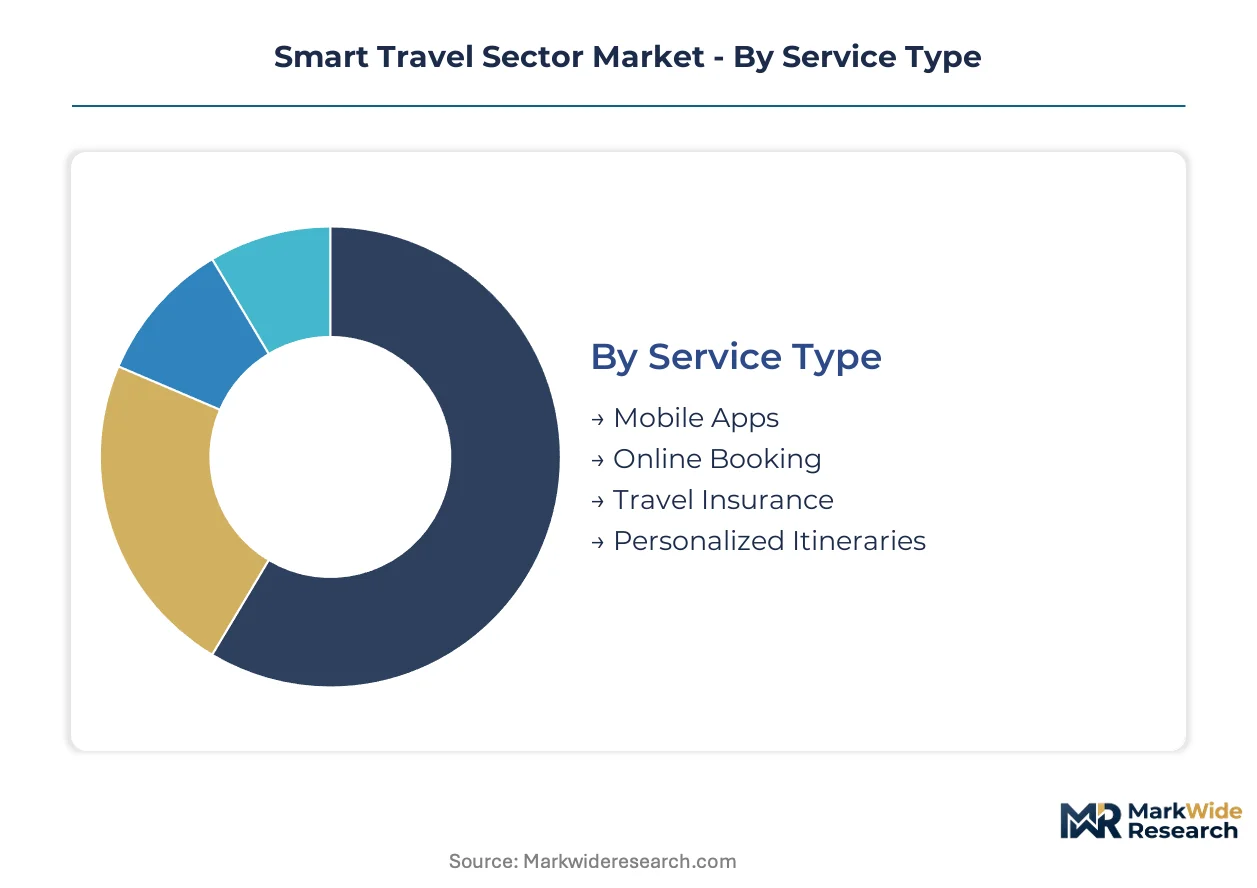
Smart travel platforms engineer distinct service architectures for each customer cohort, matching interface complexity to digital literacy and trip purpose. Technology stacks diverge sharply across segments, with AI commanding premium development budgets while mobile payment infrastructure scales through volume economics.
Service Type:
Cost tier determines feature depth and monetization architecture across service delivery modes.
- Mobile Apps:Native applications integrate biometric authentication, offline itinerary access, and push-notification alerts for gate changes and delays. Demand concentrates among urban professionals in China's tier-1 cities where super-app ecosystems embed transit, accommodation, and payment in single interfaces constrained by MIIT data-localization rules.
- Online Booking:Web-based reservation engines remain the mature revenue core for corporate procurement workflows and complex multi-city itineraries. Procurement teams at multinational enterprises favor these platforms for policy enforcement and centralized expense reconciliation despite supplier direct-channel margin compression.
- Travel Insurance:Embedded protection products attach at checkout through API partnerships with underwriters, capturing ancillary revenue with minimal friction.
- Personalized Itineraries:AI-curated trip assembly services interpret vague traveler intent and optimize for stated preferences around pace, cuisine, and activity intensity.
Online Booking holds installed capacity. Personalized Itineraries is rotating up the share rankings.
Customer Type:
Application context shapes platform interface design and policy engine calibration.
- Business Travelers:Corporate road warriors demand seamless expense integration, pre-trip approval workflows, and duty-of-care location tracking. Demand concentrates in North American technology and professional services verticals where distributed workforces expect consumer-grade booking autonomy within enterprise guardrails.
- Leisure Tourists:Vacation planners prioritize visual discovery, peer review aggregation, and flexible cancellation terms over loyalty currency accumulation.
- Senior Travelers:Accessibility-focused interfaces with enlarged typography, voice navigation, and human-assisted booking support address declining digital dexterity.
- Backpackers:Budget-conscious long-haul travelers optimize for hostel inventory, overland transit connections, and community-sourced safety intelligence.
Business Travelers holds installed capacity. Leisure Tourists is rotating up the share rankings.
Technology:
Volume scale separates infrastructure investments from interface-layer deployments.
- Artificial Intelligence:Natural language processing engines power conversational trip planning and dynamic fare prediction through reinforcement learning on historical booking patterns. EU AI Act compliance mandates are forcing reengineering of recommendation algorithms to demonstrate non-manipulative price presentation.
- Mobile Payment Solutions:QR-code and NFC transaction rails dominate Asia-Pacific markets where UPI in India and Alipay in China collapsed cash dependency among younger cohorts fastest.
- Augmented Reality:Spatial computing overlays deliver real-time translation of signage and immersive pre-trip destination exploration through smartphone cameras.
- Internet of Things:Sensor networks in airports and hotels enable automated check-in, baggage tracking, and environmental preference synchronization.
Artificial Intelligence holds installed capacity. Mobile Payment Solutions is rotating up the share rankings.
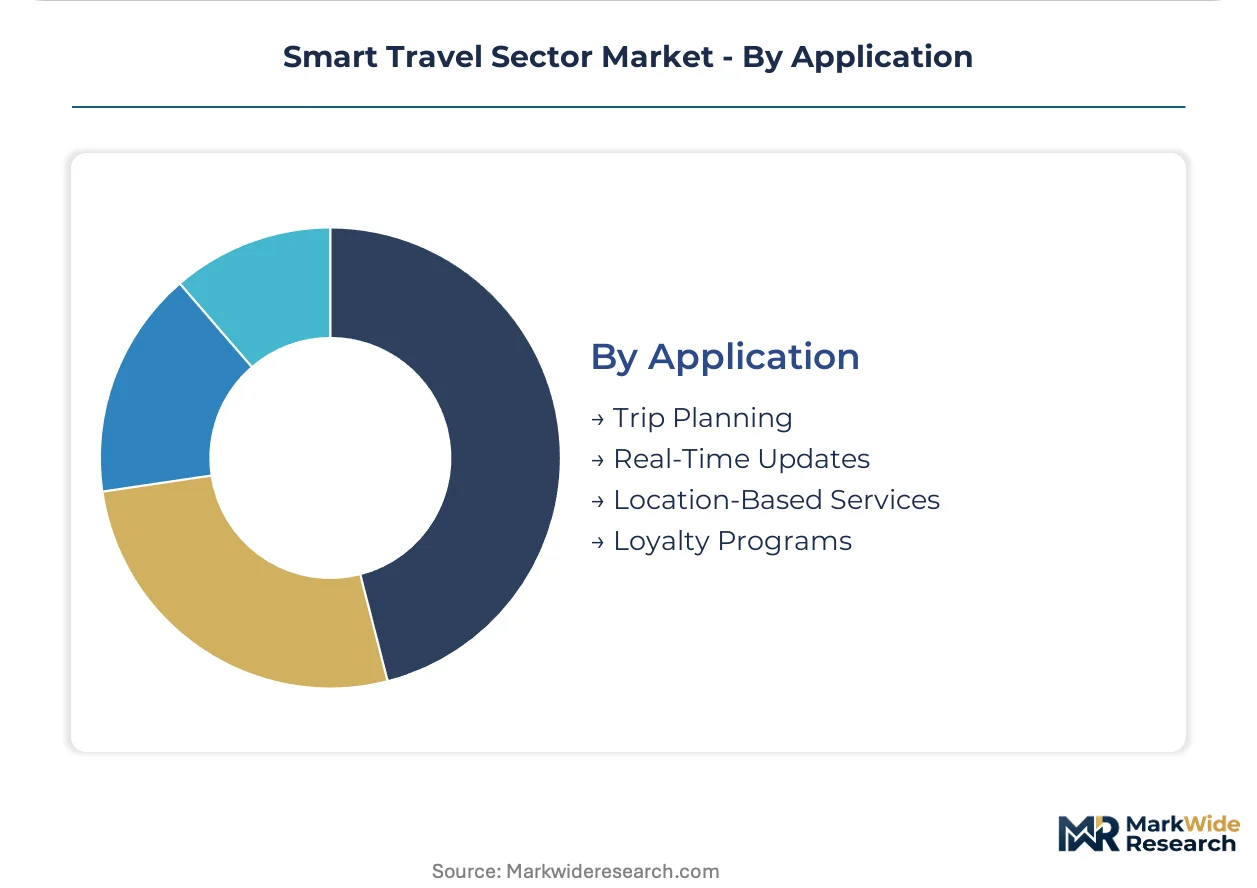
Application:
Customer type determines which utility layer commands engagement frequency and data generation volume.
- Trip Planning:Intent-capture interfaces aggregate fragmented supplier inventory and apply constraint-solving algorithms to optimize for price, duration, or convenience. Leisure Tourists in Asia-Pacific markets are abandoning keyword search fastest for generative planning that assembles complete itineraries from conversational prompts.
- Real-Time Updates:Push-notification systems synchronize flight status, gate changes, and disruption rebooking through GDS and direct airline API connections.
- Location-Based Services:Geofenced recommendations for dining and activities depend on precise GPS permission management constrained by GDPR consent requirements.
- Loyalty Programs:Points accumulation and redemption engines face supplier direct-channel competition as hotel chains and airlines privilege proprietary program exclusivity.
Trip Planning holds installed capacity. Real-Time Updates is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's TEN-T core network corridors and China's Beijing-Shanghai high-speed rail spine anchor continental mobility integration, while India's UPI payment rails and the US NextGen air traffic modernization program reshape traveler utility across distinct regulatory environments.
United States
Corporate travel management platforms and metasearch discovery layers concentrate demand among technology sector road warriors. FAA NextGen implementation and TSA biometric identity verification timelines shape aviation security architecture deployment. Dallas-Fort Worth and Atlanta metropolitan clusters host dominant airline hub operations driving real-time data synchronization requirements.
China
Super-app ecosystems embedding transit, accommodation, and payment in single interfaces capture urban mobility demand fastest. MIIT data-localization rules constrain cross-border passenger data flows for foreign platform operators. Beijing, Shanghai, and Shenzhen urban corridors drive multimodal booking engine integration across rail, ride-hail, and micro-mobility networks.
Germany
Corporate procurement of travel management services fragments as distributed workforces demand consumer-grade booking autonomy. EU AI Act algorithmic transparency mandates force reengineering of recommendation engines for dynamic fare presentation. Munich and Frankfurt metropolitan clusters anchor business travel volume concentration in automotive and financial services verticals.
India
UPI rails and mobile wallet penetration in tier-2 and tier-3 cities create underpenetrated booking volume for localized platforms. RBI payment infrastructure regulations and TRAI data governance frameworks shape platform architecture decisions. Bangalore and Hyderabad technology corridors concentrate demand for API-first corporate travel booking engines.
United Kingdom
Metasearch discovery layers capture query intent upstream of transaction decisions in leisure travel segments. GDPR consent requirements constrain geofenced recommendation engines for location-based services. London metropolitan cluster dominates corporate travel procurement volume across professional services and financial services verticals.
Smart Travel Sector Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying reservation protocols and payment rails. The vendor base organizes around three strategic archetypes: global distribution system operators maintaining legacy airline connectivity, super-app ecosystems embedding multimodal transit, and AI-native entrants collapsing search-to-booking friction. Competitive moves concentrate on embedded fintech service integration and API-first architecture licensing to corporate travel management platforms.
Among US-based technology conglomerates, Google exemplifies metasearch discovery layer dominance capturing query intent upstream of transaction decisions. Within the online travel agency tier, Booking Holdings and Expedia Group occupy positions defined by proprietary property inventory depth and B2B white-label infrastructure respectively. These three anchors represent distinct competitive vectors: upstream intent capture, downstream inventory control, and mid-market platform licensing.
| Leading Market Players |
|---|
| Expedia Group |
| Booking Holdings |
| Sabre Corporation |
| Amadeus IT Group |
| Airbnb |
| Travelport |
| Cubic Transportation Systems |
| China TravelSky Holding |
| Others |
Value Network & Pricing Analysis
Beijing's super-app ecosystem capacity anchors downstream pricing power across multimodal transit integration, compressing margin capture for foreign platform operators constrained by MIIT data-localization compliance costs. Supplier direct-channel incentives from hotel chains and airlines feed back into OTA pricing strategies, forcing continuous platform differentiation to defend revenue per booking.
Pricing Analysis
Volume-discount tiering structures dominate corporate travel management procurement, with multinational enterprises extracting preferential rates through committed annual spend thresholds. Price differentiation rests on loyalty currency accumulation velocity and embedded fintech service bundling rather than base fare transparency. Pricing pressure stems from supplier direct-channel incentives privileging proprietary loyalty program exclusivity. Backpacker segments exhibit highest price sensitivity, while corporate road warriors prioritize policy compliance over marginal cost savings.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for cloud infrastructure deployments serving cross-border passenger data flows. API-first architecture development concentrates in the United States, India, and Germany, drawing from specialized cloud engineering talent pools and open-source middleware components. Single-source vulnerability persists for GDS reservation protocol providers anchoring airline connectivity. Distribution runs through B2B white-label licensing to corporate travel management platforms and direct-to-consumer mobile app storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Travel Sector Market represents a high-growth disruption as generative artificial intelligence collapses legacy search-to-booking architectures, with the EU AI Act's algorithmic transparency mandates forcing immediate compliance investment across recommendation engine stacks.
For Market Incumbents: Build proprietary property inventory moats through exclusive rate agreements with independent hoteliers and vacation rental hosts, insulating against supplier direct-channel encroachment. Invest in auditable machine learning pipelines to satisfy EU AI Act documentation requirements for dynamic fare presentation. Reinforce API interoperability capabilities to maintain connectivity advantage as national digital identity frameworks fragment credential verification protocols. For New Entrants and Emerging Players: India's tier-2 and tier-3 cities present underpenetrated booking volume where UPI rails and mobile wallet penetration outpace platform localization. Target corporate travel management displacement in North American technology verticals where distributed workforces demand consumer-grade booking autonomy within enterprise guardrails. Pursue embedded fintech partnership strategies with buy-now-pay-later providers to capture ancillary revenue streams absent legacy loyalty currency obligations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-native entrants with conversational trip planning capabilities that collapse traditional OTA search architectures. Long-term viability over the projection horizon hinges on regulatory compliance scalability across GDPR, EU AI Act, and emerging national algorithmic governance frameworks. Watch for FDA-equivalent biometric certification timeline acceleration as the signal indicating aviation security identity verification vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Platform Integration | Natural language interfaces from Google reshape upstream query capture before booking decisions. |
| Embedded Fintech Service Launch | Buy-now-pay-later APIs attached at checkout capture ancillary revenue from Asia-Pacific younger cohorts. |
| EU AI Act Compliance Architecture | Auditable machine learning pipelines demonstrate non-manipulative price presentation to European regulators. |
| Corporate Travel Management Partnership | API-connected policy enforcement displaces traditional TMC pre-approval workflows in technology verticals. |
| Multimodal Transit Integration | Real-time synchronization across rail, ride-hail, and micro-mobility captures China's urban mobility corridor demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with platform engineering directors, corporate travel procurement managers, airline distribution strategists, and regulatory compliance officers; and secondary validation through SEC filings from Booking Holdings and Expedia Group, EU AI Act implementation guidance documents, and MIIT data-localization rulemakings. Bottom-up sizing of segment-level booking volumes triangulated against top-down macroeconomic travel demand indicators.
Forecast inputs considered service type segmentation across mobile apps, online booking, and personalized itineraries; customer type dimensions spanning business travelers and leisure tourists; and technology deployment across artificial intelligence and mobile payment solutions. CAGRs were derived through regression analysis on historical adoption curves adjusted for regulatory inflection points. Industry-specific inputs included GDS connectivity evolution timelines and UPI transaction volume growth trajectories across Indian urban tiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native entrants or accelerated EU AI Act enforcement timelines would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market