
 Global Festival Management Software Market | 2026-2036
Global Festival Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Festival Management Software Market Foresight
North America is reconfiguring the competitive terrain for festival management platforms as venues and promoters digitize operations at scale. Eventbrite sustains broad market coverage across independent organizers and mid-tier festivals. Cvent dominates the corporate and large-scale event infrastructure segment with deep workflow integration. Bizzabo differentiates through data-driven engagement tools that tie attendee behavior to sponsor ROI metrics.
Festival management software encompasses cloud-native and on-premises platforms that coordinate ticketing, vendor logistics, crowd flow, scheduling, and real-time analytics for live events, typically integrating RFID access control, mobile payment gateways, and API-connected marketing stacks to reduce operational friction across multi-day programs. Cloud-based deployment leads solution type adoption as organizers prioritize remote accessibility and automatic scaling for surge ticket releases, while hybrid architectures gain traction among European operators navigating data residency requirements. Ticketing and marketing automation capture the largest margin pools due to transaction fee structures and sponsor monetization loops, whereas crowd control modules represent the fastest-growing solution category as safety regulations tighten for mass gatherings.
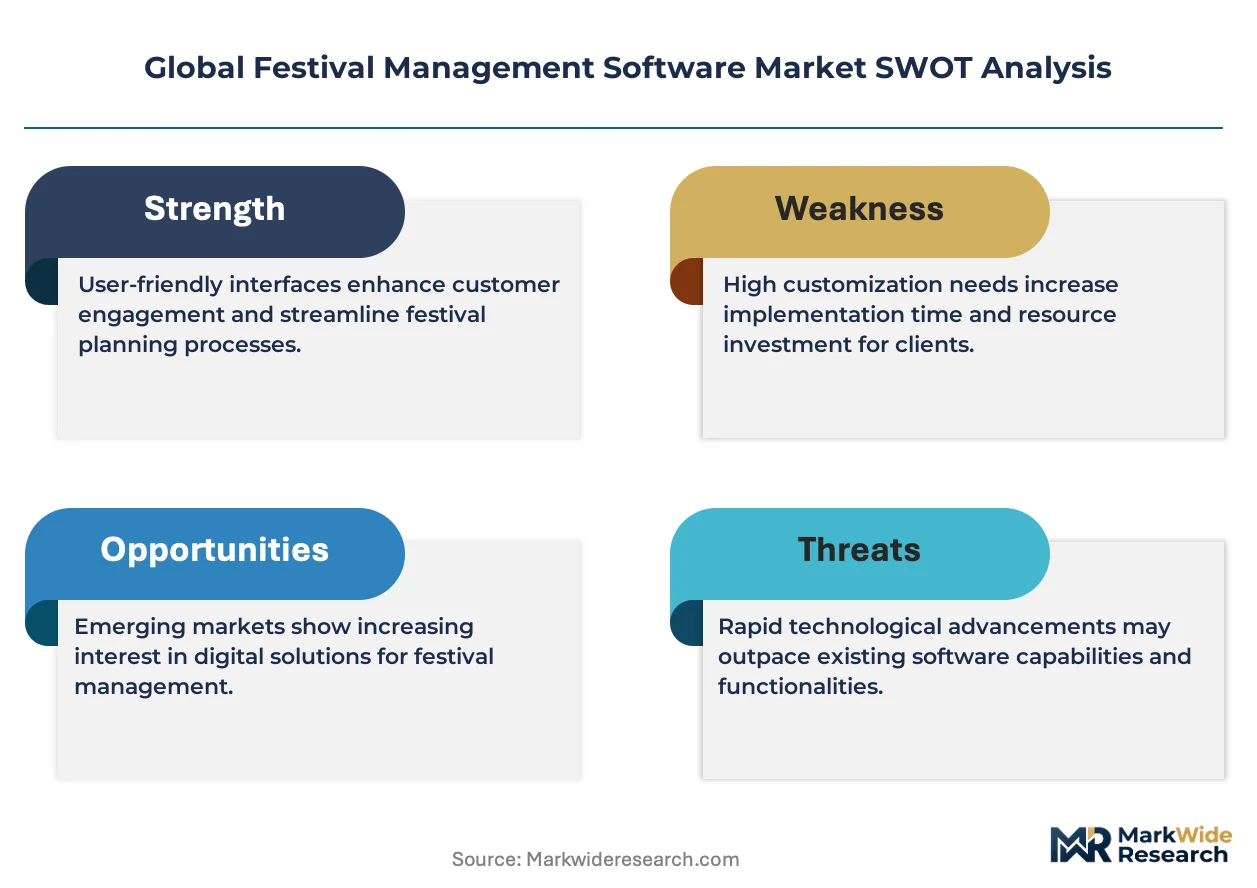
The EU AI Act and GDPR frame algorithmic transparency requirements for attendee profiling and automated marketing in European festival operations, while the US lacks federal data privacy law but sees state-level patchworks like CCPA shaping vendor roadmaps. ISO 27001 certification has become a baseline procurement filter for enterprise event organizers handling payment data and personal information. Stakeholders must weigh regulatory compliance investments against the revenue upside of real-time personalization engines that depend on granular attendee data capture.
Market Dynamics
Cloud-native deployment architectures are compressing the operational cost base for festival organizers while simultaneously exposing them to GDPR enforcement and the EU AI Act's algorithmic transparency mandates. This dual pressure is forcing vendors to rebuild core attendee profiling engines with auditable decision trails.
Growth Catalysts
- Music festival digitization:Large-scale live events now mandate real-time crowd analytics and RFID access control to satisfy insurer requirements and municipal safety permits.
- GDPR compliance tooling:European operators are procuring platforms with built-in data residency controls and automated consent management to avoid regulatory penalties.
- Mobile payment integration:Cashless transaction loops at multi-day programs are driving recurring platform revenue through transaction fee capture.
Market Restraints
- Cloud infrastructure concentration:Festival management platforms depend heavily on hyperscaler availability zones, creating single-point-of-failure exposure during surge ticket releases.
- RFID hardware cost volatility:Wristband and access control module prices fluctuate with semiconductor supply chain constraints.
- Legacy system entrenchment:Established promoters with custom-built ticketing stacks face high switching costs to migrate data archives and retrain operations staff.
Strategic Opportunities
- India festival infrastructure:The country's emerging electronic music and cultural festival circuit lacks integrated vendor logistics platforms, presenting first-mover entry potential.
- ISO 27001 certification:Enterprise event organizers are filtering procurement through this baseline security standard, creating competitive differentiation for certified vendors.
- AI-driven personalization:Converging attendee behavioral data with sponsor ROI metrics is opening premium pricing tiers for platforms that automate matchmaking.
Industry Challenges
- Cybersecurity talent scarcity:Festival platforms require dedicated security operations centers during live events, but qualified personnel command premium compensation in tight labor markets.
- Legacy API integration complexity:Connecting modern cloud-native stacks to entrenched venue management systems and municipal permit databases demands custom engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Festival Management Software Market |
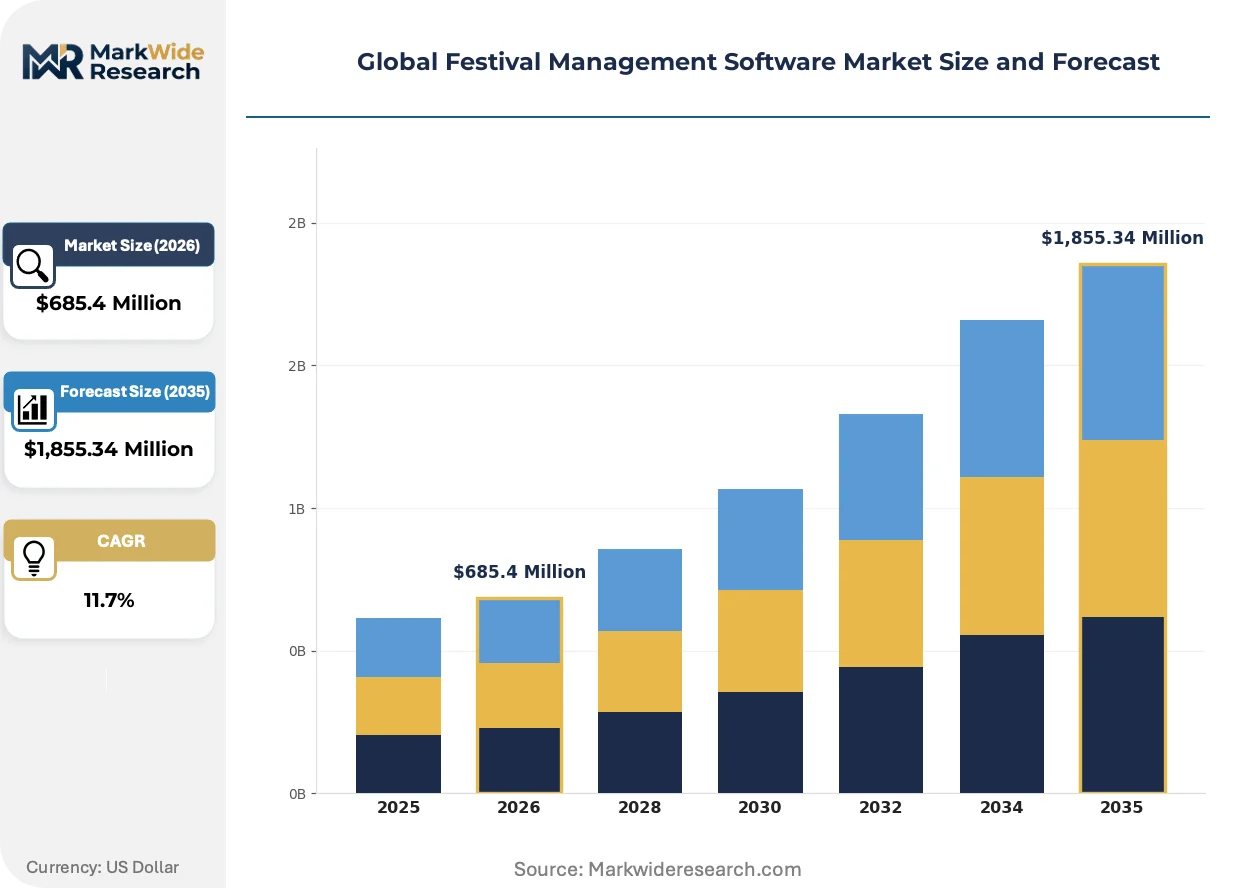
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, SaaS, Private Cloud Solution Type: Ticketing, Vendor Management, Crowd Control, Scheduling, Marketing Automation, Analytics Use Case: Music Events, Art Exhibitions, Food Fairs, Cultural Gatherings, Sports Events, Charity Events End User: Event Organizers, Production Companies, Venue Operators, Sponsors, Government Agencies |
| Companies Covered | Live Nation Entertainment, Inc., Eventbrite, Inc., Cvent, Inc., Bizzabo, Aventri, Inc., Whova, EventMobi, Stova, Momentus Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Festival Management Software Market Shifts & Advancements
Real-time data architectures are replacing batch-processed analytics in live event operations, compressing decision cycles from hours to minutes. This shift is redistributing competitive advantage toward vendors with edge computing capabilities and low-latency infrastructure.
RFID-enabled access control is migrating from static entry validation to dynamic crowd flow orchestration. Mid-tier festival operators in Germany and the Netherlands are adopting these systems fastest, driven by municipal safety mandates. The technology is compressing insurance premium differentials between venues with and without real-time density monitoring.
The EU AI Act's risk classification framework is forcing European festival platforms to document algorithmic logic for attendee recommendation engines and dynamic pricing models. Vendors serving the corporate events segment are rebuilding profiling modules with explainable AI architectures to satisfy auditor scrutiny. This regulatory pressure is spreading to US operators as enterprise clients demand equivalent transparency documentation.
Subscription-based platform access is displacing perpetual license purchases among independent promoters. North American buyers now prioritize operational expenditure predictability over capital-intensive software ownership. This preference shift is most visible in the United States, where Live Nation's vendor consolidation has normalized multi-year SaaS contracting terms across the promoter ecosystem.
Global Festival Management Software Market Segmentation
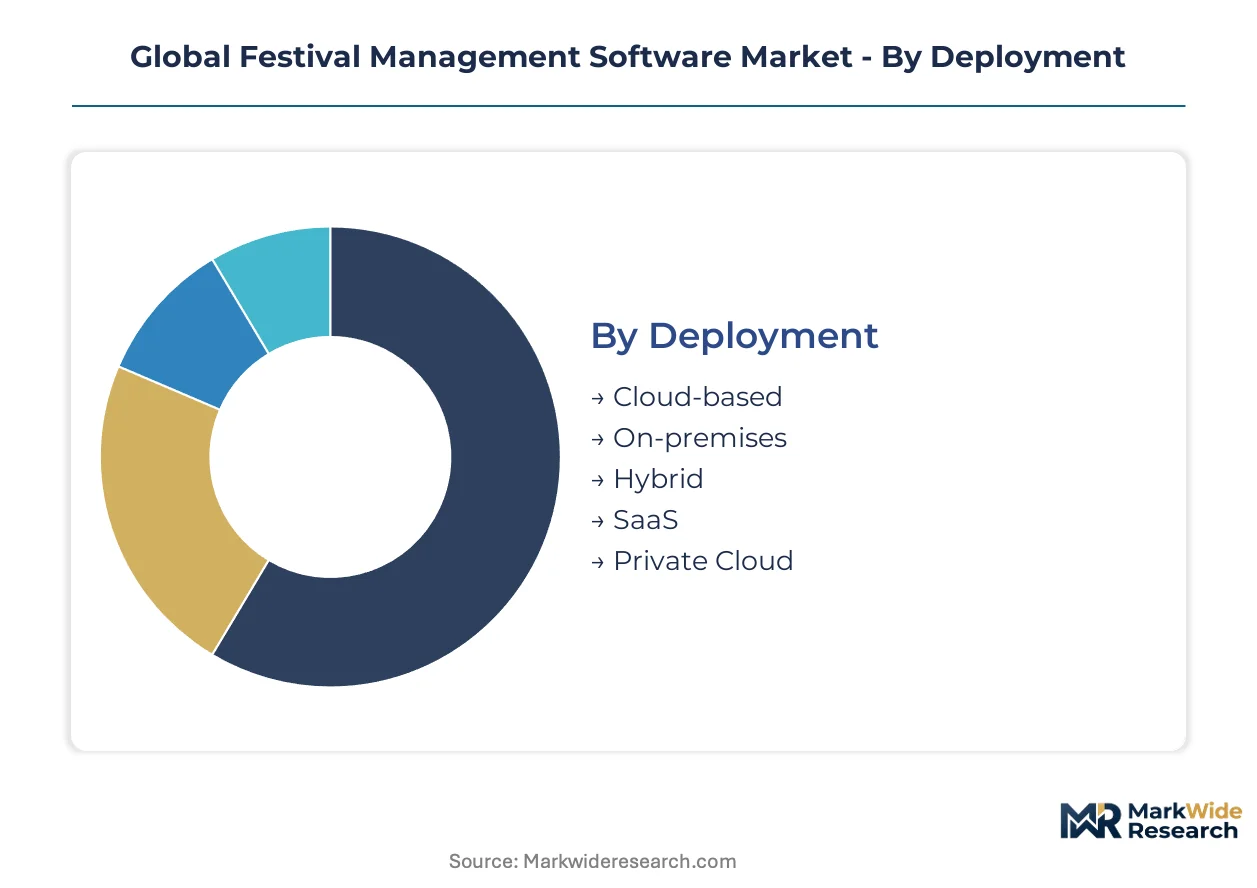
Festival management software segments reflect divergent operational rhythms across deployment cycles, solution refresh rates, and use case seasonality. Procurement patterns vary dramatically between one-time license purchases and recurring SaaS subscriptions, with contract tenures stretching from single-event terms to multi-year enterprise agreements.
Deployment:
Cloud-based deployments turn over fastest as organizers prioritize remote accessibility and automatic scaling for surge ticket releases, while on-premises installations exhibit the longest replacement cycles due to capital amortization schedules and data migration complexity.
- Cloud-based:Multi-tenant architectures with automatic scaling capabilities support remote operations teams and surge traffic handling. Demand concentrates among mid-tier independent promoters in the United States seeking operational expenditure predictability over capital-intensive ownership.
- SaaS:Subscription pricing with tiered feature access reduces upfront procurement barriers for emerging festival operators. European buyers in Germany and the Netherlands favor this model for its built-in GDPR compliance tooling and automated consent management workflows.
- On-premises:Single-tenant installations with direct infrastructure control serve large-scale operators with legacy data residency requirements.
- Hybrid:Split architectures combining cloud front-ends with on-premises data storage address European data sovereignty mandates.
- Private Cloud:Dedicated infrastructure deployments serve enterprise event organizers with ISO 27001 certification requirements.
On-premises systems dominate installed base. SaaS is where expansion concentrates.
Solution Type:
Margin structures diverge sharply across solution categories, with transaction-fee-dependent modules capturing recurring revenue streams while one-time configuration tools face pricing compression.
- Ticketing:Primary transaction engines integrating payment gateways, inventory management, and dynamic pricing algorithms. Demand clusters with Live Nation and AEG Presents in the United States, where per-ticket fee structures generate platform economics at scale.
- Crowd Control:RFID-enabled access validation and real-time density monitoring systems tied to municipal safety permits. German festival operators adopt these fastest due to insurer requirements and local authority mandates for mass gathering documentation.
- Marketing Automation:Email sequencing, social amplification, and retargeting pipelines with sponsor monetization loops.
- Analytics:Behavioral dashboards connecting attendee movement patterns to sponsor ROI metrics.
- Vendor Management:Logistics coordination for food, merchandise, and service contractors across multi-day programs.
- Scheduling:Stage programming and talent coordination tools with mobile app distribution to attendees.
Ticketing commands the largest revenue pool. Crowd Control is climbing the fastest.
Use Case:
Event format determines platform configuration complexity, with multi-day outdoor programs requiring modular orchestration capabilities that single-day indoor gatherings can address with stripped-down toolsets.
- Music Events:Multi-stage programming with RFID cashless payments, dynamic crowd flow management, and real-time artist schedule updates. Electronic music festivals in India represent the steepest expansion trajectory as integrated vendor logistics platforms remain underdeveloped.
- Cultural Gatherings:Multi-generational programming with accessibility compliance and heritage site preservation protocols. Operators in the Netherlands deploy these platforms for municipal permit automation and EU AI Act documentation requirements.
- Food Fairs:Vendor coordination with health inspection documentation and perishable inventory tracking.
- Art Exhibitions:Ticketing with timed entry slots and interactive installation analytics.
- Sports Events:Credential management for athletes, media, and VIP tiers with anti-counterfeiting protocols.
- Charity Events:Donor tracking and tax receipt automation with volunteer coordination modules.
Music Events anchor platform development roadmaps. Cultural Gatherings are gaining share fastest.
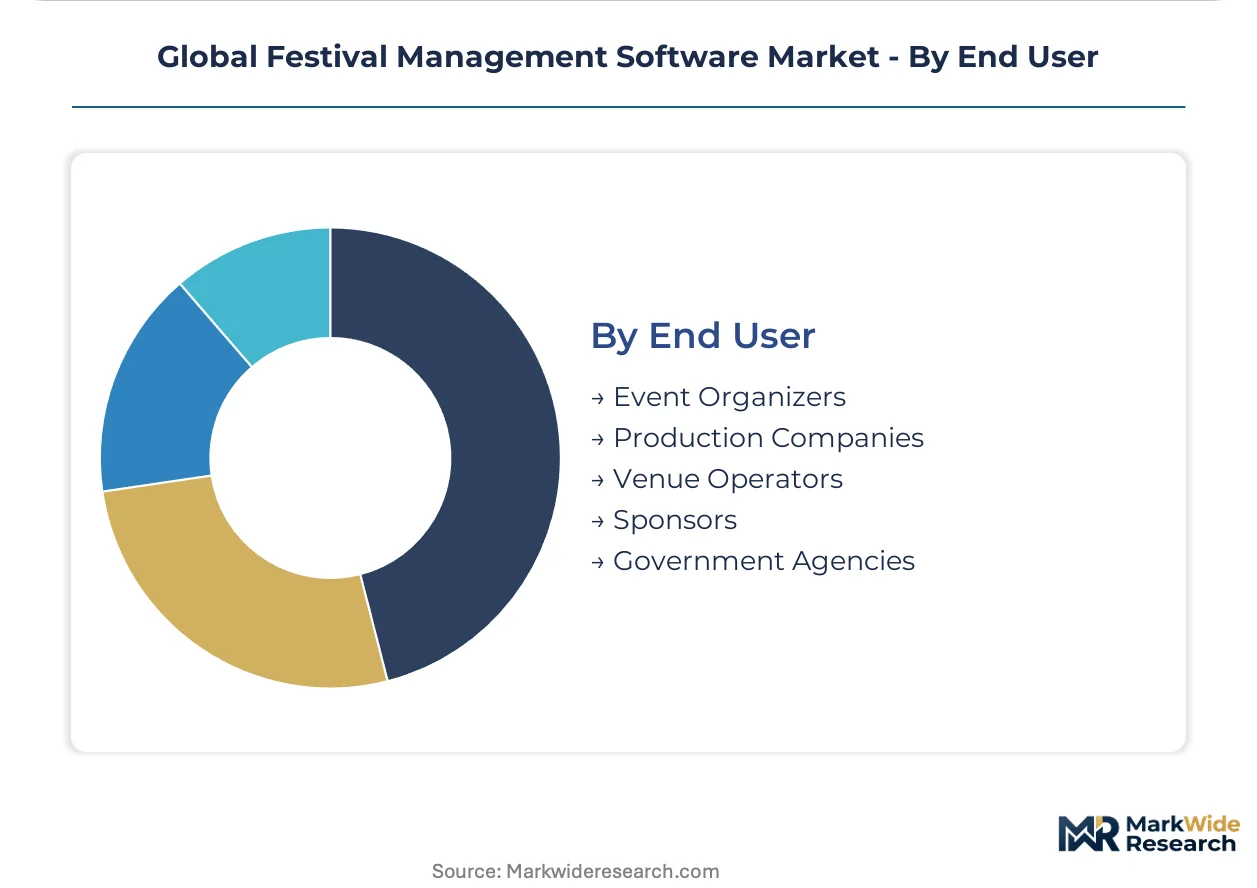
End User:
Buyer sophistication spans from independent promoters with single-event procurement cycles to enterprise organizers with centralized vendor management and multi-year SaaS contracting frameworks.
- Event Organizers:Full-stack platform purchasers coordinating ticketing, marketing, and operations across multi-day programs. Independent promoters in the United States normalize multi-year SaaS terms through Live Nation's vendor consolidation effects.
- Venue Operators:Permanent infrastructure owners requiring municipal permit integration and recurring event calendar management. German operators prioritize ISO 27001-certified platforms for payment data handling.
- Production Companies:Technical service providers subcontracting crowd control and RFID hardware deployment.
- Sponsors:Brand partners accessing attendee behavioral data for ROI measurement and lead capture.
- Government Agencies:Municipal authorities procuring platforms for public safety monitoring and emergency response coordination.
Event Organizers represent the largest addressable base. Venue Operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of payment data security in the United States intersects with state-level privacy frameworks like CCPA to create the most mature procurement environment for festival management platforms. This regulatory density shapes vendor roadmaps worldwide.
United States
Live Nation's vendor consolidation and AEG Presents' platform standardization drive enterprise SaaS adoption at scale. State-level patchworks including CCPA and emerging biometric privacy laws in Illinois and Texas reshape data capture protocols. Los Angeles and Austin anchor the highest concentration of electronic music festivals deploying real-time crowd analytics.
Germany
Municipal safety mandates for mass gatherings and insurer requirements for RFID-enabled density monitoring accelerate crowd control module procurement. The EU AI Act's risk classification framework forces algorithmic transparency documentation for dynamic pricing engines. Berlin and Munich festival operators lead European adoption of hybrid cloud architectures addressing GDPR data residency requirements.
United Kingdom
Independent promoter networks and heritage site cultural festivals generate differentiated demand for accessibility compliance tooling. The Information Commissioner's Office enforces strict attendee consent management for behavioral profiling. London's corporate events sector drives premium pricing for platforms integrating sponsor ROI measurement.
India
Emerging electronic music circuits and untapped vendor logistics integration create first-mover entry opportunities for cloud-native platforms. The country's national data protection authority is drafting localization requirements that will reshape deployment architectures. Maharashtra and Karnataka host the steepest festival infrastructure expansion trajectories.
Netherlands
Municipal permit automation and EU AI Act documentation requirements concentrate demand among cultural gathering operators. The Dutch Data Protection Authority mandates granular consent trails for automated marketing workflows. Amsterdam's festival density drives adoption of real-time crowd flow orchestration systems.
Global Festival Management Software Market Competitive Landscape
Vertically integrated entertainment conglomerates and specialized SaaS vendors split the market into distinct competitive spheres. Consolidation pressure from enterprise procurement frameworks favors vendors with multi-year contracting credibility. Three archetypes dominate: legacy ticketing platforms with payment infrastructure, cloud-native engagement specialists, and venue-integrated operations suites. M&A activity concentrates on data analytics capabilities and geographic footprint expansion.
Within the vertically integrated tier, Live Nation Entertainment, Inc. and Eventbrite, Inc. occupy positions that exemplify divergent scale strategies. Cvent, Inc. anchors the corporate events infrastructure segment with workflow integration depth. These three entities collectively represent the competitive poles around which mid-tier vendors position specialization plays.
| Leading Market Players |
|---|
| Live Nation Entertainment, Inc. |
| Eventbrite, Inc. |
| Cvent, Inc. |
| Bizzabo |
| Aventri, Inc. |
| Whova |
| EventMobi |
| Stova |
| Momentus Technologies |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber optic cable routes anchor cost dynamics for cloud-native festival platforms, compressing margins for vendors dependent on hyperscaler infrastructure while amplifying price differentiation between ISO 27001-certified private cloud tiers and standard multi-tenant SaaS offerings.
Pricing Analysis
Price spreads between German and Indian festival operators exceed threefold for equivalent crowd control modules, reflecting GDPR compliance tooling premiums and localized data residency engineering. SaaS subscription tiers dominate procurement, with ISO 27001 certification and real-time analytics depth as primary differentiation drivers. Cost compression in mid-tier ticketing stems from Eventbrite's transaction fee standardization. Independent promoters in India exhibit highest price sensitivity; enterprise organizers in the United States show least.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates semiconductor procurement risk for RFID wristband manufacturers. Cloud infrastructure concentrates in the United States, Ireland, and Singapore; hardware components source from Taiwan, South Korea, and China. The supply chain rests on NAND flash memory, RF transceivers, and hyperscaler compute capacity. Single-source vulnerability in semiconductor foundries threatens hardware cost stability. Distribution runs through direct vendor partnerships with festival operators and channel integrations with venue management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent festival management platforms face substitution pressure from vertically integrated entertainment conglomerates building proprietary tech stacks in-house, requiring defensive repositioning around data portability moats and multi-year contracting credibility.
For Market Incumbents: Entrench enterprise relationships through ISO 27001 certification investments and captive API development for municipal permit databases. Live Nation's vendor consolidation creates margin compression for standalone SaaS vendors; backward integration into RFID hardware manufacturing defends cost position against supply volatility. Prioritize explainable AI architectures to preempt EU AI Act audit requirements spreading to US enterprise clients.
For New Entrants and Emerging Players: Build out vendor logistics orchestration capabilities targeting India's electronic music festival circuit, where integrated platforms remain underdeveloped. White-space concentrates in mid-tier cultural gatherings across Maharashtra and Karnataka lacking GDPR-compliant cloud-native stacks. Go-to-market through direct partnerships with independent promoters seeking operational expenditure predictability over capital-intensive ownership.
For Investors and Strategic Acquirers: Cloud-native engagement specialists with real-time analytics capabilities represent the highest-conviction acquisition archetype for platform consolidation plays. Long-term viability hinges on data residency engineering expertise and edge computing infrastructure deployment. Watch for hyperscaler availability zone outages during surge ticket releases as inflection indicator for infrastructure resilience premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity to municipal permit databases in Germany and the Netherlands compresses compliance timelines. |
| Acquisition of Specialist Firm | Edge computing vendors with sub-second latency capabilities address real-time crowd flow orchestration requirements. |
| Geographic Expansion | India's emerging festival infrastructure lacks integrated vendor logistics, creating first-mover positioning. |
| Product Launch | Explainable AI modules satisfy EU AI Act documentation mandates spreading to US enterprise procurement. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure ensure surge capacity for Live Nation-scale ticket releases. |
Research Methodology
A standing panel of festival operations directors, CTOs at independent promoter networks, municipal permit officers in Berlin and Amsterdam, and RFID hardware procurement leads provided ongoing calibration. Primary interviews combined with secondary validation against SEC filings of publicly traded entertainment conglomerates, EU regulatory enforcement actions by national data protection authorities, and hyperscaler infrastructure capex disclosures. Bottom-up event volume estimates triangulated against top-down platform revenue analysis.
Scenario-bracketing framed projections across the analysis window, modeling deployment model shifts, organization size tiers, vertical specialization depth, integration complexity levels, and regional adoption patterns. CAGRs derived from segment-level growth rate reconciliation with macro event industry expansion indicators. Forecast inputs incorporated GDPR enforcement intensity trajectories and semiconductor supply chain normalization assumptions.
Practitioners should monitor hyperscaler outage frequency, EU AI Act audit enforcement patterns, and India data localization rule finalization for early signals. Forecasts reflect assumptions about cloud migration velocity and RFID hardware cost stabilization. Material shifts in semiconductor foundry concentration or federal US data privacy legislation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market