
 Travel Technology Market | 2026-2036
Travel Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Technology Market Intelligence
API-first architecture is repositioning legacy distribution economics in travel technology. Sabre Corporation leverages its global distribution system infrastructure to sustain connectivity advantages across airline and hotel inventory. Amadeus anchors its position through hospitality software specialization, while Navan competes by integrating corporate card issuance with real-time expense policy enforcement.
Travel technology encompasses software platforms, connectivity protocols, and data infrastructure that automate reservation workflows, revenue management, and traveler servicing across transportation and accommodation sectors. These systems typically process XML-based messaging at sub-second latency to synchronize inventory, pricing, and customer profiles across fragmented supplier networks. Booking engines and payment systems capture the largest margin pools as they sit at transaction closure points with direct monetization paths. AI Solutions within the technology dimension is expanding fastest as natural language interfaces reduce customer service cost structures for online travel services and concierge platforms.
FDA guidelines on health data portability, EU GDPR requirements for cross-border passenger data transfers, and India's RBI regulations on payment aggregator licensing collectively shape product architecture decisions and market access conditions for platform providers. Stakeholders must monitor how emerging AI governance frameworks in the European Union and data localization mandates across Asia-Pacific jurisdictions will constrain or enable cross-border service delivery models.
Market Dynamics
API-first architecture is compressing legacy distribution economics as real-time inventory synchronization becomes table stakes. Cloud infrastructure investments and AI-driven personalization engines now command the majority of sector R&D allocation.
Growth Catalysts
- EU GDPR cross-border data frameworks:Standardized passenger data protocols reduce compliance fragmentation for multi-jurisdiction platforms, accelerating pan-European product rollouts.
- Corporate card-integrated expense automation:Enterprises in Germany and India are mandating real-time policy enforcement, pulling demand toward unified travel-and-spend platforms.
- Mobile-first booking interfaces:Digital payment integration in the United States is eliminating friction at transaction closure, expanding addressable user bases beyond traditional corporate travel departments.
Market Restraints
- India's RBI payment aggregator licensing:Capital reserve requirements and operational compliance timelines create barriers to entry for fintech-embedded travel platforms.
- Legacy XML messaging infrastructure:Sub-second latency requirements lock incumbents into expensive maintenance cycles while constraining interoperability with modern REST architectures.
- Concentrated cloud infrastructure dependency:hyperscaler concentration in US West Coast data centers introduces geographic resilience risk for real-time booking engines.
Strategic Opportunities
- Natural language interface deployment:AI-powered concierge services reduce customer service cost structures for online travel platforms serving high-volume, low-margin segments.
- EU AI Act governance preparation:Early compliance with emerging algorithmic transparency requirements creates competitive moats against later entrants in European markets.
- Underpenetrated SME corporate travel:Automated expense controls previously reserved for Fortune 500 deployments are now accessible to mid-market enterprises through SaaS delivery models.
Industry Challenges
- Specialized AI/ML engineering talent scarcity:Natural language processing and recommendation system expertise concentrates in technology hubs, inflating compensation costs for platform providers.
- Fragmented supplier network integration:Harmonizing inventory, pricing, and customer profiles across airline, hotel, and ground transport systems demands sustained middleware investment.
- Data localization mandate proliferation:Asia-Pacific jurisdictions are imposing storage requirements that fragment previously unified global data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Technology Market |
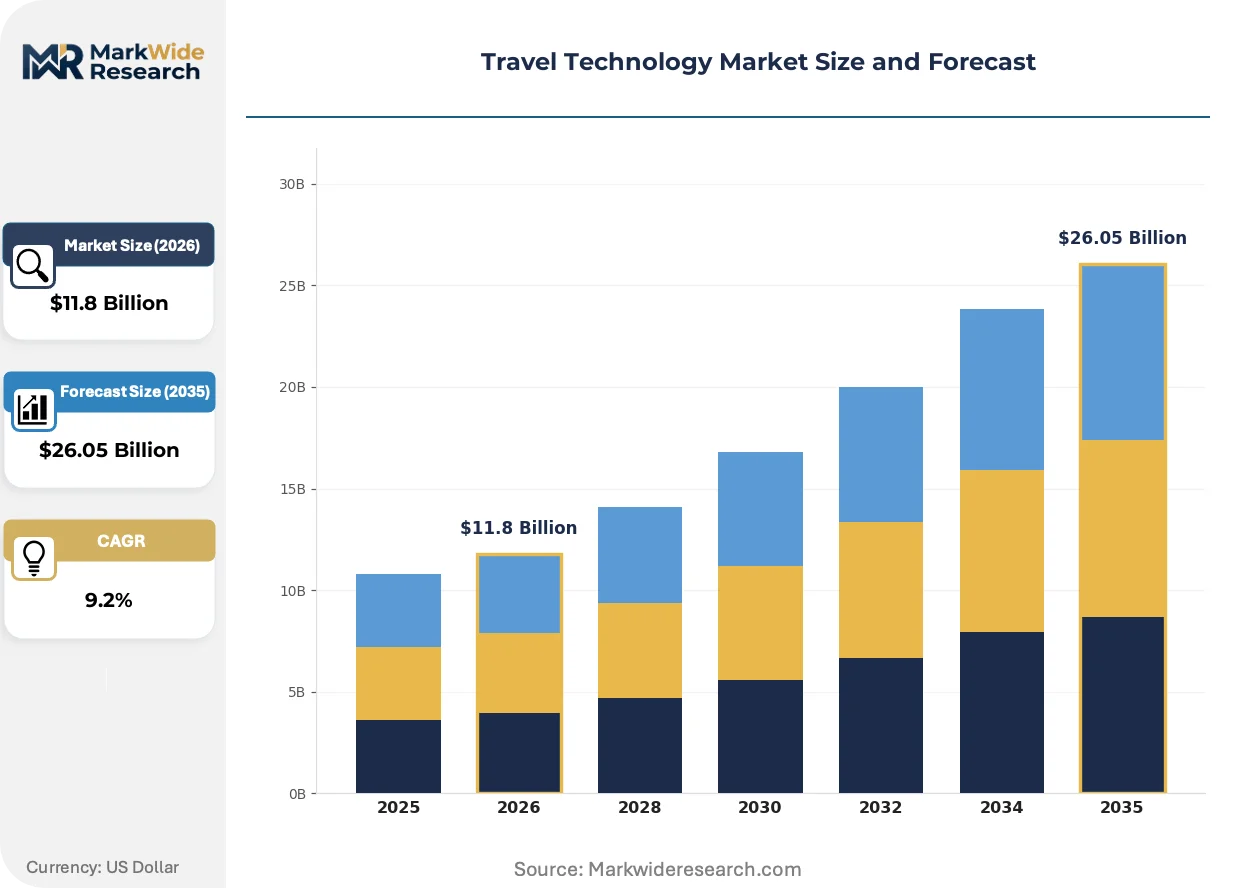
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.05 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Booking Engines, CRM Solutions, Mobile Apps, Payment Systems Customer Type: Travel Agencies, Corporations, Individual Travelers, Tour Operators Service Type: Online Travel Services, Business Travel Management, Vacation Packages, Concierge Services Technology: Cloud Computing, AI Solutions, Big Data Analytics, IoT Devices |
| Companies Covered | TravelPerk, Spotnana, Navan, Mindtrip, TourOptima, Sabre Corporation, Mews, Cloudbeds, Amadeus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Technology Market Strategic Shifts & Innovations
Generative interfaces and embedded finance capabilities are redrawing competitive boundaries between traditional global distribution systems and vertically integrated corporate platforms. Regulatory pressure on algorithmic decision-making is simultaneously creating compliance burdens and differentiation opportunities.
Conversational AI is rewriting customer service economics in travel technology. Natural language interfaces handle itinerary modifications, cancellation requests, and rebooking workflows without human agent intervention. Mid-market online travel agencies are deploying these systems fastest, compressing support cost structures from double-digit to single-digit percentages of revenue. The technology is rewriting the viability threshold for low-margin, high-volume booking segments previously served only through call center infrastructure.
The EU AI Act's risk-based classification system is mandating algorithmic transparency for dynamic pricing and recommendation engines. Travel platforms must document training data provenance and decision logic for audit trails. Corporate travel management tools with embedded personalization are most affected, responding by segregating EU-specific model instances and governance documentation workflows. This regulatory architecture is propagating beyond Europe as Brazil's ANVISA and Japan's METI develop analogous frameworks.
Embedded corporate card issuance is consolidating travel procurement and expense management into unified workflows. Finance departments are displacing separate travel booking and reimbursement systems with real-time policy enforcement at point of sale. This consolidation is most visible in the United States and Germany, where enterprise SaaS adoption rates support integrated platform deployment. The shift compresses vendor relationships from multiple point solutions to single-platform contracts with bundled transaction economics.
Travel Technology Market Segmentation
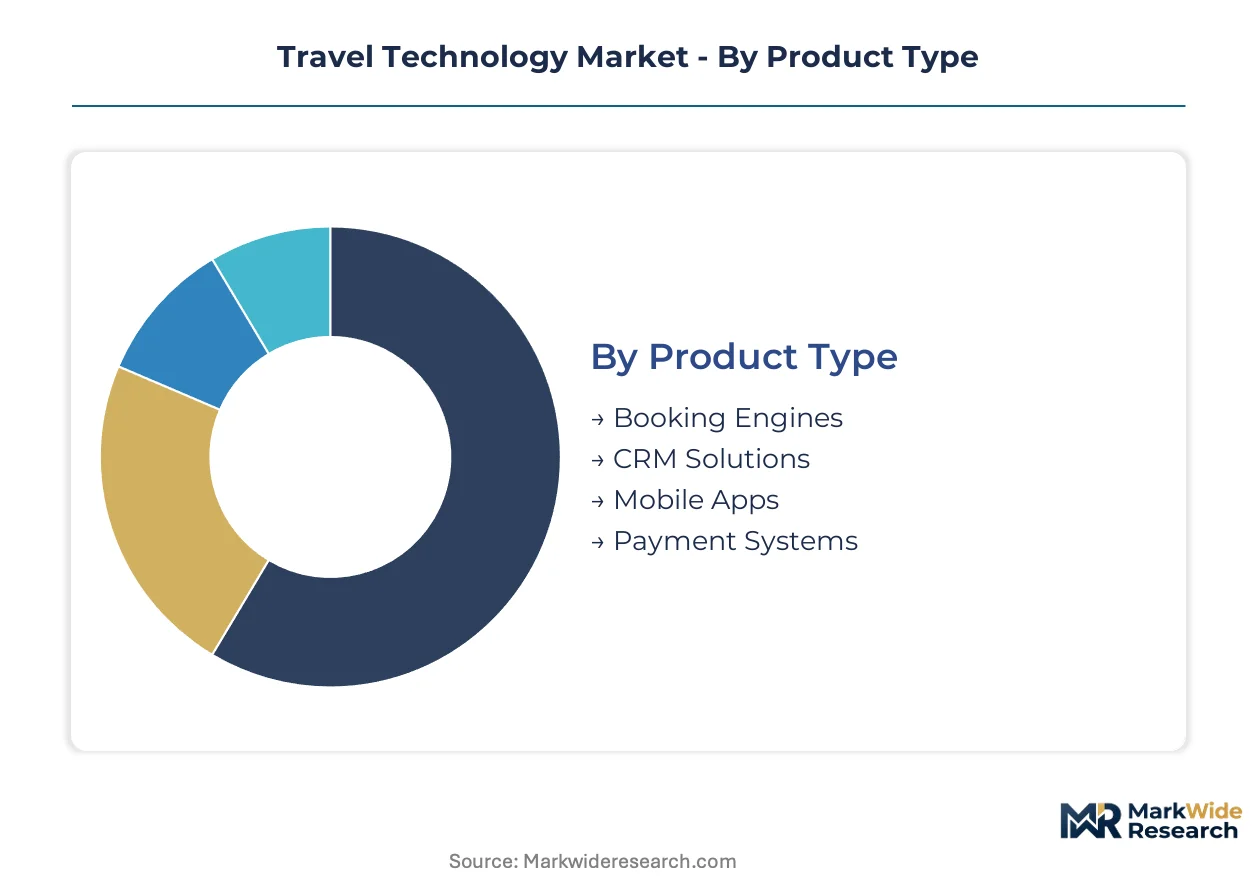
Segmentation in travel technology reveals how platform architecture choices cascade through pricing power, integration complexity, and customer lifetime value. Each dimension exposes different margin structures and competitive moats.
Product Type:
Standardization dominates infrastructure layers while customization concentrates at transaction closure points.
- Booking Engines:XML-based inventory aggregation systems process real-time availability queries across fragmented supplier networks. Corporations in Germany are mandating API-first booking engines with embedded policy enforcement, compressing deployment timelines for legacy middleware replacements.
- Payment Systems:Tokenized transaction processing with multi-currency settlement capabilities sits at the highest margin capture point. RBI licensing requirements in India are concentrating payment system provision among capitalized incumbents, raising barriers for fintech entrants.
- CRM Solutions:Unified traveler profile management with preference learning algorithms.
- Mobile Apps:React Native and Flutter-based interfaces with offline itinerary access.
Leading the category by volume: Booking Engines. Growing fastest: Payment Systems.
Customer Type:
Enterprise procurement cycles stretch 18-24 months while individual acquisition costs compress through app store optimization.
- Corporations:Multi-entity travel programs with negotiated rate access and consolidated billing requirements. United States enterprises are displacing point solutions with unified travel-and-spend platforms, bundling booking, expense, and corporate card issuance.
- Individual Travelers:Price-sensitive leisure booking with high churn and low switching costs. Mobile-first interfaces with digital wallet integration in India are expanding addressable bases beyond traditional online travel agency demographics.
- Travel Agencies:Commission-based intermediaries requiring global distribution system connectivity.
- Tour Operators:Package inventory assembly with block allocation and release management.
Highest revenue per seat: Corporations. Expanding most quickly: Individual Travelers.
Service Type:
Automation depth separates high-touch concierge from self-service commodity booking.
- Business Travel Management:Policy-compliant booking with pre-trip authorization workflows and post-trip expense reconciliation. EU GDPR cross-border data frameworks are enabling pan-European platform rollouts for mid-market enterprises previously served by fragmented national providers.
- Concierge Services:Natural language interface-driven itinerary modification and disruption management. AI-powered concierge deployment is compressing support costs from double-digit to single-digit revenue percentages for online travel platforms.
- Online Travel Services:Self-service leisure booking with dynamic packaging and price comparison.
- Vacation Packages:Bundled inventory with charter flight and ground component integration.
Deepest automation penetration: Business Travel Management. Gaining share fastest: Concierge Services.
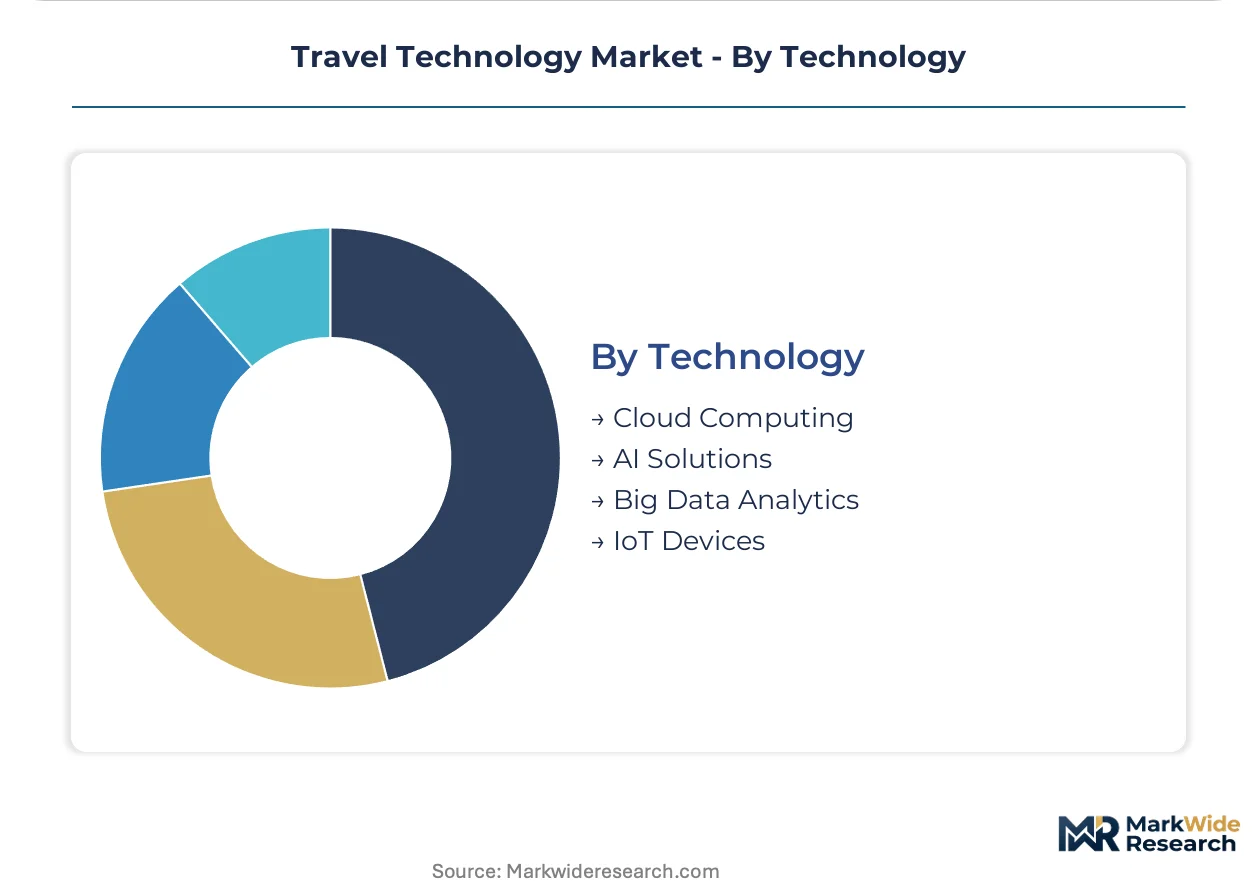
Technology:
Cloud infrastructure commoditizes while AI differentiation commands R&D allocation.
- AI Solutions:Natural language processing for customer service automation and recommendation engines. EU AI Act algorithmic transparency requirements are forcing documentation of training data provenance and decision logic for dynamic pricing systems.
- Cloud Computing:Hyperscaler-hosted reservation systems with auto-scaling for peak load events. Geographic concentration of US West Coast data centers introduces resilience risk for real-time booking engines serving Asia-Pacific markets.
- Big Data Analytics:Demand forecasting and revenue optimization with competitor rate intelligence.
- IoT Devices:Beacon-based airport wayfinding and baggage tracking integration.
Largest current deployment base: Cloud Computing. Steepest expansion trajectory: AI Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement departments in the United States, Germany, and India are driving the steepest platform adoption curves as enterprises mandate unified travel-and-spend workflows. Regulatory divergence across these three markets is forcing product architecture specialization that shapes vendor investment priorities.
United States
Enterprise SaaS procurement cycles are compressing from 24 months to 12 months as CFOs prioritize real-time expense visibility. FAA guidelines on passenger data handling intersect with state-level privacy statutes to create a patchwork compliance environment. San Francisco Bay Area hyperscaler concentration supplies cloud infrastructure for real-time booking engines serving domestic corporate travel programs.
Germany
Mid-market enterprises are displacing fragmented national travel providers with pan-European platforms enabled by GDPR cross-border data frameworks. KBA regulations on commercial transport data retention shape middleware architecture decisions for fleet-integrated booking systems. Munich and Frankfurt financial centers anchor demand for corporate card-integrated expense automation with embedded policy enforcement.
India
Mobile-first booking interfaces with UPI digital wallet integration are expanding addressable user bases beyond traditional corporate travel demographics. RBI payment aggregator licensing requirements with capital reserve mandates are concentrating payment system provision among capitalized incumbents. Bangalore and Hyderabad technology clusters host engineering centers developing AI-driven personalization engines for both domestic and export markets.
United Kingdom
Post-Brexit data adequacy negotiations are forcing platform providers to maintain separate UK-EU data architectures for corporate travel management tools. FCA regulations on embedded finance products govern corporate card issuance integrated with expense platforms. London's financial services concentration sustains demand for high-touch concierge services with natural language interface deployment.
Japan
Corporate travel policy conservatism is slowing SaaS platform adoption relative to Western markets, creating whitespace for hybrid on-premise solutions. METI guidelines on AI governance are mandating documentation standards for recommendation engines in dynamic pricing systems. Tokyo and Osaka metropolitan areas concentrate demand for business travel management with pre-trip authorization workflows and consolidated billing requirements.
Travel Technology Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with infrastructure providers commanding connectivity economics while vertical platforms capture transaction closure margins. The vendor base arranges into three tiers: global distribution system incumbents with legacy XML infrastructure, cloud-native corporate platforms with embedded finance capabilities, and hospitality software specialists with property management system integration. Dominant competitive moves include API-first architecture investments that compress legacy distribution economics, and strategic partnerships between booking engines and payment aggregators to bypass regulatory licensing barriers.
Within the global distribution system tier, Sabre Corporation and Amadeus occupy positions defined by decades of airline and hotel inventory connectivity investment. Navan exemplifies the vertically integrated corporate platform archetype, bundling booking, expense, and card issuance into unified workflows. Among hospitality software specialists, Mews and Cloudbeds represent cloud-native property management system providers competing on API flexibility against legacy on-premise installations.
| Leading Market Players |
|---|
| TravelPerk |
| Spotnana |
| Navan |
| Mindtrip |
| TourOptima |
| Sabre Corporation |
| Mews |
| Cloudbeds |
| Amadeus |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up corporate travel platforms anchor supply-side discipline through consolidated vendor negotiations and unified procurement workflows, compressing margin leakage across fragmented supplier networks while enforcing tiered SaaS pricing tied to transaction volume thresholds.
Pricing Analysis
High-volume transactional tiers sacrifice margin for market share capture while premium enterprise SaaS contracts sustain pricing power through embedded policy enforcement and corporate card integration. Three-tier pricing structure across premium, standard, and economy levels differentiates by customization depth and API access granularity. Cost compression in the mid-market segment is intensifying because cloud-native entrants undercut legacy middleware maintenance fees. Individual travelers exhibit highest price sensitivity through app-based comparison shopping, whereas Fortune 500 procurement departments prioritize total cost of ownership over per-transaction rates.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler concentration in US West Coast data centers, exposing real-time booking engines to geographic resilience risk during peak load events. Cloud infrastructure provisioning draws from the United States, Ireland, and Singapore, while AI/ML engineering talent clusters concentrate in Bangalore, San Francisco, and London. Supply chain risk manifests through regulatory fragmentation as India's RBI licensing requirements and EU GDPR data localization mandates fragment previously unified global architectures. Distribution runs through API-first platform aggregators that bypass traditional global distribution system intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
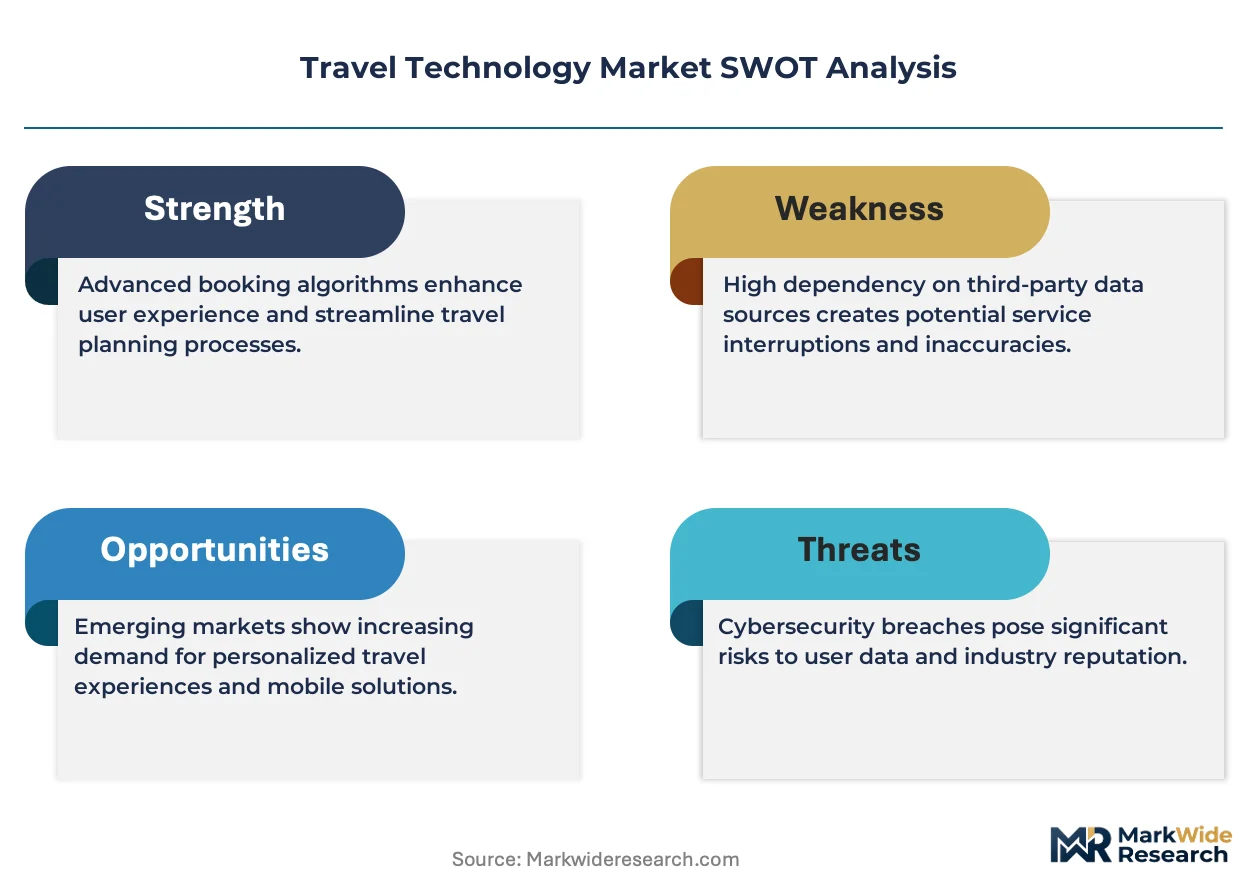
Specialized AI/ML engineering talent scarcity props pricing for automation-enabled platforms, constraining supply expansion faster than demand growth across corporate travel management segments.
For Market Incumbents: Cement API-first architecture advantages through accelerated REST migration away from legacy XML infrastructure, insulating connectivity economics against cloud-native challengers. Deepen vertical integration into payment aggregation capabilities to bypass RBI licensing barriers in India and capture transaction closure margins. Prioritize EU AI Act compliance documentation to create algorithmic transparency moats against later European market entrants. For New Entrants and Emerging Players: Natural language interface deployment offers a technology-first wedge into mid-market online travel agency customer service automation, where incumbent call center cost structures remain vulnerable. Target underpenetrated SME corporate travel segments in Germany and India with SaaS-delivered expense policy enforcement previously reserved for enterprise deployments. Lead with mobile-first UPI integration in India to expand addressable bases beyond traditional corporate demographics. For Investors and Strategic Acquirers: RBI payment aggregator license issuance volume is the leading indicator that embedded finance consolidation is accelerating across Asia-Pacific travel technology markets. Position acquisition screening around cloud-native property management system providers with API flexibility advantages against legacy on-premise installations. Monitor EU AI Act enforcement patterns as the signal for when algorithmic transparency investments transition from compliance burden to competitive differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | REST-based inventory synchronization compresses legacy XML maintenance costs while enabling real-time policy enforcement for German corporate clients. |
| Embedded Corporate Card Issuance | Unified travel-and-spend platforms displace separate booking and reimbursement systems through point-of-sale policy automation in US enterprises. |
| Natural Language Interface Deployment | AI-powered concierge services reduce online travel agency support costs from double-digit to single-digit revenue percentages. |
| EU AI Act Compliance Preparation | Early algorithmic transparency documentation creates competitive moats against later entrants in European dynamic pricing segments. |
| Hyperscaler Geographic Diversification | Multi-region cloud infrastructure deployment mitigates resilience risk from US West Coast data center concentration for Asia-Pacific booking engines. |
Research Approach
Document review covered SEC filings from global distribution system providers, RBI payment aggregator licensing records, EU AI Act regulatory texts, and hyperscaler capex disclosures, complemented by interviews with corporate travel procurement officers, airline distribution strategy leads, hotel chain revenue management executives, and fintech platform engineers. Secondary validation drew from GDS transaction volume reports, SaaS subscription databases, and mobile app analytics. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume assumptions.
Market value and transaction volume outputs across the projection horizon reflect integrated modeling of deployment model, organization size, vertical industry, and regional regulatory cluster segmentation dimensions. CAGRs were derived through trend extrapolation of historical adoption curves adjusted for technology substitution effects. Forecast inputs incorporated cloud infrastructure pricing trajectories and AI/ML talent compensation inflation indices specific to natural language processing and recommendation system engineering.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on data localization mandates, hyperscaler service disruptions from geopolitical conflict, and breakthrough advances in generative AI that obsolete current customer service automation architectures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market