
 Hospitality Point of Sale Software Market | 2026-2036
Hospitality Point of Sale Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hospitality Point of Sale Software Market Insights
Mid-market restaurant chains is collapsing the distinction between legacy on-premise buyers and cloud-native adopters. Toast, Inc. leverages an all-in-one platform architecture to capture franchise operators seeking integrated kitchen display and payroll modules. Oracle Corporation anchors enterprise hotel deployments with property management system interoperability. Square, Inc. competes aggressively on hardware subsidy models for single-location cafés and food trucks.
Hospitality Point of Sale Software constitutes a transaction processing and business operations platform that integrates order capture, payment authorization, inventory tracking, and customer data management through terminal, tablet, or handheld interfaces. Cloud-based deployments lead current growth trajectories by eliminating server maintenance burdens and enabling real-time menu synchronization across dispersed locations. Mobile product types represent the fastest-expanding category as tableside ordering and curbside checkout protocols gain operational priority in full-service restaurants. On-premise installations retain residual demand from high-volume casino and resort operators with stringent latency requirements and captive IT infrastructure.
PCI DSS governs cardholder data environments and compels vendors to maintain certified encryption architectures, directly shaping R&D allocation across the competitive set. GDPR and state-level biometric privacy laws in Illinois and Texas constrain how customer management technology collects and retains facial recognition or fingerprint authentication data. EMV compliance mandates from card networks further dictate terminal hardware refresh cycles and certification timelines. Stakeholders must weigh the trade-off between cloud agility and data sovereignty as jurisdictions introduce sector-specific financial data localization requirements.
Market Dynamics
Cloud migration is compressing hardware refresh cycles while PCI DSS compliance mandates force encryption architecture upgrades across cardholder data environments. Franchise operators now demand real-time synchronization capabilities that legacy server stacks cannot deliver.
Growth Catalysts
- PCI DSS Compliance Mandates:Card data security requirements tighten encryption standards for independent quick-service restaurants. Vendors must certify architectures annually.
- Mobile Product Type Expansion:Tableside ordering and curbside checkout protocols gain operational priority in full-service restaurants. Handheld interfaces reduce labor friction.
- United States Franchise Concentration:Multi-location rollouts drive cloud-based deployment demand. Operators seek centralized menu control across dispersed sites.
Market Restraints
- EMV Terminal Hardware Costs:Card network certification timelines dictate expensive terminal refresh cycles. Small cafés face disproportionate capital burdens.
- Data Localization Requirements:Sector-specific financial data sovereignty laws constrain cross-border cloud architectures. Jurisdictions fragment vendor operating models.
- On-Premise Residual Demand:High-volume casino and resort operators maintain captive IT infrastructure. Latency requirements resist cloud migration.
Strategic Opportunities
- Kitchen Display System Convergence:Integrated payroll and inventory modules create platform stickiness. Mid-market chains seek all-in-one architectures.
- Biometric Authentication Regulatory Tailwinds:Illinois and Texas biometric privacy laws mature into compliance frameworks. Fingerprint payment authorization gains legal clarity.
- Food Truck Segment Penetration:Mobile-first hardware subsidy models target single-location operators. Cellular connectivity replaces fixed-line dependencies.
Industry Challenges
- GDPR Customer Data Complexity:Facial recognition collection and retention rules constrain loyalty program architectures. European operations require separate data handling protocols.
- Legacy Property Management System Integration:Enterprise hotel deployments demand interoperability with existing stack. API standardization lags across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospitality Point of Sale Software Market |
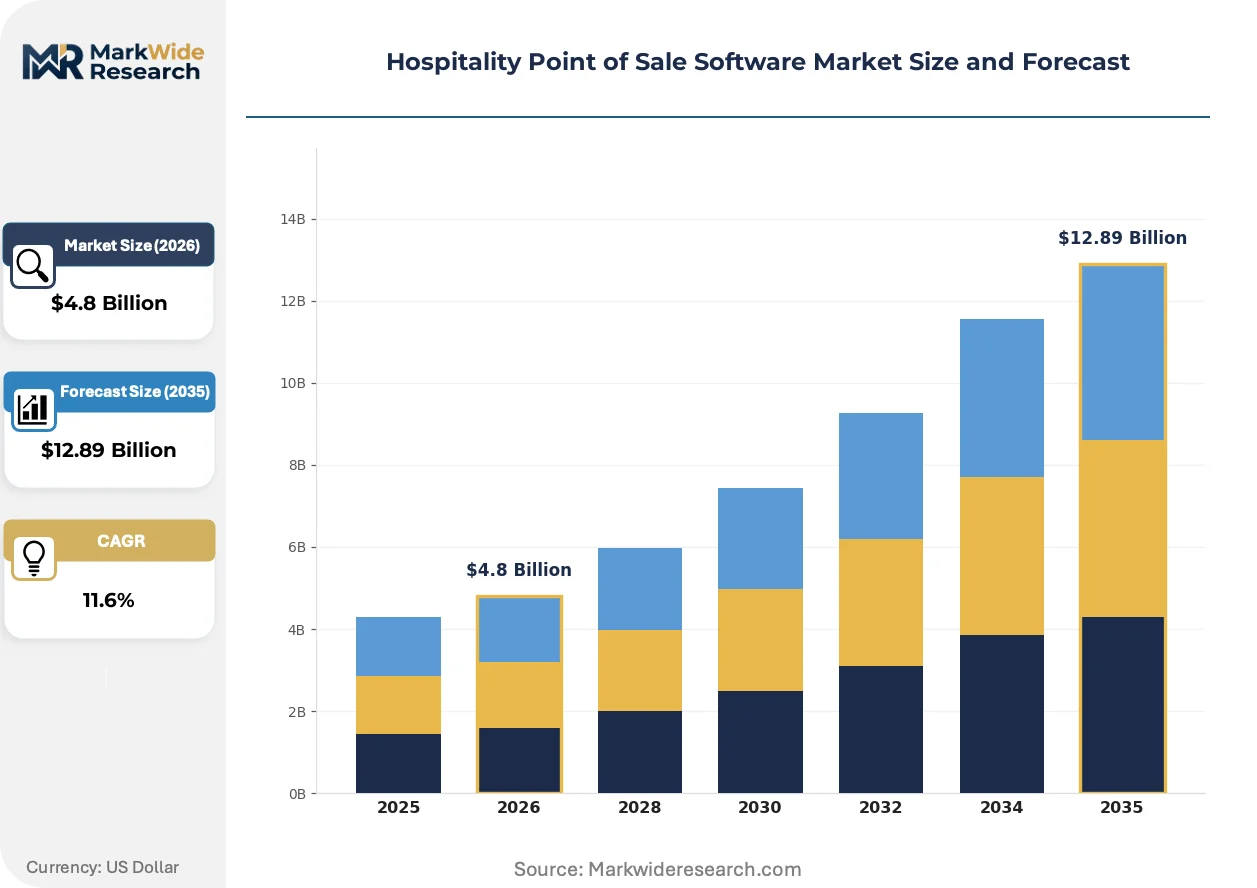
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Mobile, Integrated End User: Restaurants, Hotels, Cafés, Food Trucks Technology: Contactless Payment, EMV Compliance, Inventory Management, Customer Management Deployment Model: Single-Location, Multi-Location, Franchise, Enterprise |
| Companies Covered | Oracle Corporation, Toast, Inc., NCR Corporation, Square, Inc., Lightspeed Commerce Inc., Revel Systems Inc., TouchBistro Inc., Agilysys, Inc., PAR Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospitality Point of Sale Software Market Trends and Innovations
Software-defined payment terminals are fragmenting hardware vendor control while API-first architectures enable third-party module integration. The competitive boundary between POS core and adjacent hospitality software is dissolving.
API-first payment orchestration is decomposing the traditional terminal-hardware stack. Independent software vendors embed card processing into tablet-native applications. The monolithic POS terminal market is fragmenting into componentized services.
GDPR enforcement actions from the CNIL in France and parallel state biometric laws in Illinois are reshaping customer data collection protocols. Facial recognition loyalty programs face consent architecture requirements. Full-service restaurants in regulated jurisdictions are pivoting to opt-in fingerprint authentication.
Franchise procurement committees now mandate cloud-native architecture as a vendor qualification threshold. Legacy on-premise incumbents lose RFP eligibility at multi-location operators. This specification shift concentrates most visible in United States quick-service chain expansion.
Hospitality Point of Sale Software Market Segmentation
Channel mix in hospitality POS software varies sharply by operational scale. Franchise operators route procurement through centralized technology committees, while independent restaurants purchase through distributor networks or direct vendor relationships.
Product Type:
Channel distribution splits between direct enterprise sales for cloud platforms and hardware-bundled resellers for legacy on-premise systems. Mobile solutions increasingly flow through cellular carrier partnerships.
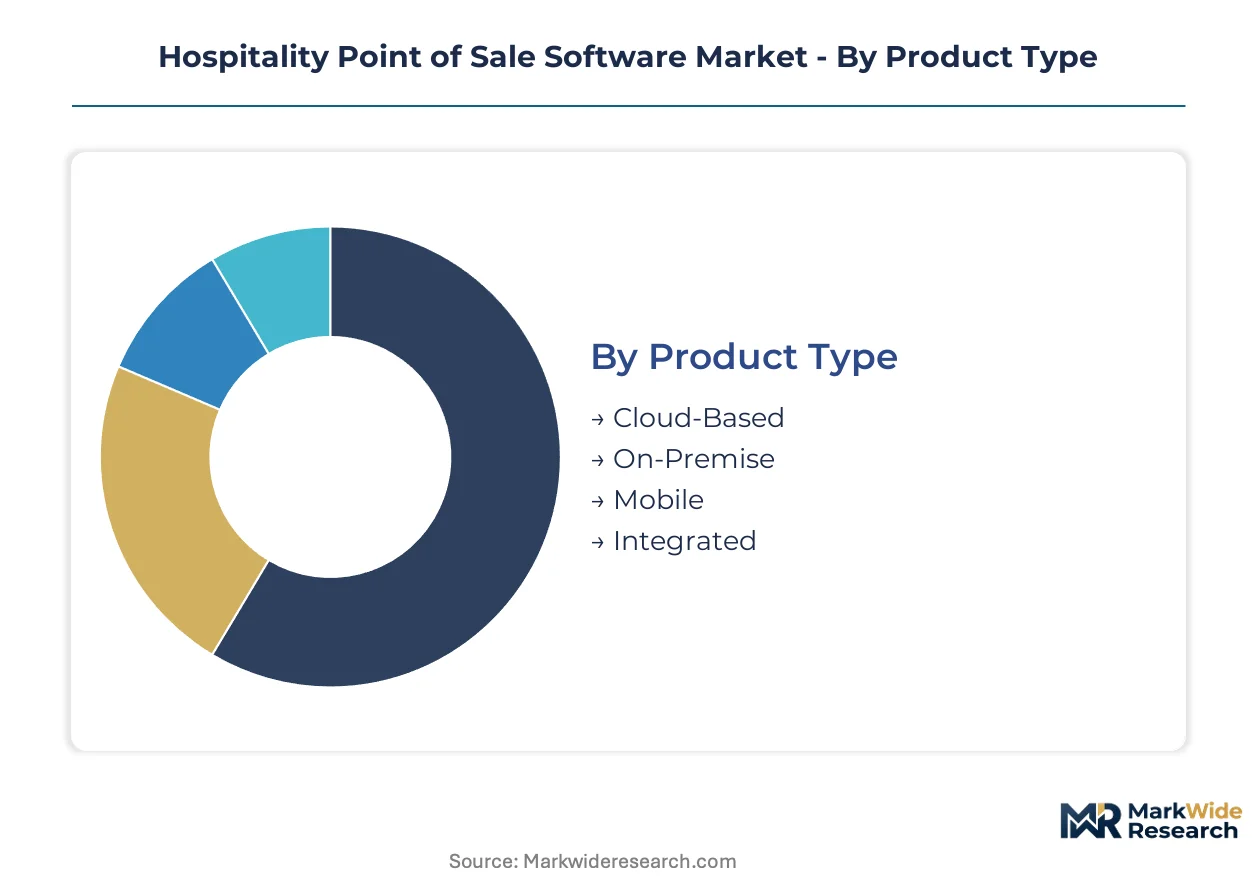
- Cloud-Based:Browser-accessible architectures eliminate local server maintenance. Demand concentrates at United States franchise chains requiring real-time menu synchronization across fifty-plus locations. PCI DSS annual recertification burdens favor vendors with dedicated compliance teams.
- Mobile:Handheld tablets and smartphones enable tableside ordering and curbside checkout. Full-service restaurants in Texas and Illinois deploy these for labor efficiency, though biometric payment integration faces state privacy law constraints. Cellular connectivity replaces fixed-line dependencies for food trucks.
- On-Premise:Local server installations retain demand from casino operators with sub-50ms latency requirements.
- Integrated:All-in-one platforms combining payroll, inventory, and kitchen display systems target mid-market chains.
Cloud-Based dominates installed base. Mobile is where expansion concentrates.
End User:
Cost tier segmentation separates enterprise hotel deployments with property management system integration requirements from single-location operators prioritizing hardware subsidy models.
- Restaurants:Full-service and quick-service operators demand order capture, payment authorization, and kitchen display coordination. United States franchise rollouts drive cloud procurement at multi-location chains. Independent quick-service restaurants face tightening PCI DSS encryption mandates.
- Hotels:Enterprise properties require POS interoperability with existing property management stacks. Oracle Corporation anchors this segment through certified integrations. API standardization lags create implementation friction.
- Cafés:Small-format operators prioritize low terminal costs and simple menu structures.
- Food Trucks:Mobile-first cellular connectivity requirements favor lightweight hardware with offline transaction caching.
Restaurants anchor volume. Hotels command highest per-site software spend.
Technology:
Application-critical features determine R&D allocation, with payment security and customer data management commanding disproportionate engineering resources.
- Contactless Payment:Near-field communication and QR-code protocols reduce physical card handling. Post-pandemic operational protocols in full-service restaurants prioritize these interfaces for speed-of-service metrics.
- EMV Compliance:Chip-card certification mandates from card networks dictate terminal hardware refresh cycles. Small cafés face disproportionate capital burdens from three-year recertification timelines.
- Inventory Management:Real-time ingredient tracking integrates with supplier ordering portals. Mid-market chains seek automated par-level alerts.
- Customer Management:Loyalty program architectures face GDPR consent requirements in European operations and Illinois biometric privacy constraints for facial recognition.
EMV Compliance saturates new deployments. Contactless Payment is climbing the fastest.
Deployment Model:
Customer type segmentation maps directly to procurement complexity, from single-location credit-card purchases to enterprise RFP processes with eighteen-month sales cycles.
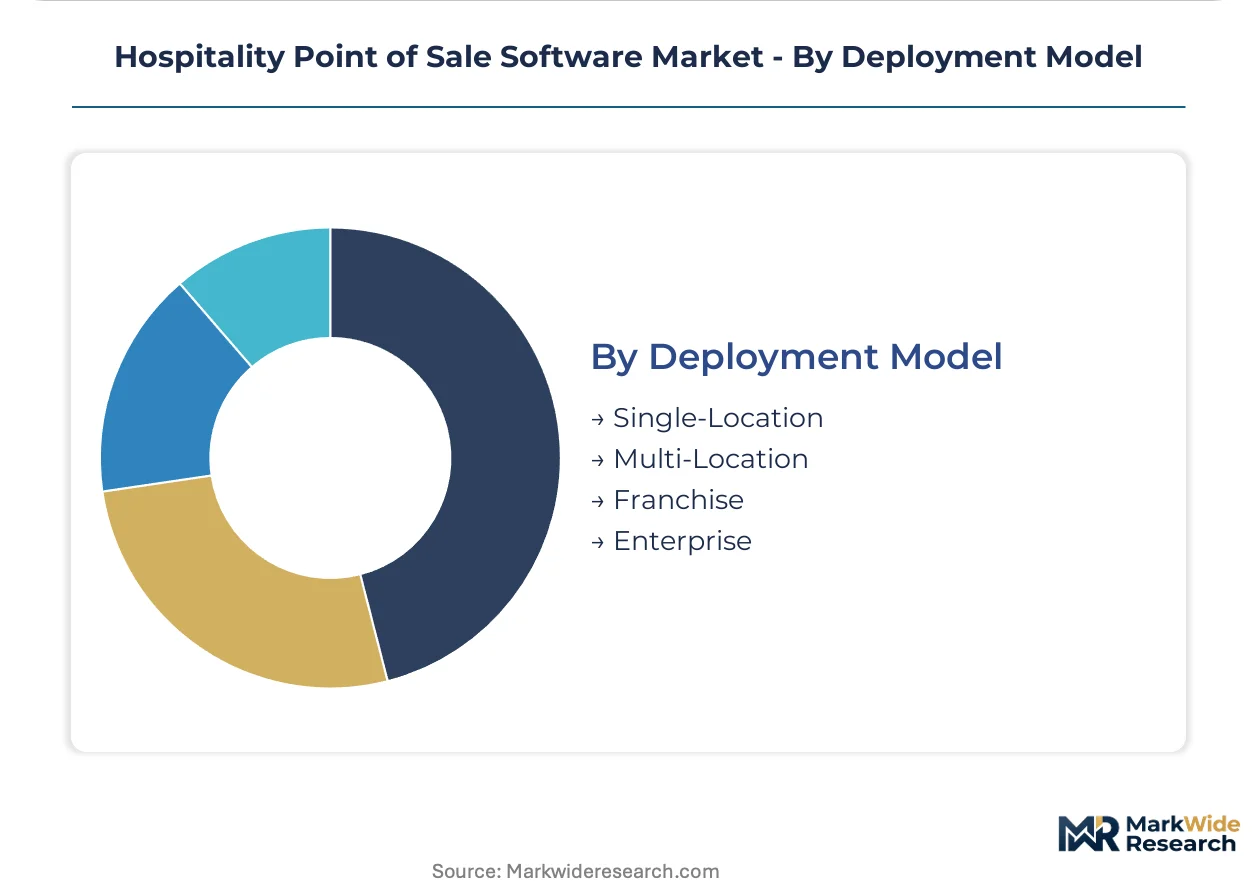
- Multi-Location:Regional chains with five to fifty sites demand centralized reporting and menu control. Cloud-native architecture has become a vendor qualification threshold in United States RFPs. Legacy on-premise incumbents lose eligibility.
- Franchise:Corporate technology committees mandate uniform stack across franchisee bases. Real-time synchronization capabilities separate qualified vendors from disqualified legacy platforms.
- Single-Location:Independent operators purchase through distributor channels with hardware subsidy sensitivity.
- Enterprise:Casino and resort operators maintain captive IT infrastructure with stringent latency requirements resisting cloud migration.
Multi-Location captures majority of new cloud contracts. Franchise represents steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate fiber backbone and major cloud availability zones in Virginia, Oregon, and Ohio underpin North American dominance in hospitality POS infrastructure deployment.
United States
Franchise operators in quick-service chains drive multi-location cloud rollouts requiring real-time menu synchronization. The FTC enforces data breach notification standards affecting customer management module architectures. Texas and Illinois cluster food truck deployments where cellular connectivity replaces fixed-line dependencies.
Germany
Mid-market hotel chains demand property management system interoperability from POS vendors. The ECHA administers REACH compliance for hardware component materials in terminal manufacturing. Bavaria anchors enterprise hospitality software development with Munich-based systems integrators.
United Kingdom
Full-service restaurants prioritize contactless payment protocols for post-pandemic speed-of-service metrics. The FCA oversees open banking regulations shaping payment orchestration API standards. London concentrates fintech-POS convergence activity with Shoreditch-based software vendors.
Japan
High-volume casino operators in integrated resorts maintain on-premise installations with sub-50ms latency requirements. METI promotes cashless payment adoption through subsidy programs affecting terminal hardware refresh cycles. Osaka-Kansai corridor hosts specialized hospitality technology distributors.
Australia
Independent cafés and small-format operators seek low-terminal-cost solutions with simple menu structures. The ACCC monitors payment system access regulations affecting processor competition. Sydney and Melbourne cluster cloud-native POS adoption among coastal restaurant chains.
Hospitality Point of Sale Software Market Competitive Landscape
Listed leaders compete with private specialists across platform integration depth, creating a tiered structure where scale advantages concentrate in cloud-native architectures. Enterprise hotel deployments favor vendors with certified property management interoperability. Franchise procurement committees now mandate cloud-native qualifications, disqualifying legacy on-premise incumbents from multi-location RFPs. Dominant competitive moves include strategic partnerships for kitchen display system convergence and portfolio diversification into payroll and inventory modules.
Within the platform-integration tier, Oracle Corporation exemplifies enterprise-grade property management interoperability, while Toast, Inc. occupies a position representing all-in-one architecture for mid-market chains. Square, Inc. anchors the hardware-subsidy model for single-location operators. These three entities collectively illustrate the competitive segmentation between enterprise, mid-market, and small-format deployment strategies.
| Leading Market Players |
|---|
| Oracle Corporation |
| Toast, Inc. |
| NCR Corporation |
| Square, Inc. |
| Lightspeed Commerce Inc. |
| Revel Systems Inc. |
| TouchBistro Inc. |
| Agilysys, Inc. |
| PAR Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with cloud infrastructure providers lock in both compute access and predictable SaaS pricing for multi-location franchise operators. These arrangements insulate vendors from spot-market volatility in data center capacity while giving buyers multi-year cost visibility across dispersed site rollouts.
Pricing Analysis
Volume-discount tiering structures separate enterprise hotel deployments from single-location food truck operators. Three-tier pricing stratifies across premium all-in-one platforms, standard cloud-native subscriptions, and economy hardware-subsidized bundles. Price differentiation hinges on integration depth and PCI DSS certification level. Pricing pressure stems from hardware subsidy competition targeting independent cafés. Single-location operators exhibit highest price sensitivity; enterprise casino operators prioritize latency guarantees over cost.
Supply Chain Analysis
China and Taiwan anchor semiconductor fabrication for payment terminal chipsets. Mexico and Vietnam feed assembly operations for handheld hardware units. The supply chain draws from rare earth elements for magnetic stripe readers and lithium-ion cells for mobile device batteries. Single-source vulnerability concentrates in EMV certification chip supply. Distribution runs through cellular carrier partnerships for mobile POS and direct enterprise sales for cloud platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where API-first architectures dissolve the boundary between core POS and adjacent hospitality software. Kitchen display system convergence exemplifies the interoperability shift consolidating vendor control over operational workflows.
For Market Incumbents: Fortify cloud-native architecture investments to maintain RFP eligibility at franchise procurement committees. Deepen backward integration into payment processing rails to capture margin from transaction volume. The disqualification threat from legacy on-premise incumbents losing multi-location contracts demands defensive certification acceleration in PCI DSS and EMV compliance. For New Entrants and Emerging Players: Food truck segment hardware gaps offer white-space penetration where cellular-first connectivity remains underserved by incumbent fixed-line dependencies. Biometric authentication modules for Illinois and Texas operators present a compliance-matured entry point. A hardware subsidy model with offline transaction caching addresses the most penetrable mobility requirements. For Investors and Strategic Acquirers: Cloud-native mid-market specialists with kitchen display integration capabilities represent the acquisition target archetype most exposed to franchise rollout expansion. Long-term viability hinges on platform stickiness through payroll and inventory module adjacencies. Watch for PCI DSS recertification failures among legacy vendors as an inflection signal indicating distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures embed POS into broader operational stacks at mid-market chains. |
| Acquisition of Specialist Firm | Kitchen display system vendors extend platform control over back-of-house workflows. |
| Geographic Expansion | Cellular carrier partnerships unlock food truck penetration in Texas and Illinois corridors. |
| Strategic Partnership | Property management system interoperability secures enterprise hotel procurement cycles. |
| Product Launch | Biometric payment modules navigate Illinois and Texas privacy law compliance frameworks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with franchise technology committees, POS vendor product managers, and hotel IT procurement officers; and secondary validation against PCI DSS certification databases, EMV terminal approval registries, and hyperscaler cloud availability zone disclosures. Bottom-up triangulation across deployment model adoption patterns and top-down reconciliation with hospitality sector technology spend estimates anchored value projections.
Across the analysis window, forecasts modeled deployment model, end-user scale tier, integration complexity, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion trajectories. Cloud migration velocity at multi-location chains and EMV hardware refresh cycle timing served as hospitality-specific forecast inputs.
Forecasts assume regulatory continuity in PCI DSS, GDPR, and Illinois biometric privacy regimes; material policy shifts would require re-modeling encryption architecture compliance costs or customer data handling protocols. Recalibration cycles align with material shifts in franchise procurement committee specifications or card network certification mandate announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market