
 South Africa Hospitality Point of Sale Software Market | 2026-2036
South Africa Hospitality Point of Sale Software Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Hospitality Point of Sale Software Market Intelligence
Hotel and resort chains are broadening their share of the hospitality POS software buyer base alongside traditional restaurants. Oracle Hospitality leverages its enterprise-grade property management integration to anchor large resort deployments. NCR Voyix Corporation competes across mid-market restaurant chains with modular hardware-software bundles. iKhokha differentiates through mobile-first POS tools tailored to informal township eateries and cash-dominant operations.
South Africa hospitality point of sale software encompasses transaction processing, inventory tracking, and customer relationship management systems deployed via cloud servers, local terminals, or mobile devices, typically integrating with payment gateways that support EMV chip authentication and NFC tap-to-pay protocols. Cloud-based deployments lead segment expansion as load-shedding resilience and remote management capabilities reduce dependency on fixed-site infrastructure. Tablet-based terminals represent the fastest-growing hardware form factor, particularly in Cape Town's high-turnover casual dining sector where space constraints favor compact, flexible setups. Contactless payment technology adoption concentrates margin pools among vendors bundling QR code ordering with integrated settlement rails.
The Protection of Personal Information Act and the Financial Sector Conduct Authority's payment system oversight jointly elevate compliance burdens for vendors handling cardholder data and consumer information. The South African Reserve Bank's National Payment System Framework shapes interoperability requirements between POS platforms and domestic banking networks. Stakeholders must monitor evolving data localization mandates and payment system licensing rules that could restrict cross-border cloud hosting arrangements.
Market Dynamics
The Protection of Personal Information Act (POPIA) is compressing vendor selection timelines as hospitality operators scramble to certify compliant data-handling systems before procurement cycles close. Load-shedding resilience has emerged as a non-negotiable technical specification, redirecting demand toward cloud-hybrid architectures that maintain transaction continuity during power interruptions.
Growth Catalysts
- EMV chip authentication mandates:The South African Reserve Bank's National Payment System Framework requires upgraded terminal infrastructure, forcing hospitality operators to replace legacy swipe-only devices. This regulatory pressure accelerates hardware refresh cycles across full-service restaurants and hotel chains.
- Township informal economy formalization:Mobile-first POS tools are penetrating cash-dominant operations in Gauteng's informal dining sector, converting unrecorded transactions into trackable digital revenue streams for tax and inventory purposes.
- Cape Town tourism corridor expansion:High-turnover casual dining establishments along the Atlantic seaboard are driving demand for compact tablet-based terminals that accommodate space-constrained floor plans.
Market Restraints
- Load-shedding infrastructure costs:Backup power systems and redundant connectivity layers add capital intensity to POS deployments, squeezing margins for mid-market restaurant operators already facing compressed food cost ratios.
- Data localization uncertainty:Potential cross-border cloud hosting restrictions under evolving financial sector oversight create compliance ambiguity, delaying procurement decisions among risk-averse hotel chains.
- Legacy system integration friction:Property management systems and kitchen display hardware from prior technology generations resist seamless API connectivity, extending implementation timelines and inflating professional services costs.
Strategic Opportunities
- Western Cape wine route penetration:Estate restaurants and tasting rooms outside Cape Town's urban core remain underserved by integrated inventory-payment platforms, presenting white space for specialized vendor expansion.
- QR code ordering convergence:The fusion of contactless payment rails with tableside digital menus is creating new margin pools for vendors bundling settlement infrastructure with customer-facing interfaces.
- Financial Sector Conduct Authority licensing tailwinds:Payment system operator licensing requirements are raising barriers for unqualified competitors, concentrating market share among established compliant vendors.
Industry Challenges
- Certification timeline compression:POPIA compliance audits and payment system licensing approvals are creating bottlenecks, stretching vendor onboarding periods and delaying revenue recognition.
- Integration complexity with kitchen hardware:Synchronizing cloud-based POS platforms with legacy kitchen display systems and thermal printers requires custom middleware development, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Hospitality Point of Sale Software Market |
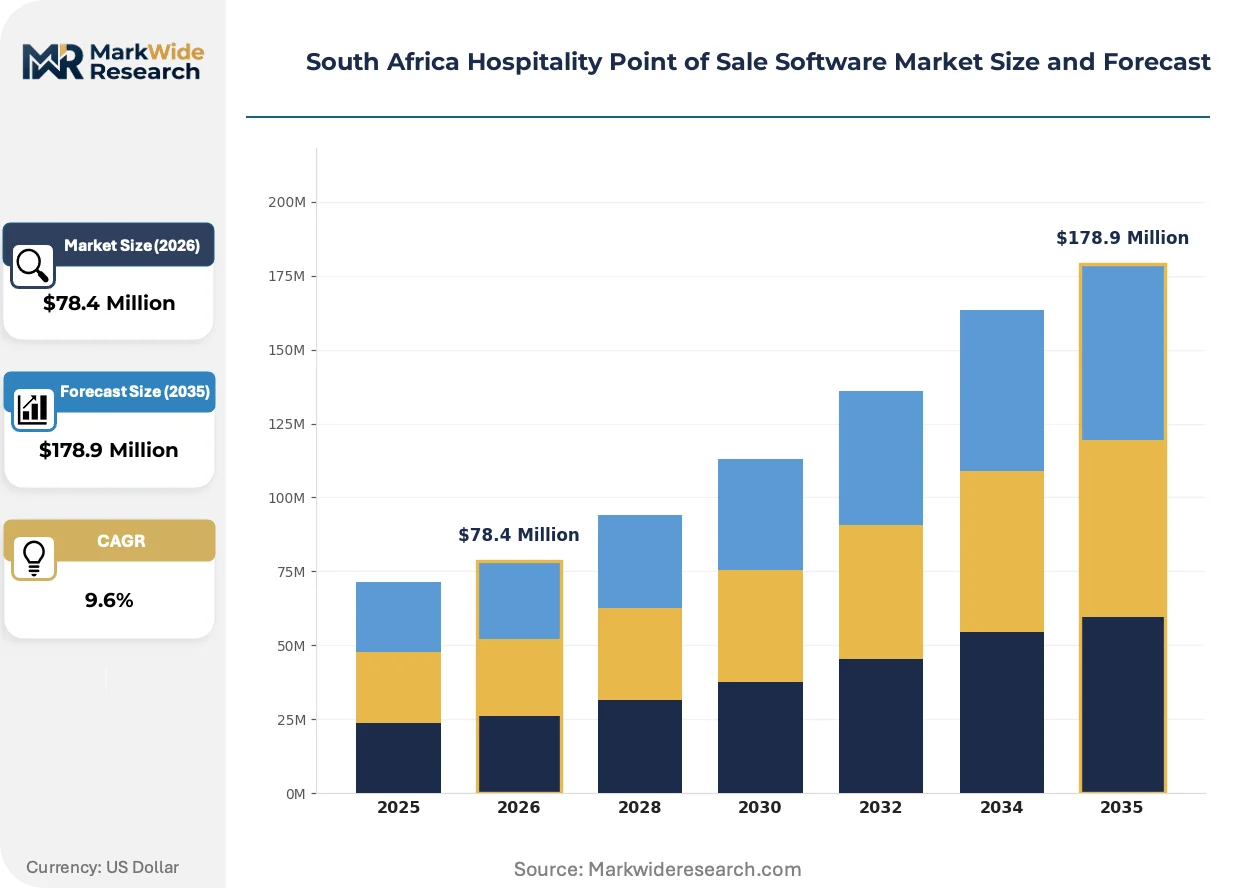
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $178.9 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Mobile, Tablet End User: Restaurants, Bars, Cafes, Hotels Technology: Contactless Payments, NFC, QR Code, EMV Service Type: Maintenance, Support, Installation, Upgradation |
| Companies Covered | Oracle Hospitality, NCR Voyix Corporation, Clover Network, Lightspeed, ROBIPOS, Tafela, iKhokha, inTouch Point of Sale, TouchBistro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Hospitality Point of Sale Software Market Strategic Shifts & Innovations
Cloud-hybrid architectures are absorbing the operational burden of power instability, converting what was a market constraint into a competitive differentiator for resilient vendors. Three interconnected developments are reshaping how hospitality operators select and deploy transaction infrastructure.
Tablet-based terminal hardware is absorbing the space constraints that previously dictated fixed-counter installations in Cape Town's high-turnover casual dining sector. Beachfront restaurants and compact urban bistros are adopting swivel-mounted iPad and Android configurations at twice the pace of traditional all-in-one terminals. This form factor shift is absorbing square footage limitations while enabling staff to process payments tableside, compressing table turn times during peak tourism seasons.
The Protection of Personal Information Act is absorbing vendor liability for consumer data breaches, elevating encryption standards and audit documentation requirements across the supplier base. Hospitality operators now demand SOC 2 Type II certification and local data residency guarantees before contract execution, filtering out undercapitalized competitors. Full-service restaurant chains in Gauteng are absorbing these compliance costs into three-year total cost of ownership calculations, extending procurement evaluation periods.
Buyer concentration among resort and hotel chains is absorbing pricing power from fragmented mid-market restaurant segments, compressing vendor margin structures. Procurement departments at large hospitality groups are consolidating supplier relationships across multiple properties, demanding volume discounts and dedicated support tiers that smaller independent operators cannot match. This concentration dynamic is most visible in the Western Cape, where international hotel brands are standardizing POS platforms across their Cape Town, Stellenbosch, and Franschhoek locations.
South Africa Hospitality Point of Sale Software Market Segmentation
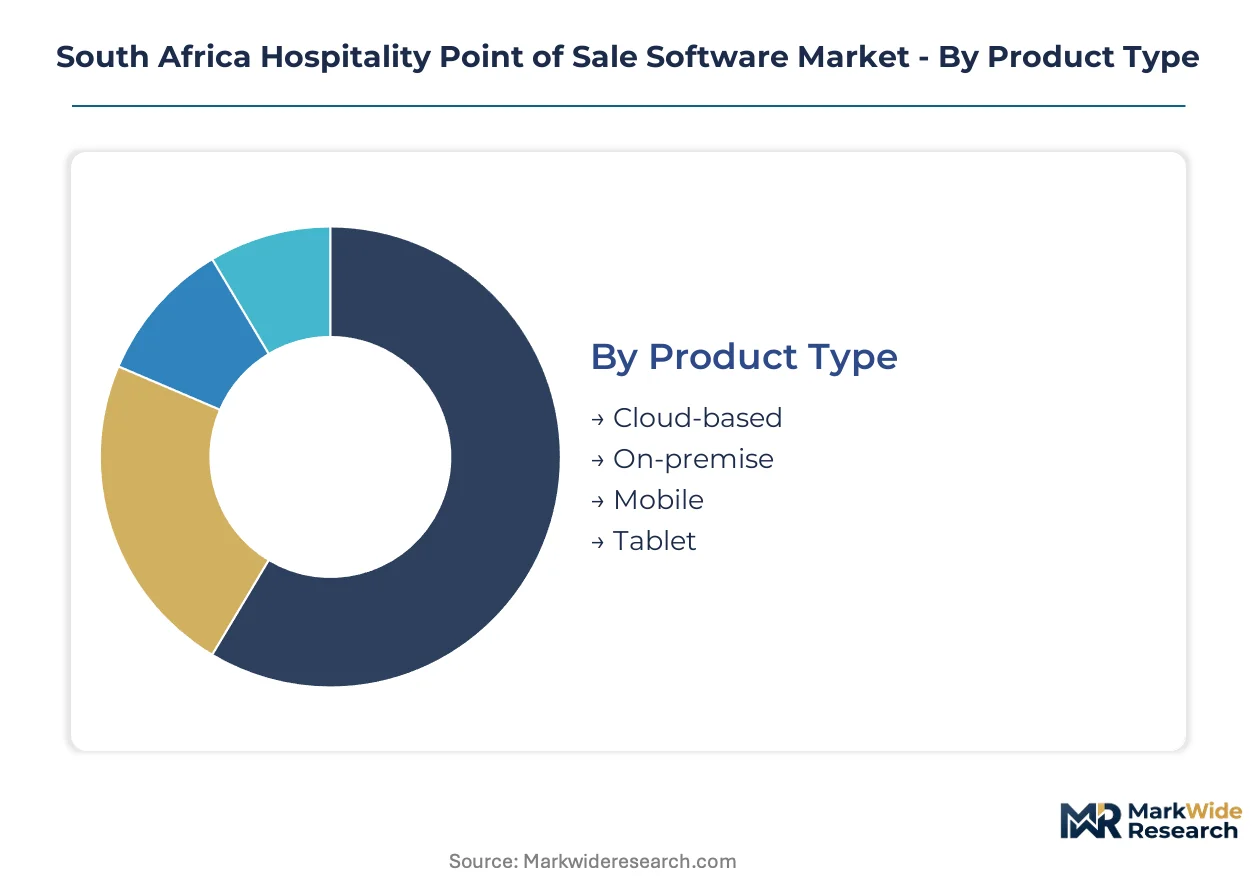
Segmentation in South Africa hospitality POS software reflects divergent resilience requirements across power-unstable operating environments. Buyer procurement patterns split sharply between cloud-native operators prioritizing remote management and on-premise holdouts in connectivity-constrained townships.
Product Type:
Capital intensity and load-shedding tolerance drive product selection across Gauteng and Western Cape hospitality operators.
- Cloud-based:Remote server architectures with offline transaction queuing capabilities maintain operational continuity during power interruptions. Full-service restaurant chains in Cape Town's Atlantic seaboard corridor are consolidating procurement around these platforms to enable centralized menu management across multiple locations.
- Mobile:Smartphone-based POS applications running on Android devices penetrate informal township eateries where dedicated terminal hardware proves cost-prohibitive. Gauteng's cash-dominant operations in Soweto and Alexandra are converting unrecorded transactions into trackable digital revenue streams through these lightweight deployments.
- On-premise:Local server installations persist among resort properties requiring guaranteed sub-second response times for high-volume payment processing.
- Tablet:Swivel-mounted iPad and Android configurations absorb space constraints in compact urban bistros.
Volume sits with cloud-based deployments; growth tilts toward mobile solutions in informal economy formalization.
End User:
Customer concentration patterns across buyer categories reshape vendor pricing power and support tier structures.
- Restaurants:Full-service and quick-service establishments generate the highest transaction velocity requirements, driving demand for integrated kitchen display systems and tableside payment capabilities. Western Cape wine route estate restaurants outside Cape Town's urban core remain underserved by specialized inventory-payment platforms.
- Hotels:Resort and hotel chains are consolidating supplier relationships across multiple properties, demanding volume discounts and dedicated support tiers that compress vendor margin structures. International hotel brands standardize platforms across Cape Town, Stellenbosch, and Franschhoek locations.
- Bars:High-turnover beverage establishments require rapid tab management and split-check functionality.
- Cafes:Compact footprint operations prioritize counter-space-efficient terminal configurations.
Revenue concentrates with hotel chains; expansion tilts most steeply toward restaurant tablet deployments.
Technology:
Regulatory mandates from the South African Reserve Bank and consumer preference shifts determine technology adoption sequencing.
- EMV:Chip authentication protocols mandated under the National Payment System Framework force hardware refresh cycles across legacy swipe-only terminal estates. Full-service restaurants and hotel chains face compressed procurement timelines to certify compliant infrastructure.
- Contactless Payments:NFC tap-to-pay and QR code convergence creates bundled margin pools for vendors integrating settlement rails with customer-facing interfaces. Cape Town tourism corridor establishments are absorbing these capabilities at twice the pace of inland markets.
- NFC:Near-field communication protocols enable sub-second transaction authorization speeds.
- QR Code:Tableside digital menu and payment integration reduces staff touchpoints.
Deployment volume clusters with EMV compliance; technology leadership is accelerating most quickly in contactless payment convergence.
Service Type:
Post-sale service economics determine vendor profitability and customer retention in a market characterized by complex legacy integrations.
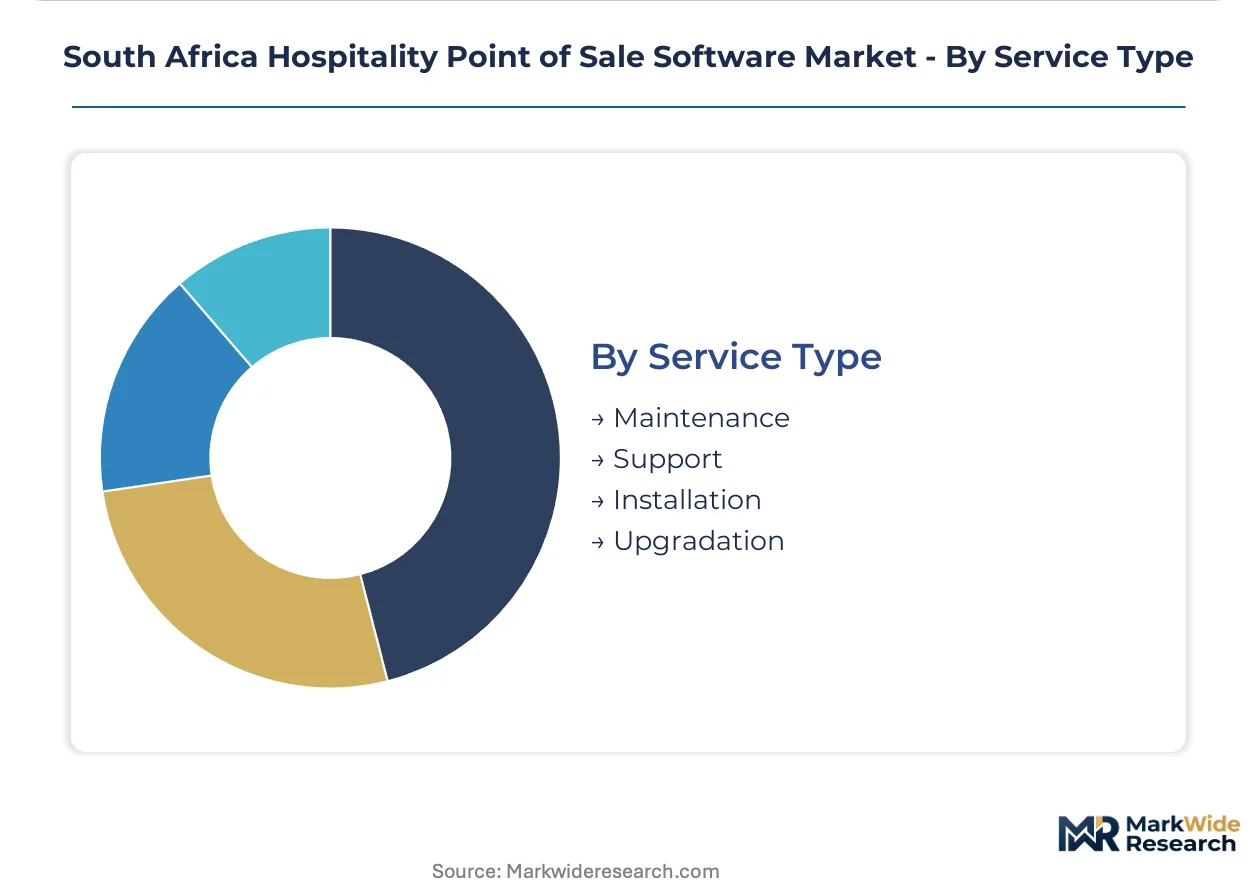
- Maintenance:Preventive hardware servicing and firmware update management absorb recurring revenue streams from installed terminal bases. Mid-market restaurant operators in Johannesburg face squeezed margins from backup power system requirements layered onto maintenance contracts.
- Installation:Professional services for property management system integration and kitchen hardware synchronization extend implementation timelines. Custom middleware development for legacy kitchen display connectivity inflates upfront project costs.
- Support:Help desk and on-site technical assistance tiers differentiate vendor offerings.
- Upgradation:Migration services from legacy platforms to cloud-hybrid architectures.
Service revenue concentrates with maintenance contracts; margin expansion tilts toward installation complexity in enterprise resort deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of hospitality POS software concentrates in Gauteng's technology corridors, while consumption spreads across Western Cape tourism corridors and KwaZulu-Natal hospitality clusters. The divergence creates distinct procurement patterns between enterprise-grade resort deployments and informal township operations.
Gauteng
Johannesburg and Pretoria anchor enterprise software development and system integration services for national hospitality chains. The Financial Sector Conduct Authority's payment system oversight shapes vendor certification requirements for operators headquartered in this province. Sandton's corporate hospitality cluster drives demand for integrated property management systems across full-service hotel chains.
Western Cape
Cape Town's Atlantic seaboard corridor generates concentrated demand for tablet-based terminals and contactless payment infrastructure in high-turnover casual dining. The Protection of Personal Information Act elevates data residency requirements for cloud-hosted platforms serving tourism-dependent establishments. Stellenbosch and Franschhoek wine route estate restaurants remain underserved by specialized inventory-payment integration.
KwaZulu-Natal
Durban's beachfront hospitality strip and uMhlanga's resort corridor drive demand for resilient load-shedding architectures in coastal operations. The South African Reserve Bank's National Payment System Framework mandates EMV-compliant terminal infrastructure across provincial payment networks. Ballito's emerging hospitality cluster attracts standardized platform deployments from national hotel chains.
Eastern Cape
Port Elizabeth's automotive corridor spillover creates mid-market restaurant demand distinct from coastal tourism patterns. Provincial economic development programs incentivize digital formalization of informal dining operations in township peripheries. The Wild Coast's emerging eco-tourism circuit presents white space for mobile-first POS penetration in remote hospitality locations.
South Africa Hospitality Point of Sale Software Market Key Industry Players
Top-tier vendors anchor enterprise resort and hotel chain deployments, while mid-market specialists compete across fragmented restaurant segments. The vendor base stratifies between global platform providers with property management integration capabilities and local mobile-first entrants targeting informal economy formalization. Three strategic archetypes dominate: enterprise-grade suite vendors, modular hardware-software bundlers, and township-focused mobile payment specialists. Competitive moves concentrate on cloud-hybrid architecture development and payment system operator licensing acquisition.
Within the enterprise integration tier, Oracle Hospitality and NCR Voyix Corporation exemplify platform consolidation strategies. iKhokha occupies a distinct position among mobile-first specialists targeting cash-dominant township operations in Gauteng's informal dining sector. These three anchors represent the spectrum from multinational property management integration to hyperlocal informal economy penetration.
| Leading Market Players |
|---|
| Oracle Hospitality |
| NCR Voyix Corporation |
| Clover Network |
| Lightspeed |
| ROBIPOS |
| Tafela |
| iKhokha |
| inTouch Point of Sale |
| TouchBistro |
| Others |
Cost & Logistics Intelligence
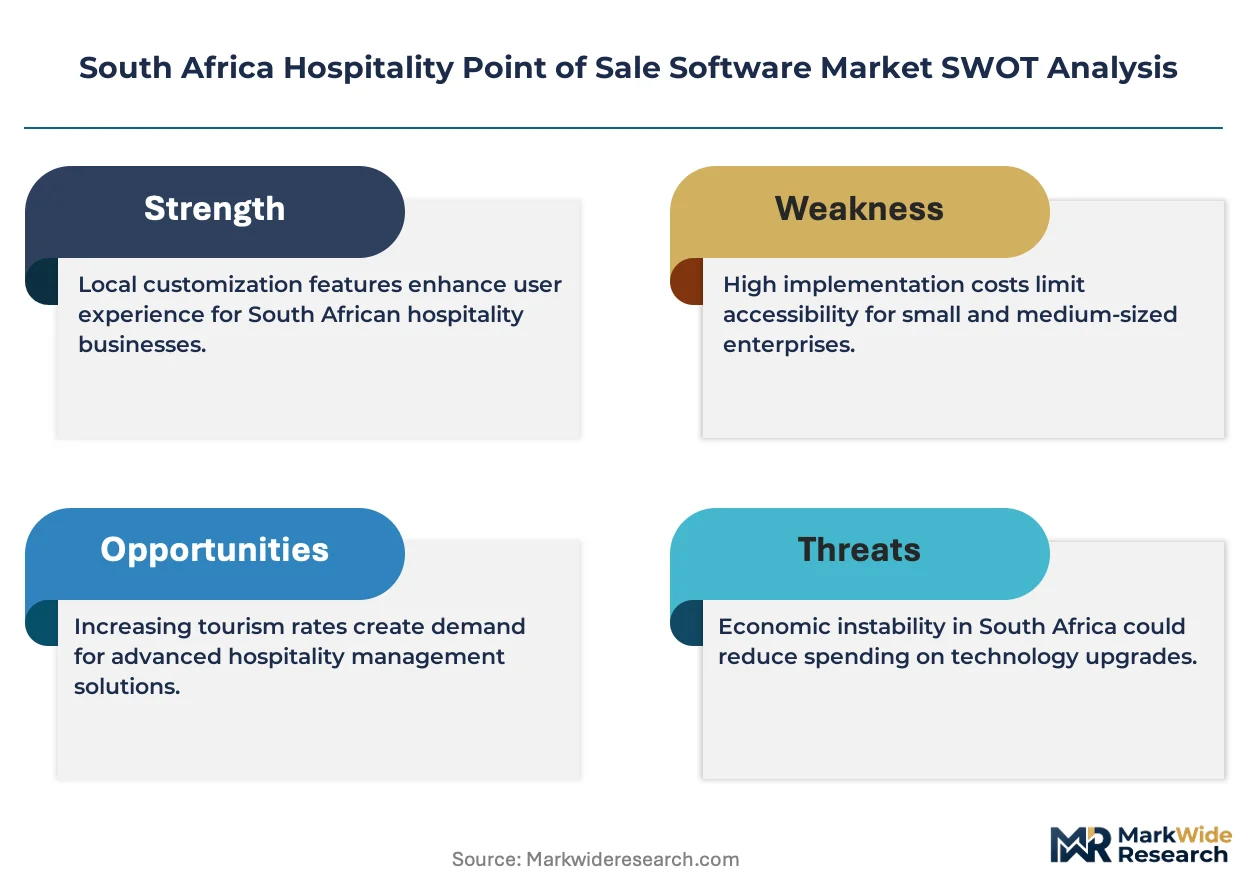
POPIA certification requirements gate both qualified supply and premium-tier pricing access, compressing vendor margins while elevating entry barriers for undercapitalized competitors. Cloud-hybrid architectures that guarantee load-shedding resilience command pricing premiums from Gauteng hotel chains and Western Cape resort operators, while uncertified providers face exclusion from procurement shortlists.
Pricing Analysis
Margin tightening in mid-market restaurant tiers reflects backup power infrastructure costs layered onto SaaS subscription fees. Three-tier pricing structure across enterprise, mid-market, and informal economy levels separates Oracle Hospitality's property management bundles from NCR Voyix's modular offerings and iKhokha's mobile-first tools. Certification investment and volume scale drive price differentiation, with hotel procurement departments extracting steepest discounts through multi-property consolidation. Township informal operators exhibit highest price sensitivity, converting unrecorded cash transactions only when mobile POS fees fall below informal money handler rates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for EMV chip terminal components, while China dominates Android tablet hardware for mobile POS deployments. Payment gateway middleware draws from India and Ireland development centers, creating timezone coordination friction for Cape Town support requirements. Tariff exposure on semiconductor imports threatens hardware refresh timelines mandated by the South African Reserve Bank. Distribution runs through Johannesburg system integrators with Western Cape satellite offices, extending implementation lead times for remote wine route estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-hybrid POS architectures are displacing on-premise legacy installations across South African hospitality, compressing procurement cycles for vendors with proven load-shedding resilience.
For Market Incumbents: Deploy payment system operator licensing as a defensive moat against unqualified competitors. Acquire specialized kitchen display system integrators to reduce middleware friction in enterprise resort deployments. Certification bottlenecks at the Financial Sector Conduct Authority threaten revenue recognition timelines for vendors without pre-established compliance infrastructure. For New Entrants and Emerging Players: Mobile-first QR code convergence represents the most penetrable wedge for township informal economy formalization in Gauteng's Soweto and Alexandra corridors. Target Western Cape wine route estate restaurants outside Cape Town's urban core with inventory-payment integration tools. Partner with local microfinance institutions for device financing to overcome cash-dominant operator capital constraints. For Investors and Strategic Acquirers: FSCA licensing approval acceleration is the leading indicator that market consolidation will concentrate share among compliant vendors. Position for 5-10 year horizon around vendors with proven cloud-hybrid architecture and SOC 2 Type II certification. Monitor POPIA audit completion rates as the signal for which mid-market players will survive procurement filter tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Payment System Operator Licensing | FSCA compliance raises barriers against unqualified competitors in Gauteng enterprise accounts. |
| Cloud-Hybrid Architecture Development | Load-shedding resilience converts operational constraint into competitive differentiator for Cape Town operators. |
| Kitchen Display System Integration | Legacy hardware synchronization reduces professional services costs in full-service restaurant deployments. |
| QR Code Ordering Convergence | Tableside digital menus bundled with settlement rails capture margin pools in Atlantic seaboard tourism corridor. |
| Western Cape Wine Route Expansion | Specialized inventory-payment platforms address underserved estate restaurants in Stellenbosch and Franschhoek. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospitality technology directors, FSCA compliance officers, hotel procurement managers, and POS integration specialists. Financial Sector Conduct Authority licensing databases, South African Reserve Bank payment system reports, and property management system vendor disclosures provided regulatory trajectory validation. Bottom-up terminal deployment estimates triangulated against top-down hospitality sector technology spending assessments.
Granularity-level modeling operated at deployment type, end-user category, and technology protocol dimensions across the projection horizon. Cloud-native, mobile, on-premise, and tablet form factors carried distinct resilience assumptions and power interruption recovery parameters. EMV compliance deadlines and contactless payment adoption curves fed into hardware refresh cycle timing. CAGRs derived from segment-level unit economics and pricing trajectory analysis.
Several conditions sit outside the modeled scope, including unannounced data localization mandates and load-shedding severity beyond current Eskom projections. Forecasts reflect assumptions about regulatory approval timelines and payment network interoperability standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Global Reservations Software Market