
 Global Virtual Reality in Tourism Market | 2026-2036
Global Virtual Reality in Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Reality in Tourism Market Outlook
The EU Green Deal is rebalancing how European tourism boards allocate experiential technology budgets, pushing operators toward lower-carbon digital alternatives. Groove Jones leverages its cinematic VR production pipeline to dominate destination marketing contracts across North American heritage sites. Felix & Paul Studios anchors its competitive position through exclusive partnerships with leading museums and cultural institutions. Matterport sustains technology leadership by extending its spatial data capture engine into hospitality walkthroughs and venue previews.
Virtual Reality in Tourism encompasses immersive hardware and software systems that render three-dimensional environments simulating destinations, accommodations, or cultural artifacts, typically requiring stereoscopic displays with 90Hz minimum refresh rates and six-degrees-of-freedom tracking for nausea-free navigation. These systems serve commercial purposes spanning pre-trip decision support, accessibility expansion for mobility-limited travelers, and operational training for hospitality staff. VR Headsets currently command the largest product revenue pool as enterprise procurement shifts toward standalone wireless devices with integrated eye-tracking. Cloud-Based delivery modes represent the fastest-expanding architecture, enabling tour operators to stream high-fidelity experiences without local rendering infrastructure. Destination Virtual Tours applications concentrate margin pools among premium heritage and luxury hospitality verticals where per-engagement licensing fees justify content production costs.
The EU AI Act and GDPR frameworks constrain how VR tourism platforms process biometric attention data and cross-border visitor profiles, compelling providers to architect edge-computing deployments that minimize personal data transmission. Japan's METI subsidizes VR content development through its digital tourism transformation program, while the UAE's MOHAP coordinates immersive healthcare tourism previews with clinical accreditation standards. China's MIIT enforces GB standards on headset electromagnetic emissions affecting import eligibility for foreign hardware suppliers. Stakeholders must monitor how divergent data localization requirements between European GDPR, Chinese cybersecurity law, and emerging Indian digital privacy codes fragment platform architecture decisions and partnership structures.
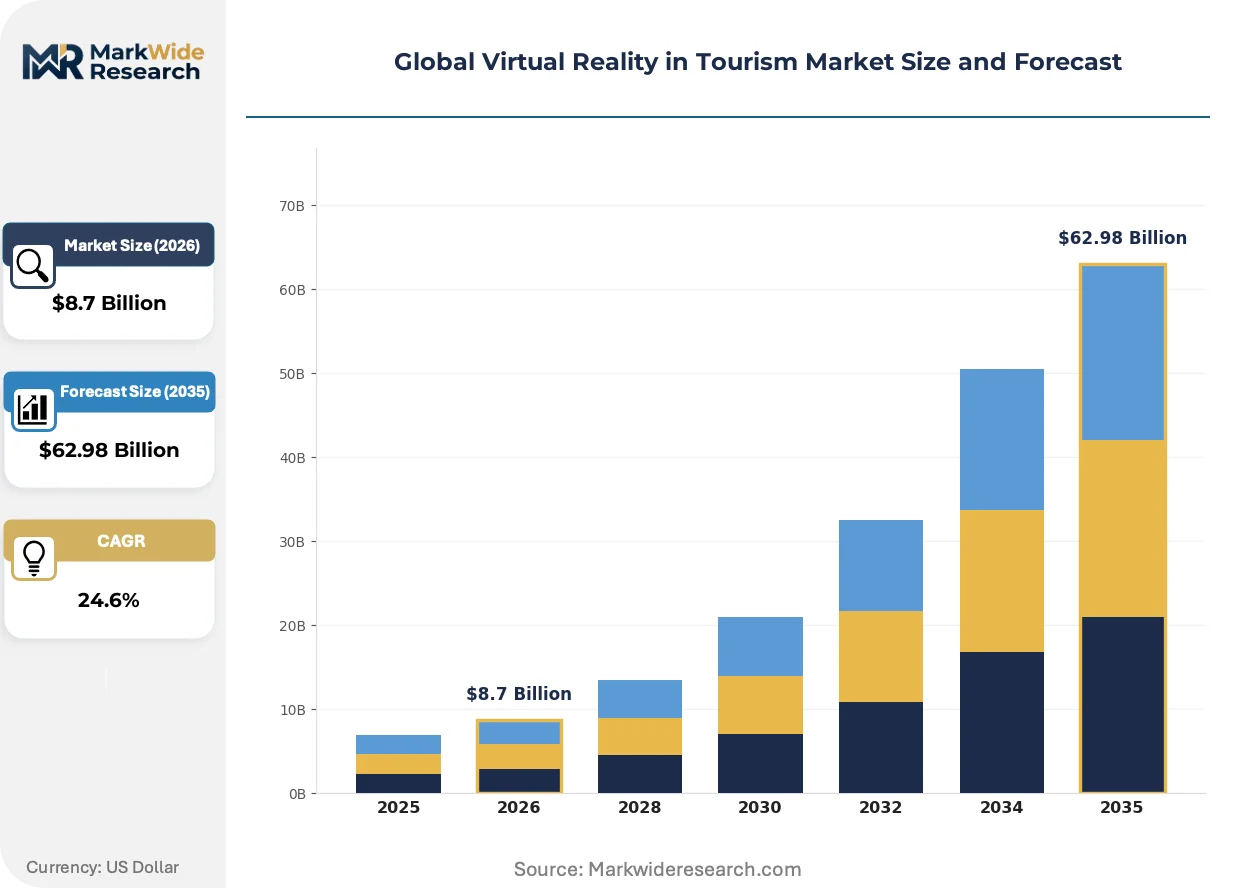
Market Dynamics
The EU Green Deal's digital tourism directives are compressing carbon footprints by pressuring operators to fund virtual alternatives alongside physical infrastructure, redirecting experiential technology budgets toward immersive pre-visit platforms.
Growth Catalysts
- EU Green Deal Mandates:European tourism boards now allocate experiential technology budgets toward lower-carbon digital alternatives, accelerating procurement of destination VR campaigns.
- Heritage Site Pre-Visit Demand:UNESCO sites and heritage museums are expanding immersive preview investments to capture accessibility-conscious travelers and extend visitor engagement windows.
- Standalone Wireless Hardware:Enterprise procurement is pivoting toward integrated eye-tracking headsets, eliminating tethered infrastructure and reducing deployment friction for hospitality operators.
Market Restraints
- Biometric Data Processing Limits:GDPR and the EU AI Act constrain how platforms process attention data and cross-border visitor profiles, forcing costly edge-computing rearchitecture.
- Electromagnetic Compliance Barriers:China's MIIT enforces GB standards on headset emissions, blocking import eligibility for foreign hardware suppliers lacking localized certification.
- Content Production Cost Concentration:High-fidelity destination experiences require cinematic production pipelines that concentrate margin pools among premium heritage and luxury hospitality verticals.
Strategic Opportunities
- Healthcare Tourism Previews:The UAE's MOHAP coordinates immersive clinical accreditation previews, creating a regulated channel for medical travel VR applications.
- Cloud-Based Delivery Expansion:Streaming architectures enable tour operators to deploy high-fidelity experiences without local rendering infrastructure, opening mid-market access.
- Japan's METI Subsidies:Digital tourism transformation funding supports domestic VR content development, lowering production barriers for regional destination marketing.
Industry Challenges
- Data Localization Fragmentation:Divergent requirements between GDPR, Chinese cybersecurity law, and emerging Indian digital privacy codes force redundant platform architectures and partnership restructuring.
- Spatial Capture Talent Scarcity:Hospitality walkthrough production requires specialized photogrammetry and volumetric video skills that outpace current vocational training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Reality in Tourism Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VR Headsets, Haptic Devices, VR Software, Accessories End User: Tour Operators, Travel Agencies, Educational Institutions, Individual Travelers Application: Destination Virtual Tours, Training Simulations, Cultural Experiences, Event Promotions Delivery Mode: Cloud-Based, On-Premise, Mixed Reality, Mobile Platforms |
| Companies Covered | Groove Jones, Felix & Paul Studios, World Travel VR, BlueLabel, Queppelin, VizioFly, Matterport, Zco Corporation, Meraki Studio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Reality in Tourism Market Strategic Shifts
Cloud streaming architectures and biometric-responsive rendering are collapsing the infrastructure barrier between enterprise-grade immersion and mass-market accessibility, compressing deployment timelines for destination marketers.
Eye-tracking integration is rewriting how tourism operators measure engagement depth and optimize content spend. Heritage sites in Germany and Japan are deploying gaze-heatmapping to refine narrative pacing, compressing the feedback loop between production investment and visitor conversion metrics.
REACH and RoHS compliance deadlines are forcing hardware manufacturers to reformulate headset component supply chains. European procurement teams now require full material disclosure documentation, shifting supplier qualification criteria toward circular design credentials and extended producer responsibility frameworks.
Subscription-based content licensing is displacing perpetual ownership models among mid-sized tour operators. German and Emirati destination marketing agencies now prefer per-engagement fees tied to actual viewer minutes, transferring production risk upstream to VR studios while preserving budget flexibility for seasonal campaign pivots.
Global Virtual Reality in Tourism Market Segmentation
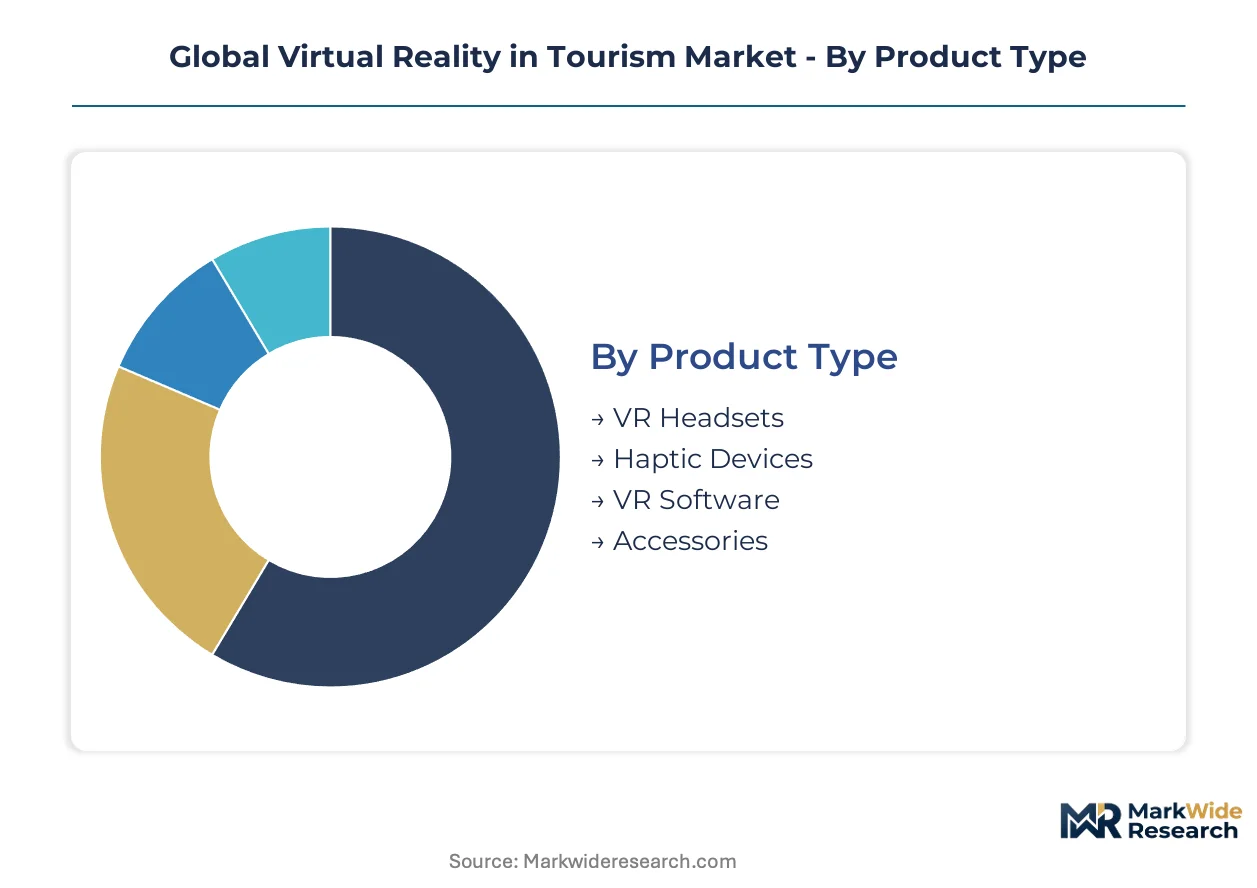
Product architecture and deployment topology determine competitive positioning across the VR tourism value chain. Specification choices cascade into procurement patterns, content production requirements, and regulatory compliance obligations for operators.
Product Type:
Display refresh rates, tracking fidelity, and sensory feedback integration define the hardware-software boundary in tourism VR systems.
- VR Headsets:Standalone wireless devices with integrated eye-tracking and six-degrees-of-freedom positional tracking dominate enterprise procurement. German heritage museums and UAE hospitality operators prioritize tetherless deployment to eliminate infrastructure friction in historic venues.
- VR Software:Cinematic rendering engines and spatial data processing platforms enable photorealistic destination reconstruction. Demand concentrates among Japanese METI-subsidized content studios and North American destination marketing agencies seeking scalable pre-visit production pipelines.
- Haptic Devices:Force-feedback gloves and motion platforms add tactile dimension to cultural artifact interaction. Deployments remain niche due to calibration complexity and maintenance overhead in high-traffic museum environments.
- Accessories:Controller peripherals, hygiene interfaces, and mounting hardware complete system configurations. Procurement typically follows headset vendor ecosystems rather than independent specification.
Mature deployment sits with VR Headsets. Newer deployment is concentrated in VR Software as studios decouple content production from hardware vendor roadmaps.
End User:
Budget scale and technical staffing depth segment procurement behavior across institutional buyer categories.
- Tour Operators:Mid-sized European operators leverage cloud-streaming architectures to deploy destination previews without capital infrastructure. GDPR compliance requirements force edge-computing investments that reshape total cost of ownership calculations.
- Travel Agencies:Commission-driven retail networks adopt per-engagement licensing models to preserve seasonal budget flexibility. German and Emirati agencies now structure vendor payments around actual viewer minutes rather than perpetual licenses.
- Educational Institutions:Curriculum-integrated cultural immersion programs drive academic procurement. Japanese universities access METI subsidy pools for VR field trip development, lowering per-student deployment costs.
- Individual Travelers:Consumer-grade headset ownership remains limited to early adopters with disposable income for premium hardware. Direct-to-traveler content revenue pools trail institutional channels significantly.
Volume leadership belongs to Tour Operators. Margin concentration favors Travel Agencies with established destination marketing relationships.
Application:
Use case specificity determines content production investment levels and measurement frameworks for engagement ROI.
- Destination Virtual Tours:Photorealistic pre-visit experiences for UNESCO sites and luxury hospitality properties command premium licensing fees. German heritage operators deploy gaze-heatmapping analytics to optimize narrative pacing and conversion metrics.
- Cultural Experiences:Artifact reconstruction and historical narrative immersion serve accessibility mandates and educational outreach. Japanese museums combine METI funding with private sponsorship to amortize volumetric video production costs.
- Training Simulations:Hospitality staff onboarding and crisis scenario rehearsal reduce operational risk. UAE healthcare tourism operators coordinate with MOHAP for clinical accreditation preview modules.
- Event Promotions:Temporary immersive activations for festivals and exhibitions generate time-bound engagement spikes. Content reuse rates trail permanent installation categories.
Revenue depth concentrates in Destination Virtual Tours. Steepest expansion trajectory appears in Cultural Experiences as accessibility regulations tighten across European heritage policy.
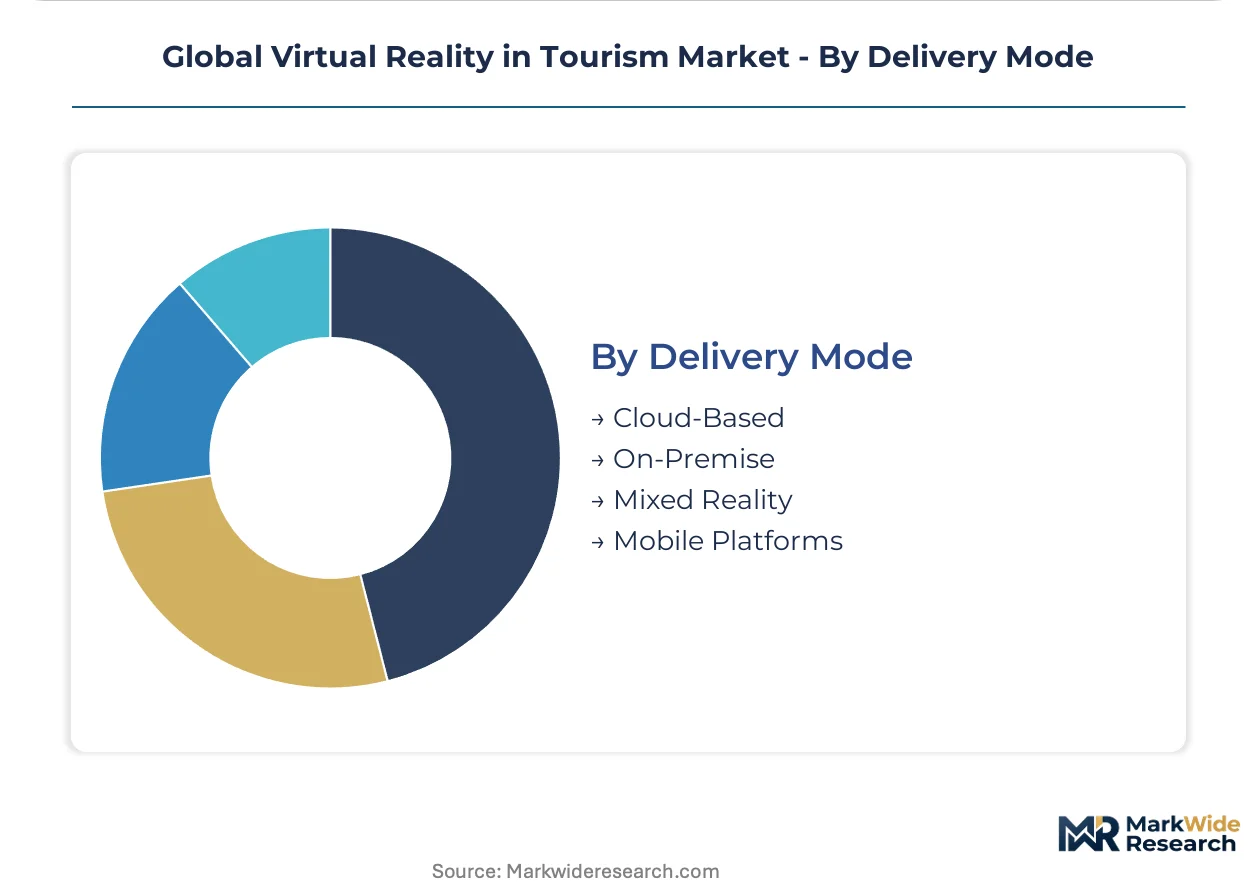
Delivery Mode:
Infrastructure location and rendering responsibility allocation determine scalability and data governance architecture.
- Cloud-Based:Centralized streaming eliminates local GPU requirements and enables instant content updates. GDPR and emerging Indian digital privacy codes force redundant regional data center deployments, fragmenting platform architecture decisions.
- On-Premise:Local rendering preserves data sovereignty for sensitive biometric attention tracking. Chinese MIIT electromagnetic compliance requirements block foreign hardware lacking localized GB certification, constraining vendor selection.
- Mixed Reality:Passthrough camera integration blends physical and virtual environments for hybrid destination previews. Hardware cost barriers limit deployment to flagship installations.
- Mobile Platforms:Smartphone-based VR through cardboard-style enclosures reaches price-sensitive segments. Technical limitations in tracking fidelity and thermal management restrict session duration and immersion quality.
Procurement momentum favors Cloud-Based delivery. Regulatory fragmentation is accelerating On-Premise reconsideration among data-sensitive European operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content production concentrates in North American and Japanese studios while consumption spreads across European heritage sites and Gulf hospitality operators. Germany and the UAE anchor procurement spending through government-funded destination campaigns. Divergent data localization regimes fragment platform deployment architectures across jurisdictions.
Germany
Heritage museums in Bavaria and Baden-Württemberg deploy gaze-heatmapping analytics to optimize narrative pacing in UNESCO site previews. The EU Green Deal redirects experiential technology budgets toward lower-carbon digital alternatives, accelerating VR procurement for pre-visit engagement. Berlin-Brandenburg hosts production studios serving destination marketing contracts across Central European heritage corridors.
United Arab Emirates
Dubai and Abu Dhabi hospitality operators commission immersive venue walkthroughs for luxury property portfolios. MOHAP coordinates clinical accreditation previews for healthcare tourism, creating regulated channels for medical travel VR applications. Federal tourism boards fund destination campaigns that prioritize standalone wireless deployment in historic venues lacking tethered infrastructure.
Japan
METI subsidizes domestic VR content development through its digital tourism transformation program, lowering production barriers for regional destination marketing. Kansai museums combine public funding with private sponsorship to amortize volumetric video production costs. Tokyo-based studios export cinematic rendering pipelines to Southeast Asian tourism boards.
United States
California and New York production houses dominate cinematic destination marketing contracts for North American heritage sites. FCC spectrum allocations influence wireless headset deployment feasibility in rural tourism corridors. Pacific Northwest tech clusters supply spatial data capture engines for hospitality walkthrough production.
China
MIIT enforces GB standards on headset electromagnetic emissions, blocking import eligibility for foreign hardware lacking localized certification. Yangtze River Delta cities host domestic manufacturers serving state-funded cultural digitization programs. Provincial tourism bidders require full supply chain documentation under circular economy frameworks.
Global Virtual Reality in Tourism Market Competitive Environment
The competitive structure tilts toward content studios with cinematic production capabilities rather than hardware manufacturers. Market concentration remains moderate with tiered specialization across destination marketing, heritage reconstruction, and hospitality walkthroughs. Two strategic archetypes dominate: integrated production studios controlling full creative pipelines and technology licensors enabling operator self-service deployment. Competitive moves center on exclusive partnership lockups with UNESCO sites and cloud-streaming infrastructure investments to bypass hardware procurement cycles.
Within the integrated production tier, Groove Jones and Felix & Paul Studios exemplify divergent geographic anchoring strategies. Groove Jones occupies a position tied to North American heritage site contracts, while Felix & Paul Studios represents the museum and cultural institution specialization vector. Matterport sits within the spatial data technology tier, extending capture engines into hospitality applications without direct content production ownership.
| Leading Market Players |
|---|
| Groove Jones |
| Felix & Paul Studios |
| World Travel VR |
| BlueLabel |
| Queppelin |
| VizioFly |
| Matterport |
| Zco Corporation |
| Meraki Studio |
| Others |
Value Chain & Pricing Dynamics
Cinematic production talent costs cascade from Los Angeles and Tokyo studios through to per-minute licensing fees charged by destination marketing agencies in Germany and the UAE. This labor concentration upstream compresses margins for mid-market tour operators downstream while premium heritage sites absorb higher rates through gaze-analytics yield optimization.
Pricing Analysis
Per-engagement fees tied to actual viewer minutes anchor value-based pricing for cloud-streamed destination experiences. Three-tier pricing structure across premium heritage, standard hospitality, and economy mobile-cardboard tiers separates UNESCO site previews from venue walkthroughs from smartphone-accessible content. Pricing pressure stems from METI-subsidized Japanese studios undercutting North American production rates. Mid-sized European tour operators exhibit highest price sensitivity due to GDPR-forced edge-computing investments.
Supply Chain Analysis
Photogrammetry specialist shortages in Shenzhen and Taipei constrain volumetric video capture capacity for hospitality walkthrough production. Optical component fabrication draws from South Korean and Japanese precision manufacturers while final headset assembly concentrates in Yangtze River Delta facilities. Single-source vulnerability sits with eye-tracking sensor modules sourced exclusively from Austrian MEMS foundries. Distribution runs through hospitality technology integrators serving museum and hotel procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial capture talent scarcity props pricing for cinematic VR production, constraining supply expansion even as cloud-streaming architectures lower deployment barriers.
For Market Incumbents: Cement exclusive partnership lockups with UNESCO heritage sites before METI-subsidized Japanese studios expand overseas. Acquire photogrammetry training pipelines to defend against volumetric video talent poaching. Vertical integration into cloud-streaming infrastructure insulates against per-engagement pricing erosion. For New Entrants and Emerging Players: Capture healthcare tourism preview contracts in the UAE where MOHAP accreditation requirements create regulatory moats. Target mid-sized German tour operators seeking GDPR-compliant edge-computing alternatives to incumbent cloud platforms. Lead with subscription-based content licensing rather than perpetual ownership to match procurement preference shifts. For Investors and Strategic Acquirers: Japanese studio export volumes to Southeast Asian tourism boards is the leading indicator that regional production capacity is achieving viable scale. Five-to-ten-year viability favors spatial data technology licensors over pure content studios given hardware vendor roadmap unpredictability. Monitor divergence between EU AI Act enforcement intensity and Chinese MIIT certification reciprocity as the signal for cross-border platform architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Streaming Infrastructure Investment | Eliminates local GPU requirements for German heritage museums operating in historic venues lacking tethered infrastructure. |
| Gaze-Analytics Platform Integration | Enables Dubai hospitality operators to optimize narrative pacing and compress feedback loops between production spend and conversion. |
| Exclusive UNESCO Site Partnership | Locks premium licensing fee pools away from METI-subsidized Japanese competitors expanding into European heritage corridors. |
| Edge-Computing Deployment | Preserves GDPR compliance for biometric attention data processing without cross-border transmission to centralized servers. |
| Volumetric Video Talent Acquisition | Addresses photogrammetry specialist scarcity constraining production capacity for cinematic destination reconstruction. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs combining with primary interviews across destination marketing directors, museum technology officers, hospitality procurement managers, and VR studio production leads. FDA 510(k) filings for healthcare tourism applications, EMA submissions, EU AI Act implementation guidance, and METI subsidy disbursement records provided validation anchors. Bottom-up content production cost modeling triangulated against top-down tourism board technology budget disclosures.
Granularity-level modeling distinguished standalone wireless headsets from tethered devices, cloud-streaming from on-premise rendering, and per-engagement from perpetual licensing across the projection horizon. Segmentation dimensions included product architecture, delivery topology, end-user budget scale, and application use-case specificity. CAGRs derived from installed base penetration curves weighted by procurement cycle timing. Industry-specific inputs incorporated UNESCO site digitization timelines and MIIT electromagnetic certification reciprocity patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act biometric data enforcement intensity and Chinese cybersecurity law data localization expansion. Forecasts reflect documented assumptions regarding METI subsidy continuity and REACH compliance deadline adherence. Material deviation in cloud-streaming bandwidth cost trajectories or volumetric video training pipeline throughput warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Smart Travel Sector Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Global Visitor Management Software Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Global Festival Management Software Market