
 Global Visitor Management Software Market | 2026-2036
Global Visitor Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Visitor Management Software Market Foresight
Subscription-based financing and asset-light SaaS procurement are reshaping competitive dynamics in visitor management, lowering barriers for mid-market buyers to access enterprise-grade security features. Envoy Inc. leverages its cloud-native architecture to dominate the corporate office segment with rapid deployment cycles. Proxyclick SA anchors its position across European multi-tenant commercial properties through deep GDPR compliance tooling. HID Global Corporation extends its hardware-software integration capabilities from physical access control into digital visitor workflows.
Visitor management software encompasses digital platforms that authenticate, track, and audit guest entry through identity verification, badge issuance, and real-time logging against facility access databases, typically integrating with directory services and physical security infrastructure. Cloud-based deployment leads solution architecture due to minimal on-site infrastructure requirements and automatic security patch delivery, while on-premise configurations retain share in defense and classified government facilities where data sovereignty mandates air-gapped operation. The reporting and analytics solution type captures expanding margin pools as organizations seek occupancy intelligence and emergency evacuation accountability beyond basic visitor logging.
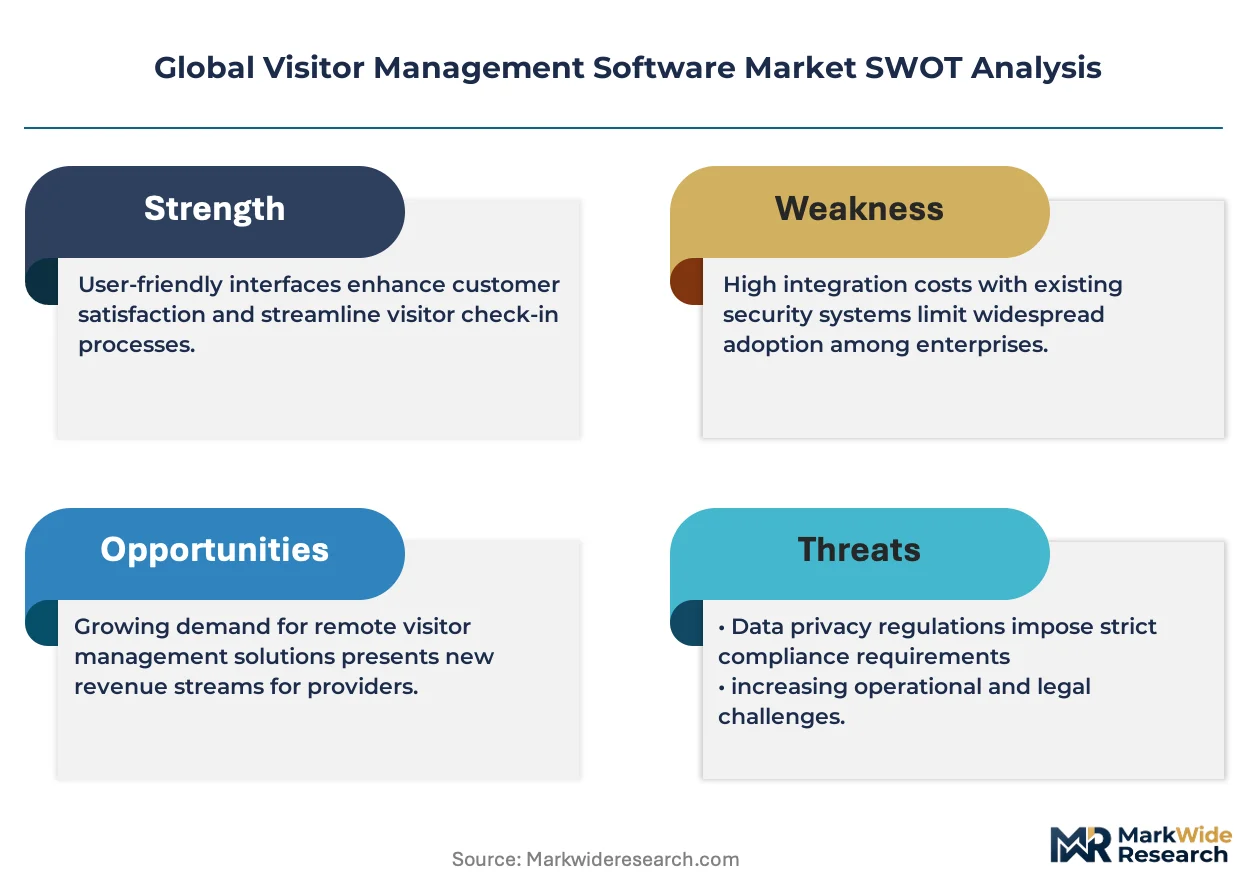
The EU AI Act, GDPR, and the U.S. HIPAA framework collectively shape product roadmaps by mandating consent capture, data retention limits, and audit trail immutability that legacy paper systems cannot satisfy. Facility security managers in Germany, France, and California now require vendors to demonstrate regulatory mapping before procurement approval. Stakeholders must monitor evolving biometric consent requirements and cross-border data localization rules that will determine which deployment architectures remain viable across multinational footprints.
Market Dynamics
Cloud-native architecture is compressing deployment timelines from months to days, forcing legacy on-premise vendors to restructure pricing models or cede mid-market share entirely.
Growth Catalysts
- HIPAA compliance mandates:US healthcare facilities must maintain immutable visitor audit trails, accelerating replacement of paper logbooks with digital platforms that integrate with existing EHR access controls.
- Biometric authentication convergence:Facial recognition and liveness detection are reducing badge fraud at high-security federal buildings and data centers, cutting unauthorized entry incidents.
- Germany's federal data protection authority:State-level DPA enforcement actions against manual visitor tracking are compelling municipal buildings and universities to adopt GDPR-certified solutions.
Market Restraints
- Biometric consent fragmentation:Illinois BIPA, California CCPA, and EU GDPR impose conflicting opt-in requirements, forcing vendors to maintain jurisdiction-specific codebases that inflate R&D overhead.
- Air-gapped facility persistence:Defense and intelligence agencies in the United States, United Kingdom, and Israel reject cloud connectivity, limiting addressable market for SaaS-native providers.
- Smartphone substitution threat:Native mobile wallet passes and building access credentials embedded in Apple Wallet and Google Wallet are displacing standalone visitor badge issuance at tech campuses.
Strategic Opportunities
- India's Smart Cities Mission:Municipal corporation tenders for integrated civic facility management are creating first-mover advantages for vendors offering Hindi-localized interfaces and Aadhaar-linked identity verification.
- EU AI Act Article 52:Mandatory disclosure requirements for emotion recognition and biometric categorization systems are creating compliance consulting revenue streams adjacent to core software licensing.
- Edge computing convergence:On-device facial processing eliminates latency and cloud data exposure, opening sovereign cloud-averse markets in Saudi Arabia, UAE, and Switzerland.
Industry Challenges
- API integration complexity:Legacy physical access control systems from Honeywell, Lenel, and Software House use proprietary protocols, extending implementation timelines and requiring specialized systems integrators.
- Cybersecurity certification backlog:FedRAMP and StateRAMP authorization processes stretch 14-18 months, delaying entry into US federal and state government procurement pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Visitor Management Software Market |
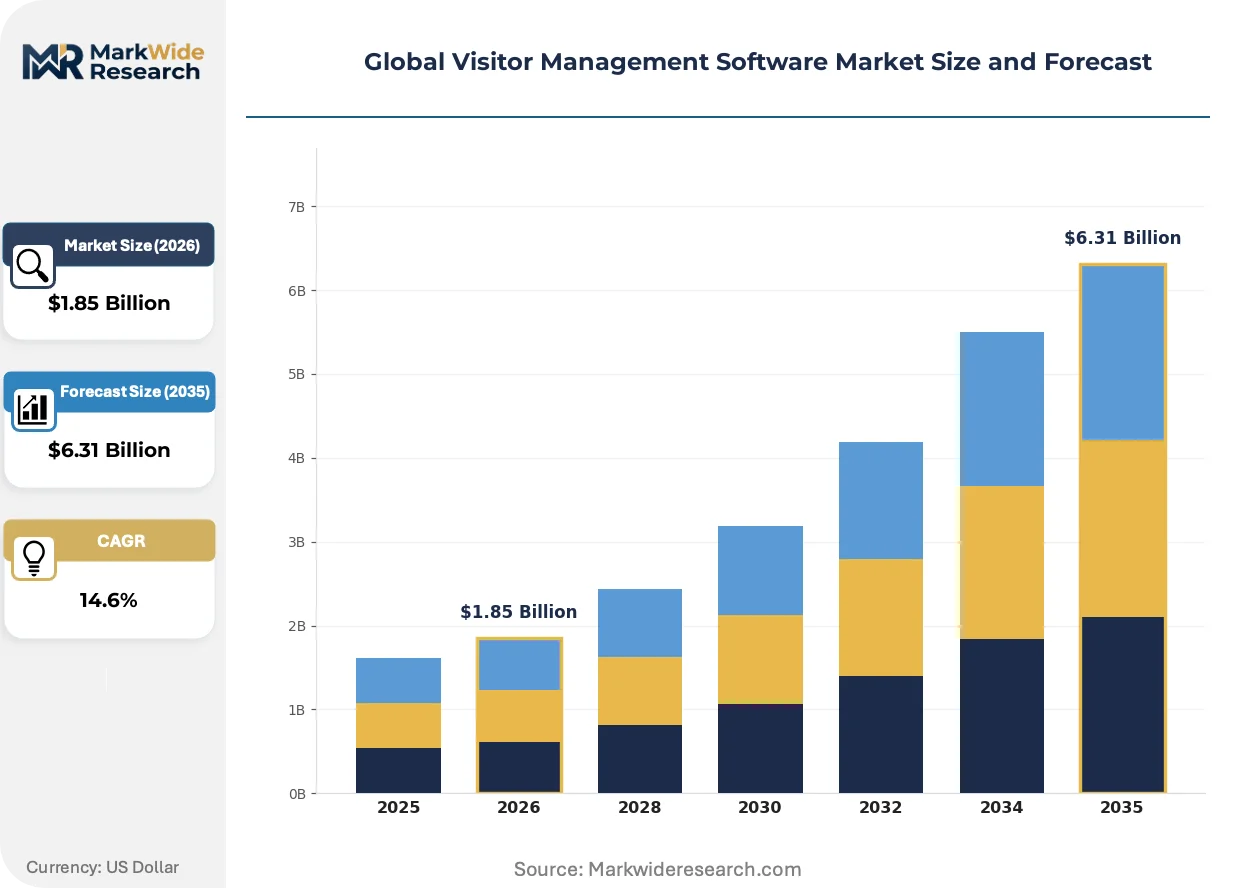
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Virtual Solution Type: Visitor Log, Pre-Registration, Badge Printing, Access Control, Reporting & Analytics Use Case: Corporate Offices, Educational Institutions, Government Facilities, Healthcare Facilities, Event Management Client Type: Enterprises, Small & Medium Businesses, Public Sector Organizations, Non-Profit Organizations |
| Companies Covered | Envoy Inc., Proxyclick SA, HID Global Corporation, Honeywell International Inc., Johnson Controls plc, iLobby Systems Inc., Traction Guest Corporation, Zebra Technologies Corporation, MRI On Location, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Visitor Management Software Market Shifts & Advancements
Artificial intelligence is embedding predictive capabilities into visitor workflows, shifting competitive advantage from data collection speed toward real-time risk scoring and facility occupancy optimization.
Computer vision with edge-based facial authentication is digitizing entry workflows at corporate campuses and healthcare systems. Enterprise security teams in the United States and United Kingdom are deploying these systems within 48-hour windows. The technology is digitizing identity verification from a front-desk bottleneck into a frictionless corridor experience, compressing staffing requirements and visitor processing costs simultaneously.
The EU AI Act's risk classification framework for biometric identification systems is restructuring product roadmaps across European vendors. High-risk system designations now mandate conformity assessments, technical documentation, and human oversight protocols before market entry. German and French facility managers are prioritizing vendors with pre-certified Article 52 compliance, creating procurement friction for non-European suppliers lacking established notified body relationships.
Subscription financing with usage-based tiers is displacing perpetual licensing in mid-market procurement. Facility management departments at US universities and UK hospital trusts are negotiating seat-flexible contracts that scale with semester or seasonal occupancy. California and Texas state procurement offices have published template RFP language favoring operational expenditure models, accelerating vendor transitions from upfront revenue recognition to recurring annual contracts.
Global Visitor Management Software Market Segmentation
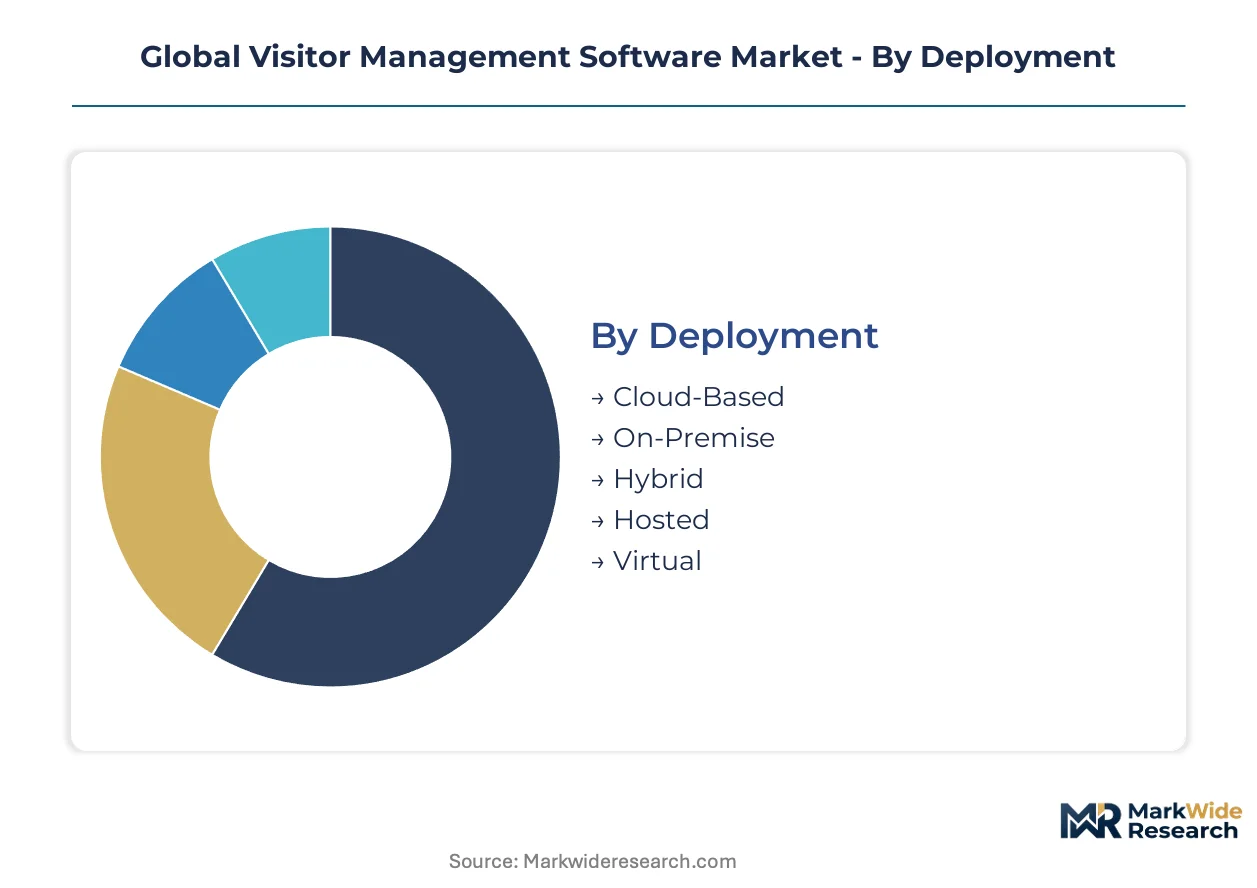
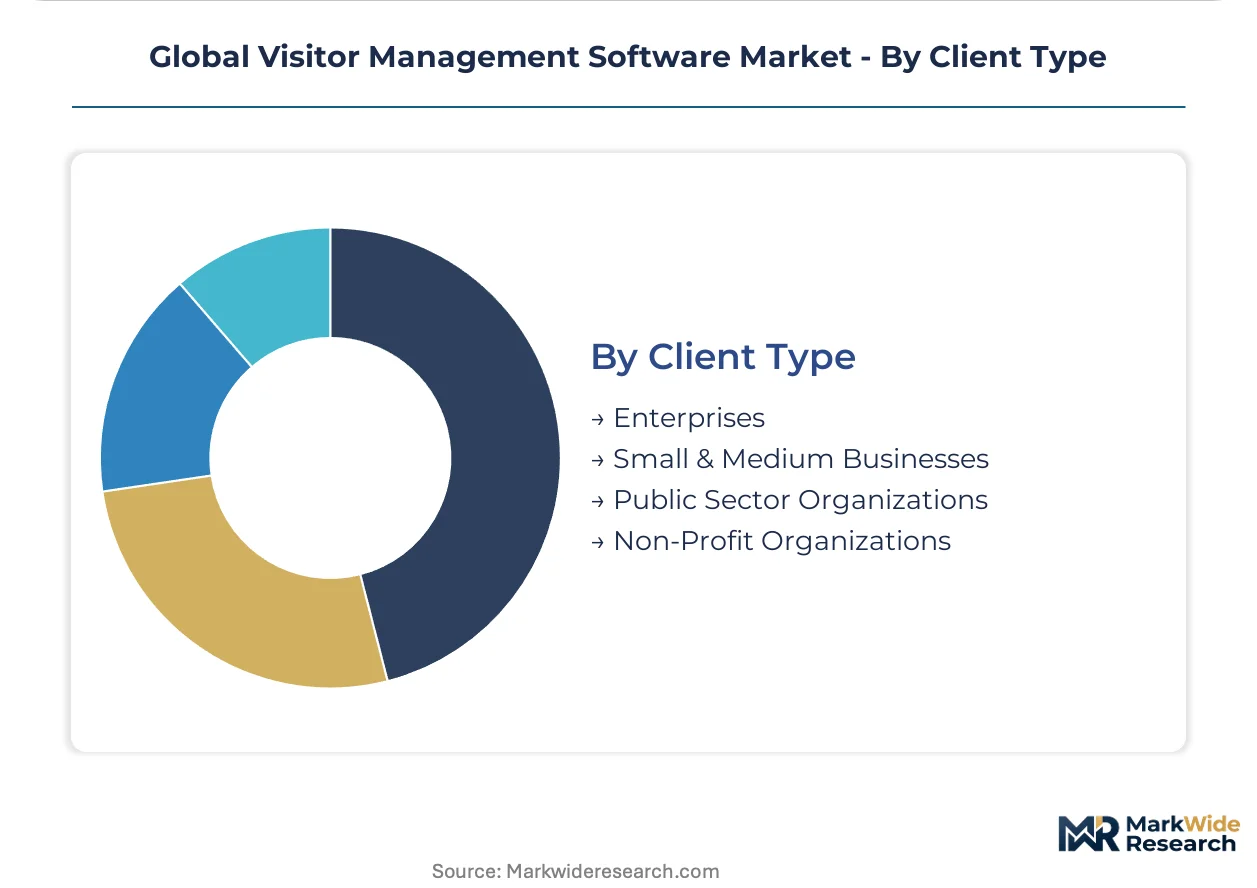
Visitor management software vendors structure product portfolios across four intersecting dimensions. Deployment architecture determines infrastructure investment and regulatory compliance pathways. Solution type governs feature depth and pricing tiers. Use case specialization drives vertical-specific compliance tooling. Client type shapes contract terms and support intensity.
Deployment:
Post-implementation service obligations vary dramatically across deployment modes, with cloud-native architectures demanding continuous security patching and uptime guarantees while on-premise installations require periodic on-site hardware maintenance.
- Cloud-Based:Multi-tenant SaaS platforms deliver automatic security updates and elastic scaling without customer-side infrastructure. Demand concentrates among US enterprise campuses and UK hospital trusts seeking rapid deployment without capital expenditure. HIPAA and GDPR compliance automation accelerates healthcare and European public sector procurement.
- On-Premise:Air-gapped installations run entirely within customer data centers with no external connectivity. US defense agencies and Israeli intelligence facilities mandate this architecture for data sovereignty. High upfront licensing and dedicated support contracts characterize commercial relationships.
- Hybrid:Split architectures process sensitive biometric data locally while syncing administrative functions to cloud dashboards.
- Hosted:Single-tenant cloud deployments on dedicated virtual infrastructure meet data residency requirements in Germany and Switzerland.
- Virtual:Containerized software packages deploy across private cloud stacks with standardized orchestration.
By volume, Cloud-Based leads. By growth pace, Hybrid is expanding most quickly as regulated industries seek middle-ground architectures.
Solution Type:
Feature bundling strategies separate commodity logging functions from premium intelligence layers, with vendors capturing margin expansion through modular add-ons rather than all-inclusive suites.
- Reporting & Analytics:Occupancy intelligence dashboards aggregate visitor flow patterns, dwell times, and facility utilization rates. US federal buildings and California corporate campuses deploy these for emergency evacuation accountability and space optimization mandates. Real-time API feeds into building management systems differentiate premium tiers.
- Access Control:Biometric authentication and physical security system integration govern entry permissions. German automotive manufacturing plants and UAE financial centers prioritize liveness detection and anti-spoofing protocols. EU AI Act conformity assessments add implementation complexity.
- Visitor Log:Digital audit trails replace paper sign-in sheets with searchable, timestamped records.
- Pre-Registration:Host-initiated guest enrollment streamlines lobby processing through advance identity verification.
- Badge Printing:On-demand credential issuance with photo capture and QR encoding supports temporary access workflows.
By revenue concentration, Access Control dominates. By margin expansion, Reporting & Analytics is gaining share fastest.
Use Case:
Vertical specialization requirements fragment vendor roadmaps, with healthcare and government segments demanding compliance certifications that corporate office deployments rarely require.
- Healthcare Facilities:HIPAA-compliant audit trails and EHR access control integration protect patient privacy. US hospital systems and NHS trusts in the United Kingdom mandate immutable visitor logs with retention limits. Infection control protocols accelerated touchless biometric adoption post-pandemic.
- Government Facilities:FedRAMP and StateRAMP authorization gates federal procurement in the United States. German municipal buildings face DPA enforcement actions against manual tracking. Multi-factor authentication and classified area segregation drive feature specifications.
- Corporate Offices:Frictionless guest experience and brand impression management prioritize speed over security depth.
- Educational Institutions:Semester-based occupancy fluctuations favor seat-flexible subscription pricing.
- Event Management:Temporary high-volume processing requires rapid badge issuance and crowd flow analytics.
By contract value, Government Facilities leads. By deployment velocity, Corporate Offices is climbing the fastest.
Client Type:
Procurement sophistication and sales cycle duration diverge sharply, with public sector tenders demanding extensive compliance documentation while SMB purchases prioritize self-service onboarding.
- Enterprises:Multi-location rollouts with directory service integration and custom workflow configuration. Fortune 500 technology companies and pharmaceutical headquarters in New Jersey and Massachusetts negotiate enterprise licensing agreements. Dedicated customer success teams and SLA guarantees accompany deployments.
- Small & Medium Businesses:Self-service SaaS adoption with credit-card billing and minimal implementation support. UK professional services firms and Texas healthcare clinics purchase through channel partners and software marketplaces. Monthly subscription flexibility reduces commitment risk.
- Public Sector Organizations:RFP-driven procurement with mandatory small business subcontracting and open standards compliance.
- Non-Profit Organizations:Donor-restricted budgets and grant-funded technology investments constrain pricing elasticity.
By aggregate spending, Enterprises leads. By customer acquisition growth, Small & Medium Businesses shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA compliance mandates and GDPR enforcement actions are accelerating digital visitor tracking procurement across healthcare and government facilities worldwide. The United States dominates enterprise deployment volumes, while European regulatory pressure reshapes vendor certification requirements. Emerging markets in Asia-Pacific and the Middle East are opening through smart city infrastructure programs.
United States
Federal building security upgrades and FedRAMP authorization requirements drive procurement at defense agencies and civilian departments. HIPAA audit trail mandates compel hospital systems to replace paper logbooks with immutable digital records. Enterprise campuses in California and Texas negotiate seat-flexible SaaS contracts that scale with seasonal occupancy fluctuations.
Germany
State-level data protection authority enforcement against manual visitor tracking compels municipal buildings and universities toward certified digital platforms. GDPR Article 30 documentation requirements and the EU AI Act's high-risk system classification mandate conformity assessments for biometric deployments. Automotive manufacturing plants in Bavaria prioritize liveness detection and anti-spoofing protocols for facility access control.
United Kingdom
NHS trust procurement specifications mandate immutable visitor logs with defined retention limits for patient privacy protection. Post-pandemic infection control protocols accelerated touchless biometric adoption across hospital networks. Corporate headquarters in London and financial services clusters in Edinburgh deploy frictionless entry systems to compress staffing requirements.
India
Smart Cities Mission tenders for integrated civic facility management create first-mover opportunities for localized platform providers. Municipal corporations in Maharashtra and Karnataka seek Hindi-localized interfaces with Aadhaar-linked identity verification. Educational institutions in Delhi-NCR and Bangalore favor subscription pricing that accommodates semester-based occupancy variations.
United Arab Emirates
Financial center security requirements and sovereign cloud preferences drive demand for edge-based facial processing systems. Edge computing architectures eliminate latency and cross-border data exposure concerns for Dubai and Abu Dhabi commercial properties. Government-led digital transformation programs prioritize vendors offering Arabic-language support and local data residency guarantees.
Global Visitor Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: cloud-native SaaS specialists, hardware-software integrators from physical access control, and compliance-focused regional champions. Strategic archetypes include subscription-first platform vendors, legacy security infrastructure extenders, and GDPR-certified European specialists. Competitive dynamics center on M&A activity to acquire biometric capabilities and strategic partnerships to penetrate air-gapped government markets.
Within the cloud-native tier, Envoy Inc. exemplifies rapid-deployment architecture, while Proxyclick SA anchors GDPR-compliant positioning across European multi-tenant properties. HID Global Corporation occupies the hardware-software integration vector, extending physical access control capabilities into digital visitor workflows. These three players represent distinct competitive positioning strategies: speed-to-deploy, regulatory certification depth, and infrastructure convergence.
| Leading Market Players |
|---|
| Envoy Inc. |
| Proxyclick SA |
| HID Global Corporation |
| Honeywell International Inc. |
| Johnson Controls plc |
| iLobby Systems Inc. |
| Traction Guest Corporation |
| Zebra Technologies Corporation |
| MRI On Location |
| Others |
Supply & Pricing Matrix
Silicon Valley's cloud infrastructure concentration compresses SaaS delivery costs while amplifying pricing power for vendors serving HIPAA-mandated healthcare facilities and FedRAMP-authorized government buyers. The interplay between elastic compute pricing and compliance certification costs creates divergent margin structures across deployment architectures.
Pricing Analysis
Certification level creates the primary spread between commodity logging tiers and premium biometric-integrated suites. Three-tier pricing structure across enterprise-grade FedRAMP, mid-market GDPR-compliant, and basic digital logbook tiers dominates procurement. Pricing pressure stems from smartphone wallet substitution eroding standalone badge issuance revenue. Small and medium businesses exhibit highest price sensitivity, while defense agencies accept premium positioning for air-gapped sovereignty.
Supply Chain Analysis
Export-control restrictions on facial recognition algorithms and edge-processing chips limit component flows from US and Chinese suppliers into certain Middle Eastern and European deployments. Software development concentrates in the United States, India, and Israel, with hardware integration anchored in Taiwan and Germany. Supply chain risk centers on single-source vulnerability for liveness-detection sensors. Distribution runs through systems integrators and direct SaaS marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as directory service integration and physical access control convergence transform visitor management from standalone software into infrastructure middleware.
For Market Incumbents: Pre-empt smartphone wallet displacement by embedding native credential APIs into core workflows before Apple and Google capture campus access share. Deepen biometric certification investment to maintain pricing power against cloud-native challengers lacking FedRAMP depth. For New Entrants and Emerging Players: Build out Hindi-localized, Aadhaar-linked platforms for India's Smart Cities municipal tenders before established vendors adapt pricing models. Target Saudi and UAE sovereign-cloud-averse buyers with edge-only architectures that eliminate cross-border data exposure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-specialist vendors with HIPAA or GDPR certification moats rather than horizontal corporate office providers. Monitor EU AI Act enforcement velocity as the inflection signal for biometric system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Certification Investment | EU AI Act Article 52 compliance opens German and French public sector procurement pipelines. |
| Edge Computing Architecture | On-device facial processing penetrates Saudi and Swiss sovereign-cloud-restricted markets. |
| Directory Service Integration | Azure AD and Okta interoperability converts visitor management into identity infrastructure layer. |
| Vertical Compliance Specialization | HIPAA audit trail automation captures US hospital system replacement cycles. |
| Channel Partner Expansion | UK and Texas state procurement templates favor operational expenditure models via reseller networks. |
Research Methodology
A spread of perspectives from facility security managers, health system compliance officers, government procurement specialists, and physical access control integrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FedRAMP authorization databases, NHS procurement specifications, and EU AI Act implementation guidance. Bottom-up deployment sizing and top-down regulatory mandate tracking triangulated market scope.
Demand-supply balance across cloud-native, hybrid, and air-gapped architectures anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical compliance requirements, integration complexity, and regional regulatory cluster. CAGRs derived from replacement cycle analysis of paper logbook displacement and biometric upgrade timelines. Forecast inputs incorporated HIPAA enforcement velocity and GDPR DPA penalty data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale identity providers would shift outcomes. Material shifts in biometric consent litigation or EU AI Act enforcement thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel Technology and Hospitality Software
South Africa Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Hotel Revenue Management Software Market
Travel Technology and Hospitality Software
Global Festival Management Software Market
Travel Technology and Hospitality Software
Travel Technology Market
Travel Technology and Hospitality Software
Global Virtual Reality in Tourism Market
Travel Technology and Hospitality Software
Restaurant Reservations Software Market
Travel Technology and Hospitality Software
Travel Management Software Market
Travel Technology and Hospitality Software
Travelport GDS Systems Market
Travel Technology and Hospitality Software
Timeshare Software Market
Travel Technology and Hospitality Software
Hospitality Point of Sale Software Market
Travel Technology and Hospitality Software
Airline Reservation Software Market
Travel Technology and Hospitality Software
Hospitality Property Management Software (PMS) Market
Travel Technology and Hospitality Software
Global Hotel Reservation Software Market
Travel Technology and Hospitality Software
Global Reservations Software Market
Travel Technology and Hospitality Software
Connected Hotel Systems and Solutions Market
Travel Technology and Hospitality Software
Smart Travel Sector Market