
 Global Classroom Management Software Market | 2026-2036
Global Classroom Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Classroom Management Software Market Foresight
Platform bundling is hardening as the dominant procurement pattern in education technology, with districts favoring integrated suites over point solutions. Google LLC leverages its Workspace for Education ecosystem to anchor classroom management within broader productivity workflows. Microsoft Corporation competes through deep Azure infrastructure integration and enterprise-grade compliance tooling. Apple Inc. differentiates via proprietary hardware-software cohesion and premium positioning in affluent districts.
Classroom management software comprises applications that enable real-time oversight of student devices, digital content distribution, behavior tracking, and formative assessment within instructional environments; these systems typically operate through agent-based client installations or browser-mediated cloud dashboards with latency thresholds below 200 milliseconds for synchronous screen broadcasting. Cloud-based deployment leads solution type adoption as districts abandon on-premise server maintenance, while assessment tools command premium pricing due to Learning Management System interoperability demands. K-12 education remains the largest application segment, though corporate training exhibits faster growth as workforce reskilling budgets expand.
The U.S. Department of Education, the EU's GDPR enforcement network, and India's BIS digital standards framework collectively shape product roadmaps through student data privacy mandates, cross-border transfer restrictions, and localization requirements. Compliance architecture now functions as a competitive moat rather than a cost center, particularly for vendors seeking multi-jurisdictional contracts. Stakeholders must weigh interoperability investments against the risk of platform lock-in as district consolidation accelerates.
Market Dynamics
Cloud migration is compressing procurement cycles as K-12 districts abandon multi-year server refresh contracts in favor of SaaS subscriptions. This shift is redistributing vendor power toward platform ecosystems with embedded compliance tooling.
Growth Catalysts
- Federal Connectivity Subsidies:United States districts leverage E-Rate program funds to accelerate device refresh timelines. Hardware saturation expands the addressable base for management software licensing.
- GDPR Enforcement Network:European data protection authorities impose granular student data processing requirements. Compliance mandates drive replacement of legacy on-premise systems with auditable cloud alternatives.
- Formative Assessment Interoperability:Learning Management System integration demands reshape RFP specifications. Districts prioritize platforms with native LTI Advantage certification over standalone classroom tools.
Market Restraints
- Input Cost Volatility:Semiconductor shortages and memory price fluctuations inflate Chromebook and tablet procurement costs. District hardware budgets constrain concurrent software licensing expansion.
- Technical Latency Thresholds:Synchronous screen broadcasting requires sub-200 millisecond response times. Rural broadband infrastructure gaps in Australia and Canada limit real-time feature adoption.
- Substitution Threat:Native operating system parental controls and mobile device management suites absorb basic classroom oversight functions. Free alternatives capture price-sensitive private school segments.
Strategic Opportunities
- Corporate Training Reskilling:Workforce development budgets in Germany and Japan expand faster than K-12 procurement. Vendors repurpose classroom architectures for enterprise certification programs.
- AI-Act Compliance Tooling:The EU AI Act's risk classification system for educational applications creates premium service tiers. Automated bias auditing and explainability modules command pricing premiums.
- Browser-Native Deployment:WebRTC and Progressive Web App standards eliminate client installation friction. Channel partners in Brazil and Mexico accelerate district penetration without IT staff dependency.
Industry Challenges
- Interoperability Engineering Talent:LTI 1.3 Advantage, OneRoster, and Caliper Analytics certifications require scarce integration specialists. Vendors compete for developers with prior IMS Global certification experience.
- Legacy System Coexistence:Decades-old student information systems in United Kingdom and France municipalities resist API modernization. Middleware development consumes disproportionate R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Classroom Management Software Market |
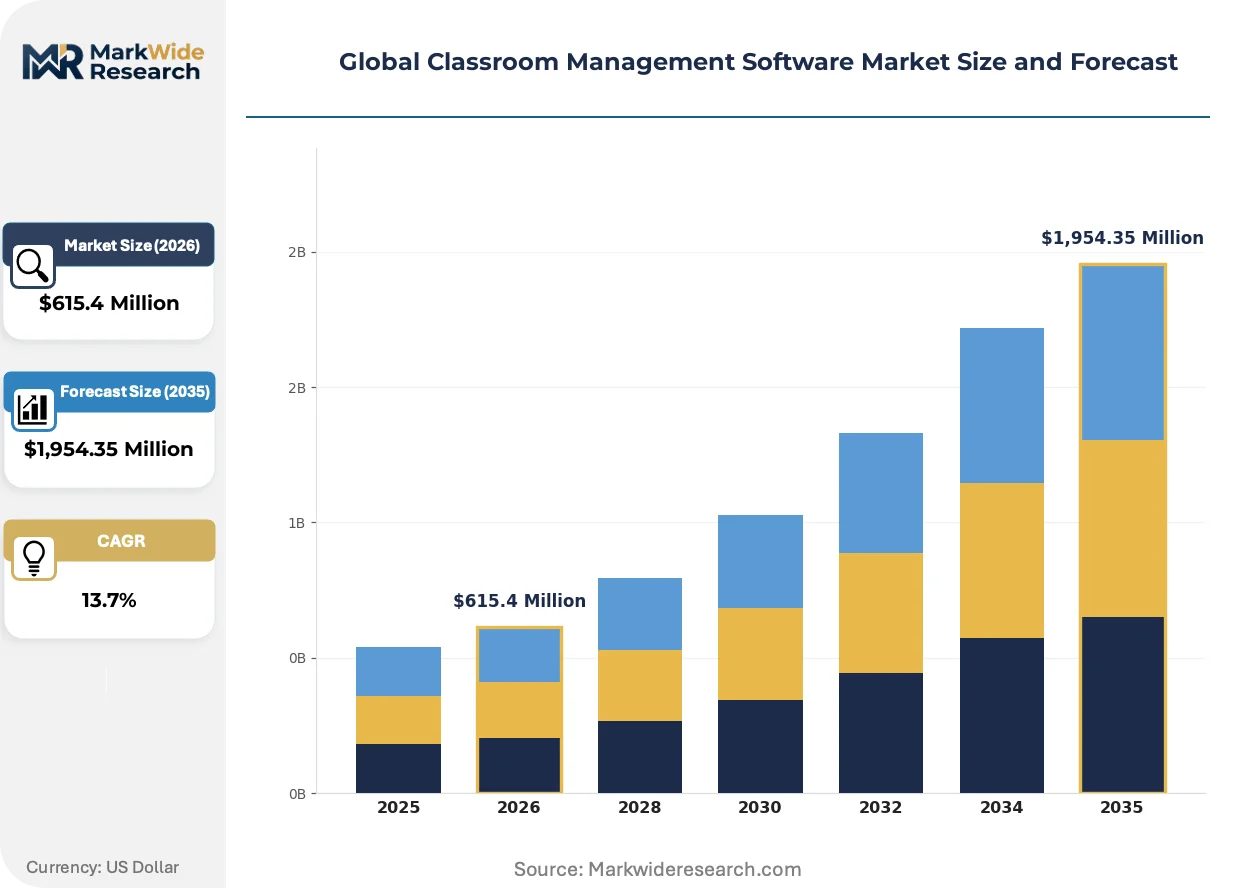
| Market Size in 2026 | $615.4 Million |
| Market Size in 2035 | $1,954.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based Solution Type: Device Control, Screen Monitoring, Content Filtering, Student Collaboration, Assessment Tools Application: K-12 Education, Higher Education, Corporate Training, Distance Learning, Vocational Training End User: Schools, Universities, Training Centers, Online Educators, Tutoring Services |
| Companies Covered | Google LLC, Microsoft Corporation, Apple Inc., Blackboard Inc., ClassDojo Inc., D2L Corporation, Instructure Inc., Faronics Corporation, NetSupport Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Classroom Management Software Market Shifts & Advancements
Artificial intelligence inference at the edge is rewriting real-time classroom analytics. Vendors race to embed behavioral prediction models without triggering cross-border data transfer restrictions.
Edge-deployed machine learning is integrating computer vision for attention-tracking and engagement scoring. United States districts with one-to-one device programs pilot these capabilities in high-stakes testing environments. The technology is integrating formative assessment data streams with automated intervention recommendations, compressing the feedback loop between observation and instructional adjustment.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on emotion recognition features in educational software. Vendors serving European markets must document training data provenance and algorithmic transparency. French and German authorities lead enforcement, with Dutch and Spanish regulators building specialized EdTech inspection capacities.
District purchasing cooperatives are consolidating procurement authority across multiple municipalities. United States intermediate service agencies in Texas and New York negotiate enterprise licenses on behalf of dozens of member districts. This concentration shifts bargaining power toward buyers and pressures point-solution vendors to join established platform marketplaces or exit the segment entirely.
Global Classroom Management Software Market Segmentation
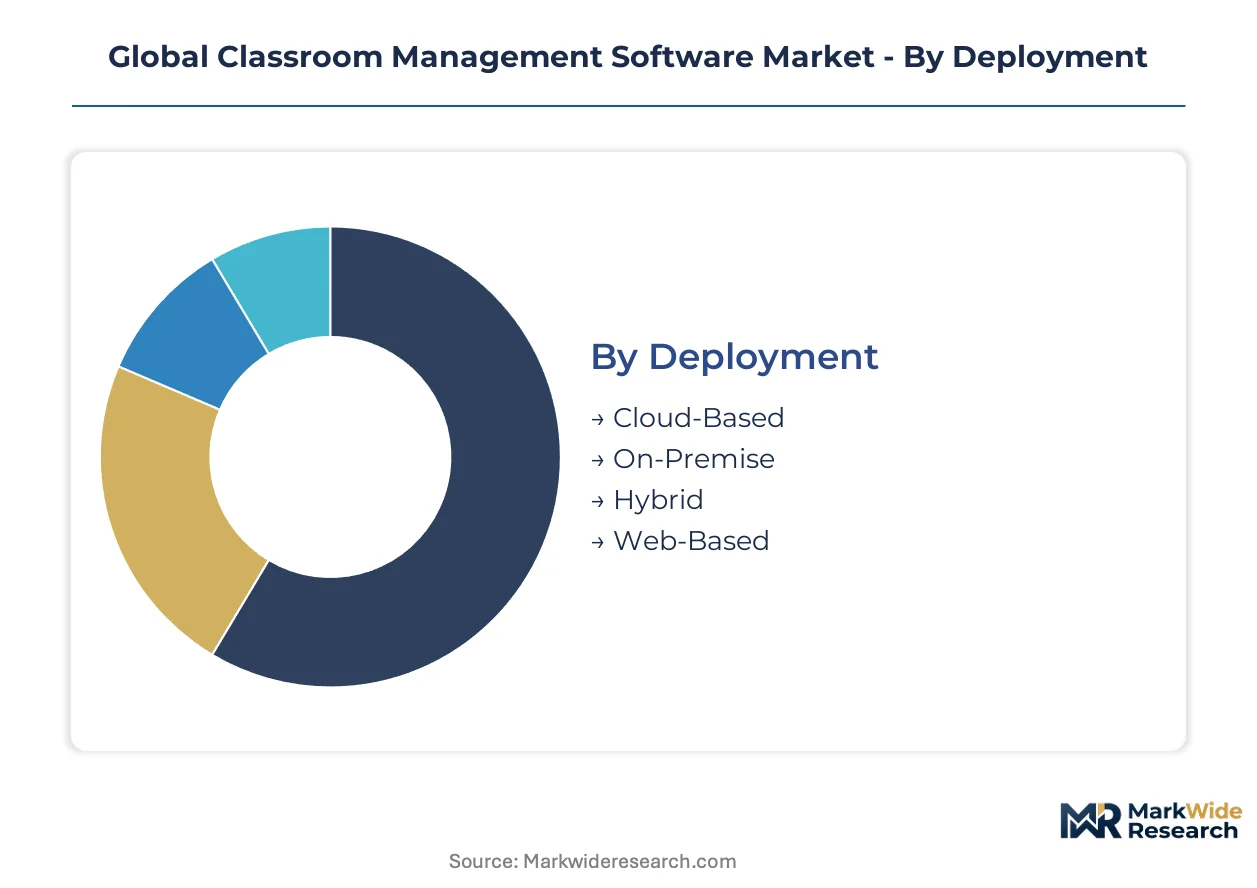
District procurement patterns fragment the classroom management software landscape across deployment architectures, functional modules, and institutional tiers. Vendor positioning requires precise alignment with how specific segments concentrate purchasing authority and technical requirements.
Deployment:
Supply concentration in hyperscale infrastructure is compressing deployment options toward browser-native delivery models.
- Cloud-Based:SaaS architectures eliminate server maintenance burdens for district IT departments. United States K-12 districts leverage E-Rate subsidies to accelerate cloud migration, with state-level digital learning mandates reinforcing procurement velocity.
- Web-Based:Progressive Web App standards enable zero-install deployment through standard browsers. Brazilian and Mexican channel partners penetrate price-sensitive municipalities without requiring dedicated IT staff for client distribution.
- Hybrid:Combines local caching with cloud orchestration for bandwidth-constrained environments.
- On-Premise:Persists in French and United Kingdom municipalities with decades-old student information systems resisting API modernization.
Cloud-Based absorbs the bulk of installed capacity; Web-Based is expanding most quickly.
Solution Type:
Functional specialization creates tiered pricing architectures based on Learning Management System interoperability depth.
- Assessment Tools:Native LTI Advantage certification commands premium licensing due to formative data integration demands. District RFP specifications increasingly prioritize these capabilities over standalone classroom oversight functions.
- Device Control:Real-time screen broadcasting with sub-200 millisecond latency thresholds anchors core platform value. Rural broadband gaps in Australia and Canada constrain feature adoption in dispersed geographies.
- Screen Monitoring:Computer vision integration for attention-tracking pilots in high-stakes testing environments.
- Content Filtering:GDPR enforcement networks impose granular student data processing requirements on filtering logic.
- Student Collaboration:WebRTC standards enable synchronous document editing without client installation friction.
Assessment Tools concentrate vendor R&D investment; Device Control maintains the largest addressable base.
Application:
End-use diversification is reshaping product roadmaps as workforce reskilling budgets outpace traditional education procurement cycles.
- Corporate Training:German and Japanese workforce development programs repurpose classroom architectures for certification delivery. Enterprise buyers demand enterprise-grade compliance tooling absent in K-12 procurement.
- K-12 Education:One-to-one device saturation in United States districts expands management software licensing attach rates. Federal connectivity subsidies compress hardware refresh timelines.
- Higher Education:Multi-tenant deployment requirements for university system consolidations.
- Distance Learning:Browser-native standards eliminate geographic constraints on instructor-student synchronous interaction.
- Vocational Training:EU AI Act risk classifications reshape emotion recognition feature deployment in skills assessment.
K-12 Education retains the deepest installed base; Corporate Training shows the steepest expansion trajectory.
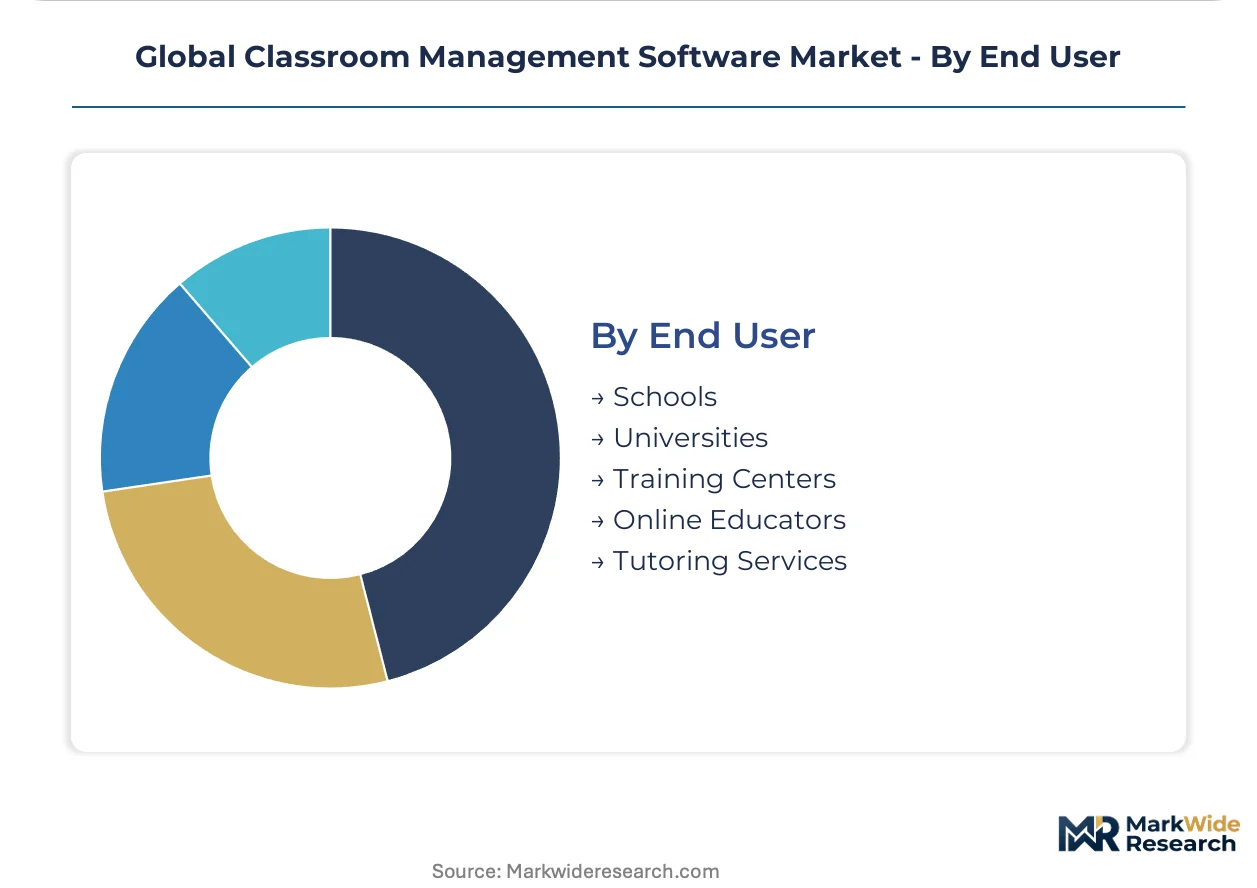
End User:
Purchasing authority consolidation across cooperative intermediaries is compressing vendor access to individual institutions.
- Schools:United States intermediate service agencies in Texas and New York negotiate enterprise licenses spanning dozens of member districts. Platform bundling favors integrated suites over point solutions.
- Training Centers:India's BIS digital standards framework imposes localization requirements on software architecture. Compliance tooling functions as competitive moat for multi-jurisdictional contracts.
- Universities:Legacy system coexistence demands consume disproportionate middleware development resources.
- Online Educators:Free native OS parental controls absorb basic oversight functions in price-sensitive segments.
- Tutoring Services:Browser-mediated dashboards reduce technical support dependency for small-scale operators.
Schools dominate procurement volume; Training Centers are gaining share fastest through workforce policy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and Western Europe while consumption spreads across K-12 districts globally. Procurement authority tilts toward national education ministries and consolidated purchasing cooperatives. Regulatory fragmentation forces vendors to maintain multiple compliance architectures.
United States
E-Rate program subsidies compress hardware refresh timelines across 13,000 districts. State-level digital learning mandates in Texas and New York accelerate cloud procurement cycles. Intermediate service agencies in Austin and Albany negotiate enterprise licenses spanning dozens of member districts.
Germany
Workforce reskilling budgets outpace K-12 procurement through federal employment agency programs. The EU AI Act's risk classification system imposes conformity assessments on emotion recognition features. Berlin and Munich host specialized EdTech inspection capacities building enforcement expertise.
India
BIS digital standards framework imposes localization requirements on software architecture for 1.5 million schools. State-level digital learning missions in Karnataka and Telangana drive district modernization. Hyderabad and Bangalore clusters concentrate vendor development centers serving domestic and export markets.
United Kingdom
Decades-old student information systems in municipal authorities resist API modernization. GDPR enforcement through the Information Commissioner's Office drives replacement of legacy on-premise installations. London and Manchester purchasing cooperatives consolidate procurement authority across multi-academy trusts.
Japan
METI workforce development programs repurpose classroom architectures for enterprise certification delivery. GIGA School Program device saturation expands management software licensing attach rates. Tokyo and Osaka districts pilot edge-deployed machine learning for high-stakes testing environments.
Global Classroom Management Software Market Competitive Landscape
The competitive structure tilts toward platform ecosystem dominance over point-solution specialization. Three tiers have crystallized: hyperscale cloud providers with education verticals, dedicated education technology vendors with deep LMS integration, and regional specialists serving compliance-constrained markets. Dominant moves include strategic partnerships with purchasing cooperatives and portfolio diversification into workforce training segments.
Within the hyperscale tier, Google LLC and Microsoft Corporation anchor platform bundling strategies that embed classroom management within broader productivity workflows. Apple Inc. occupies a premium positioning vector through proprietary hardware-software cohesion. These three exemplify how compliance architecture now functions as competitive moat rather than cost center for multi-jurisdictional contracts.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Apple Inc. |
| Blackboard Inc. |
| ClassDojo Inc. |
| D2L Corporation |
| Instructure Inc. |
| Faronics Corporation |
| NetSupport Ltd. |
| Others |
Supply & Pricing Matrix
Platform-native versus standalone deployment bifurcation manifests in divergent pricing architectures and supply chain configurations across the classroom management software landscape. SaaS-native vendors leverage hyperscale infrastructure to compress delivery costs while point-solution providers absorb disproportionate middleware development burdens in legacy system integrations.
Pricing Analysis
Margin tightening in assessment-tool tiers reflects LTI Advantage certification scarcity and the engineering premium commanded by formative-data interoperability. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance depth, with EU AI Act conformity assessment modules anchoring top-tier positioning. Price differentiation hinges on audit-grade data lineage documentation and real-time latency performance. Private school segments exhibit acute price sensitivity to free native-OS alternatives, while consolidated purchasing cooperatives in Texas and New York extract volume discounts from platform bundling.
Supply Chain Analysis
Reverse-logistics flows for Chromebook refresh cycles and tablet redeployment create secondary hardware markets that constrain concurrent software licensing expansion. Cloud infrastructure concentrates in United States hyperscale regions and European data-sovereignty zones, with latency-sensitive edge deployments tethered to municipal broadband hubs. Semiconductor memory and ARM-based processor supply draw from Taiwan, South Korea, and China, exposing procurement timelines to single-source vulnerability in advanced node fabrication. Distribution runs through channel partners in Brazil and Mexico for zero-install WebRTC deployment, bypassing IT staff dependency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Browser-native standards and edge-deployed machine learning are displacing client-based architectures, compressing vendor differentiation windows as districts abandon installation-dependent legacy systems.
For Market Incumbents: Lock in cooperative purchasing authority by embedding compliance tooling for GDPR enforcement networks and EU AI Act risk classifications directly into platform bundles. Deepen LMS interoperability investments to raise switching costs against standalone assessment-tool entrants. Vertical integration into edge-computing infrastructure for sub-200 millisecond latency guarantees defends against hyperscale cloud provider encroachment.
For New Entrants and Emerging Players: The EU AI Act's conformity assessment obligations in France and Germany open a window for specialized audit-automation modules that incumbent platforms lack. Target vocational training segments in Japan and corporate reskilling programs in Germany where workforce development budgets outpace K-12 procurement cycles. Lead with browser-native Progressive Web App deployment to penetrate price-sensitive municipalities without dedicated IT staff.
For Investors and Strategic Acquirers: Re-rating potential sits with compliance-specialist vendors given GDPR enforcement network expansion and the EU AI Act's documentation requirements. Long-term viability favors platforms with multi-jurisdictional certification depth rather than single-market point solutions. Monitor district purchasing cooperative consolidation in United States intermediate service agencies as an inflection indicator for pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding classroom management within Google Workspace for Education or Microsoft Azure ecosystems captures district bundling preferences. |
| Compliance Certification Investment | LTI 1.3 Advantage and OneRoster credentials unlock enterprise cooperative procurement contracts in Texas and New York. |
| Geographic Expansion | Channel partner networks in Brazil and Mexico accelerate penetration through WebRTC-based zero-install deployment models. |
| Acquisition of Specialist Firm | Computer vision attention-tracking capabilities address high-stakes testing pilots in United States one-to-one device districts. |
| Strategic Partnership | Alliances with hyperscale cloud providers secure data-sovereignty hosting for GDPR-constrained European municipality contracts. |
Research Methodology
Multi-period observation of E-Rate subsidy disbursement patterns, district hardware refresh timelines, and LMS procurement specifications anchored the trend analysis, supplemented by interviews with K-12 IT directors, EdTech procurement officers at intermediate service agencies, platform integration engineers, channel partners in Latin America, and compliance specialists for EU data protection authorities. Secondary validation drew from United States Department of Education connectivity program filings, EU AI Act implementation guidance, India's BIS digital standards documentation, and IMS Global certification registries. Bottom-up district-level adoption modeling triangulated against top-down vendor revenue segmentation.
Input-output matrices mapped deployment architecture choices to procurement authority concentration across cooperative intermediaries. Segmentation dimensions modeled encompassed cloud versus on-premise infrastructure, assessment-tool versus device-control functional modules, K-12 versus corporate training end-use, and regional regulatory framework clusters. CAGRs were derived from installed-base expansion rates and licensing attach-rate progression across the projection horizon. Forecast inputs incorporated E-Rate funding trajectory assumptions and EU AI Act enforcement phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for edge-deployed machine learning inference would alter the outlook if rural broadband infrastructure gaps in Australia and Canada resolve faster than projected. Forecasts reflect underlying assumptions about district consolidation velocity and hyperscale platform bundling persistence. Practitioners should monitor intermediate service agency license negotiation outcomes and EU AI Act conformity assessment timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Corporate Learning Management System Market