
 Global Mobile Learning Market | 2026-2036
Global Mobile Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Learning Market Foresight
Enterprise learning teams is rotating toward deskless and frontline worker populations as the fastest-growing buyer archetype in mobile learning procurement. SAP SE leverages deep ERP integration to anchor corporate training workflows inside existing enterprise systems. Microsoft Corporation competes through cloud-native infrastructure that sustains real-time collaboration across distributed workforces. Adobe Inc. differentiates via creative-content authoring tools that dominate multimedia course production for brand-sensitive employers.
Mobile learning denotes educational-content delivery through portable connected devices, typically requiring responsive interfaces, offline synchronization, and adaptive bitrate streaming to function across variable network conditions. Its primary commercial purpose is to extend training and credentialing access beyond fixed-location classrooms to geographically dispersed or time-constrained learners. Smartphone delivery leads volume in developing markets where single-device ownership prevails, while corporate training commands premium pricing through customized compliance and certification pathways. Gamified modules represent the fastest-growing content type as employers seek measurable engagement metrics from shortened attention spans.
Governments in multiple geographies are tightening oversight: the EU AI Act and GDPR constrain automated tutoring algorithms and cross-border student data flows, while India's TRAI and BIS influence device standards and connectivity pricing that shape platform accessibility. Compliance with these overlapping frameworks now determines market-access eligibility for multinational content providers. Stakeholders must monitor regulatory divergence between data-localization mandates and portability requirements when architecting delivery infrastructure.
Market Dynamics
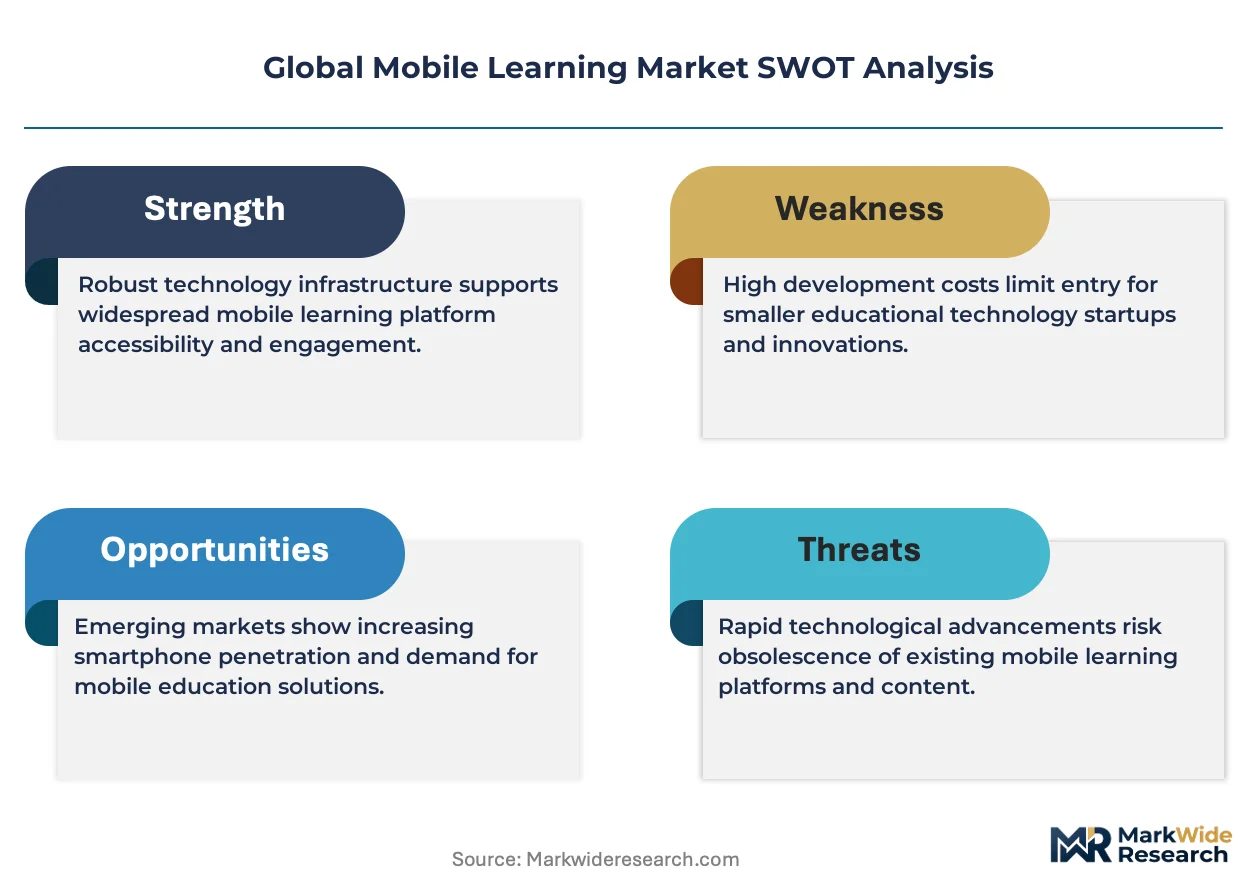
The Global Mobile Learning Market is restructuring around compliance-driven procurement decisions as GDPR, EU AI Act, and India's TRAI rules force platform providers to architect multi-jurisdictional data infrastructure before securing enterprise contracts.
Growth Catalysts
- India's Digital India campaign:Government subsidies for rural broadband and affordable 4G smartphones from domestic manufacturers are expanding addressable learner populations beyond urban centers.
- Gamified microlearning modules:Employers in logistics and retail sectors are mandating bite-sized certification content that delivers measurable engagement metrics through completion tracking.
- GDPR Article 44 adequacy decisions:Cross-border data transfer mechanisms are enabling EU-headquartered corporations to standardize mobile training deployments across subsidiary networks.
Market Restraints
- Content localization costs:Translation and cultural adaptation for India's 22 scheduled languages and China's regional dialects inflate per-course development budgets by 40-60%.
- Device fragmentation:Entry-level Android handsets with sub-2GB RAM dominate rural India and sub-Saharan Africa, constraining rich-media course delivery.
- EU AI Act algorithmic auditing:Automated tutoring systems with adaptive learning engines face mandatory conformity assessments before market entry.
Strategic Opportunities
- Indonesia's outer island provinces:Papua, Maluku, and Nusa Tenggara Timur show sub-15% corporate training penetration with expanding 4G coverage from state-owned Telkomsel.
- AR-enabled field maintenance training:Overlay instructions on industrial equipment through smartphone cameras are converging with 5G low-latency streaming.
- Brazil's ANVISA remote certification pathway:Regulatory acceptance of mobile-delivered continuing medical education creates channel entry for healthcare-focused platforms.
Industry Challenges
- Instructional design talent scarcity:Shortage of professionals combining pedagogical credentials with mobile UX expertise delays course development cycles.
- Legacy LMS integration friction:SAP and Oracle on-premise installations require middleware development for real-time progress synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Learning Market |
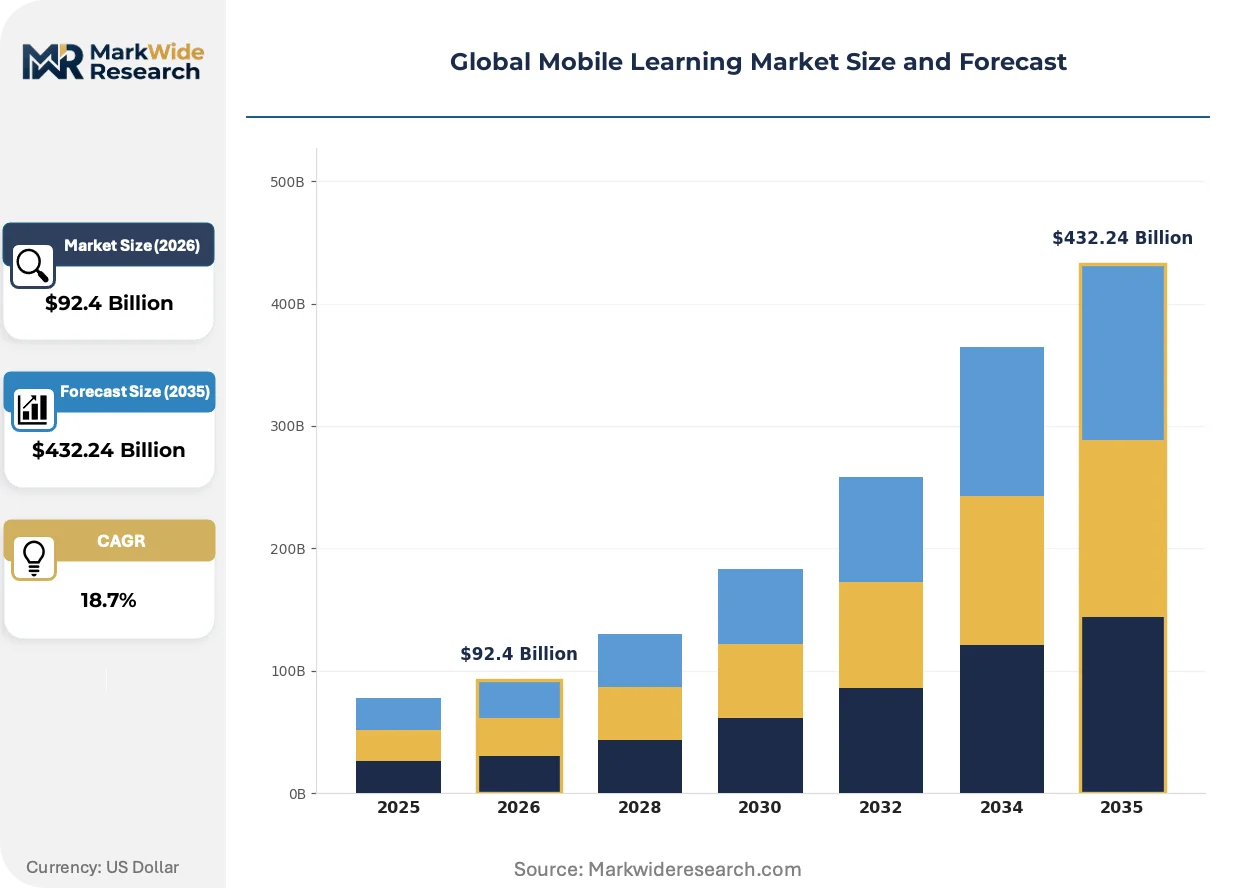
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $432.24 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Platform: Smartphones, Tablets, Laptops, Wearable Devices, Phablets Use Case: Corporate Training, K-12 Education, Higher Education, Skill Development, Language Learning Content Type: Video Tutorials, Interactive Quizzes, Gamified Modules, E-books, Podcasts Customer Segment: Enterprises, Educational Institutions, Government Agencies, Non-Profit Organizations, Freelancers |
| Companies Covered | SAP SE, Microsoft Corporation, Adobe Inc., Skillsoft Corporation, Cisco Systems Inc., Dell Inc., Upside Learning Solutions Pvt. Ltd., Coursera Inc., Udemy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Learning Market Shifts & Advancements
Generative AI is compressing content production timelines while regulatory fragmentation forces architectural decisions that prioritize compliance over feature velocity.
Adaptive bitrate streaming with offline-first caching is displacing always-connected course delivery models. Manufacturing and logistics employers with distributed workforces in India and Brazil are adopting this architecture aggressively. The technology is displacing premium-priced dedicated learning hardware previously required for remote site training.
The EU AI Act's risk-based classification system mandates human oversight for high-stakes automated tutoring decisions. EdTech providers must redesign algorithmic recommendation engines to include explainable output pathways. Corporate procurement teams in Germany and France are now requiring AI Act conformity documentation before contract execution.
Employer procurement committees are consolidating vendor relationships from fragmented point solutions to integrated talent platforms. Human resource departments are replacing standalone mobile learning contracts with bundled workforce development suites. This pattern is most visible in North American Fortune 500 enterprises seeking unified skills taxonomy across hiring, training, and succession planning.
Global Mobile Learning Market Segmentation
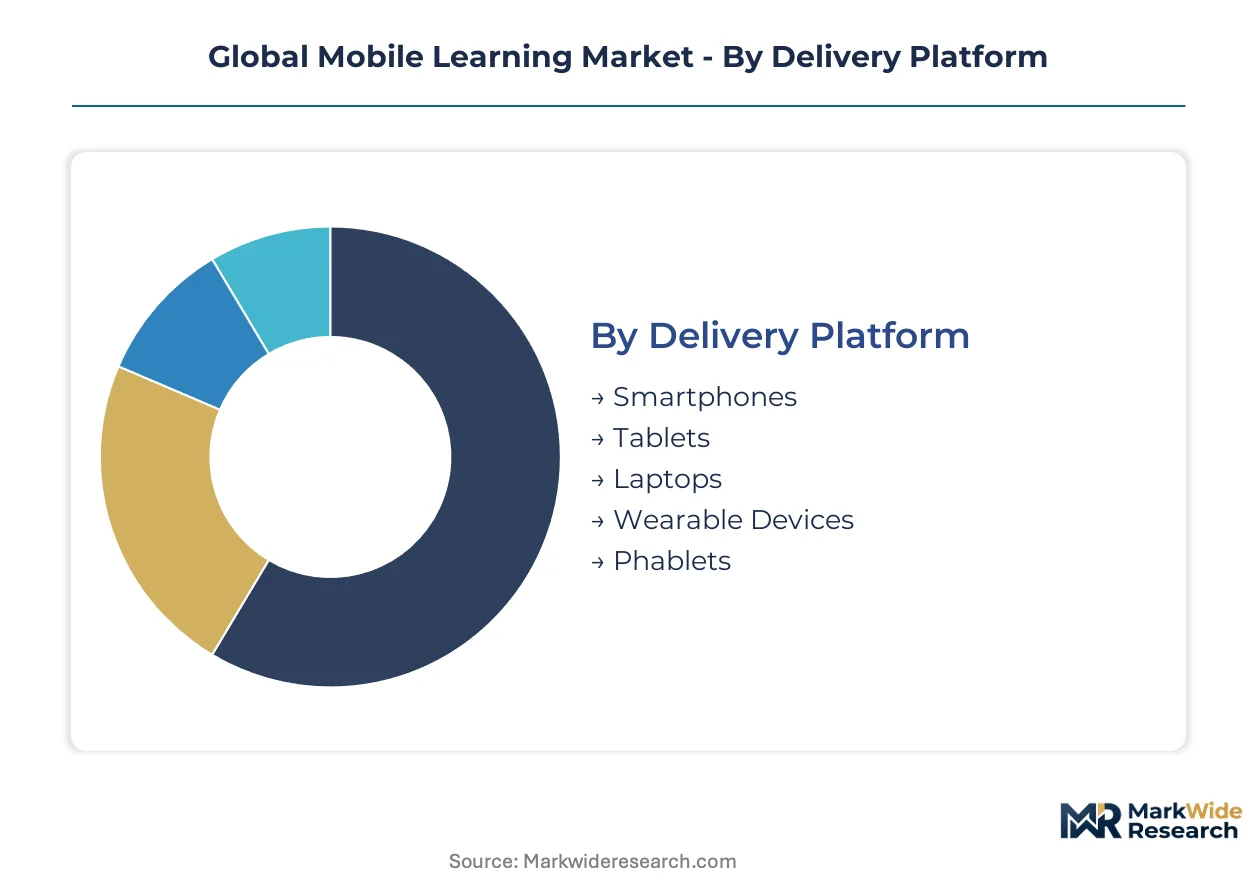
Segmentation in mobile learning reveals how procurement priorities diverge between compliance-driven enterprises and access-focused education systems. Platform choice and content format decisions increasingly hinge on connectivity constraints in target geographies rather than feature sophistication alone.
Delivery Platform:
Margin pools concentrate in smartphone-optimized architectures where single-device ownership dominates developing-market procurement.
- Smartphones:Android and iOS handsets with responsive HTML5 interfaces handle variable network conditions through adaptive bitrate streaming. India's rural broadband expansion and Indonesia's Telkomsel 4G rollout are concentrating demand among deskless workforces requiring offline synchronization capabilities.
- Tablets:Larger-screen devices support stylus-based annotation and split-screen multitasking for technical documentation review. K-12 systems in Brazil and higher education institutions in South Korea are standardizing on tablet-dominant deployments where device subsidies offset hardware costs.
- Laptops:Full-keyboard form factors persist in corporate environments requiring extensive data entry or coding instruction.
- Wearable Devices:Smartwatches and AR glasses deliver microlearning notifications and hands-free guidance for logistics and field maintenance workflows.
- Phablets:6-7 inch hybrid devices bridge smartphone portability with tablet readability for language learning applications.
Smartphones hold installed capacity. Tablets are rotating up the share rankings.
Use Case:
Application intensity varies sharply between mandatory compliance training and voluntary skill acquisition.
- Corporate Training:Customized certification pathways with SCORM-compliant tracking integrate directly into SAP and Oracle HR systems. GDPR Article 44 adequacy decisions are enabling EU-headquartered corporations to standardize deployments across subsidiary networks in Germany, France, and the Netherlands.
- Skill Development:Bite-sized microlearning modules with completion metrics address shortened attention spans in logistics and retail sectors. Brazil's ANVISA regulatory acceptance of mobile-delivered continuing education is accelerating healthcare-focused platform adoption.
- K-12 Education:Curriculum-aligned content requires alignment with national standards and parental oversight controls.
- Higher Education:Degree-credit courses demand proctored assessment integration and learning management system compatibility.
- Language Learning:Speech recognition and spaced repetition algorithms target consumer subscription revenue in urban India and Southeast Asian markets.
Corporate Training commands premium pricing. Skill Development is expanding most quickly.
Content Type:
Production economics favor formats with reusable asset libraries and automated localization pipelines.
- Gamified Modules:Points, badges, and leaderboards generate measurable engagement metrics that satisfy procurement committee reporting requirements. Employers in India's manufacturing corridors are mandating gamified safety certification to replace paper-based compliance tracking.
- Video Tutorials:MP4 delivery with offline caching dominates technical training where visual demonstration outperforms text description. Sub-2GB RAM device constraints in rural India and sub-Saharan Africa are forcing compression trade-offs between resolution and accessibility.
- Interactive Quizzes:Branching scenario assessments support adaptive learning paths with immediate feedback loops.
- E-books:Reflowable EPUB formats minimize data transfer costs for text-heavy policy and procedure documentation.
- Podcasts:Audio-only delivery targets commuting learners with low-bandwidth requirements and multilingual dubbing flexibility.
Video Tutorials hold installed capacity. Gamified Modules are gaining share fastest.
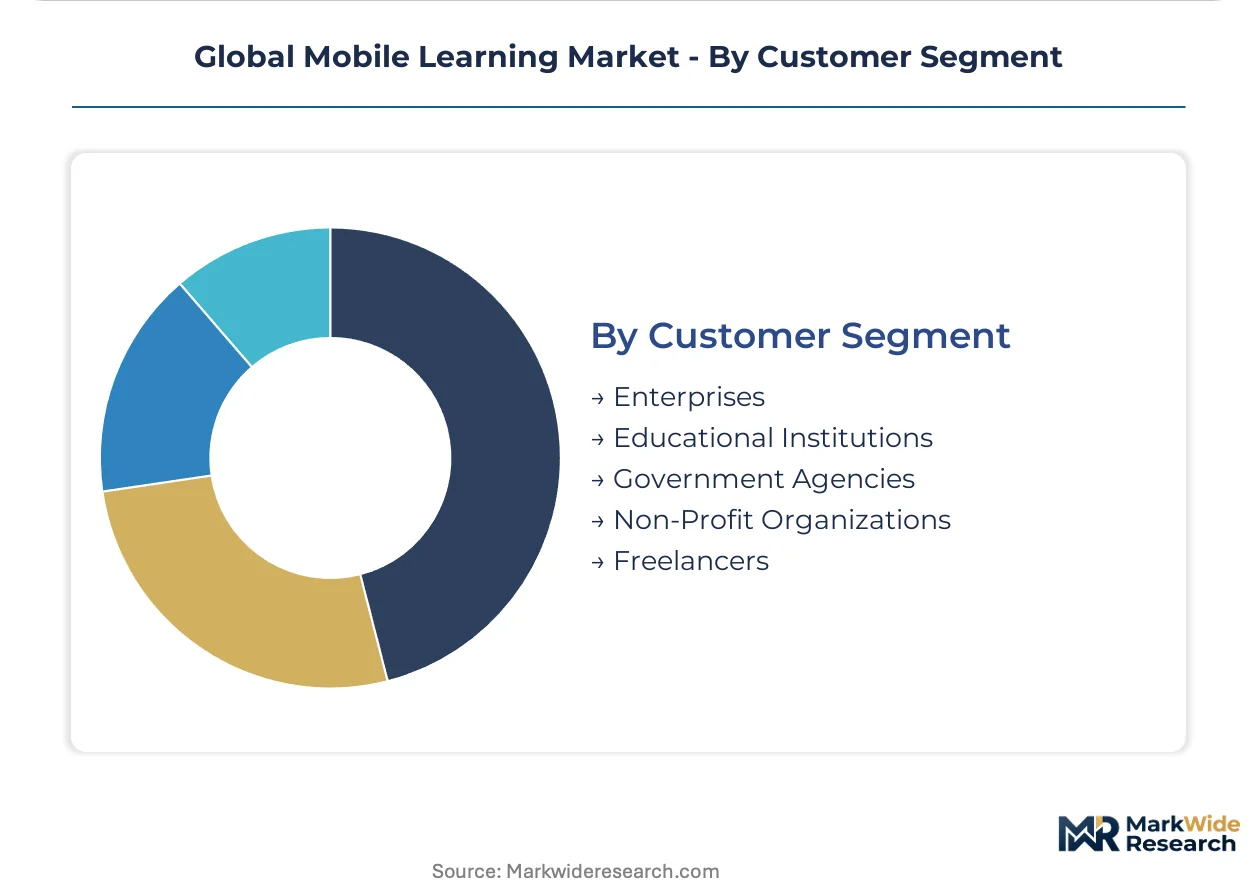
Customer Segment:
Budget authority and procurement cycle length differentiate institutional buyers from individual purchasers.
- Enterprises:Multi-year contracts with customized compliance pathways and API integration requirements dominate revenue concentration. North American Fortune 500 procurement committees are consolidating fragmented point solutions into bundled workforce development suites.
- Educational Institutions:K-12 and university systems negotiate volume licensing with accessibility mandates and student data privacy provisions. India's Digital India campaign subsidies are expanding addressable populations beyond urban centers into rural Maharashtra and Uttar Pradesh.
- Government Agencies:Public-sector training mandates require adherence to national data-localization standards and accessibility regulations.
- Non-Profit Organizations:Grant-funded deployments prioritize low-cost feature phones and SMS-based delivery for last-mile reach.
- Freelancers:Individual subscription purchases drive consumer app store revenue with high churn and price sensitivity.
Enterprises anchor contract value. Educational Institutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise learning teams in India and Brazil are driving procurement volume for deskless-worker training platforms. Compliance mandates from EU regulators and India's TRAI are reshaping data-infrastructure requirements for multinational content providers. Geographic expansion now hinges on localized connectivity solutions rather than feature sophistication alone.
United States
Fortune 500 procurement committees are consolidating fragmented learning contracts into bundled workforce development suites. OSHA and FCC regulations govern remote certification protocols for logistics and field maintenance applications. Texas and California enterprise corridors anchor demand for SAP-integrated compliance training systems.
Germany
Industrial employers mandate GDPR Article 44 conformity documentation before mobile training contract execution. The EU AI Act requires human oversight loops for automated tutoring algorithms used in manufacturing certification. Bavaria's automotive clusters deploy AR-enabled maintenance training through 5G low-latency infrastructure.
India
TRAI connectivity pricing and BIS device standards shape platform accessibility across rural Maharashtra and Uttar Pradesh. Digital India campaign subsidies expand addressable learner populations beyond urban centers into tier-3 cities. Domestic smartphone manufacturers supply sub-$100 4G handsets that dominate enterprise rollout programs.
Brazil
ANVISA regulatory acceptance of mobile-delivered continuing medical education accelerates healthcare-focused platform adoption. Logistics and retail sectors mandate gamified microlearning modules with completion tracking for distributed workforces. São Paulo's corporate training market commands premium pricing for customized compliance pathways.
Indonesia
Telkomsel's 4G expansion into Papua, Maluku, and Nusa Tenggara Timur creates channel entry where corporate training penetration remains below 15%. State-owned infrastructure investments reduce connectivity pricing barriers for platform providers. Jakarta-based enterprise headquarters pilot smartphone-optimized architectures for subsequent outer-island deployment.
Global Mobile Learning Market Competitive Landscape
Player mix skews toward enterprise software incumbents with deep ERP integration capabilities. SAP SE and Microsoft Corporation anchor procurement decisions through existing IT infrastructure relationships. Three strategic archetypes dominate: ERP-integrated suite providers, cloud-native collaboration platforms, and specialized content authoring tool vendors. Competitive moves concentrate on middleware development for legacy LMS synchronization and multi-jurisdictional data infrastructure architecture.
Among ERP-integrated incumbents, SAP SE represents the enterprise workflow anchoring archetype through deep human capital management system penetration. Microsoft Corporation exemplifies cloud-native infrastructure competition with real-time collaboration capabilities across distributed workforces. Adobe Inc. occupies a position within creative-content authoring, dominating multimedia course production for brand-sensitive employers. These three companies illustrate how procurement committees prioritize existing vendor relationships over point-solution functionality when consolidating training budgets.
| Leading Market Players |
|---|
| SAP SE |
| Microsoft Corporation |
| Adobe Inc. |
| Skillsoft Corporation |
| Cisco Systems Inc. |
| Dell Inc. |
| Upside Learning Solutions Pvt. Ltd. |
| Coursera Inc. |
| Udemy Inc. |
| Others |
Supply & Pricing Matrix
Multi-year enterprise subscription contracts lock in supply access for platform providers while anchoring price visibility through tiered user-count commitments. India's TRAI-mandated connectivity pricing and GDPR Article 44 adequacy requirements force vendors to absorb compliance infrastructure costs into contract structures.
Pricing Analysis
Cost-plus contracts with cloud infrastructure indexation dominate enterprise procurement, tying SaaS subscription tiers to hyperscaler compute pricing. Three-tier pricing structure across premium, standard, and economy levels separates API-integrated compliance pathways from self-service content libraries. Pricing pressure stems from India's government-subsidized rural broadband programs compressing margins for localized delivery. Fortune 500 procurement committees demonstrate lowest price sensitivity, while educational institutions in tier-3 Indian cities and Indonesian outer islands exhibit acute cost consciousness.
Supply Chain Analysis
India and the United States anchor content production pipelines, with Bangalore and Austin hosting instructional design studios that feed multilingual asset libraries. Cloud infrastructure draws from hyperscaler regions in Ireland, Singapore, and Virginia, while device manufacturing rests on Shenzhen and Hanoi assembly lines for sub-$100 4G handsets. Single-source vulnerability concentrates in AWS and Azure hosting dependencies for EU data-localization compliance. Distribution runs through direct enterprise sales teams and mobile carrier bundling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile learning platforms represent a service-attach opportunity where recurring content licensing and compliance-update subscriptions expand faster than initial platform deployment fees. The shift from perpetual licenses to consumption-based models concentrates lifetime value in post-sale revenue layers.
For Market Incumbents: Compound ERP integration advantages by deepening middleware development for legacy SAP and Oracle synchronization, while acquiring specialized instructional design boutiques to address talent scarcity. GDPR and EU AI Act conformity documentation requirements threaten margin erosion for vendors lacking pre-certified algorithmic auditing capabilities. Vertical integration into offline-first caching technology preserves pricing power in India's sub-2GB RAM device segments. For New Entrants and Emerging Players: Lead with AR-enabled field maintenance modules targeting Indonesia's Papua and Maluku provinces where corporate training penetration remains below 15 percent and Telkomsel 4G expansion creates first-mover windows. Brazil's ANVISA regulatory acceptance of mobile-delivered continuing medical education offers the most penetrable healthcare segment. Channel entry through state-owned Telkomsel enterprise sales partnerships bypasses direct procurement committee friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platforms with embedded compliance-update subscriptions tied to GDPR and sectoral data-protection rule changes. Long-term viability across the 5-10 year window favors vendors with multi-jurisdictional data infrastructure already deployed. Acquisition targets should demonstrate proven localization pipelines for India's 22 scheduled languages. The signal to watch is consolidation velocity among North American Fortune 500 procurement committees migrating from point solutions to bundled workforce development suites.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Data Infrastructure Buildout | GDPR Article 44 adequacy decisions and India's data-localization mandates determine contract eligibility for EU-headquartered corporations. |
| Offline-First Caching Architecture Deployment | Adaptive bitrate streaming with synchronization capabilities displaces premium learning hardware in India's manufacturing corridors. |
| AR-Enabled Field Maintenance Module Launch | Smartphone camera overlays converging with 5G low-latency infrastructure target Bavaria's automotive clusters and Brazilian logistics hubs. |
| Instructional Design Studio Acquisition | Pedagogical-UX talent scarcity delays course development cycles for gamified microlearning certification content. |
| Hyperscaler Cloud Partnership Expansion | AWS, Azure, and Google Cloud regional instances anchor compliance infrastructure for EU AI Act algorithmic auditing requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief learning officers, enterprise IT procurement managers, instructional design directors, and mobile platform engineers. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, TRAI regulatory circulars, and EU AI Act implementation guidance documents. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against aggregate enterprise training spend produced convergent market sizing.
Across the analysis window, forecasts model delivery platform segmentation, use case intensity, content format economics, and customer segment procurement cycle length. CAGRs derive from logistic adoption curves fitted to smartphone penetration trajectories and enterprise SaaS transition patterns. India Digital India campaign subsidy schedules and Indonesia Telkomsel 4G rollout timelines inform geographic expansion assumptions.
The analysis sits within stated boundaries; outcomes outside sustained rural broadband expansion in India, continued GDPR enforcement stringency, and stable hyperscaler pricing would require recalibration. Forecasts reflect documented assumptions regarding device fragmentation constraints and algorithmic auditing compliance timelines. Recalibration cycles align with material shifts in EU AI Act implementation guidance and India's BIS device standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Global Training Software Market