
 Managed Learning Service Market | 2026-2036
Managed Learning Service Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Learning Service Market Analysis
EU CSRD disclosure requirements for workforce skill metrics is restructuring procurement priorities across continental enterprises. SAP Litmos leverages its embedded analytics architecture to sustain compliance-driven contracts in DACH markets. Cornerstone OnDemand anchors North American presence through multi-tenant infrastructure serving Fortune 500 reskilling programs. 360Learning competes via collaborative authoring tools that reduce content production cycles for decentralized HR departments.
Managed learning services encompass the outsourced design, delivery, administration, and measurement of enterprise training programs through cloud-hosted platforms with SCORM/xAPI interoperability, AI-driven competency mapping, and real-time skills gap analytics. These systems integrate learning management systems, content repositories, and assessment engines to optimize workforce capability against operational targets. Content Development captures premium margin pools where bespoke regulatory and technical curricula command annual retainers, while Virtual Classroom delivery exhibits fastest trajectory as distributed workforces normalize synchronous remote instruction. Large Corporations dominate client type revenue through multi-year managed training outsourcing agreements spanning leadership pipelines and digital upskilling mandates.
FDA quality system regulation for pharmaceutical training documentation, EU AI Act risk-classification requirements for automated tutoring systems, and OSHA hazard-specific instruction mandates collectively elevate audit-ready platform demand. Compliance architecture now functions as a primary vendor selection filter rather than secondary feature. Stakeholders must evaluate whether provider data residency configurations align with emerging sector-specific AI governance before committing to platform migrations.
Market Dynamics
ISO 30414 human capital reporting standards are restructuring enterprise procurement priorities, forcing learning service providers to embed audit-ready analytics and skills-gap telemetry directly into platform architectures.
Growth Catalysts
- Federal workforce reskilling mandates:United States government procurement channels now require xAPI-compliant learning record stores for all civilian training contracts, expanding addressable market for managed service providers.
- EU CSRD disclosure requirements:Workforce skill metrics reporting obligations are triggering enterprise migrations from legacy LMS to integrated managed learning platforms with embedded compliance dashboards.
- AI-driven competency mapping:Machine learning algorithms that auto-tag content against evolving role taxonomies are compressing content curation cycles from months to weeks.
Market Restraints
- Data residency configuration costs:EU AI Act risk-classification requirements for automated tutoring systems force providers to maintain region-specific infrastructure, elevating capital intensity.
- SCORM interoperability lock-in:Technical debt from two decades of proprietary learning object packaging creates friction during platform migrations, extending sales cycles.
- Substitution by in-house L&D teams:Large technology enterprises with captive instructional design capabilities are repatriating content development rather than outsourcing.
Strategic Opportunities
- Underpenetrated mid-market segment:Organizations with 500-5,000 employees currently rely on fragmented point solutions, presenting consolidation opportunity for unified managed service offerings.
- OSHA hazard-specific instruction mandates:Manufacturing and logistics verticals face expanding compliance training obligations that favor outsourced specialized content production.
- Convergence of VR and haptic feedback:Immersive simulation technologies for high-risk procedural training are opening premium service tiers in energy and healthcare verticals.
Industry Challenges
- Instructional designer talent scarcity:Shortage of professionals capable of authoring both regulatory-compliant technical content and adaptive learning pathways limits platform content velocity.
- Legacy HRIS integration complexity:Enterprise customers demand seamless API connections to decades-old personnel systems, requiring costly custom engineering for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Learning Service Market |
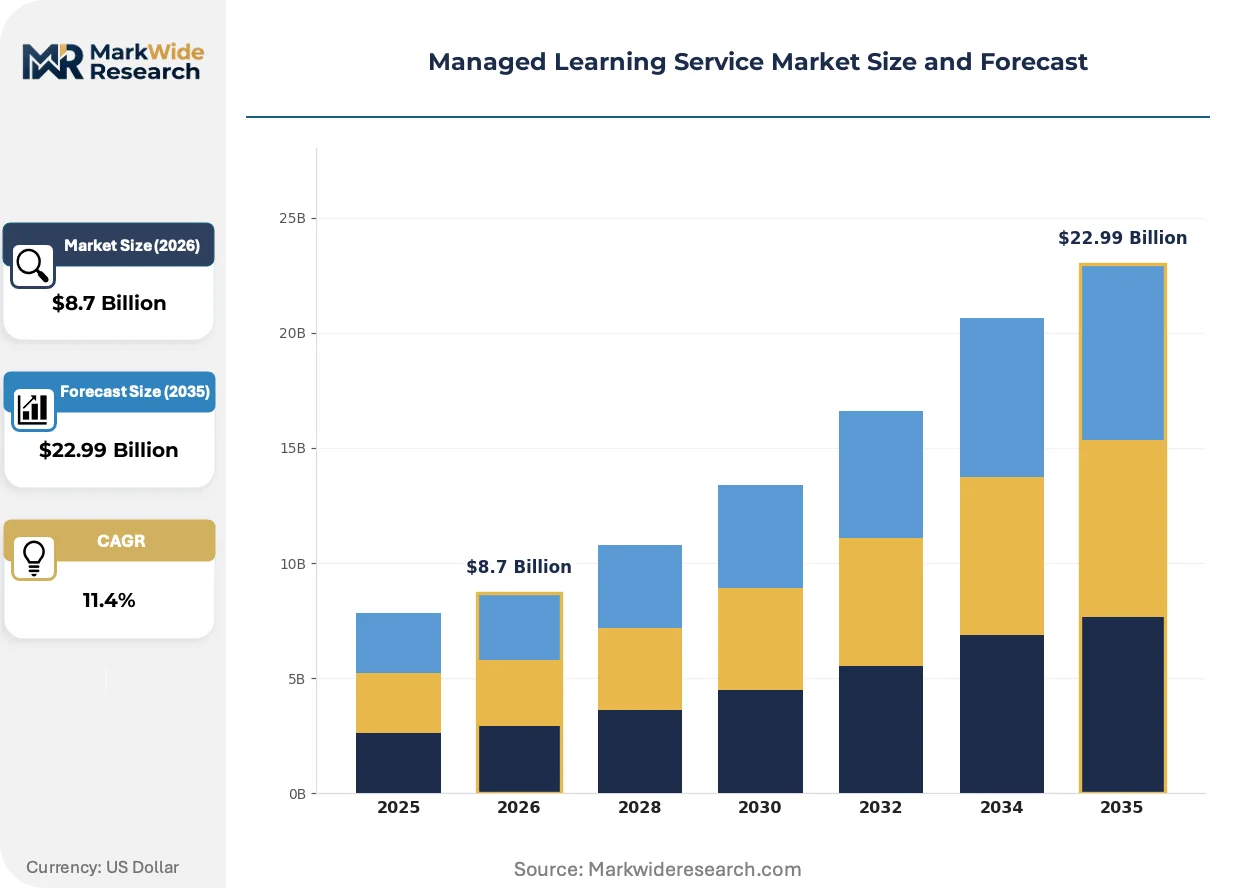
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Content Development, Learning Delivery, Learning Management, Assessment Services Industry Vertical: Corporate Training, K-12 Education, Higher Education, Healthcare Delivery Model: Blended Learning, On-Demand Learning, Instructor-Led Training, Virtual Classroom Client Type: Small Enterprises, Large Corporations, Government Agencies, Non-Profit Organizations |
| Companies Covered | SAP Litmos, 360Learning, Docebo, D2L Brightspace, LearnUpon, Absorb LMS, TalentLMS, Cornerstone OnDemand, CYPHER Learning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Learning Service Market Emerging Trajectories
Generative AI is compressing content production timelines while synchronous remote instruction modalities are displacing asynchronous self-paced modules as the default enterprise delivery mechanism.
Collaborative authoring environments with real-time co-editing and version control are decentralizing content production authority from centralized L&D departments to distributed subject matter experts. Manufacturing and professional services firms are deploying these tools at scale, enabling plant managers and practice leads to generate audit-ready training modules without instructional design intermediation. This shift is compressing content update cycles from quarterly to weekly rhythms while elevating platform stickiness through embedded workflow integration.
The EU AI Act risk-classification framework for automated tutoring systems is mandating algorithmic transparency documentation and human-in-the-loop oversight protocols. Providers serving European multinationals must now maintain technical files demonstrating conformity assessment procedures for adaptive learning pathways. Pharmaceutical and financial services verticals face the steepest compliance burdens, driving procurement toward vendors with pre-certified quality management systems.
Enterprise buyers are unbundling content development from platform licensing, contracting directly with freelance instructional design networks while retaining managed service providers for infrastructure and analytics. This disintermediation is visible most acutely in technology and consulting sectors where internal content studios already exist. Vendors responding with modular pricing for analytics-only tiers are capturing retention in accounts that would otherwise churn to pure-play authoring tools.
Managed Learning Service Market Segmentation
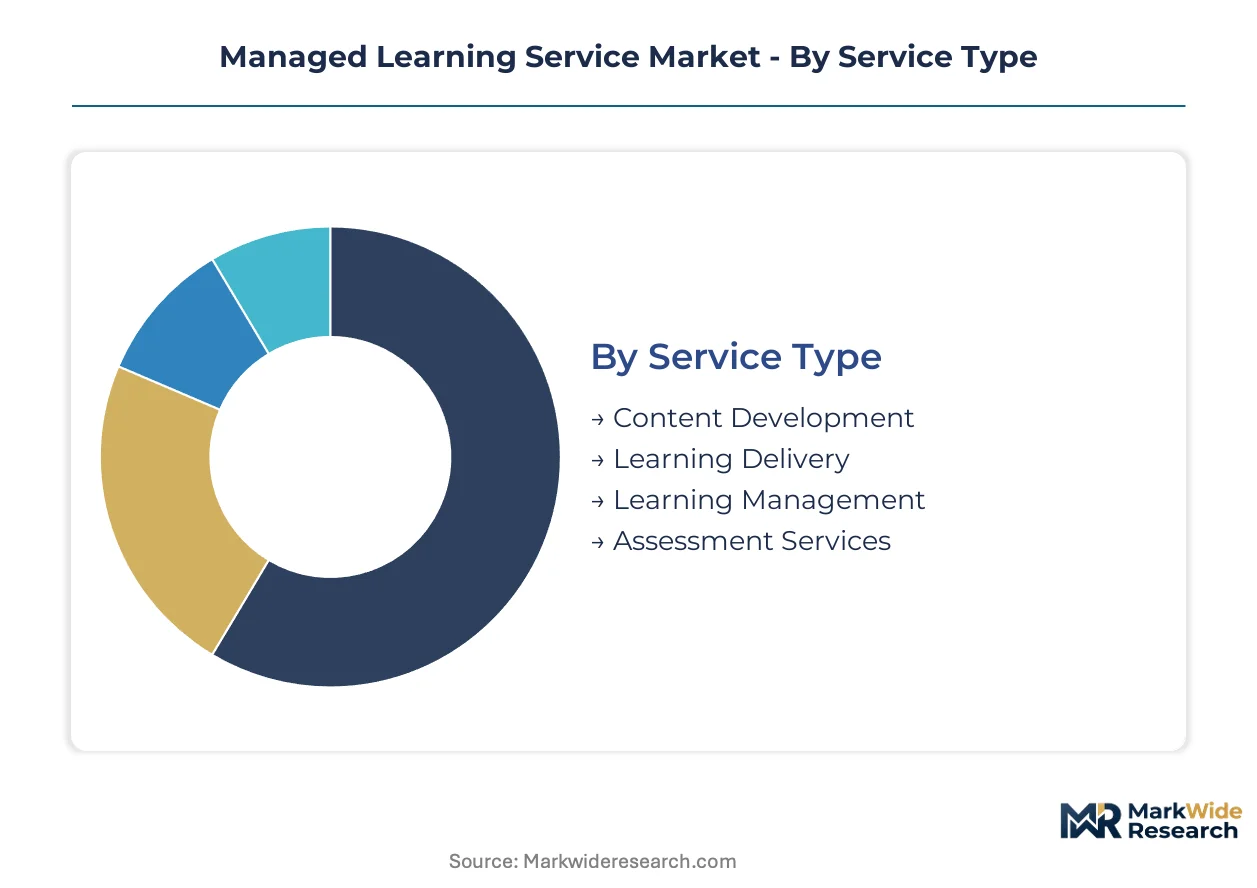
Managed learning services fragment across four structural dimensions that determine procurement patterns and vendor economics. Each category carries distinct margin profiles and integration requirements that shape competitive positioning.
Service Type:
Supply concentration in high-margin technical content production creates tiered vendor capabilities across the value chain.
- Content Development:Bespoke regulatory and technical curricula command annual retainers through specialized instructional design labor. Pharmaceutical and energy verticals in Germany and the United States drive premium demand for FDA and OSHA-compliant documentation modules.
- Learning Delivery:Synchronous remote instruction modalities are displacing asynchronous self-paced modules as default enterprise mechanisms. Distributed workforces across United States federal agencies and European multinationals normalize virtual classroom procurement.
- Learning Management:Cloud-hosted platforms with SCORM/xAPI interoperability anchor multi-year outsourcing agreements.
- Assessment Services:AI-driven competency mapping and skills-gap telemetry embed directly into audit-ready architectures.
Today's leader: Content Development. Tomorrow's challenger: Learning Delivery.
Industry Vertical:
Cost tier differentiation separates compliance-heavy regulated sectors from discretionary training budgets in education.
- Corporate Training:ISO 30414 human capital reporting standards and EU CSRD disclosure requirements restructure procurement priorities. European multinationals migrate from legacy LMS to integrated platforms with embedded compliance dashboards.
- Healthcare:FDA quality system regulation for pharmaceutical training documentation elevates audit-ready platform demand. Medical device manufacturers in the United States and Switzerland face steepest documentation burdens.
- Higher Education:Accreditation-driven assessment protocols favor established providers with regional certification relationships.
- K-12 Education:Public funding constraints limit addressable market to supplemental digital curriculum services.
Corporate Training captures dominant revenue share. Healthcare offers steepest expansion trajectory.
Delivery Model:
Volume concentration shifts toward synchronous modalities as distributed workforces stabilize post-pandemic operational rhythms.
- Virtual Classroom:Real-time remote instruction with integrated assessment tools compresses content update cycles from quarterly to weekly. Manufacturing and professional services firms deploy collaborative authoring environments at scale.
- Blended Learning:Hybrid modalities combining synchronous sessions with self-paced modules optimize seat-time efficiency for technical certification programs.
- Instructor-Led Training:Face-to-face delivery persists for high-risk procedural training in energy and healthcare verticals where haptic feedback requirements dominate.
- On-Demand Learning:Asynchronous libraries serve compliance refresh requirements and just-in-time skill acquisition.
Virtual Classroom is gaining share fastest. Blended Learning defends installed base.
Client Type:
Customer type determines contract duration and platform customization intensity across the market.
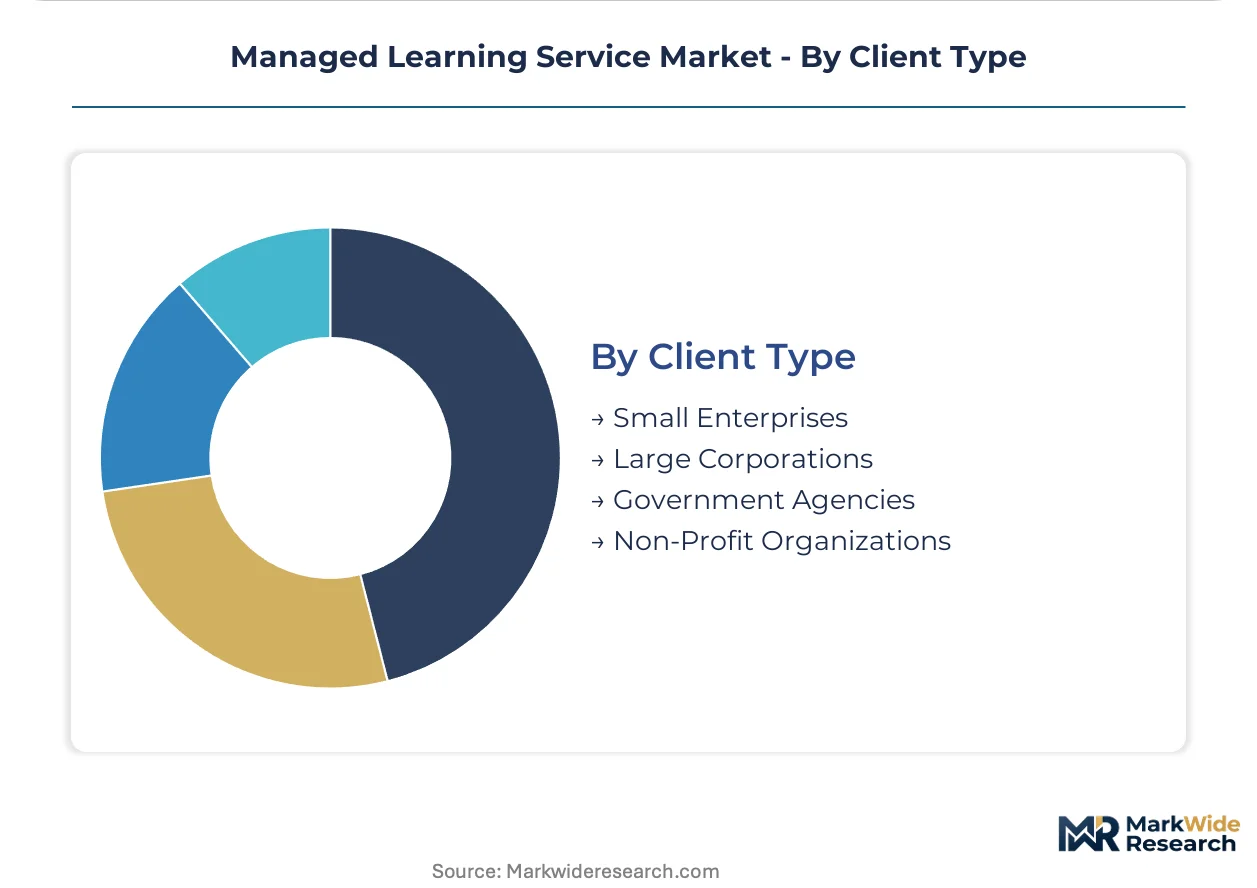
- Large Corporations:Multi-year managed training outsourcing agreements span leadership pipelines and digital upskilling mandates. Fortune 500 reskilling programs in the United States anchor North American demand concentration.
- Government Agencies:Federal workforce reskilling mandates require xAPI-compliant learning record stores for all civilian training contracts.
- Small Enterprises:Organizations with 500-5,000 employees rely on fragmented point solutions, presenting consolidation opportunity for unified managed service offerings.
- Non-Profit Organizations:Grant-dependent budgets favor modular analytics-only tiers over comprehensive platform licensing.
Large Corporations dominate contract value. Government Agencies drive standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal workforce reskilling mandates in the United States anchor procurement volume for xAPI-compliant learning record stores. European multinationals under CSRD disclosure obligations drive platform migration toward integrated compliance dashboards.
United States
Fortune 500 reskilling programs and federal civilian training contracts concentrate demand in cloud-hosted managed learning platforms. OSHA hazard-specific instruction mandates for manufacturing and logistics elevate specialized content production requirements. Greater Boston and the San Francisco Bay Area host dense clusters of instructional design talent serving pharmaceutical and technology verticals.
Germany
ISO 30414 human capital reporting standards gain traction among DACH-region industrial conglomerates restructuring procurement priorities. EU AI Act risk-classification requirements for automated tutoring systems force providers to maintain region-specific infrastructure. Bavaria and Baden-Württemberg anchor automotive and precision engineering training demand through embedded analytics architectures.
United Kingdom
Financial services firms facing FCA conduct rules drive audit-ready platform procurement for competency documentation. GDPR data residency configurations elevate capital intensity for providers serving London-headquartered multinationals. The City of London and Manchester metropolitan area concentrate fintech and professional services training budgets.
Switzerland
Swissmedic pharmaceutical documentation requirements intersect with FDA quality system regulation for medical device manufacturers. Precision manufacturing and life sciences clusters in Basel and Zurich generate premium demand for regulatory-compliant technical curricula. Bilingual training delivery mandates across German and French cantons favor providers with localized content capabilities.
India
IT services exporters and GCC captive centers drive scalable managed learning procurement for digital upskilling at volume. BIS standards for skill certification create compliance overlay for technical training programs. Bengaluru and Hyderabad anchor delivery center concentration where collaborative authoring tools compress content production cycles.
Managed Learning Service Market Vendor Landscape
Capital-heavy platform infrastructure providers compete with asset-light content specialists across tiered service configurations. Market structure consolidates around multi-tenant cloud architectures while fragmenting across specialized instructional design boutiques. Three archetypes dominate: integrated suite vendors with embedded analytics, collaborative authoring specialists with decentralized workflow tools, and compliance-focused providers with pre-certified quality systems. Competitive dynamics center on modular pricing disaggregation and regional data residency certification.
Within the integrated suite tier, SAP Litmos and Cornerstone OnDemand exemplify providers anchoring multi-year outsourcing agreements through compliance-ready architectures. Among collaborative authoring specialists, 360Learning occupies a position representing decentralized content production authority. These named entities sit within broader competitive patterns where geographic presence in DACH markets and North American federal channels determines contract access.
| Leading Market Players |
|---|
| SAP Litmos |
| 360Learning |
| Docebo |
| D2L Brightspace |
| LearnUpon |
| Absorb LMS |
| TalentLMS |
| Cornerstone OnDemand |
| CYPHER Learning |
| Others |
Supply Flow & Price Mechanics
Instructional designer labor costs cascade through service tiers from specialized technical authoring to standardized platform administration, with FDA and EU AI Act compliance requirements elevating premium retainers for audit-ready content production while compressing margins in commoditized LMS licensing.
Pricing Analysis
Bundled platform-content-analytics packages are unbundling as enterprise buyers contract directly with freelance instructional design networks. Three-tier pricing structure across premium, standard, and economy levels separates bespoke regulatory curricula with ISO 30414 certification support from self-service authoring tools. Pricing pressure stems from in-house L&D team repatriation at technology enterprises, with small enterprises exhibiting highest price sensitivity and Fortune 500 reskilling programs demonstrating lowest.
Supply Chain Analysis
EU AI Act local-content-rule requirements for algorithmic transparency documentation are reshaping sourcing toward region-specific infrastructure investments. Platform development concentrates in the United States, Germany, and India, with cloud hosting and instructional design talent as critical inputs. Single-source vulnerability sits with specialized regulatory content authors holding FDA and Swissmedic certification. Distribution runs through direct enterprise sales teams and federal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into sustained demand, with EU CSRD disclosure obligations for workforce skill metrics restructuring procurement priorities across European multinationals.
For Market Incumbents: Deepen vertical integration into specialized instructional design talent pools to defend against freelance network disintermediation. Invest in pre-certified quality management systems for EU AI Act conformity assessment. Add Bavaria and Baden-Württemberg delivery centers to anchor DACH-region data residency compliance.
For New Entrants and Emerging Players: AI-driven competency mapping algorithms offer a technology-first wedge against established platform vendors. Target the 500-5,000 employee mid-market segment currently reliant on fragmented point solutions. Pursue OSHA hazard-specific content partnerships with manufacturing verticals as go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where compliance architecture functions as primary vendor selection filter rather than secondary feature. Five-to-ten year viability favors providers with embedded analytics and multi-tenant federal infrastructure. Acquisition target archetype: collaborative authoring specialists with decentralized workflow tools. Signal to watch: xAPI-compliant learning record store procurement volume at US federal agencies.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Architecture Certification | EU AI Act pre-certification opens DACH-region enterprise contracts with audit-ready quality systems. |
| Mid-Market Consolidation Play | Unified managed service offerings capture 500-5,000 employee organizations from fragmented point solutions. |
| Federal Channel Expansion | xAPI-compliant infrastructure secures multi-year civilian training contracts under workforce reskilling mandates. |
| Immersive Simulation Investment | VR-haptic convergence opens premium tiers for high-risk procedural training in energy and healthcare verticals. |
| Analytics-Only Tier Launch | Modular pricing retains accounts disintermediating content development to freelance instructional design networks. |
Methodological Framework
Multiple input streams — primary interviews with chief learning officers and federal procurement officers, secondary validation through SEC filings and EU regulatory databases, and trade data from hyperscaler capex disclosures — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned L&D directors at Fortune 500 manufacturers, instructional design boutique principals, and compliance officers at pharmaceutical firms. Secondary sources included FDA quality system regulation filings, EU AI Act technical documentation requirements, and OSHA hazard-specific training mandates.
Data-stream reconciliation across service type, industry vertical, delivery model, and client type segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled enterprise training budget trajectories against compliance-driven platform migration timelines. Forecast inputs incorporated ISO 30414 adoption curves among European multinationals and federal workforce reskilling procurement velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement timing and federal budget appropriation cycles. Forecasts reflect documented assumptions about regulatory adoption rates and technology substitution patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market