
 Qatar E-Learning Management System Market | 2026-2036
Qatar E-Learning Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar E-Learning Management System Market Analytics
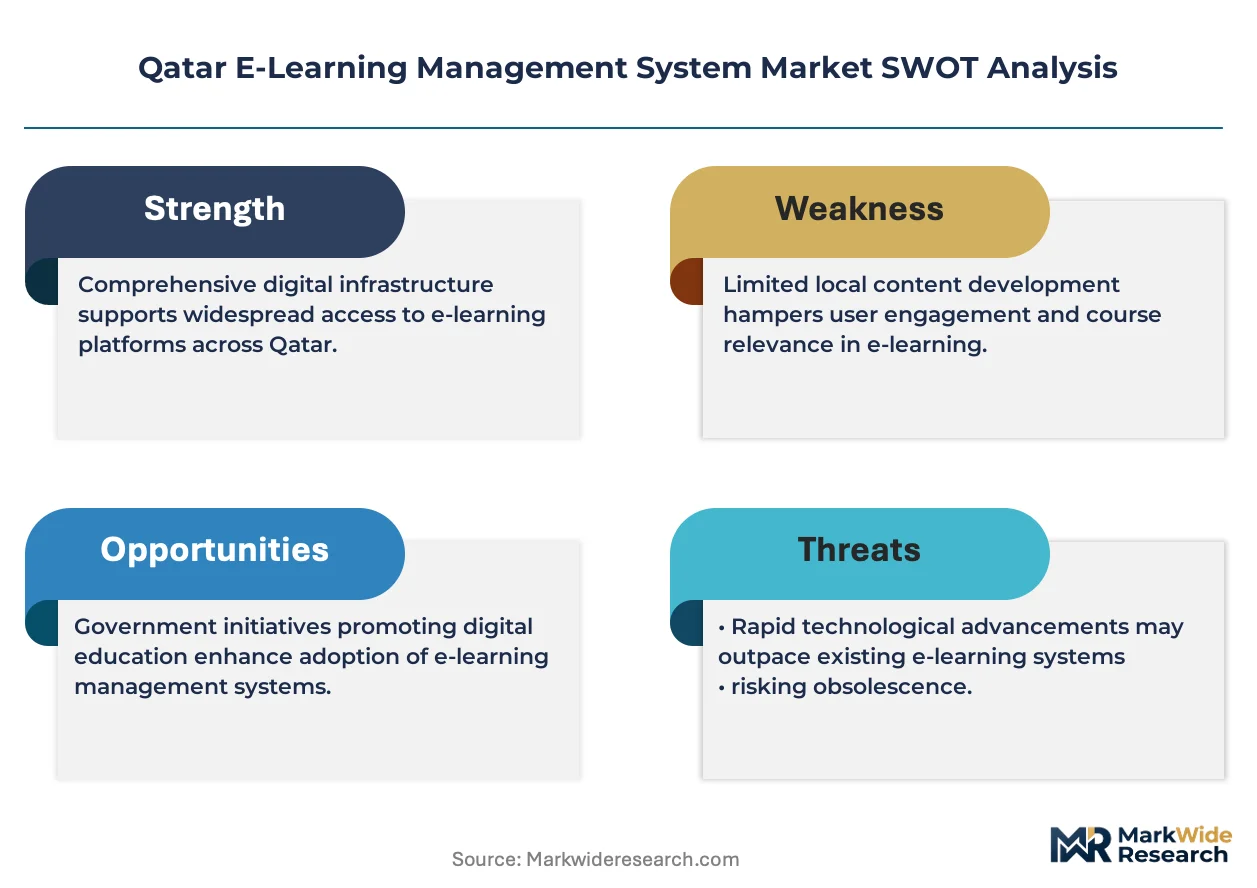
Subscription-based SaaS financing is fragmenting competitive entry barriers for mid-sized platform vendors in Qatar. Cypher Learning Inc. leverages its multi-tenant cloud architecture to serve K-12 districts across Doha and Al Wakrah. Blackboard Inc. anchors its position through deep integration partnerships with Qatar Foundation education networks. Moodle Pty. Ltd competes via open-source flexibility that reduces total cost of ownership for budget-constrained technical institutes.
An E-Learning Management System constitutes a software platform that orchestrates course administration, learner enrollment tracking, content sequencing, and competency assessment through SCORM or xAPI interoperability standards. Its primary commercial purpose centers on reducing instructor administrative burden while generating granular learning analytics for institutional accountability. Cloud-Based deployment leads segment adoption as Qatar's telecom infrastructure reaches parity with Gulf Cooperation Council benchmarks, while Virtual Classroom technology represents the fastest-expanding technology layer as hybrid instruction models persist in higher education and corporate settings. The Government end-user category sustains above-average budget allocation through civil service modernization programs tied to national development frameworks.
Qatar's communications regulator enforces data sovereignty requirements that constrain cross-border student information flows and mandate in-country server residency for educational platforms. The Ministry of Education and Higher Education imposes accreditation standards that shape procurement eligibility for LMS vendors serving public universities and technical colleges. Stakeholders must monitor evolving localization mandates and alignment with Qatar National Vision human capital targets as procurement criteria tighten.
Market Dynamics
Qatar's data sovereignty requirements and Qatar National Vision human capital mandates are compressing vendor selection criteria while accelerating cloud infrastructure deployment across education and government sectors.
Growth Catalysts
- Qatar National Vision 2030:Civil service modernization programs mandate digital competency frameworks that require scalable LMS infrastructure for workforce reskilling.
- Hybrid instruction models:Higher education institutions in Doha maintain blended learning protocols that sustain demand for virtual classroom technology layers.
- Cloud infrastructure parity:Qatar's telecom networks now match Gulf Cooperation Council benchmarks, removing latency barriers for SaaS platform adoption.
Market Restraints
- Data localization mandates:The communications regulator requires in-country server residency, increasing capital expenditure for foreign platform providers establishing Qatar operations.
- Accreditation procurement barriers:Ministry of Education and Higher Education standards restrict vendor eligibility for public university contracts to pre-qualified systems.
- Technical interoperability limitations:Legacy SCORM content repositories create migration friction when institutions transition to xAPI-based analytics platforms.
Strategic Opportunities
- Corporate training expansion:Energy sector workforce development programs in Ras Laffan Industrial City represent underpenetrated demand for specialized compliance training platforms.
- K-12 district consolidation:Independent school operators in Al Wakrah seek unified district-wide LMS deployments to replace fragmented single-school solutions.
- Artificial intelligence convergence:Adaptive learning engines combined with Arabic natural language processing create differentiation potential for regional platform developers.
Industry Challenges
- Specialized integration talent scarcity:System architects capable of bridging legacy student information systems with modern LMS APIs command premium compensation in Doha's constrained labor market.
- Multi-stakeholder procurement complexity:Qatar Foundation education networks require alignment across academic, IT, and finance departments, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar E-Learning Management System Market |
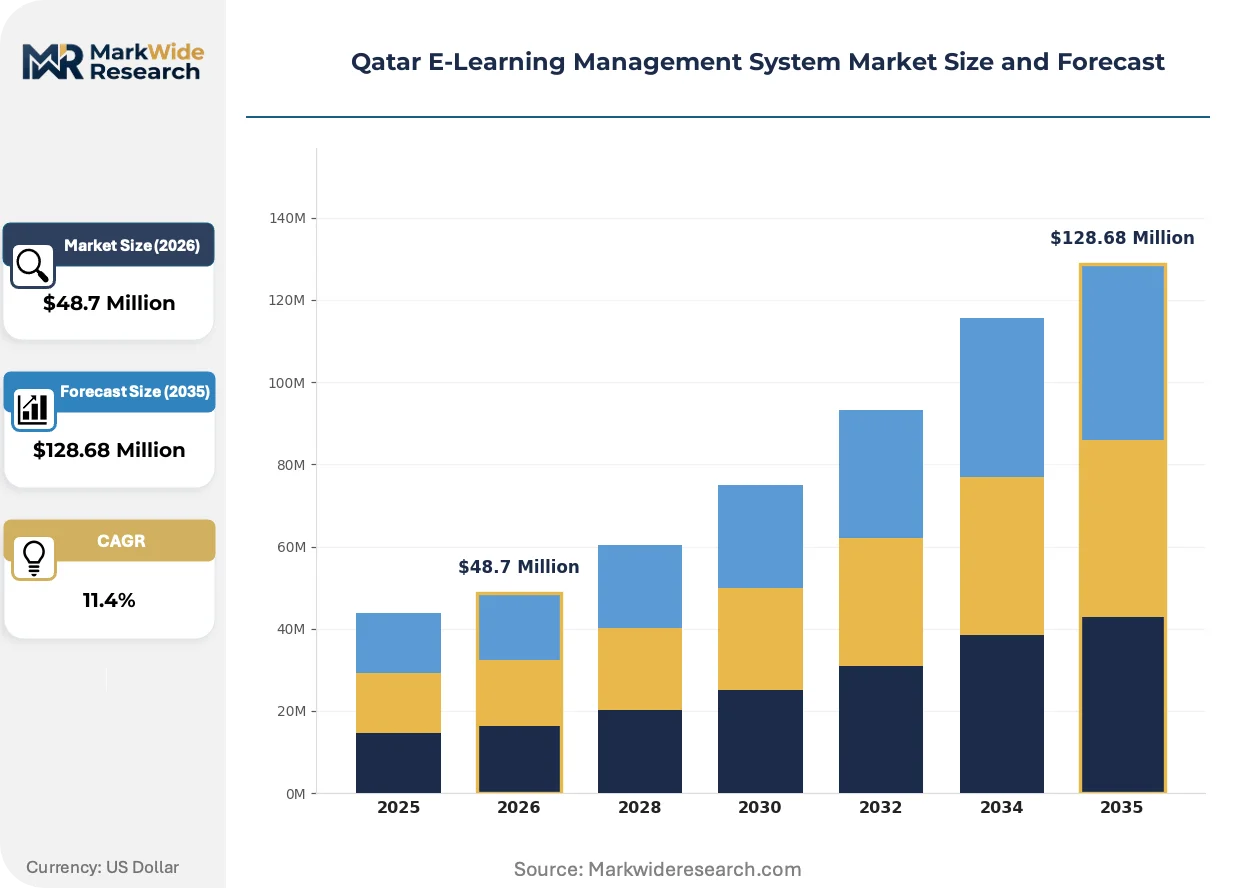
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Mobile End User: K-12 Institutions, Higher Education, Corporate, Government Technology: Learning Management Systems, Virtual Classrooms, Content Management, Assessment Tools Solution: Content Delivery, User Management, Integration Services, Analytics |
| Companies Covered | Zinger Stick Software, Cypher Learning Inc., Blackboard Inc., Ascentsoft, Moodle Pty. Ltd, Edraak, Capytech FZ LLC, Classera, Malomatia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar E-Learning Management System Market Evolving Landscape
Platform architecture decisions in Qatar are increasingly driven by regulatory compliance requirements rather than pure feature comparison, with interoperability standards and data residency capabilities becoming primary selection filters.
Virtual classroom infrastructure is migrating from supplementary meeting tools to core instructional delivery systems. Technical institutes in Doha now treat synchronous video platforms as primary learning environments rather than emergency remote teaching fallbacks. This shift is compressing vendor differentiation around real-time engagement analytics and low-bandwidth optimization for mobile-first student populations.
Communications regulator enforcement of student data sovereignty rules is hardening compliance requirements for educational technology providers. Foreign LMS vendors must establish Qatar-based server infrastructure or partner with local cloud operators to maintain procurement eligibility. Public universities are responding by prioritizing vendors with demonstrated in-country data residency architectures during tender evaluations.
Subscription financing models are displacing perpetual license structures across government and corporate training procurement. Qatar's civil service modernization programs favor multi-year SaaS agreements with outcome-based renewal criteria tied to learner completion metrics. This pattern is most visible in technical college workforce development contracts, where annual recurring revenue terms now dominate RFP specifications.
Qatar E-Learning Management System Market Segmentation
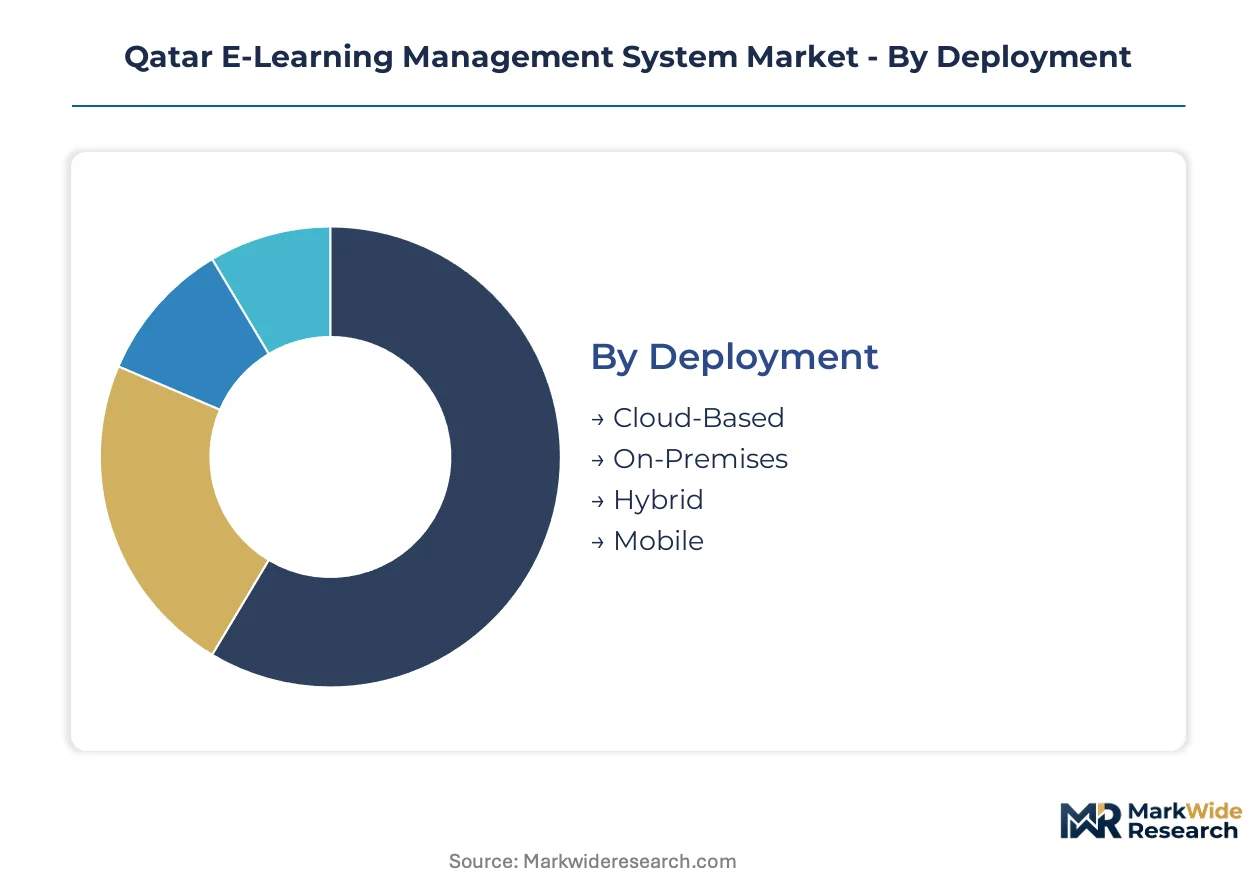
Segmentation in Qatar's E-Learning Management System market reveals how procurement criteria diverge across institutional buyer types and technical infrastructure requirements. Deployment architecture and end-user category together determine vendor eligibility and pricing structures.
Deployment:
Mature cloud architectures dominate procurement specifications, while emerging mobile-first models reshape access patterns among younger learner demographics.
- Cloud-Based:Multi-tenant SaaS platforms deliver course administration through browser-based interfaces with automatic scalability. Qatar's telecom infrastructure parity with Gulf Cooperation Council benchmarks removes latency barriers that previously constrained adoption in Doha and Al Wakrah educational districts. Government workforce development programs mandate this architecture for civil service reskilling initiatives.
- On-Premises:Self-hosted server installations within institutional data centers provide direct control over student information flows. The communications regulator's data sovereignty requirements drive demand among public universities seeking compliance without third-party server dependency.
- Hybrid:Split architectures combine local content repositories with cloud-based analytics engines. Technical institutes use this model to maintain sensitive assessment data on-site while leveraging external compute for learning analytics.
- Mobile:Native application delivery optimized for smartphone-first student populations. Qatar Foundation education networks pilot this approach for commuter students accessing coursework outside campus boundaries.
Cloud-Based deployment handles the majority of throughput; Mobile is expanding most quickly on share as smartphone penetration reaches saturation among Qatar's youth demographic.
End User:
Customer type segmentation follows budget authority concentration, with government and corporate buyers commanding multi-year contract values that dwarf individual institutional purchases.
- K-12 Institutions:District-wide unified deployments replace fragmented single-school solutions across Doha and Al Wakrah independent school operators. Ministry of Education and Higher Education accreditation standards restrict vendor eligibility to pre-qualified platform providers.
- Higher Education:Blended learning protocols at Doha universities sustain demand for virtual classroom technology layers integrated with core LMS infrastructure. Qatar Foundation education networks require multi-departmental alignment across academic, IT, and finance units.
- Corporate:Energy sector workforce development programs in Ras Laffan Industrial City seek specialized compliance training platforms. Subscription financing models with outcome-based renewal criteria now dominate RFP specifications.
- Government:Civil service modernization programs tied to Qatar National Vision 2030 mandate digital competency frameworks requiring scalable infrastructure. Above-average budget allocation persists through national development framework commitments.
Government contracts command the largest individual deal values; Corporate training shows the steepest expansion trajectory as energy sector reskilling accelerates.
Technology:
Technology layer segmentation reflects the shift from administrative record-keeping toward immersive instructional delivery systems.
- Learning Management Systems:Core platforms orchestrating course administration, learner enrollment tracking, and content sequencing through SCORM or xAPI interoperability standards. Public universities prioritize vendors with demonstrated in-country data residency architectures.
- Virtual Classrooms:Synchronous video platforms migrating from supplementary tools to primary instructional delivery environments. Real-time engagement analytics and low-bandwidth optimization differentiate vendor offerings for mobile-first student populations.
- Content Management:Repository systems for organizing learning materials with version control and access permissions. Legacy SCORM content creates migration friction when institutions transition to xAPI-based analytics platforms.
- Assessment Tools:Competency evaluation engines generating granular learning analytics for institutional accountability. Adaptive testing combined with Arabic natural language processing creates differentiation potential for regional developers.
Learning Management Systems anchor the installed base; Virtual Classrooms are gaining share fastest as hybrid instruction models persist across higher education.
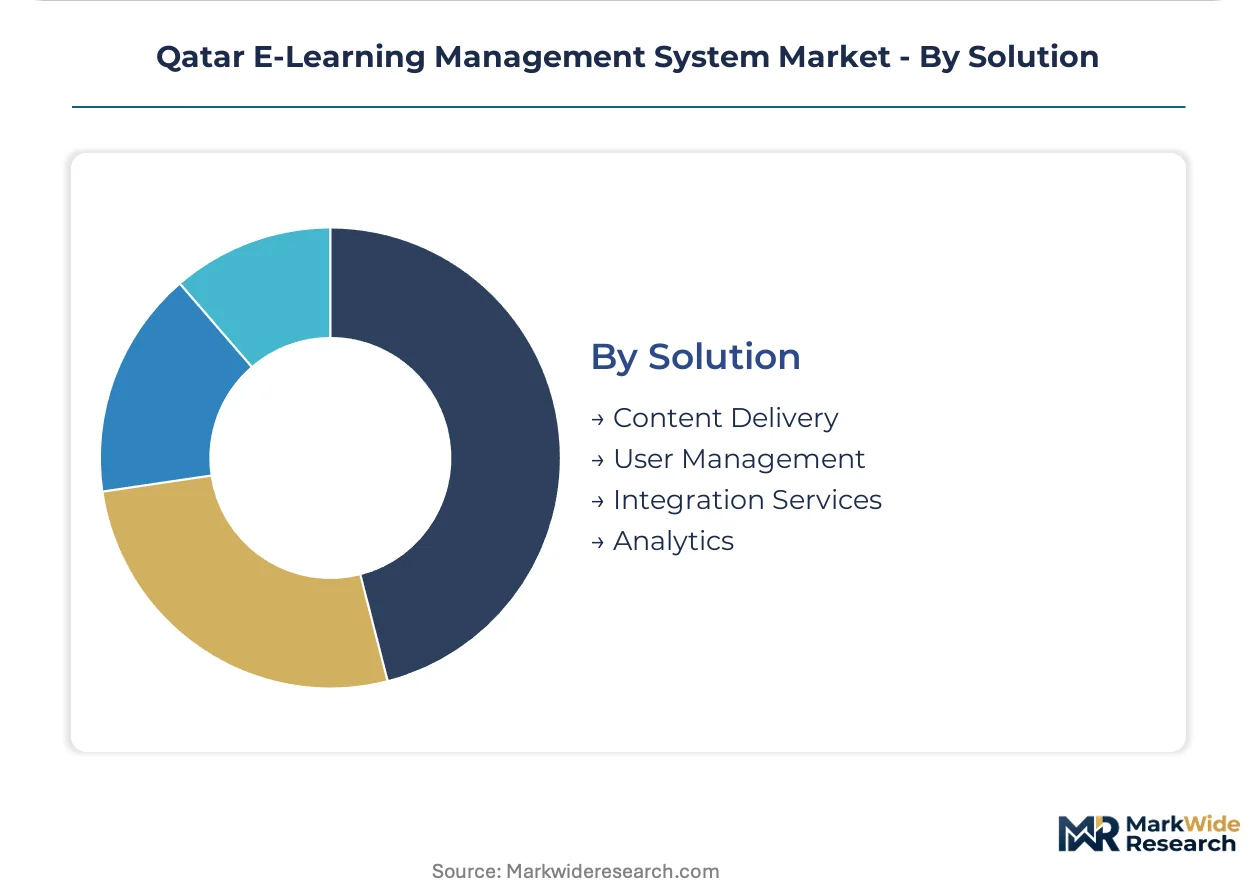
Solution:
Solution component segmentation tracks how procurement is fragmenting from monolithic suites toward modular, best-of-breed integrations.
- Content Delivery:Distribution mechanisms for video, interactive simulations, and downloadable resources optimized for Qatar's network topology. Low-bandwidth optimization capabilities determine vendor selection for mobile-first deployments.
- User Management:Identity provisioning, role-based access control, and enrollment workflows bridging with legacy student information systems. System architects capable of these integrations command premium compensation in Doha's constrained labor market.
- Integration Services:API middleware connecting LMS platforms with existing campus ERP and SIS infrastructure. Multi-stakeholder procurement complexity across Qatar Foundation networks extends sales cycles for these services.
- Analytics:Learning data visualization and predictive modeling engines feeding institutional accountability reporting. Outcome-based renewal criteria in technical college workforce development contracts tie contract value to learner completion metrics.
Content Delivery captures the largest solution spend; Analytics climbs the fastest as accountability requirements tighten across public university procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar National Vision 2030 mandates digital competency frameworks across Gulf Cooperation Council states, accelerating cloud-based LMS procurement in education and government sectors throughout the Arabian Peninsula.
Doha Metropolitan Area
Qatar Foundation education networks drive demand for multi-tenant SaaS platforms serving blended learning protocols. The Ministry of Education and Higher Education enforces accreditation standards that restrict vendor eligibility for public university contracts. Higher education institutions in Education City maintain hybrid instruction models sustaining virtual classroom technology layers.
Al Wakrah Governorate
Independent school operators seek unified district-wide LMS deployments to replace fragmented single-school solutions. The communications regulator's data sovereignty requirements mandate in-country server residency for educational platforms. K-12 districts across Al Wakrah prioritize vendors with demonstrated Arabic natural language processing capabilities.
Ras Laffan Industrial City
Energy sector workforce development programs generate specialized demand for compliance training platforms. Qatar Petroleum's civil service modernization initiatives tie contract value to learner completion metrics. Corporate training procurement in this industrial cluster favors multi-year SaaS agreements with outcome-based renewal criteria.
Al Rayyan Municipality
Technical institutes migrate from legacy SCORM content repositories toward xAPI-based analytics platforms. The Ministry of Education and Higher Education shapes procurement eligibility through pre-qualification standards for public technical colleges. Hybrid architectures combining local content repositories with cloud-based analytics engines dominate institutional preferences.
Al Khor and Al Thakhira
Government workforce development programs in northern municipalities sustain above-average budget allocation for scalable LMS infrastructure. Civil service reskilling initiatives under Qatar National Vision 2030 mandate digital competency frameworks requiring cloud deployment models. Public sector procurement in this region prioritizes vendors with established Qatar-based server infrastructure.
Qatar E-Learning Management System Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: global SaaS platforms with multi-tenant cloud architectures, open-source specialists emphasizing total cost reduction, and regional developers leveraging Arabic language capabilities. Competitive positioning hinges on data residency compliance and accreditation pre-qualification rather than pure feature differentiation. Dominant competitive moves include strategic partnerships with Qatar Foundation education networks and geographic expansion through local server infrastructure establishment.
Within the global SaaS tier, Blackboard Inc. and Cypher Learning Inc. exemplify vendors anchoring positions through deep integration partnerships with Qatar Foundation networks. Moodle Pty. Ltd occupies a distinct archetype as an open-source platform reducing total cost of ownership for budget-constrained technical institutes. These three companies represent the primary competitive anchors shaping procurement patterns across Doha's higher education and government training sectors.
| Leading Market Players |
|---|
| Zinger Stick Software |
| Cypher Learning Inc. |
| Blackboard Inc. |
| Ascentsoft |
| Moodle Pty. Ltd |
| Edraak |
| Capytech FZ LLC |
| Classera |
| Malomatia |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure concentration in the United States and Ireland anchors margin capture for Qatar-based LMS deployments, with hyperscaler server residency costs feeding directly into SaaS subscription tiers for Doha education networks.
Pricing Analysis
Certification level (Ministry of Education and Higher Education pre-qualification status) creates the primary spread between premium and standard vendor tiers. Subscription-based SaaS financing dominates procurement specifications, with three-tier pricing structure across premium, standard, and economy levels differentiating by data residency architecture depth and Arabic NLP capability integration. Cost compression in mid-tier offerings is intensifying because regional developers are undercutting global platforms on localization compliance. Government workforce development programs show least price sensitivity due to Qatar National Vision mandate backing, while independent K-12 operators in Al Wakrah demonstrate highest sensitivity to total cost of ownership.
Supply Chain Analysis
Export-control restrictions on advanced AI training chips constrain adaptive learning engine development flows into Qatar's education technology sector. Software supply concentrates in the United States, Ireland, and Singapore for core cloud infrastructure, with India and the United Arab Emirates providing integration services and Arabic content localization. Raw material dependencies include GPU compute clusters, SCORM/xAPI interoperability middleware, and student information system API connectors. Single-source vulnerability runs through hyperscaler cloud platforms subject to data sovereignty enforcement. Distribution runs through direct enterprise sales teams for government and Qatar Foundation contracts, with channel partners serving fragmented K-12 independent schools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across Qatar's education sectors creates niche entry points, as Ministry of Education and Higher Education accreditation standards and Qatar National Vision workforce mandates simultaneously expand addressable demand while constraining vendor eligibility.
For Market Incumbents: Build switching-cost moats through deep student information system integration and multi-year Qatar-based server infrastructure commitments. Defensive priorities center on securing pre-qualification status renewal ahead of tightening localization mandates and embedding virtual classroom layers into core instructional workflows to reduce churn risk from modular competitors. Capacity addition in Doha metro data centers represents the critical infrastructure lever. For New Entrants and Emerging Players: Build out specialized compliance training modules targeting Ras Laffan Industrial City energy sector workforce development programs, the most penetrable segment given outcome-based procurement criteria favoring niche capability over platform breadth. Al Wakrah K-12 district consolidation offers secondary white-space as unified LMS deployments replace fragmented single-school solutions. Go-to-market execution should leverage channel partnerships with established Qatar Foundation network integrators rather than direct sales buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional Arabic-language platform developers possessing Ministry pre-qualification status but lacking scale for hyperscaler infrastructure investment. Long-term viability across the analysis window hinges on data residency compliance architecture rather than feature differentiation. The signal to watch is enforcement tightening by the communications regulator on cross-border student information flows, which would accelerate consolidation toward in-country server operators.| Strategic Initiative | Industry Significance |
|---|---|
| Qatar-Based Server Infrastructure Establishment | Communications regulator data sovereignty mandates require in-country residency for procurement eligibility. |
| Arabic Natural Language Processing Integration | Al Wakrah K-12 districts prioritize vendors with demonstrated Arabic adaptive learning capabilities. |
| Virtual Classroom Platform Acquisition | Hybrid instruction persistence in Education City universities sustains demand for synchronous video layers. |
| Energy Sector Compliance Module Development | Ras Laffan Industrial City workforce programs seek specialized safety and certification training platforms. |
| Qatar Foundation Network Partnership | Multi-departmental procurement alignment across academic, IT, and finance units extends contract duration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with LMS platform executives, Ministry of Education procurement officers, Qatar Foundation IT directors, and technical institute system architects; and secondary validation through SEC filings of listed education technology providers, hyperscaler Qatar region capex disclosures, and Ministry of Education and Higher Education accreditation bulletins. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against Qatar National Vision human capital spending frameworks anchored value estimates.
Forecast inputs considered cloud infrastructure penetration curves, accreditation pre-qualification vendor counts, and civil service reskilling program scale across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user category, technology layer, and solution component. CAGRs were derived from elasticity-adjusted adoption curves and budget allocation trajectories tied to Qatar National Vision 2030 implementation phases, with cross-validation against Gulf Cooperation Council education technology spending patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by regional Arabic-language platform developers or hyperscaler direct market entry would shift outcomes. Material shifts in communications regulator data sovereignty enforcement or Ministry of Education and Higher Education accreditation standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
School Management System Market