
 Global Corporate M-Learning Market | 2026-2036
Global Corporate M-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corporate M-Learning Market Foresight
Buyer concentration in the Global Corporate M-Learning Market is consolidating around Fortune 500 enterprises and large multinational employers seeking unified talent development platforms. SAP SE anchors its position through deep ERP integration that extends learning data into workforce analytics. Adobe Inc leverages creative cloud synergies to dominate content authoring for personalized mobile curricula. Skillsoft competes through specialized leadership and compliance libraries that occupy niche but high-retention segments.
Corporate M-Learning encompasses portable digital education systems delivered through smartphones, tablets, and wearables, typically employing responsive HTML5 architectures, offline content synchronization, and xAPI tracking protocols to enable skills acquisition outside traditional classroom settings. Mobile apps and microlearning formats lead delivery mode adoption due to their alignment with fragmented work schedules and just-in-time knowledge needs. Compliance training and technical skills content command the strongest renewal rates among content type segments, reflecting regulatory pressure and rapid technology obsolescence cycles. Cloud-based and SaaS deployment models capture the dominant share of new implementations as enterprises prioritize scalability over capital-intensive on-premises infrastructure.
The U.S. Department of Labor's OSHA guidelines, the EU GDPR framework enforced by national data protection authorities, and India's TRAI data localization advisories collectively shape platform architecture decisions around user privacy, content accessibility standards, and cross-border data governance. ISO 9001 quality management certifications and IEC security standards further constrain vendor qualification processes for regulated industries. Stakeholders must monitor evolving AI governance requirements across the European Union, United States, and China to anticipate compliance-driven procurement shifts.
Market Dynamics
EU AI Act enforcement and GDPR audit requirements are compressing vendor qualification timelines while simultaneously elevating procurement premiums for platforms with native compliance architecture. Financial services and healthcare employers now mandate auditable learning data lineage as a non-negotiable threshold criterion.
Growth Catalysts
- OSHA workforce safety mandates:US employers must document continuous training completion for distributed field personnel. Mobile delivery satisfies audit trail requirements while reducing classroom logistics costs.
- Microlearning format penetration:Fragmented work schedules among frontline workers in retail and logistics sectors favor sub-10-minute content modules. HTML5 responsive architectures enable seamless device switching without content degradation.
- India's enterprise mobility infrastructure buildout:TRAI data localization advisories combined with 5G spectrum expansion are accelerating domestic platform deployment decisions among multinational subsidiaries.
Market Restraints
- Cross-border data governance friction:Conflicting localization requirements between EU GDPR, China PIPL, and India's draft data protection framework fragment platform architecture roadmaps and inflate compliance engineering costs.
- Offline synchronization technical limitations:xAPI tracking protocols struggle with conflict resolution when learners reconnect after extended offline periods, degrading learning record completeness in low-connectivity environments.
- Content development cost concentration:Specialized compliance and technical skills libraries require subject matter expert curation that concentrates with premium-tier vendors, limiting mid-market procurement options.
Strategic Opportunities
- Wearables integration white space:Smartwatch and AR glasses form factors remain underpenetrated for just-in-time performance support. Convergence of biometric sensors with microlearning delivery creates differentiated positioning for early movers.
- Germany's Mittelstand compliance automation:Mid-sized manufacturers face CSRD sustainability reporting obligations that require workforce upskilling at scale. Bundled ESG training modules represent attach-rate expansion potential.
- AI-generated personalized curricula:Large language model convergence with learner performance data enables dynamic content assembly. Regulatory clarity from EU AI Act risk classification frameworks will unlock procurement acceleration.
Industry Challenges
- xAPI and SCORM integration complexity:Legacy learning management systems deployed across enterprise technology stacks resist seamless data exchange with modern mobile-first platforms, extending implementation timelines.
- Accessibility certification delays:WCAG 2.1 AA compliance validation for multimedia content creates bottlenecks in regulated industries where procurement requires documented conformance.
- Skills gap in learning data analytics:Talent capable of translating xAPI stream data into workforce performance insights remains scarce, limiting platform value realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corporate M-Learning Market |
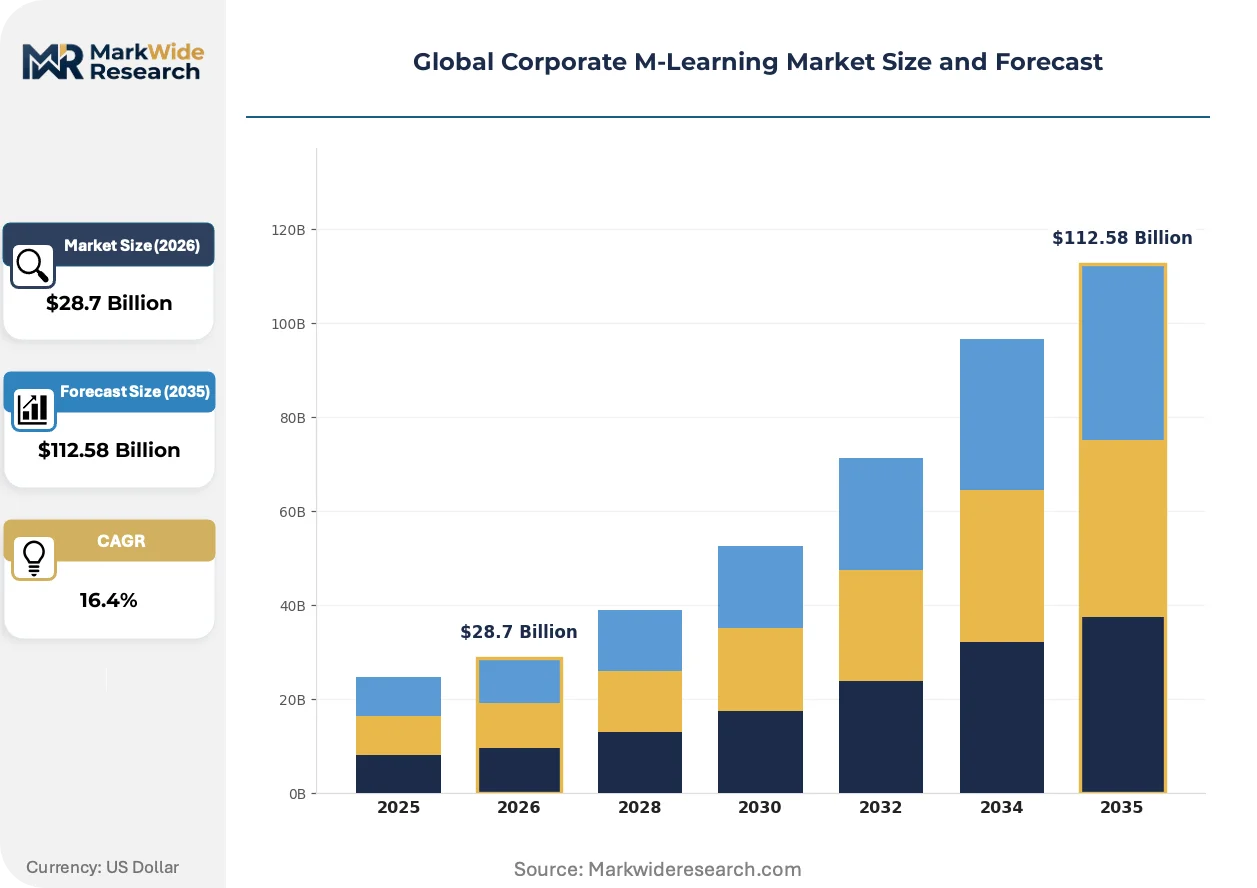
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Learning Delivery Mode: Mobile Apps, Web-Based, Virtual Reality, Augmented Reality, Microlearning, Podcasts Content Type: Compliance Training, Soft Skills, Technical Skills, Leadership Development, Product Knowledge, Customer Service End User Industry: Financial Services, Information Technology, Manufacturing, Telecommunications, Hospitality, Education Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS, Enterprise License |
| Companies Covered | Adobe Inc, Skillsoft, Coursera, D2L Corporation, IBM Corporation, SAP SE, Microsoft Corporation, Oracle Corporation, Cornerstone OnDemand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corporate M-Learning Market Shifts & Advancements
Generative AI capabilities are compressing content production cycles while simultaneously raising the bar for platform differentiation around data governance and learner privacy protection.
xAPI tracking protocols are consolidating learning data interoperability across previously siloed enterprise systems. Fortune 500 employers with heterogeneous technology stacks are mandating xAPI-native platforms to unify skills analytics with workforce planning systems. This consolidation is collapsing vendor tiers that previously maintained proprietary data formats as switching barriers.
EU AI Act risk classification frameworks are reshaping procurement evaluation criteria for adaptive learning systems. High-risk applications in credentialing and performance assessment now require documented human oversight mechanisms and algorithmic audit trails. German and French enterprise buyers are advancing compliance verification to pre-contract stages, disqualifying platforms without native governance architecture.
Subscription-based licensing models are displacing perpetual seat licenses among mid-market employers seeking operational expenditure predictability. Channel partners in India and Germany are bundling implementation services with recurring platform fees, compressing upfront capital requirements. This shift is most visible among healthcare and professional services verticals where IT budget cyclicality complicates multi-year planning horizons.
Global Corporate M-Learning Market Segmentation
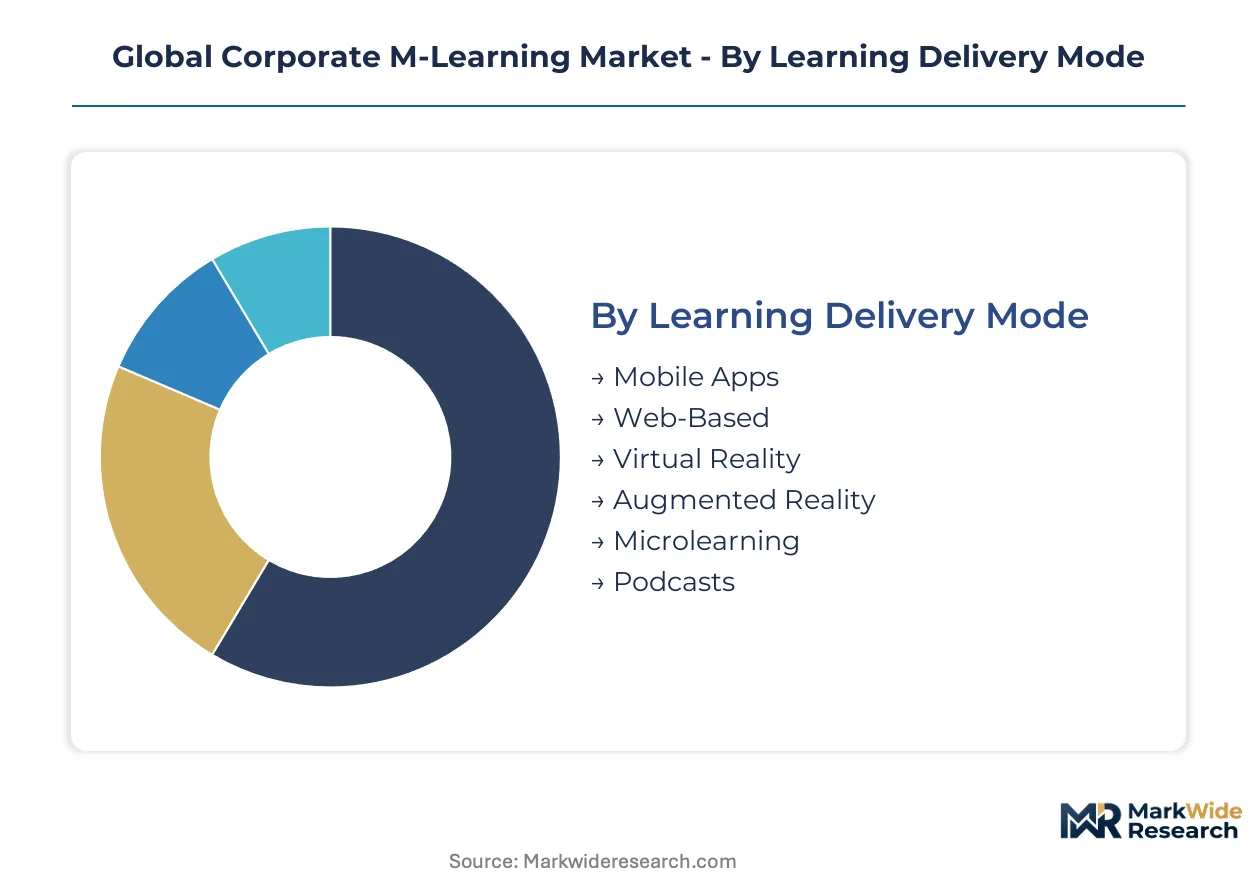
Corporate M-Learning procurement diverges sharply across delivery architectures, content domains, and deployment economics. Understanding these segment boundaries clarifies where platform investments concentrate and which configurations face obsolescence pressure.
Learning Delivery Mode:
Platform refresh cycles accelerate where mobile-first architectures displace legacy web portals that fail offline synchronization requirements.
- Mobile Apps:Native iOS and Android applications leverage device hardware for push notifications and biometric authentication. Financial services employers in the United States and Germany mandate these for field workforce compliance documentation.
- Microlearning:Sub-10-minute content modules delivered through HTML5 responsive architectures enable seamless device switching. Logistics and retail sectors in India favor this format for fragmented shift schedules.
- Web-Based:Browser-accessible platforms retain relevance for desktop-centric knowledge work environments.
- Virtual Reality:Immersive simulations concentrate in high-stakes technical training for manufacturing and energy sectors.
- Augmented Reality:Overlay guidance systems penetrate field service and equipment maintenance workflows.
- Podcasts:Audio-first delivery serves commuting professionals in consulting and sales roles.
Volume placements concentrate in Mobile Apps; the faster expansion belongs to Microlearning.
Content Type:
Content development cost structures vary dramatically, with regulatory-mandated curricula commanding premium pricing against discretionary soft skills libraries.
- Compliance Training:Legally mandated curricula covering OSHA workplace safety, EU GDPR data handling, and India's TRAI telecommunications standards. Financial services and healthcare employers treat this as non-discretionary spend with automatic renewal clauses.
- Technical Skills:Rapidly obsolescing material covering cloud architectures, cybersecurity protocols, and software development frameworks. Information technology sector procurement in the United States and Germany drives replacement cycles.
- Soft Skills:Communication, collaboration, and adaptability content for professional services and hospitality verticals.
- Leadership Development:Executive succession and management capability building for Fortune 500 talent pipelines.
- Product Knowledge:Sales enablement and customer-facing technical specifications for manufacturing and telecommunications firms.
- Customer Service:Frontline interaction protocols for retail, hospitality, and telecommunications contact centers.
Procurement volume clusters in Compliance Training; Technical Skills libraries are climbing the fastest as cloud and AI capabilities reshape workforce requirements.
End User Industry:
Industry-specific regulatory density determines platform customization depth and integration complexity with sector-specific workforce systems.
- Financial Services:Banks, insurers, and asset managers subject to SEC record-keeping, EU MiFID II training documentation, and RBI cybersecurity mandates in India. These employers require auditable learning data lineage as a threshold procurement criterion.
- Information Technology:Software vendors and cloud service providers facing rapid skills obsolescence in artificial intelligence, DevOps, and zero-trust security architectures.
- Manufacturing:OSHA safety compliance and ISO 9001 quality management certification requirements shape platform selection.
- Telecommunications:TRAI data localization advisories in India and FCC accessibility standards in the United States constrain architecture decisions.
- Hospitality:High-turnover workforce environments favoring low-friction mobile onboarding and multilingual content delivery.
- Education:Universities and corporate training departments seeking credentialing integration with established learning management ecosystems.
Platform deployments concentrate in Financial Services; the steepest expansion trajectory appears in Information Technology as AI capabilities reshape technical workforce requirements.
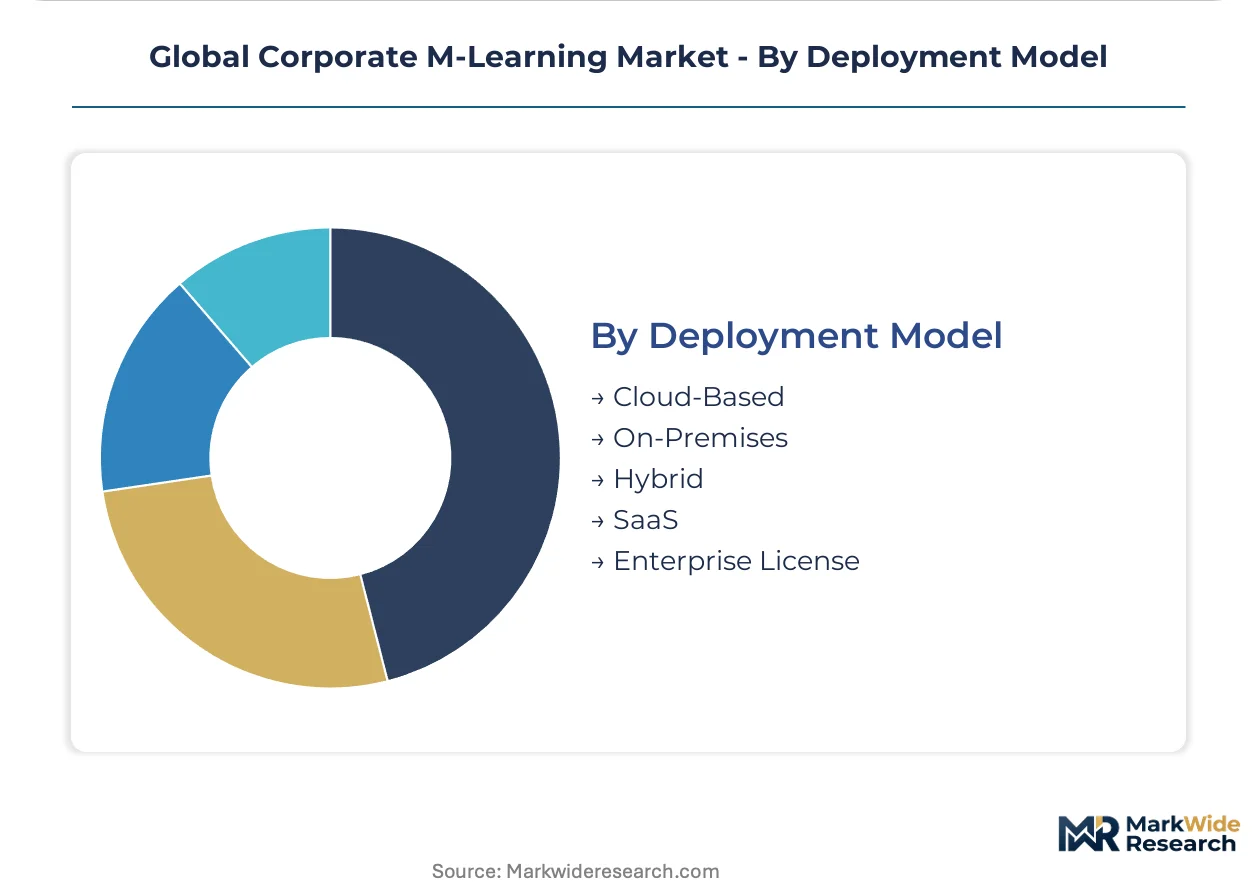
Deployment Model:
Capital expenditure constraints and data sovereignty requirements push procurement toward operational expenditure models with localization flexibility.
- Cloud-Based:Scalable infrastructure with automatic updates and reduced IT overhead. Mid-market employers across all geographies favor this for budget predictability.
- SaaS:Subscription licensing with per-seat or consumption-based pricing. Healthcare and professional services verticals in the United States and Germany lead adoption.
- Hybrid:Sensitive compliance data retained on-premises while general content leverages cloud delivery. EU GDPR and India TRAI localization requirements drive this configuration.
- On-Premises:Capital-intensive legacy installations persisting in defense and classified government environments.
- Enterprise License:Unlimited organizational deployment with customization rights for multinational employers with heterogeneous subsidiary requirements.
New implementations concentrate in Cloud-Based models; SaaS licensing is gaining share fastest as channel partners bundle implementation services with recurring fees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in three distinct national markets where enterprise mobility infrastructure and regulatory pressure intersect. Financial services employers in the United States, Germany, and India are scaling mobile-first training investments for distributed workforces.
United States
Financial services and healthcare employers drive procurement volume. OSHA workforce safety mandates require documented training completion for distributed field personnel. Mobile delivery satisfies audit trail requirements while reducing classroom logistics costs. New York and San Francisco host the densest concentrations of Fortune 500 headquarters deploying unified talent development platforms.
Germany
Mid-sized manufacturers in the Mittelstand segment face CSRD sustainability reporting obligations. EU AI Act enforcement compresses vendor qualification timelines while elevating procurement premiums for platforms with native compliance architecture. Bavaria and Baden-Württemberg anchor industrial automation clusters where workforce upskilling at scale creates bundled ESG training module opportunities.
India
Multinational subsidiaries accelerate domestic platform deployment decisions. TRAI data localization advisories combined with 5G spectrum expansion reshape architecture roadmaps. Bangalore and Hyderabad concentrate information technology sector procurement as AI capabilities reshape technical workforce requirements.
United Kingdom
Professional services firms favor subscription-based licensing models for operational expenditure predictability. GDPR audit requirements push enterprises toward secure, auditable learning platforms. London anchors consulting and financial services demand where channel partners bundle implementation services with recurring platform fees.
Japan
Manufacturing employers prioritize ISO 9001 quality management certifications in vendor qualification processes. METI industrial policy supports workforce reskilling initiatives for digital transformation. Tokyo and Osaka metropolitan areas concentrate enterprise technology stacks where legacy learning management systems resist seamless data exchange with mobile-first platforms.
Global Corporate M-Learning Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-generated personalized curricula and wearables integration. The vendor base consolidates around three tiers: ERP-integrated platforms, specialized content libraries, and cloud-native challengers. Strategic archetypes include deep enterprise system integrators, compliance-focused niche specialists, and horizontal SaaS scale players. M&A activity concentrates on AI governance capabilities and regional channel partnerships.
Within the ERP-integrated tier, SAP SE anchors European demand through workforce analytics convergence. Adobe Inc exemplifies the content authoring archetype leveraging creative cloud synergies for personalized mobile curricula. Skillsoft occupies the specialized library position with leadership and compliance collections that command high-retention segments. These three represent distinct competitive vectors rather than direct substitution.
| Leading Market Players |
|---|
| Adobe Inc |
| Skillsoft |
| Coursera |
| D2L Corporation |
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Oracle Corporation |
| Cornerstone OnDemand |
| Others |
Supply & Pricing Matrix
Fortune 500 procurement consolidation around auditable learning data lineage forces vendors to absorb compliance engineering costs while maintaining subscription accessibility for mid-market buyers. This demand-side pressure compresses margins on standard-tier offerings while amplifying premium capture for platforms with native GDPR and EU AI Act architecture.
Pricing Analysis
Volume concentrates in SaaS subscription tiers while margin accrues to enterprise license deployments with customization rights. Pricing stratifies across premium, standard, and economy tiers based on compliance certification depth and integration complexity with legacy ERP systems. Cost compression in the standard tier stems from channel partner bundling of implementation services with recurring fees. Mid-market employers in healthcare and professional services verticals exhibit highest price sensitivity; financial services buyers prioritize audit trail completeness over per-seat economics.
Supply Chain Analysis
Content refurbishment and curriculum update cycles create reverse-logistics value recovery for specialized compliance libraries subject to annual regulatory refresh mandates. Platform development concentrates in the United States, Germany, and India where enterprise mobility infrastructure and data localization requirements intersect. Raw material inputs draw from cloud computing capacity, subject matter expert networks, and multimedia production studios. Single-source vulnerability sits with premium-tier vendors controlling specialized leadership and technical skills content libraries. Distribution runs through direct enterprise sales teams in North America and channel partners in European and Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile-first architectures are displacing legacy web portals that fail offline synchronization requirements, compressing vendor refresh cycles and opening white space for cloud-native challengers. This technology transition favors platforms with native xAPI tracking and responsive HTML5 delivery over incumbent systems burdened by SCORM integration complexity.
For Market Incumbents: Anchor defensive positioning through deep ERP integration that extends learning data into workforce analytics, resisting substitution from horizontal SaaS scale players. Prioritize AI governance capability investments to satisfy EU AI Act risk classification requirements that German and French buyers now verify at pre-contract stages. Control channel relationships in India and Germany where bundled implementation services compress upfront capital requirements and lock in recurring revenue streams. For New Entrants and Emerging Players: Direct-to-enterprise digital sales routes bypass incumbent channel gatekeepers in mid-market segments where procurement teams self-serve platform evaluations. Target wearables integration white space where smartwatch and AR glasses form factors remain underpenetrated for just-in-time performance support. Lead with AI-generated personalized curricula capabilities that enable dynamic content assembly from learner performance data, differentiating against static library vendors. For Investors and Strategic Acquirers: The window for entry favors cloud-native platforms with compliance-native architecture over legacy on-premises installations facing obsolescence pressure. Long-term viability rests on acquisition targets possessing AI governance capabilities and regional channel partnerships in data-localization-constrained markets. Monitor EU AI Act enforcement timelines and TRAI data localization finalization as inflection indicators for procurement acceleration in regulated verticals.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Capability Investment | EU AI Act risk classification frameworks now require documented human oversight mechanisms in high-risk credentialing applications. |
| Wearables Integration Development | Smartwatch and AR glasses form factors create differentiated positioning for just-in-time performance support in field service workflows. |
| Regional Channel Partnership Expansion | Channel partners in India and Germany bundle implementation services with recurring fees, compressing upfront capital barriers. |
| xAPI-Native Platform Architecture | Fortune 500 employers mandate xAPI-native platforms to unify skills analytics with heterogeneous workforce planning systems. |
| Compliance Library Specialization | OSHA, GDPR, and TRAI-mandated curricula command automatic renewal clauses from financial services and healthcare employers. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and enterprise software procurement databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with chief learning officers, IT procurement officers, platform engineers, and channel partners validated deployment trends and pricing dynamics across financial services, healthcare, and information technology verticals. Bottom-up and top-down triangulation reconciled vendor-reported metrics with employer budget allocation patterns.
Bottom-up modeling aggregated individual segment trajectories across delivery mode, content type, end-user industry, and deployment model dimensions. Top-down validation cross-checked aggregate projections against macroeconomic indicators and regulatory implementation timelines. CAGRs were derived from fitted growth curves incorporating 5G infrastructure buildout, EU AI Act enforcement phases, and enterprise mobility adoption saturation patterns. Forecast inputs included TRAI data localization compliance costs and xAPI integration complexity premiums.
The model holds under steady regulatory implementation timelines; deviation in EU AI Act enforcement severity or India data protection framework finalization would shift procurement acceleration patterns. Forecasts reflect assumptions around cloud migration continuity and mid-market subscription adoption elasticity. Practitioners should monitor CSRD sustainability reporting obligation expansion and wearable device enterprise adoption curves for early signals of segment reallocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
Global Mobile Learning Market