
 Global Exam Management Software Market | 2026-2036
Global Exam Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exam Management Software Market Foresight
Modular unbundling of proctoring from full-suite platforms is repositioning how universities evaluate procurement trade-offs. ExamSoft Worldwide leverages deep integration with learning management systems to anchor its position in North American law and medical schools. Kryterion specializes in flexible, white-label certification delivery for professional associations. Inspera Assessment competes through native support for open-source interoperability standards across Nordic and British higher education systems.
Exam management software comprises digital platforms that orchestrate the full examination lifecycle, including item banking, secure delivery, live or automated proctoring, and analytics-driven result processing, typically operating through browser-based clients or locked-down applications with keystroke logging and screen capture capabilities. Cloud-based deployment leads in new installations due to elastic capacity for high-stakes testing windows, while on-premise configurations retain share among defense and government clients with air-gapped security requirements. Proctoring solutions command premium pricing as they integrate AI-based behavioral analysis and human review workflows.
FDA oversight applies where exam software supports medical licensure pathways, while GDPR and FERPA constrain cross-border data flows for European and American student populations. ISO 27001 certification has become a baseline procurement filter for university IT departments evaluating vendor risk profiles. Stakeholders must monitor evolving AI proctoring litigation in California and Illinois courts, where biometric privacy statutes are creating compliance exposure that reshapes vendor liability structures and insurance requirements.
Market Dynamics
AI proctoring systems are compressing vendor margins while expanding compliance exposure, forcing platform providers to restructure liability frameworks and insurance coverage across multiple jurisdictions.
Growth Catalysts
- National digital examination programs:India, the United Kingdom, and the United States are deploying government-backed testing infrastructure at scale, creating sustained procurement pipelines for integrated assessment platforms.
- GDPR and FERPA compliance mandates:European and American data protection frameworks are compelling institutions to replace legacy systems with certified alternatives, accelerating replacement cycles for non-compliant vendors.
- Hybrid learning normalization:Universities and professional certification bodies have institutionalized remote assessment capabilities, embedding software procurement into permanent operational budgets rather than emergency spending.
Market Restraints
- Cloud infrastructure concentration:Reliance on hyperscale providers in the United States creates geopolitical exposure for European and Asian clients facing data sovereignty requirements.
- Biometric privacy litigation:Illinois BIPA and California CCPA enforcement actions are generating unquantified liability reserves for vendors deploying facial recognition and keystroke analysis.
- On-premise legacy entrenchment:Defense and government clients in air-gapped environments resist cloud migration, fragmenting vendor R&D across incompatible deployment architectures.
Strategic Opportunities
- Open-source interoperability:Nordic and British higher education systems are mandating standards-based integration, rewarding vendors with native LTI and QTI compliance over proprietary alternatives.
- Professional certification expansion:White-label delivery models for medical, legal, and IT credentialing bodies in Germany and Australia offer recurring revenue streams with lower customer acquisition costs.
- ISO 27001 procurement filtering:University IT departments are elevating information security certification to mandatory status, disqualifying uncertified competitors from formal bidding processes.
Industry Challenges
- AI training data scarcity:Behavioral analysis algorithms require diverse, labeled examination datasets that institutions are reluctant to share due to FERPA and GDPR constraints.
- Cross-border data architecture:Building regionally isolated infrastructure to satisfy European, American, and Asian regulatory regimes duplicates fixed costs without proportional revenue expansion.
- Human review workflow scaling:Automated flagging systems generate false positive rates requiring costly manual adjudication during high-stakes testing windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exam Management Software Market |
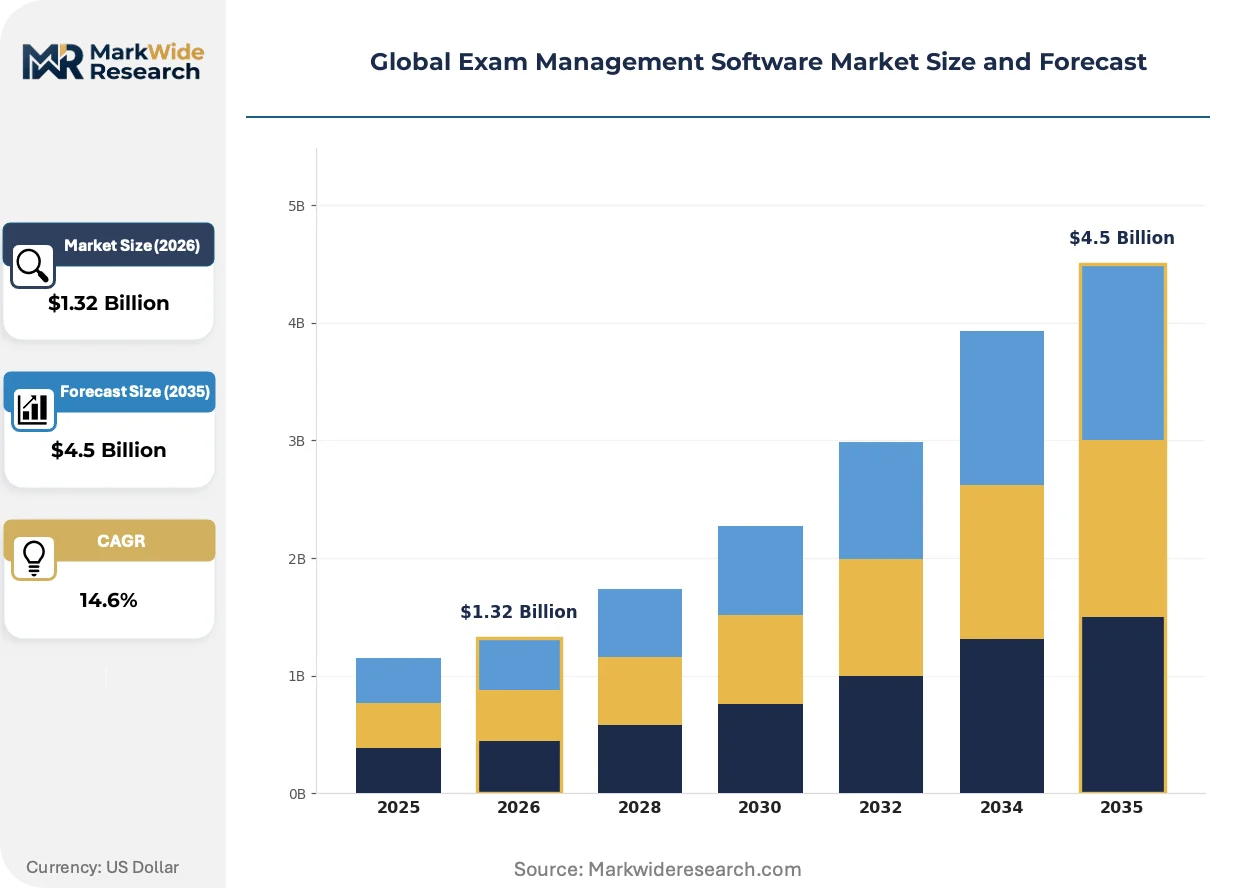
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $4.5 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Virtual Private Cloud Solution Type: Proctoring, Question Bank Management, Scheduling & Registration, Result Analysis, Certification Management Application: Academic Institutions, Certification Bodies, Corporate Training, Government Examinations, Language Testing End User: Universities, Vocational Schools, Professional Associations, E-Learning Platforms, Training Organizations |
| Companies Covered | ProctorU Inc., DigiExam AB, ExamSoft Worldwide, Inc., Edbase, Kryterion, LLC, Questionmark Corporation, Inspera Assessment AS, QuizCV, Scantron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exam Management Software Market Shifts & Advancements
Browser-based lockdown technology is displacing downloadable applications, reducing deployment friction while introducing new attack surfaces that vendors must continuously patch.
Computer vision systems with multimodal behavioral analysis are electrifying proctoring accuracy by correlating gaze tracking, keystroke dynamics, and audio signatures into unified risk scores. Medical schools in the United States and law faculties in Canada are piloting these integrated systems for bar and licensure examinations. The technology is compressing the acceptable error tolerance for false negatives in high-stakes credentialing decisions.
GDPR Article 22 restrictions on automated decision-making are compelling European vendors to redesign AI proctoring workflows with mandatory human review loops for contested flags. German and French higher education ministries are requiring transparency documentation for algorithmic flagging criteria before platform approval. Institutions in the Netherlands and Belgium are delaying procurement until vendors demonstrate compliant appeal mechanisms.
Subscription pricing with usage-based overage charges is displacing perpetual licensing in North American university procurement. Chief information officers in California and Texas systems are consolidating vendor relationships to capture volume discounts on per-exam fees. British and Australian institutions are resisting this shift, preferring fixed annual costs to protect budget predictability against enrollment volatility.
Global Exam Management Software Market Segmentation
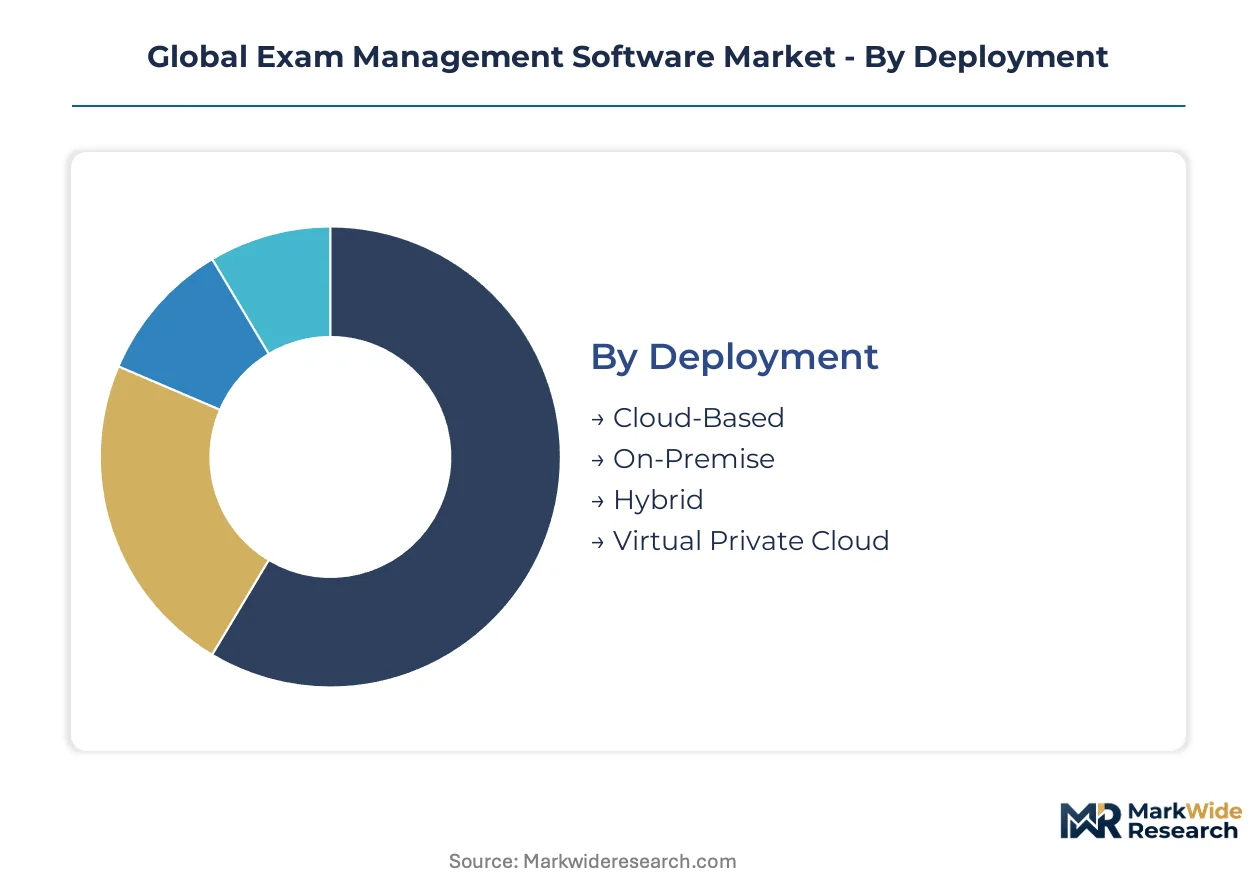
Exam management software segments reflect divergent technical architectures and procurement priorities across higher education, credentialing bodies, and government clients. Understanding these divisions clarifies why vendors maintain parallel development tracks for cloud-native and air-gapped deployments despite operational complexity.
Deployment:
Cloud infrastructure configurations determine scalability ceilings, data sovereignty compliance, and total cost of ownership for examination programs.
- Cloud-Based:Elastic compute resources accommodate surge capacity during high-stakes testing windows for medical licensure and bar examinations. Universities in California and Texas systems favor this model for its elimination of on-site server maintenance and automatic security patching.
- On-Premise:Air-gapped installations serve defense departments and national security agencies in the United States, Germany, and India with complete network isolation. These configurations require dedicated hardware procurement cycles and specialized technical staff, constraining vendor margins through customization demands.
- Hybrid:Split architectures route sensitive biometric data through local processing while leveraging cloud analytics for pattern recognition. British and Australian universities deploy hybrid models to satisfy GDPR and Privacy Act constraints without sacrificing AI proctoring capabilities.
- Virtual Private Cloud:Isolated tenant environments within hyperscale data centers offer middle-ground security for Saudi and UAE government examination boards. These deployments carry premium pricing but avoid full on-premise capital expenditure.
Cloud-Based deployments lead on scale; Virtual Private Cloud leads on momentum as data sovereignty requirements proliferate across Middle Eastern and Asian markets.
Solution Type:
Functional modules command differentiated pricing based on regulatory sensitivity and technical sophistication.
- Proctoring:AI-driven behavioral analysis with multimodal inputs including gaze tracking, keystroke dynamics, and audio signatures. Medical schools in the United States and law faculties in Canada pilot these systems for licensure examinations where false negative tolerance approaches zero.
- Question Bank Management:Item banking with psychometric analysis and adaptive testing algorithms supports high-volume certification programs. Professional IT credentialing bodies in Germany and Australia rely on these tools for examination integrity across multiple language versions.
- Scheduling & Registration:Calendar orchestration with accommodation management for disability services offices. This module integrates with student information systems through LTI standards preferred in Nordic higher education markets.
- Result Analysis:Statistical reporting with demographic disaggregation for accreditation compliance. Regional accreditors in the United States require these analytics for program review cycles.
- Certification Management:Lifecycle tracking from examination through credential renewal and continuing education. White-label configurations serve medical boards and legal societies with branded candidate portals.
Proctoring solutions capture premium pricing; Certification Management is expanding most quickly through professional association outsourcing.
Application:
End-use contexts shape feature prioritization from high-stakes security to accessibility compliance.
- Academic Institutions:Comprehensive platforms serving registrar offices, disability services, and faculty assessment needs. Universities in the United Kingdom and Netherlands mandate open-source interoperability standards that favor vendors with native QTI compliance.
- Certification Bodies:White-label delivery with customizable branding and international payment processing. Medical and legal credentialing organizations in Germany and Australia demand these configurations for global candidate pools.
- Corporate Training:Integration with learning management systems for skills verification and compliance documentation. Multinational employers in India deploy these tools for scaleable employee certification across distributed workforces.
- Government Examinations:National-scale deployment with air-gapped security and audit trails for public procurement compliance. India's government-backed digital examination infrastructure exemplifies this segment's procurement complexity.
- Language Testing:Specialized delivery for spoken response capture and automated scoring. British Council and IDP Education operations require these capabilities for IELTS and comparable assessments.
Academic Institutions dominate current procurement volume; Government Examinations show the steepest expansion trajectory through national digital transformation programs.
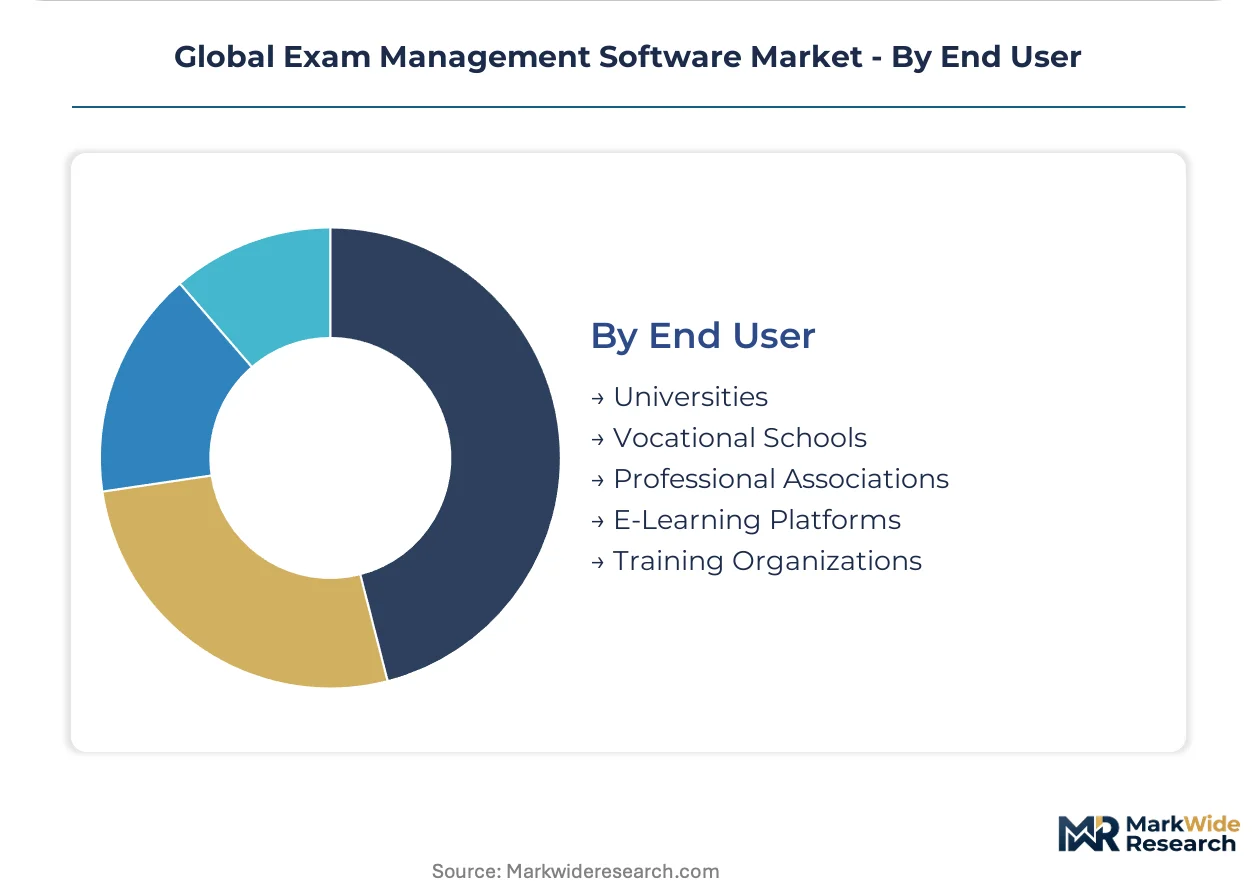
End User:
Organizational scale and procurement authority determine platform configuration complexity and sales cycle duration.
- Universities:Multi-departmental deployments with federated authentication and learning management system integration. Research-intensive institutions in the United States and United Kingdom consolidate vendor relationships to capture volume pricing on per-exam fees.
- Vocational Schools:Streamlined configurations emphasizing practical skills assessment and industry credential alignment. German and Swiss technical colleges prioritize these tools for apprenticeship certification pathways.
- Professional Associations:Member-focused platforms with continuing education tracking and recertification workflows. Medical and legal societies in Canada and Australia leverage these systems for mandated professional development.
- E-Learning Platforms:API-first architectures enabling embedded assessment within massive open online courses and corporate learning paths. Coursera and comparable providers require these integrations for verified certificate programs.
- Training Organizations:Rapid-deployment configurations for corporate clients with customized content and branding. These users prioritize speed-to-launch over deep feature customization.
Universities anchor revenue concentration; Professional Associations are gaining share fastest through recurring certification revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital examination infrastructure first achieved commercial scale in North American university systems during the early 2010s, with subsequent waves of national government investment in India and the United Kingdom establishing these three markets as the primary demand centers for integrated assessment platforms.
United States
Medical schools and law faculties drive procurement of AI proctoring systems with multimodal behavioral analysis. FDA oversight applies where platforms support medical licensure pathways. California and Texas university systems anchor cloud-based deployment volumes through consolidated vendor relationships.
India
Government-backed national digital examination programs create sustained procurement pipelines for high-stakes testing infrastructure. The country's central education ministry mandates ISO 27001 certification for platform eligibility. Bangalore and Hyderabad host domestic technology providers developing localized deployment configurations.
United Kingdom
Open-source interoperability standards reshape vendor selection criteria across higher education systems. GDPR Article 22 restrictions on automated decision-making compel AI proctoring redesigns with mandatory human review loops. London and Manchester universities lead platform consolidation for volume pricing capture.
Germany
Federal and state higher education ministries require transparency documentation for algorithmic flagging criteria before platform approval. Professional IT credentialing bodies generate demand for white-label certification management with multilingual item banking. Berlin and Munich technical colleges prioritize practical skills assessment tools for apprenticeship pathways.
Australia
Privacy Act constraints drive hybrid deployment architectures that process biometric data locally while leveraging cloud analytics. British Council and IDP Education operations require specialized spoken response capture for language testing delivery. Sydney and Melbourne institutions resist subscription pricing shifts, preferring fixed annual costs for budget predictability.
Global Exam Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across proctoring sophistication and compliance certification depth. The vendor base stratifies between full-suite platform providers and modular specialists unbundling specific functional components. Three archetypes dominate: learning management system-integrated suites, white-label certification delivery engines, and open-source interoperability-native challengers. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and geographic expansion through regulatory-compliant regional infrastructure.
Among North American platform providers, ExamSoft Worldwide and ProctorU occupy positions within the LMS-integrated tier, while Inspera Assessment anchors the open-source interoperability segment for Nordic and British markets. Kryterion exemplifies the white-label certification archetype serving professional associations with flexible delivery configurations. These named entities represent strategic positioning patterns rather than definitive market share claims.
| Leading Market Players |
|---|
| ProctorU Inc. |
| DigiExam AB |
| ExamSoft Worldwide, Inc. |
| Edbase |
| Kryterion, LLC |
| Questionmark Corporation |
| Inspera Assessment AS |
| QuizCV |
| Scantron Corporation |
| Others |
Supply & Pricing Matrix
AI engineering talent concentration in Bangalore and Hyderabad establishes labor-cost differentials that widen pricing-tier spreads between premium proctoring suites and economy scheduling modules.
Pricing Analysis
Subscription pricing with usage-based overage charges separates comprehensive platforms from modular point solutions across deployment scales. Price differentiation hinges on ISO 27001 certification tier and AI proctoring sophistication level. Pricing pressure stems from AI proctoring litigation reserves in Illinois and California compressing vendor margins. Corporate training buyers exhibit highest price sensitivity; medical licensure programs show least.
Supply Chain Analysis
Cloud infrastructure engineering talent availability in the United States, India, and Ireland determines hyperscale partnership terms and regional data center buildout velocity. Vendor technology stacks draw from AWS, Azure, and Google Cloud compute resources alongside proprietary biometric processing silicon. Single-source vulnerability concentrates where FDA-compliant medical licensure platforms rely on specific AI training data pipelines. Distribution runs through direct enterprise sales teams for universities and channel partners for vocational schools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
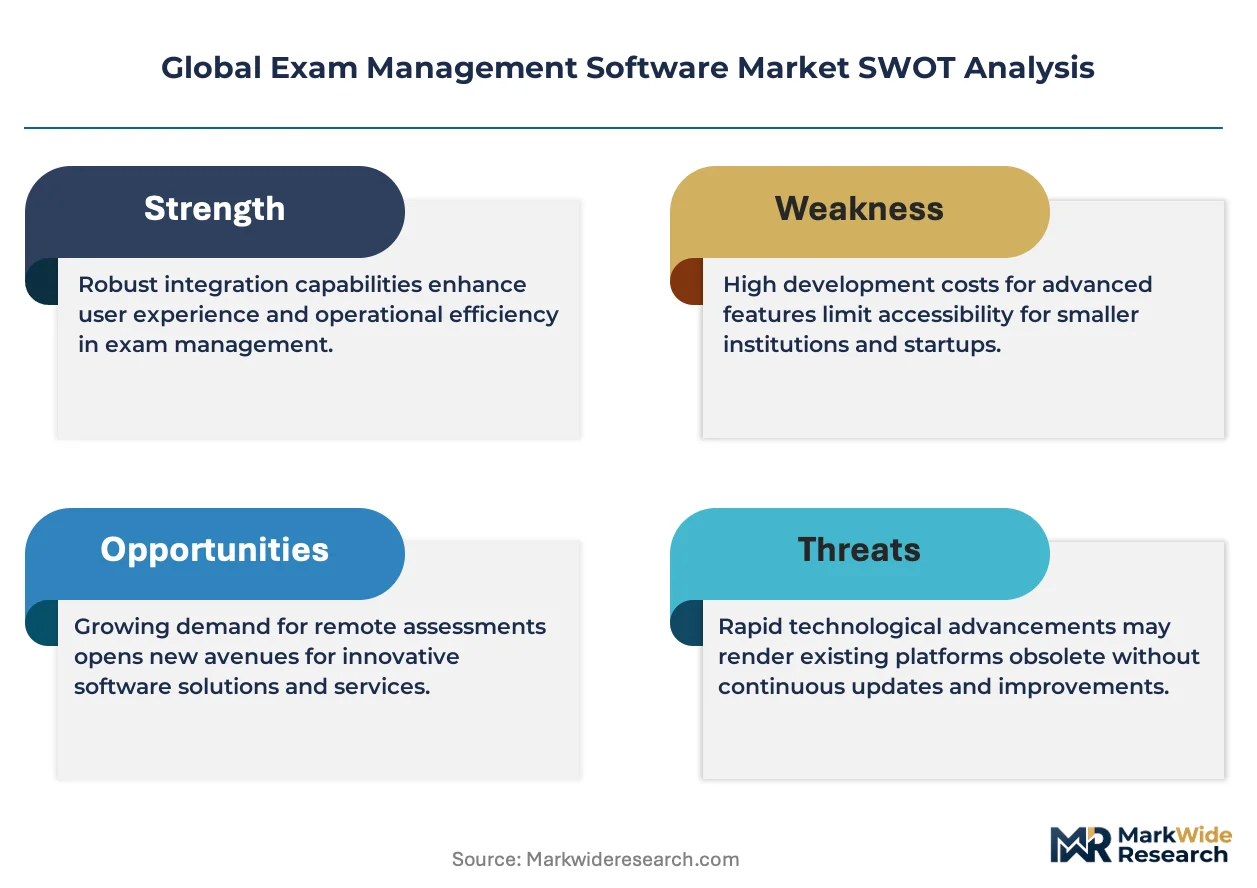
The Global Exam Management Software Market represents a late-cycle quality story as procurement filters elevate ISO 27001 certification from preference to mandatory status across university IT departments.
For Market Incumbents: Deploy open-source interoperability investments to anchor position against proprietary challengers in Nordic and British higher education systems. Consolidate vendor relationships with California and Texas university systems to capture volume pricing leverage. Counter modular unbundling threats by deepening LMS integration moats. For New Entrants and Emerging Players: The mid-tier pricing gap between premium AI proctoring suites and basic scheduling modules creates entry opportunity for hybrid deployment specialists. Target Australian and British institutions resisting subscription shifts toward fixed annual contracts. Pursue white-label certification delivery for German professional IT credentialing bodies. For Investors and Strategic Acquirers: Learning management system providers are the most active acquirer in this space, seeking assessment capabilities to complete platform stacks. Five-to-ten year viability favors vendors with regional infrastructure footprints satisfying data sovereignty requirements. Monitor Illinois BIPA and California CCPA enforcement action volumes as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep LMS integration anchors retention at ExamSoft Worldwide's North American law and medical school installations. |
| Geographic Expansion | Regional data center buildouts in Germany and India satisfy GDPR and data sovereignty procurement filters. |
| Acquisition of Specialist Firm | Modular proctoring specialists unbundling from full-suite platforms attract strategic buyer interest. |
| Strategic Partnership | Hyperscale cloud alliances with AWS and Azure enable elastic capacity for high-stakes testing windows. |
| Product Launch | Browser-based lockdown technology displaces downloadable applications, reducing deployment friction. |
Research Methodology
Multiple input streams — primary interviews with university CIOs, certification body operations directors, and AI proctoring vendors; secondary validation through SEC filings, hyperscaler capex disclosures, and procurement databases; plus regulatory documentation from GDPR and FERPA enforcement actions — were reconciled through bottom-up and top-down triangulation.
Historical adoption curves were cross-referenced against expert panel inputs across deployment model, organization size, vertical, and regional regulatory cluster dimensions. CAGRs were derived from segmented growth trajectory modeling incorporating AI proctoring litigation exposure and national digital examination program procurement pipelines.
Caveats apply where biometric privacy litigation outcomes or data sovereignty regulatory shifts could materially shift the outlook. Material deviation in Illinois BIPA enforcement intensity or European GDPR Article 22 interpretation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Smart Learning Systems Market