
 School Management System Market | 2026-2036
School Management System Market Size, Share, and Industry Trends Forecast 2026-2036
School Management System Market Analysis
Legacy server hardware is shifting toward containerized cloud infrastructure as districts and universities seek lower total cost of ownership. PowerSchool Group leverages its installed base across North American K-12 districts to sustain recurring revenue through modular add-ons. Ellucian Company LP anchors its position in higher education with deep ERP integration for enrollment and financial aid workflows. Oracle Corporation competes through database-layer dominance, embedding its school management offerings within broader cloud ecosystem contracts.
A school management system constitutes an integrated software platform that automates administrative, academic, and operational workflows within educational institutions, typically requiring RESTful API architectures, role-based access controls, and real-time data synchronization across student information databases. Cloud-based deployment leads in new installations due to scalability and reduced IT staffing burdens, while on-premise systems retain share where data sovereignty policies restrict off-site hosting. Among end users, K-12 institutions generate the largest volume base, though higher education commands richer per-seat pricing through complex multi-campus configurations.
FCC E-Rate funding in the United States subsidizes broadband and internal connectivity upgrades that enable SaaS-dependent school management platforms, while GDPR and FERPA impose encryption and consent architectures that vendors must embed by design. ISO 27001 certification has become a de facto procurement filter for district-level RFPs, particularly in jurisdictions with centralized education purchasing authorities. Stakeholders should monitor how generative AI integrations reshape functionality roadmaps and procurement criteria without triggering new regulatory compliance categories.
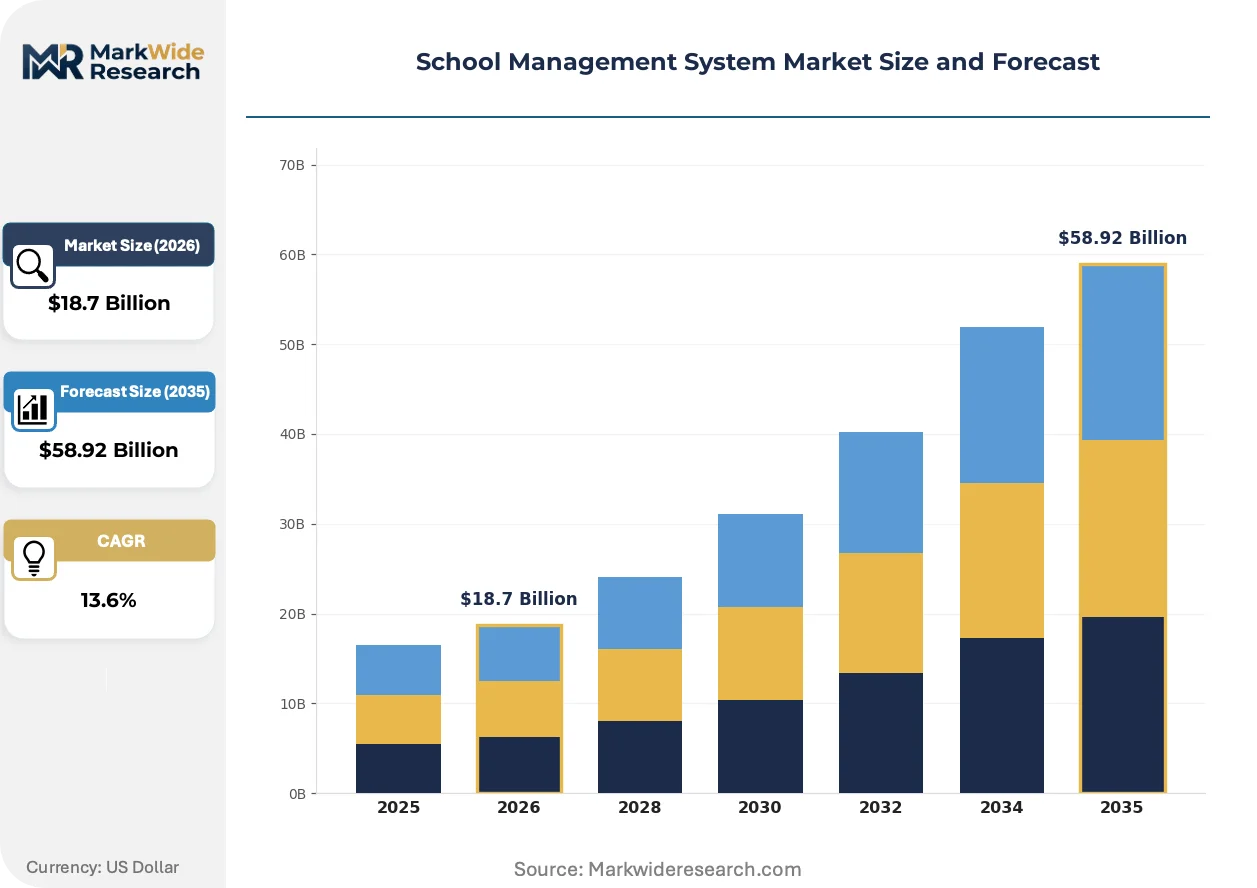
Market Dynamics
Cloud-native architectures are displacing legacy on-premise installations across K-12 and higher education institutions, forcing vendors to rebuild data sovereignty and API interoperability into every deployment while district IT budgets consolidate around SaaS subscriptions.
Growth Catalysts
- FCC E-Rate subsidies:United States federal funding for broadband infrastructure enables under-resourced districts to adopt bandwidth-dependent SaaS platforms without capital outlay for server hardware.
- GDPR Article 32 encryption mandates:European data protection requirements accelerate procurement of ISO 27001-certified platforms that embed privacy-by-design architectures.
- Containerized microservices:Kubernetes-orchestrated deployment models reduce district IT staffing burdens while enabling modular feature expansion without system downtime.
Market Restraints
- Data sovereignty restrictions:German state-level education authorities and French regional academies prohibit student data hosting outside national borders, fragmenting vendor cloud strategies.
- Legacy ERP lock-in:Deep integration between student information systems and decades-old financial aid databases in higher education creates switching costs that delay replacement cycles.
- Interoperability standard gaps:Incomplete adoption of IMS Global Learning Consortium specifications forces expensive custom API development for multi-vendor environments.
Strategic Opportunities
- Generative AI tutoring modules:Large language model integration into assignment grading and personalized learning pathways opens premium pricing tiers for vendors with compliant training data pipelines.
- Rural district consolidation:Cooperative purchasing agreements across sparsely populated United States counties create volume aggregation opportunities for standardized SaaS contracts.
- India National Education Policy 2020:Digital infrastructure mandates for 400,000+ public schools drive demand for localized, low-bandwidth adaptive learning platforms.
Industry Challenges
- FERPA audit complexity:United States districts face escalating compliance documentation requirements for third-party vendor access to education records, lengthening procurement timelines.
- Cybersecurity talent scarcity:K-12 IT departments lack personnel to manage zero-trust architectures and penetration testing protocols required by cyber insurance underwriters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School Management System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile Application End User: K-12 Institutions, Higher Education, Training Centers, Educational Administrators Functionality: Attendance Management, Grade Management, Scheduling, Communication Tools Deployment: Self-hosted, SaaS, Multi-tenant, Dedicated Hosting |
| Companies Covered | PowerSchool Group, Ellucian Company LP, Oracle Corporation, Instructure Holdings Inc, Blackboard Inc, Skyward Inc, Infinite Campus Inc, Jenzabar Inc, Classter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School Management System Market Emerging Trajectories
Artificial intelligence and API-first design principles are compressing feature development cycles while reshaping how educational institutions evaluate vendor roadmaps and data governance capabilities.
Edge computing nodes deployed within school district networks are electrifying real-time attendance and behavioral analytics by processing sensitive biometric data locally before encrypted synchronization to central clouds. Texas and Florida districts with 100,000-plus student populations pilot these architectures to reduce latency for emergency response systems. The technology is electrifying competitive differentiation around data residency compliance without sacrificing mobile accessibility for parents and administrators.
The European Union AI Act risk classification framework imposes conformity assessment obligations on educational software incorporating automated decision-making for student placement or disciplinary actions. Vendors serving French and German markets must document algorithmic transparency and human oversight protocols before CE marking. Higher education admissions platforms deploying predictive enrollment analytics face the steepest compliance retrofit costs and timeline compression.
District-level cooperative purchasing consortia are consolidating vendor evaluation authority away from individual school principals toward centralized state or regional procurement offices. California's K-12 Joint Powers Authorities and Ontario's Education Quality and Accountability Office now negotiate enterprise-wide SaaS contracts with standardized data portability clauses. This concentration is most visible in jurisdictions with elected school boards seeking liability protection through collective cybersecurity insurance arrangements.
School Management System Market Segmentation
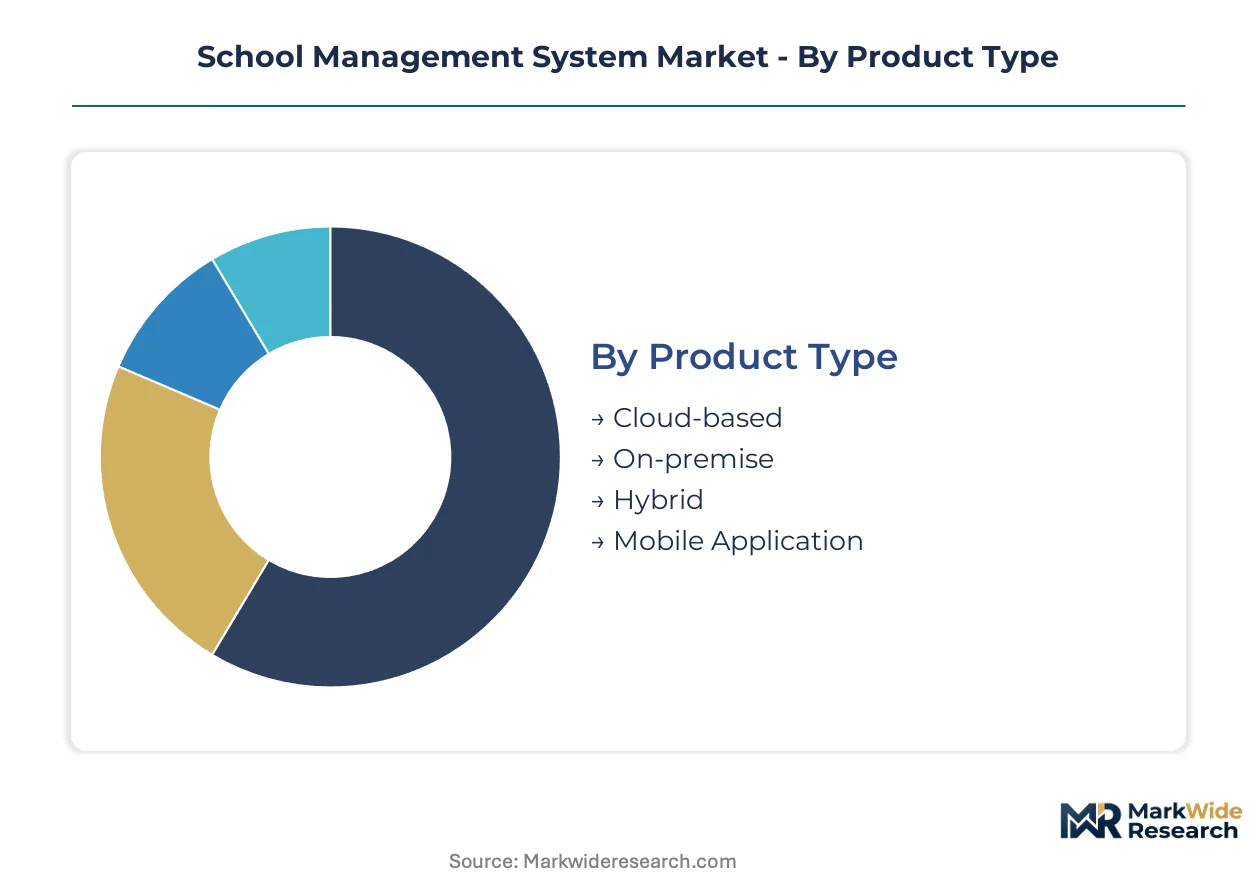
School management system procurement varies sharply by institutional IT maturity and data sovereignty requirements. Vendors structure pricing tiers and feature modules around these divides, with integration depth determining whether platforms operate as standalone suites or embedded components within broader enterprise architectures.
Product Type:
Cloud-based deployments function as standalone SaaS platforms with API gateways for third-party integration, while on-premise and hybrid variants embed more deeply into institutional ERP ecosystems through direct database coupling.
- Cloud-based:Multi-tenant architectures with Kubernetes orchestration enable elastic scaling across enrollment fluctuations. North American K-12 districts with FCC E-Rate subsidized connectivity drive procurement volume, though German state-level data residency restrictions fragment vendor strategies.
- On-premise:Legacy server installations persist where FERPA audit trails require physical data control or where bond-funded capital budgets preclude recurring SaaS subscriptions. Higher education financial aid systems with decades-old COBOL backends create switching cost barriers.
- Hybrid:Edge-computing nodes process biometric attendance locally before encrypted cloud synchronization, satisfying GDPR Article 32 encryption mandates while maintaining mobile accessibility.
- Mobile Application:React Native and Flutter frameworks dominate parent-facing interfaces, with offline-first architectures essential for rural districts with intermittent broadband.
Cloud-based leads volumes today; hybrid configurations are gaining share fastest.
End User:
Cost tier stratification separates volume-driven K-12 deployments from premium-priced higher education configurations with multi-campus complexity.
- K-12 Institutions:Standardized SIS modules with state reporting compliance dominate procurement. California Joint Powers Authorities negotiate enterprise contracts with standardized data portability clauses.
- Higher Education:Complex ERP integration for enrollment management, financial aid, and advancement workflows commands per-seat premiums. Legacy database lock-in delays replacement cycles.
- Training Centers:Modular LMS-SIS hybrids with competency-based progression tracking serve vocational and corporate upskilling programs.
- Educational Administrators:Superintendent and principal dashboards with predictive analytics for resource allocation represent emerging premium tiers.
K-12 Institutions lead volumes today; Training Centers are climbing the fastest.
Functionality:
Application criticality determines whether modules deploy as core platform components or specialized add-ons with separate licensing.
- Attendance Management:Biometric and RFID-based systems with real-time parent notification APIs. Texas districts with 100,000-plus enrollments pilot edge-computing nodes for emergency response latency reduction.
- Grade Management:Standards-based gradebooks with state reporting exports form the core SIS value proposition. Transcript portability via IMS Global specifications reduces transfer friction.
- Scheduling:Constraint-based optimization engines for master scheduling and room allocation. Course request workflows with predictive enrollment analytics face EU AI Act conformity assessment obligations.
- Communication Tools:Unified parent-teacher messaging with automatic translation and two-factor authentication. FERPA audit complexity for third-party vendor access lengthens procurement timelines.
Grade Management leads volumes today; Communication Tools are expanding most quickly.
Deployment:
Maturity-stage differentiation separates established SaaS models from emerging architectures serving specialized compliance requirements.
- Self-hosted:Complete institutional control over patch cycles and backup protocols. French regional academies with CNIL oversight requirements favor this model for sensitive student data.
- SaaS:Subscription pricing with vendor-managed infrastructure updates. ISO 27001 certification has become a de facto procurement filter for district-level RFPs.
- Multi-tenant:Shared infrastructure with logical data segregation reducing per-customer hosting costs. Cooperative purchasing agreements across rural United States counties aggregate volume.
- Dedicated Hosting:Single-tenant cloud instances with guaranteed resource allocation. Indian National Education Policy 2020 digital infrastructure mandates for 400,000-plus public schools drive localized deployment demand.
SaaS leads volumes today; Dedicated Hosting is expanding most quickly.
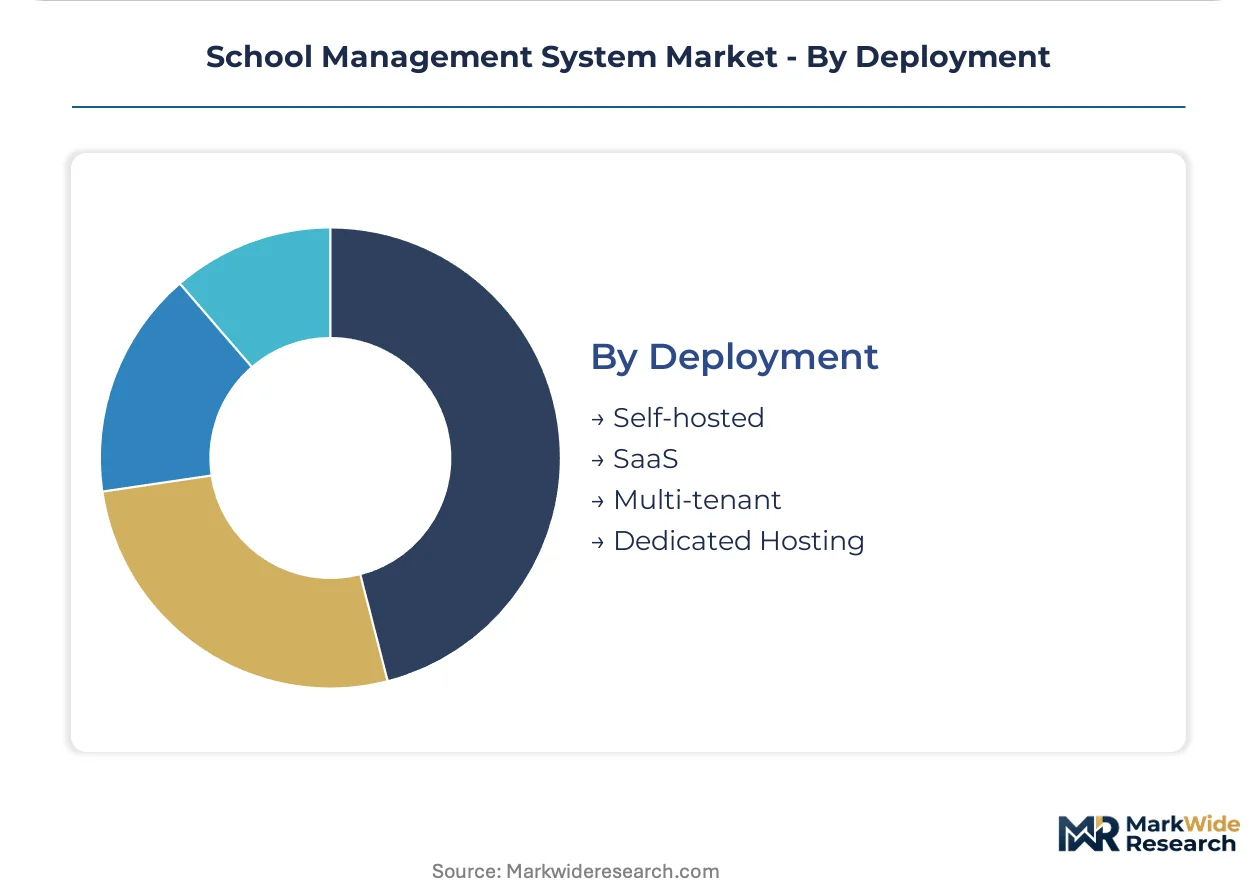
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's education technology corridor anchors software development for cloud-native student information systems. District procurement patterns diverge sharply between digitally mature urban centers and bandwidth-constrained rural jurisdictions. Regulatory fragmentation across national borders forces vendors to maintain multiple compliance architectures.
United States
FCC E-Rate subsidies enable SaaS adoption in under-resourced districts without capital outlay for server hardware. FERPA audit requirements for third-party vendor access lengthen procurement timelines for education records systems. Texas and Florida districts with 100,000-plus enrollments pilot edge-computing nodes for emergency response latency reduction.
Germany
State-level education authorities prohibit student data hosting outside national borders, fragmenting vendor cloud strategies. GDPR Article 32 encryption mandates accelerate procurement of ISO 27001-certified platforms with privacy-by-design architectures. Bavarian and North Rhine-Westphalian regional academies favor self-hosted models for sensitive biometric attendance data under CNIL-equivalent oversight.
India
National Education Policy 2020 digital infrastructure mandates for 400,000-plus public schools drive demand for localized, low-bandwidth adaptive learning platforms. BIS certification requirements shape procurement filters for district-level hardware-software bundles. Maharashtra and Karnataka state education departments negotiate enterprise SaaS contracts with standardized data portability clauses for interstate student mobility.
United Kingdom
Department for Education capital funding streams subsidize multi-academy trust consolidation around standardized management platforms. UK GDPR and Information Commissioner's Office guidance impose encryption and consent architectures for student biometric data. London and Southeast England academy chains aggregate purchasing volume through cooperative procurement consortia with collective cybersecurity insurance arrangements.
France
Regional academies under Ministry of National Education jurisdiction restrict cloud hosting to EU sovereign infrastructure providers. EU AI Act conformity assessment obligations impose documentation requirements for automated scheduling and placement algorithms. Île-de-France and Auvergne-Rhône-Alpes education authorities mandate CE marking for educational software with predictive analytics capabilities.
School Management System Market Vendor Landscape
Global majors compete with regional champions across compliance architecture specialization and installed base depth. The vendor landscape stratifies between database-layer incumbents with ecosystem contract leverage and modular SaaS specialists with API-first integration capabilities. Three archetypes dominate: cloud-native platform builders, legacy ERP extenders, and verticalized K-12 workflow optimizers. Competitive moves concentrate on cooperative purchasing consortium penetration and generative AI feature roadmapping without triggering new regulatory categories.
Within the legacy ERP extender tier, Ellucian Company LP and Jenzabar Inc occupy positions anchoring higher education financial aid and enrollment workflows through deep system integration. Oracle Corporation exemplifies the database-layer incumbent archetype, embedding school management offerings within broader cloud infrastructure contracts. Among K-12-focused platform builders, PowerSchool Group represents the modular SaaS specialist model, sustaining recurring revenue through standardized state reporting compliance and incremental feature add-ons across North American district installed bases.
| Leading Market Players |
|---|
| PowerSchool Group |
| Ellucian Company LP |
| Oracle Corporation |
| Instructure Holdings Inc |
| Blackboard Inc |
| Skyward Inc |
| Infinite Campus Inc |
| Jenzabar Inc |
| Classter |
| Others |
Supply Flow & Price Mechanics
Captive cloud infrastructure development anchors both supply positioning and pricing power for school management system vendors serving data-sovereignty-constrained markets. Vendors maintaining in-country server deployments in Germany and India command premium positioning against multi-tenant competitors while absorbing higher fixed costs that compress margins at lower enrollment scales.
Pricing Analysis
Input-cost pass-through from ISO 27001 certification audits and GDPR-compliant encryption architecture development intensifies pricing pressure across mid-tier SaaS providers. Subscription pricing stratifies across premium, standard, and economy tiers with differentiation driven by API call volume allowances and state reporting module depth. Cost compression in the standard tier stems from cooperative purchasing consortium aggregation across rural United States counties. K-12 institutions with E-Rate subsidized connectivity exhibit highest price sensitivity, while multi-campus higher education configurations with legacy ERP integration requirements demonstrate lowest sensitivity due to switching cost barriers.
Supply Chain Analysis
Single-source vulnerability sits with United States hyperscaler cloud regions for North American K-12 deployments, creating concentration risk for vendors without multi-cloud orchestration capabilities. Software development draws from India, Ireland, and Poland for engineering talent pools, while data center infrastructure sources from Taiwan, South Korea, and domestic German suppliers for edge-computing hardware. Tariff exposure on server components intensifies cost volatility for self-hosted deployment models. Distribution runs through direct enterprise sales teams for large district contracts and regional value-added resellers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
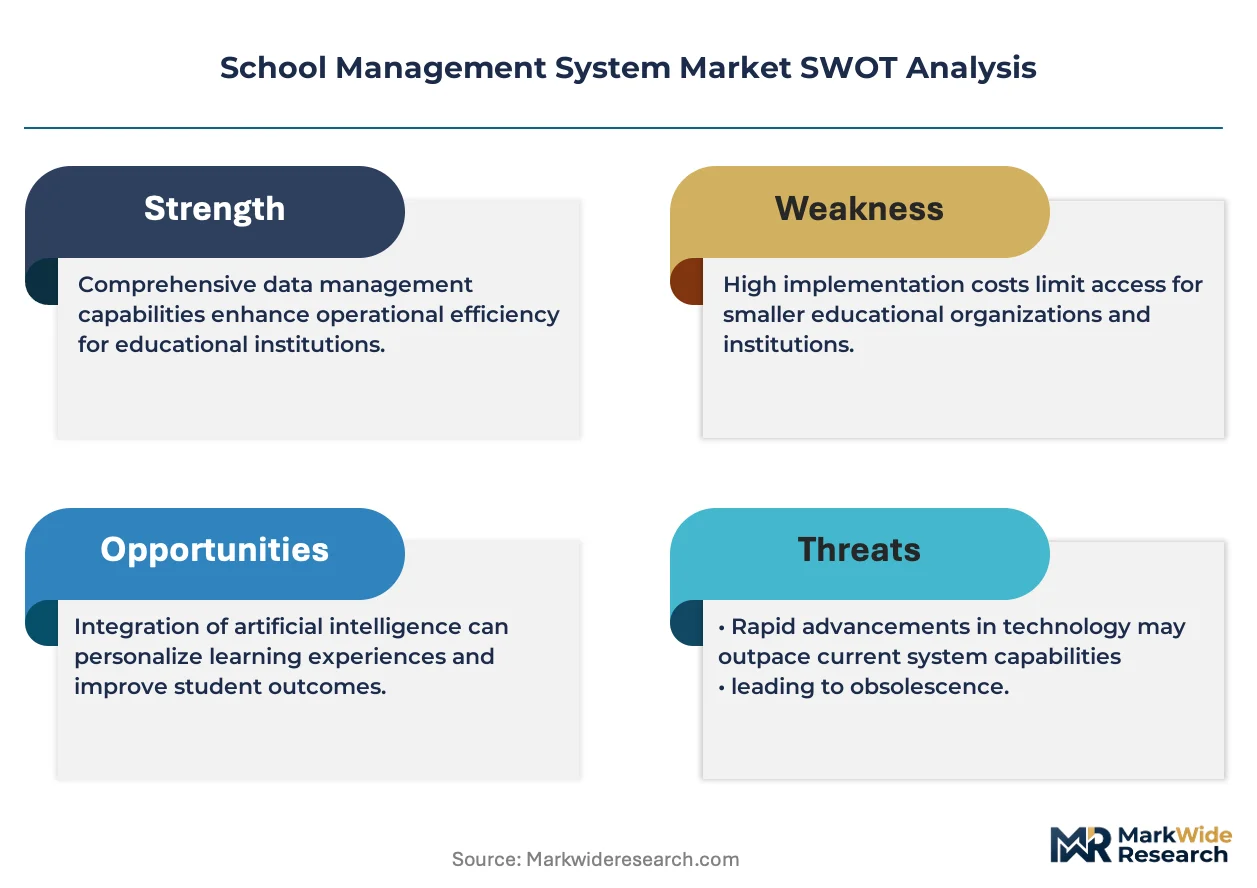
Margin expansion in school management systems rests on containerized microservices architecture reducing per-customer infrastructure costs and generative AI tutoring modules opening premium pricing tiers. Vendors capturing compliance-first positioning in data-sovereignty jurisdictions capture disproportionate value.
For Market Incumbents: Extend API interoperability investments to defend against modular challengers eroding core SIS functionality through best-of-breed point solutions. Deepen vertical integration into edge-computing hardware partnerships for Texas and Florida district emergency response deployments. Certification investment in EU AI Act conformity assessment protocols creates switching cost barriers for higher education admissions platforms. For New Entrants and Emerging Players: Cooperative purchasing consortium digital portals offer low-friction entry paths for standardized SaaS contracts with state-mandated data portability clauses. Rural district consolidation across sparsely populated United States counties represents the most penetrable geography. Direct-to-institution freemium models with viral parent-mobile adoption build land-and-expand traction against incumbent renewal cycles. For Investors and Strategic Acquirers: Roll-up economics work for verticalized K-12 workflow optimizers because state reporting compliance modules create sticky recurring revenue with low churn. Five-to-ten year viability favors vendors with installed base depth in jurisdictions with centralized procurement authority migration. Watch FCC E-Rate funding reauthorization negotiations as inflection indicator for SaaS adoption velocity in under-resourced districts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | RESTful API gateway expansion enables third-party LMS embedding without custom development. |
| Acquisition of Specialist Firm | Biometric attendance hardware vendors add edge-computing capabilities for GDPR-compliant deployments. |
| Geographic Expansion | Localized low-bandwidth adaptive learning platforms capture India National Education Policy 2020 mandates. |
| Strategic Partnership | Hyperscaler sovereign cloud agreements satisfy German state-level data residency prohibitions. |
| Product Launch | Generative AI tutoring modules with compliant training data pipelines open premium pricing tiers. |
Methodological Framework
Multiple input streams — district technology directors, higher education CIOs, state procurement officers, and EdTech integration specialists — were reconciled against vendor SEC filings, FCC E-Rate disbursement databases, and GDPR enforcement action records. Secondary validation drew from IMS Global Learning Consortium specification adoption tracking and cooperative purchasing consortium contract repositories. Bottom-up enrollment-based sizing and top-down education technology budget allocation analysis were cross-referenced for triangulation.
Historical deployment velocity was cross-referenced against panel input from platform engineering leads and K-12 IT administrators to anchor projections across the analysis window. Segmentation dimensions modeled include deployment architecture, institutional tier, integration complexity, and regional regulatory cluster. CAGRs were derived from enrollment growth correlation, SaaS penetration curve fitting, and replacement cycle compression factors specific to legacy ERP lock-in decay.
Regulatory enforcement intensity shifts, hyperscaler pricing volatility, and generative AI training data litigation outcomes are the dominant revision risks for forecast trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Corporate Learning Management System Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
Global Training Software Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market