
 Baby Apparel Market | 2026-2036
Baby Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Apparel Market Analysis
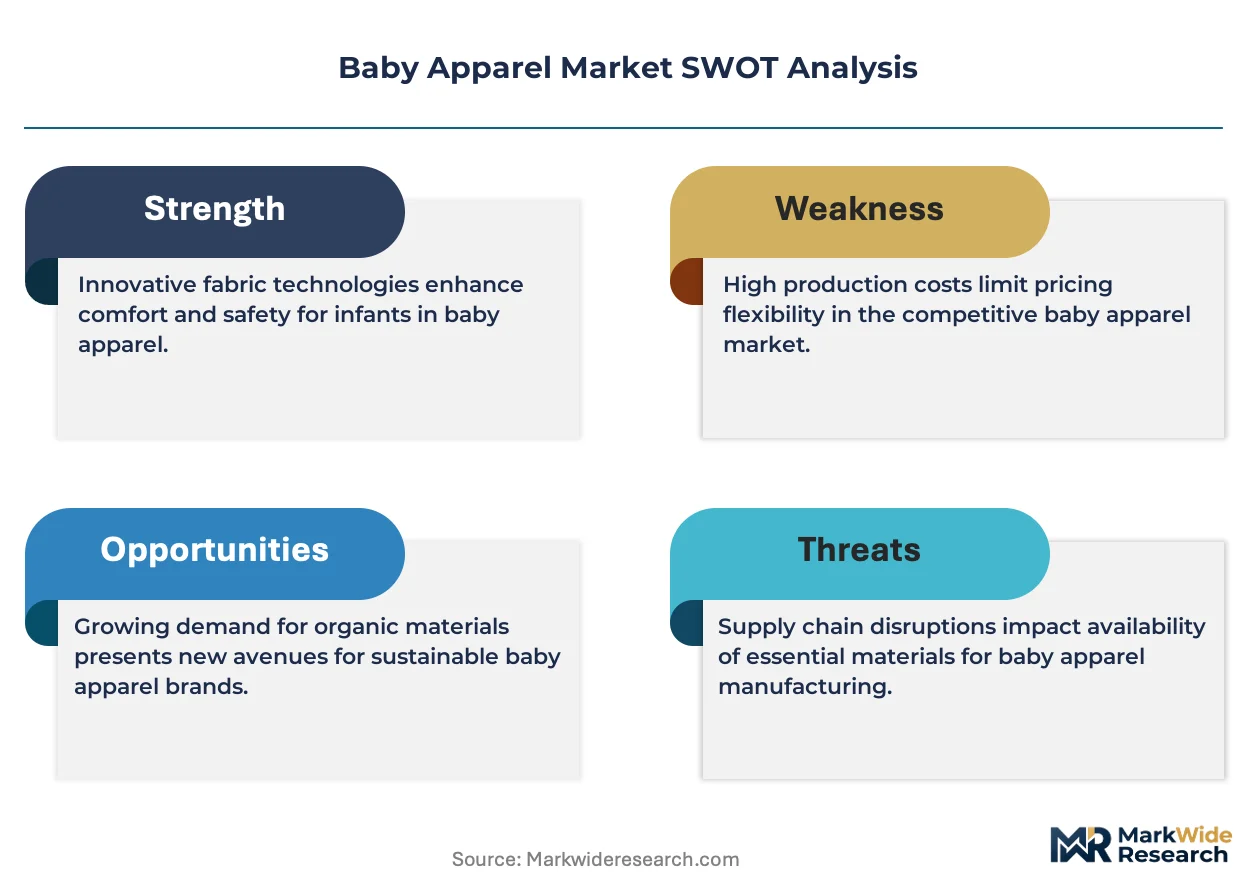
Apparel pattern-making talent is bifurcating the competitive landscape, as brands with in-house technical design teams capture speed-to-market advantages while outsourced manufacturers struggle with fit consistency. Carter's anchors its position through vertical control over North American distribution, reaching mass-market retailers and direct-to-consumer channels with replenishment-focused basics. H&M navigates sustainability mandates by leveraging its global sourcing network to scale organic cotton programs across its baby collections.
Baby apparel encompasses garments engineered for children from birth through preschool age, typically sized by weight and length percentiles rather than standard adult measurements, with construction requiring flat seams, tagless labels, and flame-resistant sleepwear to meet safety protocols. The category serves both functional needs—thermoregulation, ease of diaper access, rapid growth accommodation—and symbolic consumption by gift-givers and parents expressing identity through child presentation. Bodysuits and sleepers dominate volume as repeat-purchase essentials with predictable replacement cycles, while bamboo fiber segments attract premium positioning due to inherent antimicrobial properties and softness metrics that outperform conventional cotton. Outerwear commands disproportionate margin contribution despite lower purchase frequency, as weather-protection specifications justify higher price architecture.
FDA flammability standards for children's sleepwear and CPSC small-parts regulations govern product safety architecture in the United States, while OEKO-TEX and GOTS certification schemes create tiered market access conditions across European and Asian retail channels. Brands must maintain dual compliance frameworks to serve cross-border e-commerce demand without customs detention or marketplace delisting. Stakeholders should monitor evolving extended producer responsibility legislation in key sourcing countries, as textile waste mandates will reshape cost structures for disposable-income-dependent categories.
Market Dynamics
REACH chemical restrictions and CPSIA flammability mandates are forcing brands to requalify entire material libraries, compressing supplier lead times and elevating technical design teams as strategic differentiators in baby apparel sourcing decisions.
Growth Catalysts
- REACH substance restrictions:European chemical safety protocols are eliminating azo dyes and formaldehyde-based finishes from baby garment supply chains, creating certified-material premiums that reward early-adopter brands with shelf-space advantages in EU retail channels.
- Bamboo fiber processing:Closed-loop viscose manufacturing is reducing water intensity in textile production, attracting sustainability-focused millennial parents who prioritize antimicrobial performance in base-layer purchasing decisions.
- E-commerce live-streaming:Chinese digital retail formats are collapsing traditional wholesale markups, enabling domestic brands to capture first-time parent acquisition through real-time fit demonstrations and flash replenishment cycles.
Market Restraints
- Organic cotton supply concentration:Certified fiber production clusters in India and Turkey, exposing brands to monsoon-driven yield volatility and geopolitical processing disruptions that compress margin predictability.
- Dual compliance architecture:Brands serving cross-border demand must simultaneously satisfy FDA flammability standards for sleepwear and OEKO-TEX certification tiers, multiplying testing costs and extending product development timelines.
- Synthetic microfiber substitution:Polyester fleece alternatives are capturing outerwear volume in price-sensitive segments, eroding natural fiber positioning despite inferior thermoregulation performance for infant thermostability.
Strategic Opportunities
- Extended producer responsibility mandates:EU textile waste legislation is creating take-back program infrastructure that brands can leverage for circular collection schemes, converting disposal liability into subscription-based resale revenue streams.
- GOTS-certified rental models:Rapid growth accommodation in infant sizing is enabling garment-as-a-service platforms to capture repeat-purchase value through subscription tiers rather than discrete transaction economics.
- AI-driven pattern grading:Machine learning fit prediction is converging with 3D body scanning data to reduce return rates in direct-to-consumer channels, compressing inventory risk for specialty retailers without physical fitting infrastructure.
Industry Challenges
- Technical pattern-making scarcity:Flat-seam construction expertise and percentile-based grading knowledge are concentrating among aging specialists, constraining speed-to-market for emerging brands dependent on outsourced technical design.
- Flame-resistant finish certification timelines:CPSC sleepwear compliance testing requires multi-batch validation protocols that extend seasonal product launches by eight to twelve weeks, compressing sell-through windows for weather-dependent outerwear.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Apparel Market |
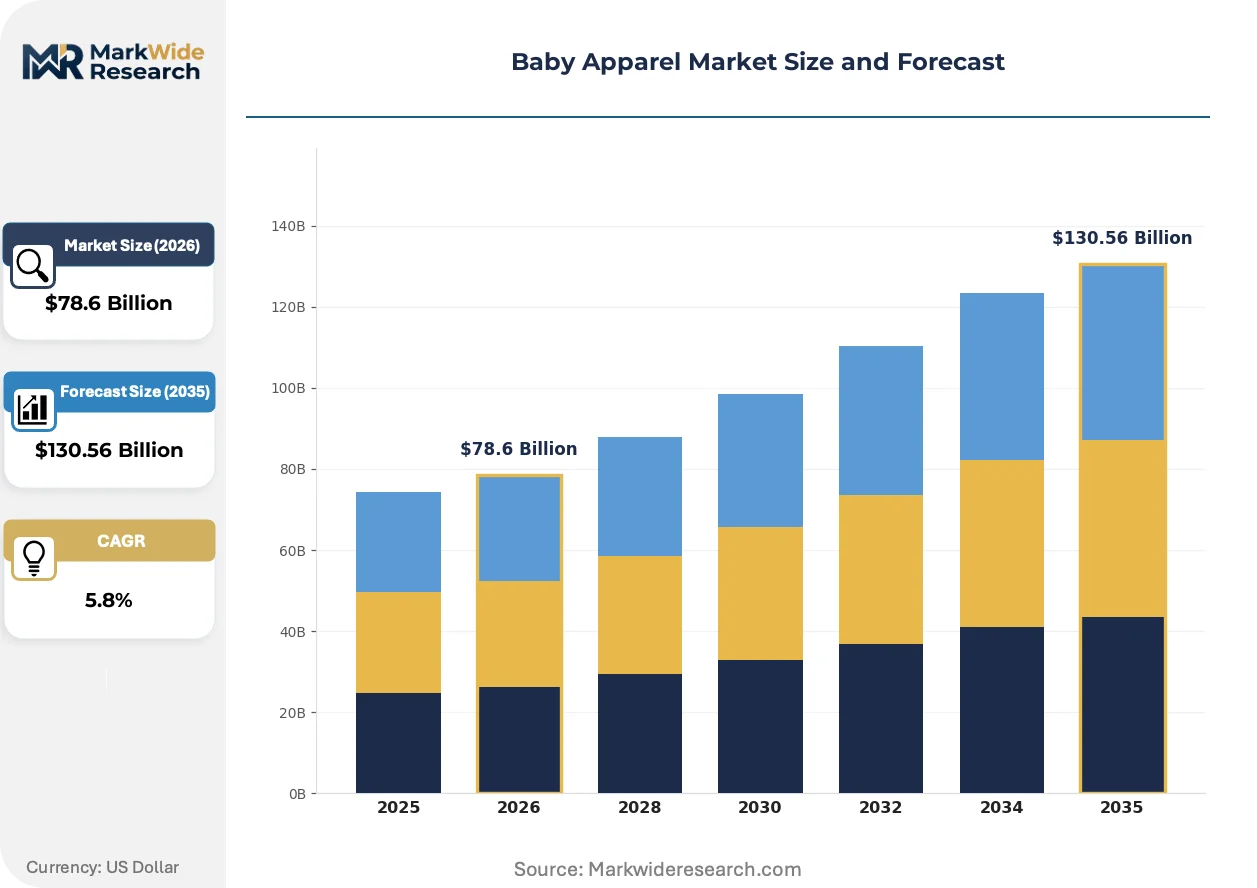
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $130.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bodysuits, Sleepers, Dresses, Outerwear Material: Cotton, Polyester, Wool, Bamboo Age Group: Newborn, Infant, Toddler, Preschool Gender: Unisex, Boys, Girls, Others |
| Companies Covered | Ralph Lauren Corporation, Hanesbrands, Nike, Burberry Group, The Children's Place, Hennes & Mauritz (H&M), Inditex, Old Navy, Carter's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Apparel Market Emerging Trajectories
Material science advances and regulatory disclosure mandates are compressing traditional sourcing hierarchies, while digital-native parents are collapsing discovery-to-purchase cycles through platform-integrated fit tools and transparency scanning applications.
Wearable biometric monitoring is miniaturizing through conductive yarn integration in bodysuit construction, enabling continuous infant temperature and respiratory tracking. Premium positioning parents in South Korea and California are adopting these garments for post-neonatal intensive care monitoring. The technology is miniaturizing hardware requirements to textile-embedded sensors, eliminating separate device procurement and enabling apparel brands to capture recurring data-subscription revenue alongside garment margins.
EU Green Deal textile strategy disclosure requirements are mandating fiber origin documentation and water footprint labeling across member state retail channels. Brands must now map tier-three supplier locations and chemical inputs to maintain marketplace access. Small-batch organic producers in Portugal and Romania are gaining shelf-space advantages over opaque Asian supply chains that cannot satisfy granular traceability audits.
Subscription-based sizing progression is displacing discrete gift purchasing as the dominant acquisition model for first-time parents in urban US and UK markets. Specialty retailers are unbundling traditional layette bundles into monthly curated boxes that anticipate growth percentile transitions. This behavioral shift concentrates lifetime value capture with platform-integrated brands while eroding department store registry economics.
Baby Apparel Market Segmentation
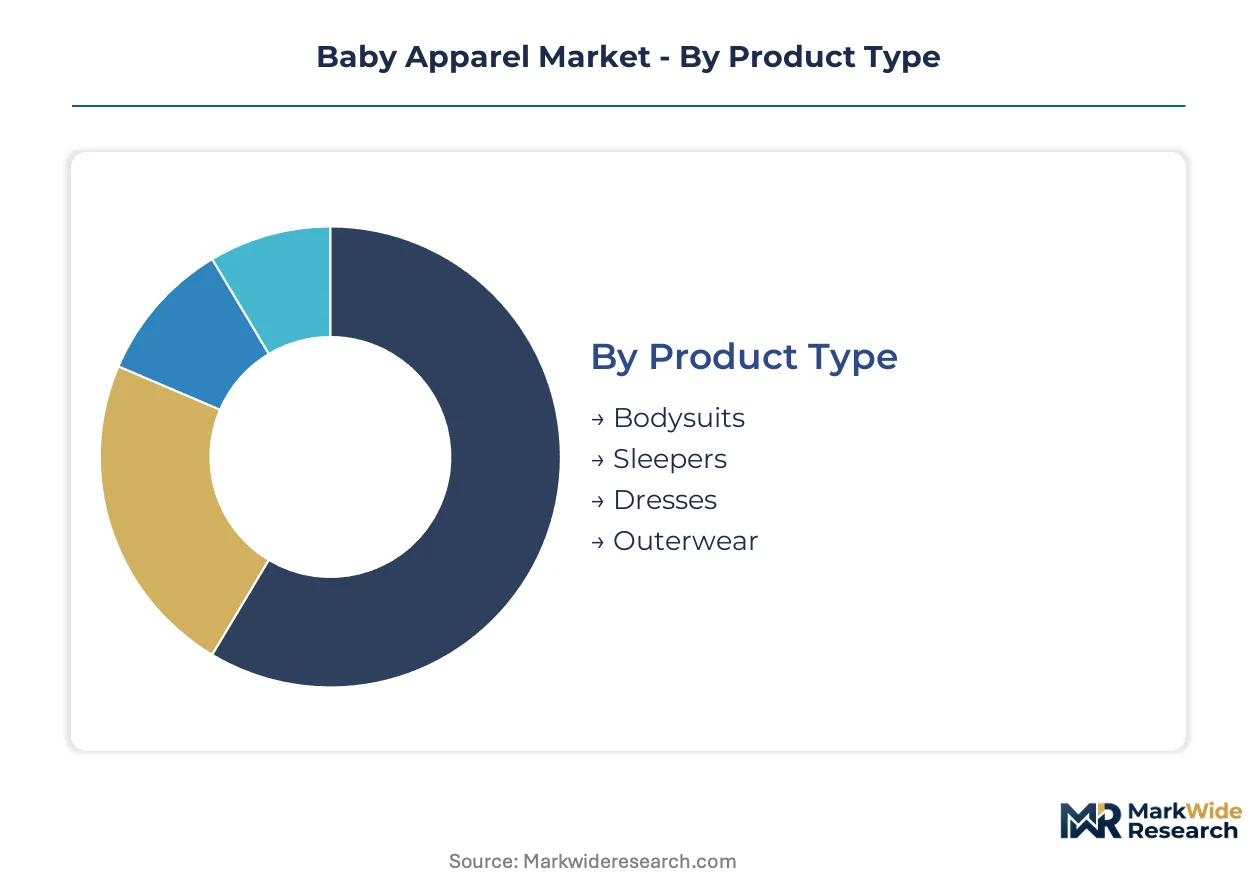
Baby apparel segmentation reflects divergent sourcing logics across product categories, with replenishment essentials and occasion-driven garments following distinct margin and velocity profiles. Material certification tiers and age-based sizing granularity further stratify competitive positioning in specialty versus mass retail channels.
Product Type:
Bodysuits and sleepers concentrate manufacturing in South Asian export clusters serving North American replenishment programs, while outerwear retains domestic production in Turkey and Portugal for EU proximity sourcing.
- Bodysuits:Envelope-neck construction with nickel-free snaps enables rapid diaper access. Demand clusters in US big-box retail channels where Carter's and private-label programs compete on unit-economics for multipack basics.
- Sleepers:Flame-resistant finishes meeting CPSC standards dominate US requirements, while EU REACH compliance favors organic cotton without chemical treatments. Zip-front and magnetic closure variants are gaining share in premium direct-to-consumer channels.
- Dresses:Occasion-driven purchases with higher gift-giving incidence. Seasonal collections from Spanish and Italian brands command boutique placement through embroidery and smocking craftsmanship.
- Outerwear:Weather-protection specifications justify elevated price architecture. Technical fabrics with waterproof-breathable membranes concentrate production in Chinese coastal provinces for cost-sensitive segments.
Bodysuits command the established base. The steepest expansion runs through sleepers as safety-certified organic variants capture millennial parent preference.
Material:
Cost tier stratification separates commodity fiber programs from certified premium positioning, with processing geography determining compliance pathway feasibility.
- Cotton:Conventional upland varieties dominate volume in mass-market channels. GOTS-certified organic grades from Indian and Turkish cooperatives attract EU specialty retail placement under Green Deal disclosure mandates.
- Bamboo:Closed-loop viscose processing reduces water intensity versus conventional rayon. Antimicrobial properties and softness metrics outperform cotton in base-layer applications for South Korean and California premium markets.
- Polyester:Recycled PET fleeces capture outerwear volume in price-sensitive segments. Microfiber shedding concerns are prompting EU regulatory scrutiny of synthetic fiber disposal pathways.
- Wool:Merino grades from Australian and New Zealand origins serve thermoregulation requirements in Nordic and Alpine climates. Machine-washable superwash treatments expand care convenience for urban parents.
Cotton retains volume leadership across all price tiers. Bamboo is climbing the fastest as sustainability positioning converts first-time parent acquisition.
Age Group:
Customer lifecycle progression drives repeat-purchase frequency, with sizing granularity compressing inventory risk for subscription-based business models.
- Newborn:Preemie and 0-3 month sizing requires percentile-based grading expertise. Hospital discharge gift sets concentrate purchasing in US and UK registry channels.
- Infant:Rapid growth accommodation necessitates frequent replacement cycles. Monthly subscription boxes from US specialty retailers capture lifetime value through anticipatory sizing transitions.
- Toddler:Mobility-driven design shifts toward reinforced knees and adjustable waistbands. Potty-training compatibility features differentiate premium positioning in Japanese and German markets.
- Preschool:Extended size ranges overlap with children's apparel categories. Durability specifications intensify as garment life extends beyond seasonal wear.
Infant sizing commands the established base. The steepest expansion runs through toddler segments as mobility-driven functional requirements justify premium pricing.
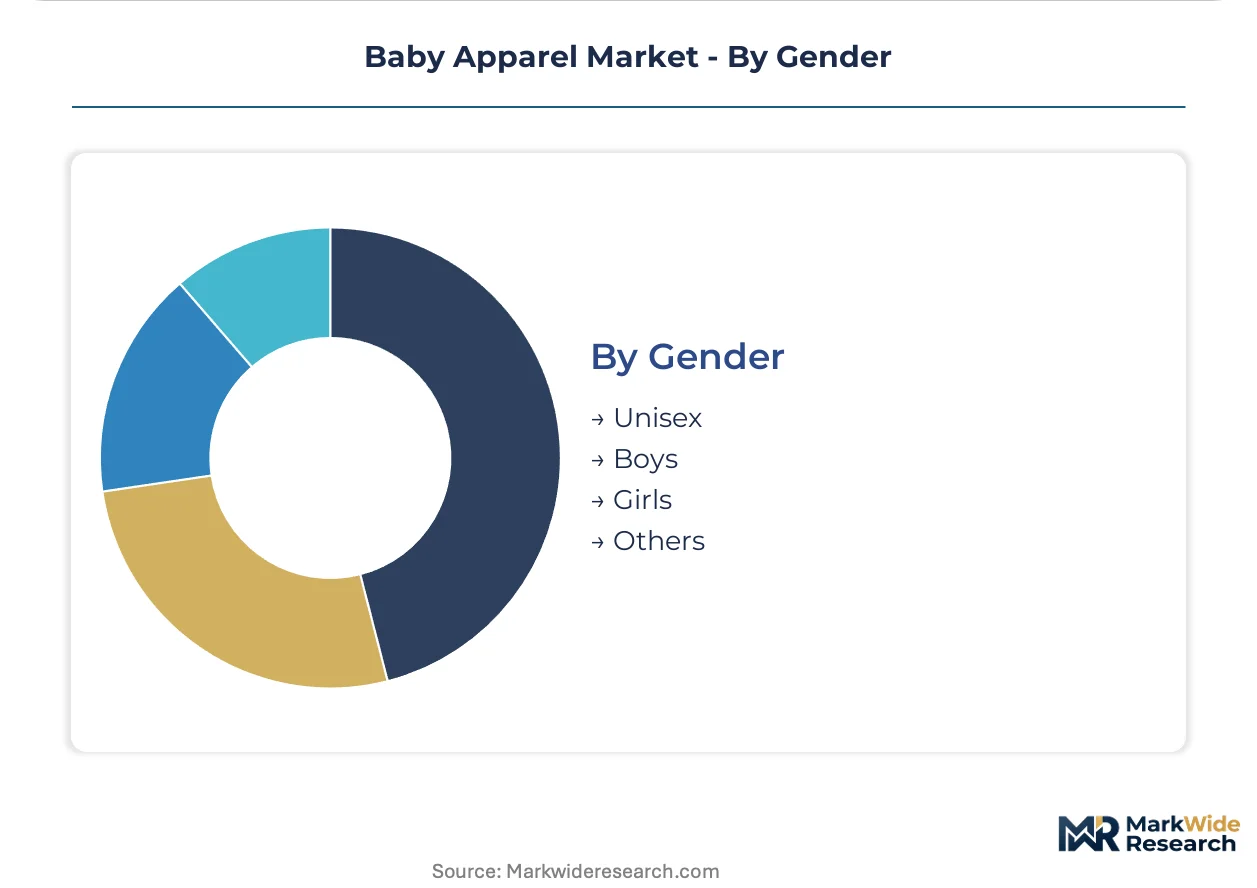
Gender:
Merchandising strategy bifurcates between registry-driven predictability and self-expression positioning, with unisex collections capturing sustainability-minded consolidation purchasing.
- Unisex:Neutral color palettes and minimalist branding reduce inventory fragmentation for retailers. Scandinavian and Japanese brands lead positioning through GOTS-certified essentials.
- Girls:Floral and pastel assortments dominate traditional retail allocation. Embellishment density varies by geography, with French and Italian brands emphasizing hand-finished details.
- Boys:Vehicle and animal motifs concentrate in mass-market channels. UK and US specialty retailers are expanding neutral-core collections with limited accent differentiation.
- Others:Gender-expansive merchandising is emerging in urban coastal US and Canadian markets. Small-batch producers in Brooklyn and Vancouver test inclusive sizing nomenclature.
Unisex positioning commands the established base. The steepest expansion runs through gender-expansive collections as registry economics shift toward consolidation purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CPSC flammability standards and REACH chemical restrictions anchor regulatory complexity in the United States and European Union, while Chinese e-commerce innovation and Indian organic cotton production reshape supply-side geography.
United States
Millennial parents drive demand for GOTS-certified organic basics through direct-to-consumer channels. FDA flammability standards for children's sleepwear mandate multi-batch testing protocols that extend product development timelines. Carter's vertical distribution control reaches mass-market retailers and specialty channels from Atlanta headquarters.
China
Domestic brands capture first-time parent acquisition through e-commerce live-streaming formats with real-time fit demonstrations. SAMR textile labeling requirements enforce fiber content disclosure across Tmall and JD.com marketplaces. Guangdong and Zhejiang coastal provinces concentrate technical outerwear production for cost-sensitive export segments.
Germany
Green Deal disclosure mandates require tier-three supplier mapping and water footprint labeling for marketplace access. ECHA REACH substance restrictions eliminate azo dyes and formaldehyde-based finishes from baby garment supply chains. Bavarian and Baden-Württemberg specialty retailers leverage proximity sourcing from Portuguese organic cotton cooperatives.
India
GOTS-certified organic cotton production clusters in Gujarat and Maharashtra serve EU and North American specialty retail channels. BIS textile quality standards create domestic compliance infrastructure for export-oriented processing units. Monsoon-driven yield volatility exposes brands to margin compression during deficient rainfall cycles.
United Kingdom
Subscription-based sizing progression displaces discrete gift purchasing among urban first-time parents. Trading Standards Institute enforces flammability labeling requirements parallel to EU regulatory frameworks. London-based specialty retailers unbundle traditional layette bundles into monthly curated anticipatory sizing boxes.
Baby Apparel Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with mass-market verticals and premium positioning houses occupying distinct competitive spaces. The structure rewards scale-driven replenishment programs alongside craftsmanship-intensive occasion collections. Three archetypes dominate: North American mass-market verticals with captive distribution, European fast-fashion platforms with global sourcing networks, and luxury heritage houses with symbolic consumption positioning. Competitive moves concentrate on backward integration into organic cotton supply chains and AI-driven fit prediction technology licensing.
Among mass-market verticals, Carter's and The Children's Place exemplify scale-driven replenishment economics with North American distribution concentration. Hennes & Mauritz represents the fast-fashion platform archetype, leveraging global sourcing networks to scale certified material programs across baby collections. Ralph Lauren Corporation anchors the luxury heritage positioning, where symbolic consumption by gift-givers justifies elevated price architecture through brand equity rather than functional differentiation.
| Leading Market Players |
|---|
| Ralph Lauren Corporation |
| Hanesbrands |
| Nike |
| Burberry Group |
| The Children's Place |
| Hennes & Mauritz (H&M) |
| Inditex |
| Old Navy |
| Carter's |
| Others |
Supply Flow & Price Mechanics
Capacity utilization in South Asian cut-and-sew clusters shapes both minimum order quantities and price floors for baby apparel brands sourcing replenishment basics. Scale advantages in Bangladesh and Vietnam enable mass-market players to compress unit costs below what smaller European producers can achieve under REACH compliance burdens.
Pricing Analysis
Geographic price spreads between EU-certified organic cotton garments and conventional Asian-produced basics exceed three-to-one multiples at retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because polyester fleece substitutes are eroding natural fiber positioning. Mass-market big-box buyers exhibit highest price sensitivity, while direct-to-consumer subscription parents accept premium positioning for GOTS-certified materials.
Supply Chain Analysis
Gujarat cotton ginning capacity acts as a chokepoint for GOTS-certified fiber flowing to EU and North American specialty channels. Raw material flows draw from Indian organic cooperatives, Turkish processing units, and Chinese viscose manufacturers. Single-source vulnerability concentrates in monsoon-dependent Indian cotton yields. Distribution runs through vertically controlled North American networks and Chinese e-commerce live-streaming platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based sizing progression represents a service-attach opportunity expanding faster than discrete garment transactions, converting one-time gift economics into recurring revenue capture.
For Market Incumbents: Shield core replenishment volume by backward integration into GOTS-certified cotton supply chains before Indian yield volatility disrupts margin predictability. Defend against domestic Chinese brands by accelerating AI-driven fit prediction deployment to reduce direct-to-consumer return rates. Channel control through owned subscription platforms offers the strongest defensive lever against marketplace disintermediation. For New Entrants and Emerging Players: OEKO-TEX certification fast-track enables shelf-space access in German and UK specialty retail channels with shorter validation timelines than GOTS conversion. White-space exists in toddler mobility-driven segments where reinforced-knee construction commands premium positioning underserved by mass-market players. Target urban US subscription box penetration with anticipatory sizing algorithms as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-enabled fit prediction specialists over commodity garment producers as return-rate compression becomes the dominant value driver. Long-term viability hinges on circular infrastructure readiness under extended producer responsibility mandates. Watch EU textile waste legislation implementation velocity as the signal for subscription-model valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Fast-Track | Accelerates EU market access ahead of Green Deal disclosure mandate enforcement. |
| AI-Driven Fit Prediction Investment | Reduces return rates for direct-to-consumer channels without physical fitting infrastructure. |
| Subscription Platform Launch | Captures lifetime value through anticipatory sizing rather than discrete transactions. |
| Backward Integration into Organic Cotton | Secures margin predictability against Indian monsoon-driven yield volatility. |
| Circular Collection Infrastructure | Converts EU extended producer responsibility liability into resale revenue streams. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with brand sourcing directors, technical design leads, specialty retail buyers, and subscription platform operators; and secondary validation through GOTS certification databases, EU customs textile trade records, and CPSC compliance filing repositories. Bottom-up demand modeling triangulated against top-down market sizing from trade association disclosures.
Across the projection horizon, the analytical framework segmented volume and value by product type, material certification tier, age-based sizing granularity, and gender merchandising strategy. CAGRs were derived from growth rate convergence modeling applied to historical shipment data and forward-looking parent demographic projections. Forecast inputs incorporated e-commerce live-streaming penetration curves and REACH substance restriction implementation timelines.
Decision-makers should treat outputs as directional under sustained millennial parent preference for organic materials; material deviation would warrant model refresh if synthetic fiber substitution accelerates beyond current trajectory. Practitioners should keep alternative scenarios live as EU textile waste mandate enforcement evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO