
 Global Artificial Intelligence for Accounting Market | 2026-2036
Global Artificial Intelligence for Accounting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence for Accounting Market Foresight
The EU AI Act is broadening compliance obligations for automated financial decision systems across European accounting firms and corporate finance departments. Intuit Inc. leverages its TurboTax and QuickBooks ecosystems to embed AI-driven tax compliance workflows for small and medium enterprises. Deloitte anchors its audit practice with proprietary machine learning models that flag anomalous transactions across multinational client portfolios. Microsoft Corporation extends its Copilot architecture into Excel and Dynamics 365, competing for enterprise budgeting and forecasting workloads against specialized fintech entrants.
Artificial intelligence for accounting encompasses machine learning algorithms, natural language processing engines, and robotic process automation tools trained on structured financial data to execute bookkeeping, audit, and forecasting tasks with minimal human intervention. Cloud-based deployment leads solution delivery, though edge computing configurations are gaining traction among banking-sector clients requiring localized inference for sensitive payroll processing. Invoice automation and fraud detection command the largest solution-type revenue pools, while regulatory reporting applications show the steepest growth trajectory as jurisdictional disclosure requirements multiply. Corporate finance teams represent the most concentrated end-user segment, yet accounting firms are expanding faster as partnership networks consolidate vendor relationships.
The SEC, EBA, and EU AI Act collectively shape product development roadmaps, mandating explainability standards for algorithmic audit tools and granular documentation of automated risk assessments. GDPR and CSRD intersect with accounting AI by requiring auditable data lineage for sustainability metrics processed through financial planning software. Stakeholders must monitor divergence between U.S. disclosure frameworks and EU algorithmic accountability rules when architecting cross-border deployment strategies.
Market Dynamics
The EU AI Act's explainability mandates are forcing accounting software vendors to re-architect their machine learning pipelines around auditable decision trails rather than black-box predictions.
Growth Catalysts
- Algorithmic accountability mandates:The EU AI Act and CSRD disclosure rules require automated financial systems to maintain granular audit logs, expanding procurement of compliance-ready platforms across European corporate finance departments.
- IRS modernization:The US Internal Revenue Service's digitization initiatives are accelerating deployment of automated tax compliance tools by enterprises seeking to preempt enforcement actions.
- Cloud infrastructure maturation:Multi-tenant SaaS architectures now support real-time inference on encrypted financial data, removing latency barriers that previously constrained AI adoption in payroll processing.
Market Restraints
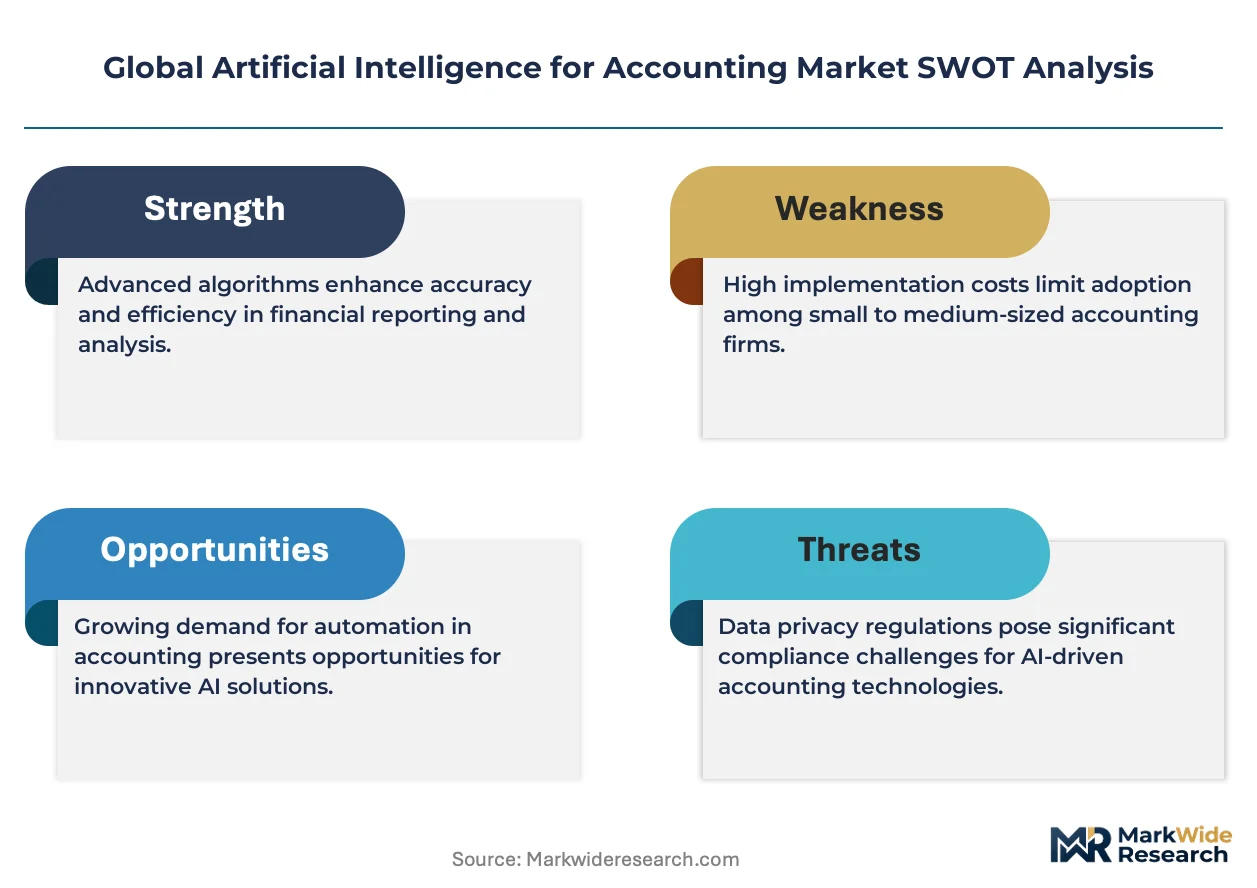
- Compute cost volatility:GPU cluster pricing fluctuations are compressing margins for vendors training large language models on proprietary audit datasets.
- Data localization requirements:GDPR's cross-border transfer restrictions fragment training data pools, forcing redundant infrastructure deployment across EU member states.
- Explainability-performance tradeoffs:Interpretable machine learning techniques sacrifice predictive accuracy, limiting their utility in complex fraud detection scenarios.
Strategic Opportunities
- Mid-market penetration:Small and medium enterprises in Germany and France remain underserved by current vendor pricing tiers, creating whitespace for modular, per-seat AI bookkeeping tools.
- Sustainability-integrated reporting:The CSRD's double materiality requirements are opening demand for AI platforms that reconcile financial and environmental metrics within unified disclosure workflows.
- Edge computing convergence:Banking-sector clients in Switzerland and Singapore are piloting localized inference for sensitive payroll data, combining on-premise hardware with cloud-trained models.
Industry Challenges
- Cross-functional talent scarcity:Firms struggle to hire professionals conversant in both International Financial Reporting Standards and transformer model architecture.
- Legacy ERP integration friction:Decades-old on-premise accounting systems lack API connectivity, requiring expensive middleware development for AI augmentation.
- Certification timeline compression:The EU AI Act's conformity assessment deadlines are outpacing vendors' ability to document algorithmic risk management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence for Accounting Market |
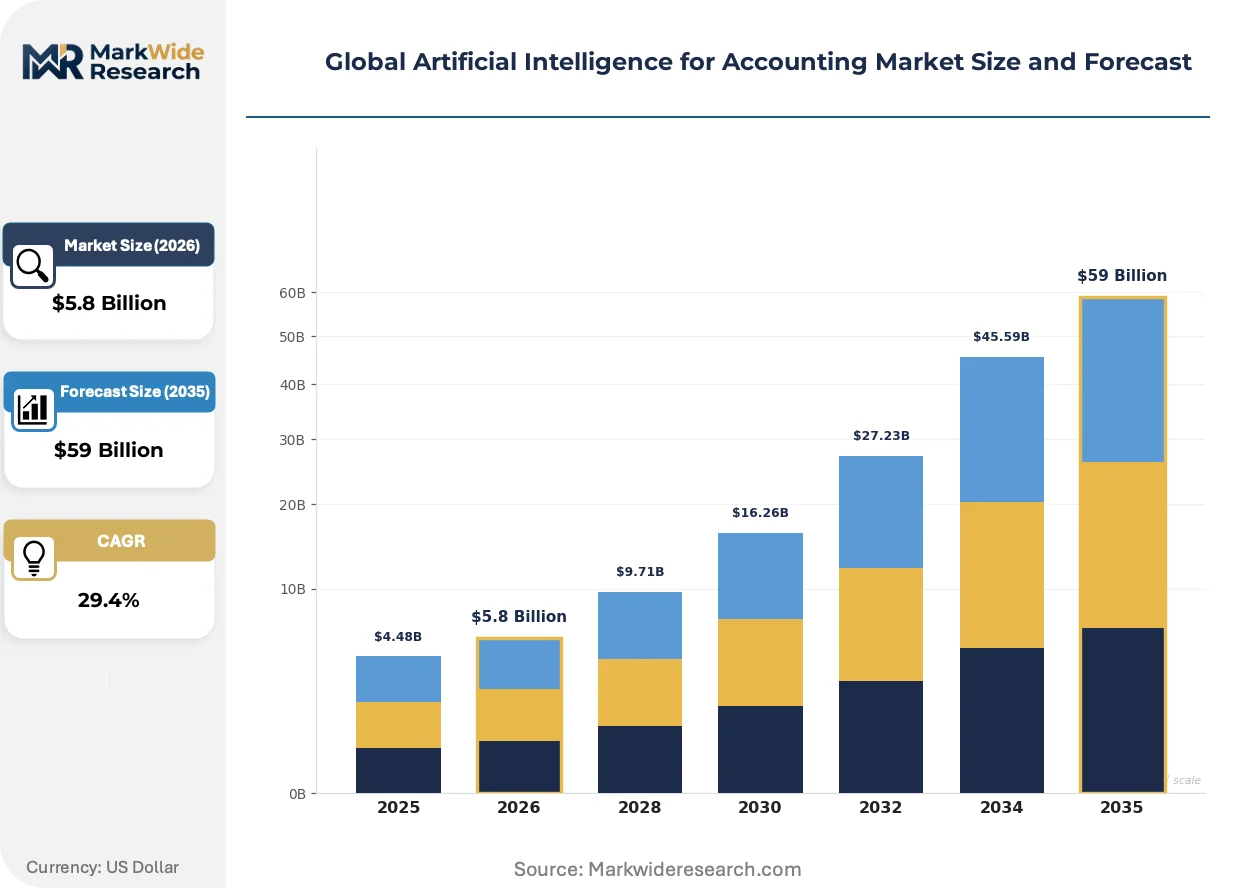
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $59 Billion |
| CAGR (2026 – 2036) | 29.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Invoice Automation, Expense Management, Fraud Detection, Financial Forecasting, Auditing Software Application: Tax Compliance, Budget Planning, Risk Assessment, Payroll Processing, Regulatory Reporting End User: Accounting Firms, Corporate Finance Teams, Small & Medium Enterprises, Tax Consultants, Bookkeeping Services |
| Companies Covered | Intuit Inc., AppZen Inc., Bill.com, Inc., Botkeeper, Inc., Deloitte, IBM, Microsoft Corporation, SAP SE, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence for Accounting Market Shifts & Advancements
Generative AI is restructuring how accounting workflows are automated, shifting competitive advantage from rule-based engines toward systems capable of contextual reasoning across unstructured financial documents.
Large language models fine-tuned on International Accounting Standards are integrating natural language interfaces into audit preparation tools. Mid-tier accounting firms in the United Kingdom and Australia are deploying these systems to compress documentation review cycles. The technology is integrating previously siloed tasks—contract analysis, journal entry validation, and variance explanation—into unified conversational workflows.
The SEC's climate disclosure rules are mandating machine-readable sustainability reporting formats. Asset managers and public issuers must now submit structured ESG data alongside traditional financial statements. Investment banks and corporate treasury functions are reconfiguring their planning software to capture Scope 3 emissions data, with US-based vendors accelerating product roadmaps to meet the 2026 filing deadlines.
Subscription pricing for AI accounting modules is displacing perpetual license models across North American and European mid-markets. Chief financial officers are demanding consumption-based billing tied to document volumes processed rather than seat counts. This shift is most pronounced in the United States, where private equity-backed portfolio companies are consolidating vendor relationships around platforms offering flexible cost scaling through economic cycles.
Global Artificial Intelligence for Accounting Market Segmentation
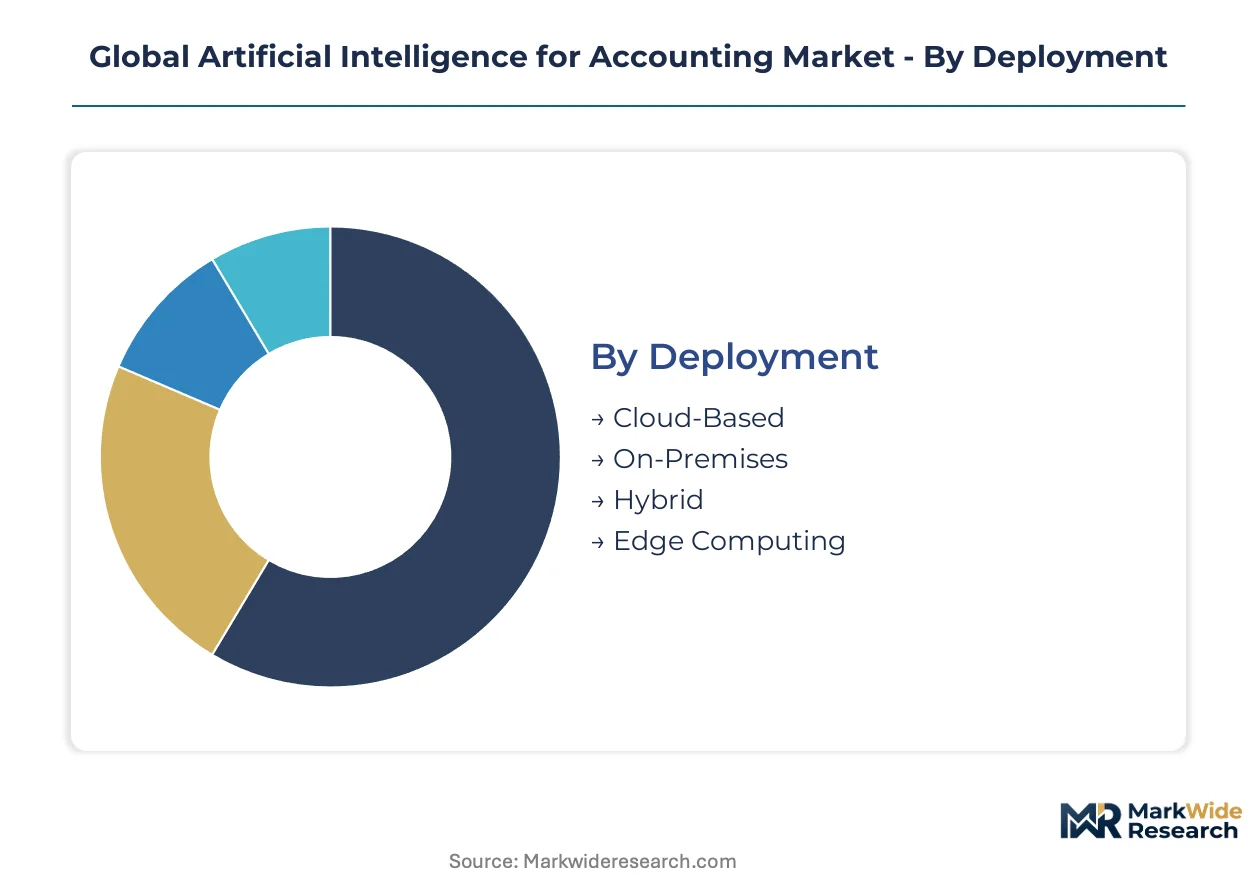
Segmentation reveals how AI capabilities embed at different depths within accounting technology stacks. Deployment modes determine data sovereignty tradeoffs, while solution types expose where automation delivers measurable labor displacement versus augmentation.
Deployment:
Standalone cloud architectures dominate procurement volumes, yet embedded edge configurations are penetrating banking infrastructure where latency constraints override cost efficiency.
- Cloud-Based:Multi-tenant SaaS platforms host the majority of machine learning inference for invoice automation and tax compliance workflows. Corporate finance teams in the United States and Germany favor this model for elastic scaling through quarterly close cycles.
- On-Premises:Legacy ERP integrations and data residency mandates drive continued investment in localized server infrastructure. Swiss banking clients and Japanese manufacturing conglomerates maintain these deployments for sensitive payroll processing.
- Hybrid:Split architectures train models in cloud environments while executing inference on localized hardware. This configuration satisfies GDPR cross-border restrictions without sacrificing algorithmic sophistication.
- Edge Computing:Micro-datacenter deployments at branch locations enable real-time fraud detection without WAN dependency. Singaporean financial institutions pilot these systems for high-frequency transaction monitoring.
Cloud-Based deployments lead volumes today; Edge Computing is gaining share fastest.
Solution Type:
Revenue concentration follows document-processing intensity, with high-volume transactional workflows commanding premium pricing against analytical forecasting tools.
- Invoice Automation:Optical character recognition pipelines extract line-item data from supplier documents, eliminating manual entry for accounts payable departments. Manufacturing and retail enterprises in France and Italy deploy these systems to compress procurement cycle times.
- Fraud Detection:Anomaly detection algorithms flag anomalous payment patterns and duplicate vendor records. Banking-sector procurement in the United Kingdom concentrates demand here as authorized push payment fraud escalates.
- Expense Management:Mobile receipt capture and policy enforcement engines streamline employee reimbursement workflows. Mid-market professional services firms represent the primary adoption cohort.
- Financial Forecasting:Time-series models project cash flows and revenue trajectories from historical ledger data. Treasury functions at multinational corporations integrate these tools with ERP planning modules.
- Auditing Software:Machine learning classifiers prioritize journal entry samples for substantive testing. EU AI Act documentation requirements are accelerating procurement across Big Four partnership networks.
Invoice Automation captures the largest revenue pool; Auditing Software shows the steepest expansion trajectory.
Application:
Functional use cases map directly to regulatory pressure intensity, with compliance-mandated workflows outpacing discretionary planning tools.
- Tax Compliance:Automated calculation engines reconcile jurisdictional rate tables with transactional data. IRS modernization initiatives and Making Tax Digital mandates in the United Kingdom are synchronizing demand spikes.
- Regulatory Reporting:Structured data generation for SEC climate disclosures and CSRD sustainability metrics. Asset managers and public issuers in the United States and European Union reconfigure systems for machine-readable ESG submissions.
- Budget Planning:Driver-based modeling tools link operational metrics to financial projections. Corporate finance teams deploy these for rolling forecast updates between annual planning cycles.
- Risk Assessment:Credit scoring and counterparty exposure models for treasury and insurance functions. Basel III liquidity coverage ratio calculations represent a specialized sub-segment.
- Payroll Processing:Gross-to-net calculation engines with jurisdictional withholding logic. GDPR sensitivity drives hybrid deployment preferences for this application.
Tax Compliance anchors current procurement volumes; Regulatory Reporting is climbing the fastest.
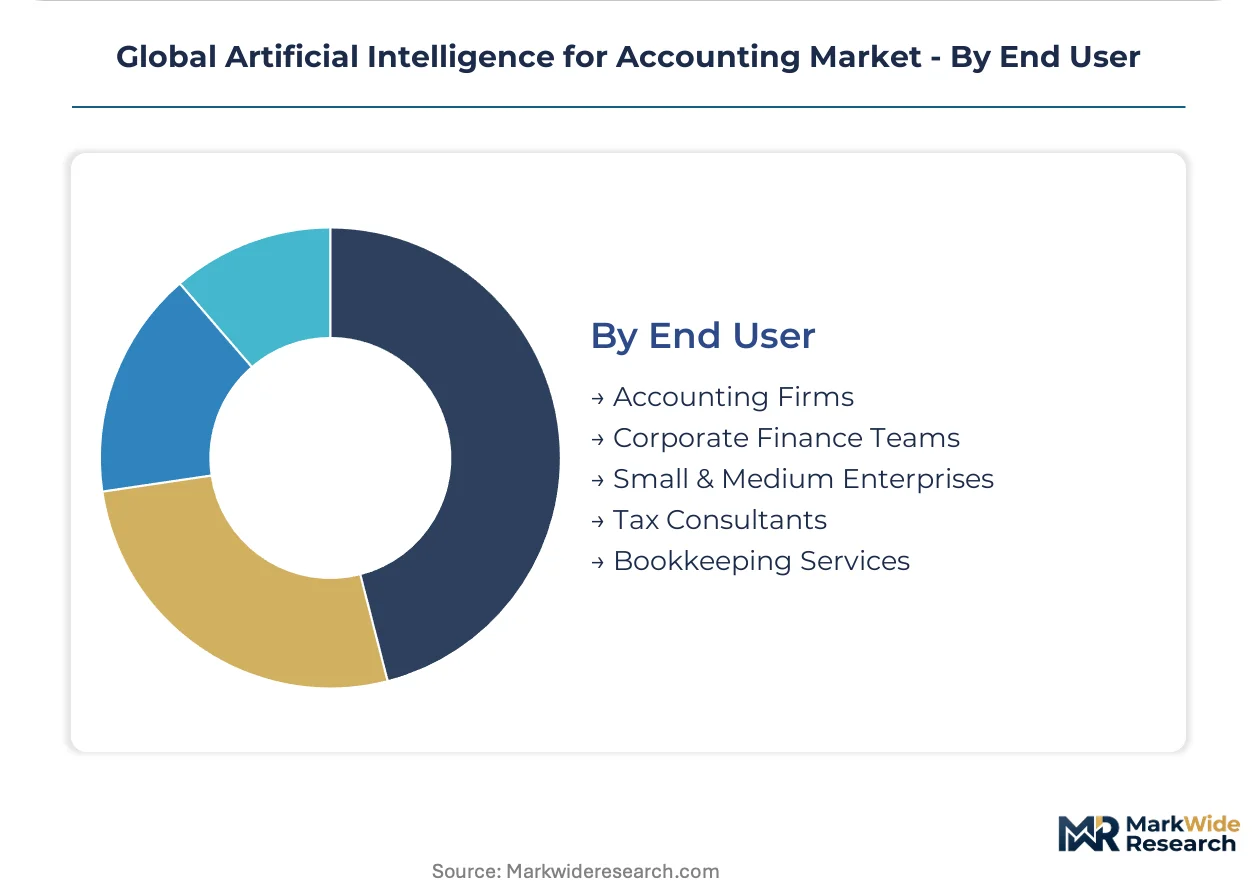
End User:
Customer type determines pricing tolerance and implementation complexity, with consolidated enterprise buyers extracting volume discounts unavailable to fragmented professional services.
- Corporate Finance Teams:Centralized procurement of integrated platforms spanning forecasting, reporting, and compliance. Fortune 500 treasury and controller functions in the United States represent the highest contract values.
- Accounting Firms:Partnership networks standardizing audit methodology through vendor consolidation. Deloitte, PwC, EY, and KPMG affiliate practices are synchronizing tool selection across country operations.
- Small & Medium Enterprises:Modular per-seat subscriptions for bookkeeping and tax preparation. German Mittelstand companies and French PMEs remain underserved by current vendor pricing tiers.
- Tax Consultants:Specialized practitioners requiring jurisdictional depth over functional breadth. Seasonal demand patterns favor consumption-based billing models.
- Bookkeeping Services:Outsourced providers automating high-volume transaction coding for client portfolios. Cloud-native entrants target this segment with aggressive per-document pricing.
Corporate Finance Teams dominate contract values; Accounting Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The artificial intelligence for accounting industry traces its commercial origins to Silicon Valley's enterprise software expansion during the 2010s, when cloud infrastructure first enabled scalable machine learning deployment for financial workflows. Early adoption concentrated among Fortune 500 treasury functions in the United States before spreading to European regulatory technology clusters.
United States
Corporate finance teams in New York and Chicago drive procurement of automated tax compliance platforms as the IRS accelerates digitization initiatives. The SEC's climate disclosure rules mandate machine-readable sustainability reporting, forcing asset managers to reconfigure planning software. Silicon Valley vendors anchor development of large language models fine-tuned on International Accounting Standards.
Germany
Mittelstand companies in Bavaria and North Rhine-Westphalia represent underserved whitespace for modular AI bookkeeping tools priced per-seat rather than by enterprise contract. The EU AI Act's explainability mandates compel vendors to re-architect machine learning pipelines around auditable decision trails. Frankfurt's banking cluster pilots hybrid cloud-edge configurations for sensitive payroll processing.
United Kingdom
Mid-tier accounting firms in London and Manchester deploy natural language interfaces to compress documentation review cycles for audit preparation. Making Tax Digital mandates synchronize demand spikes for automated calculation engines reconciling jurisdictional rate tables. The Financial Conduct Authority's algorithmic accountability guidance shapes procurement criteria for fraud detection systems.
France
PMEs in Île-de-France and Auvergne-Rhône-Alpes seek consumption-based billing models as subscription pricing displaces perpetual licenses across European mid-markets. The CSRD's double materiality requirements open demand for platforms reconciling financial and environmental metrics within unified disclosure workflows. Paris-based asset managers reconfigure systems for Scope 3 emissions data capture.
Singapore
Financial institutions in the central business district pilot edge computing micro-datacenters for real-time fraud detection without WAN dependency. The Monetary Authority of Singapore's technology risk management guidelines accelerate procurement of localized inference systems for high-frequency transaction monitoring. Regional headquarters of multinational banks use Singapore as a testbed before broader Asia-Pacific rollout.
Global Artificial Intelligence for Accounting Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light software architects across divergent margin structures in the artificial intelligence for accounting market. The vendor base stratifies into three tiers: global technology conglomerates with embedded productivity suites, specialized fintech entrants with cloud-native architectures, and professional services networks consolidating audit methodology through proprietary machine learning models. Dominant competitive moves include strategic partnerships bridging legacy ERP connectivity gaps and portfolio diversification into sustainability-integrated reporting modules.
Within the technology conglomerate tier, Microsoft Corporation and Oracle Corporation exemplify platform-centric positioning that extends existing productivity and database ecosystems into automated financial workflows. SAP SE anchors the enterprise application segment with deeply integrated planning and compliance modules. Intuit Inc. occupies a distinct position serving small and medium enterprises through tax preparation and bookkeeping ecosystems. Deloitte represents the professional services archetype, embedding proprietary anomaly detection within multinational audit practices.
| Leading Market Players |
|---|
| Intuit Inc. |
| AppZen Inc. |
| Bill.com, Inc. |
| Botkeeper, Inc. |
| Deloitte |
| IBM |
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Horizontal integration into cloud infrastructure partnerships anchors supply positioning while compressing pricing power for standalone software vendors. Microsoft and Oracle leverage captive hyperscaler networks to bundle AI accounting modules at marginal cost, forcing specialized entrants toward per-seat transactional models. The EU AI Act's certification overhead feeds back into premium tier pricing for auditable platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by explainability certification depth and ERP integration complexity. Premium tiers command differentiation through EU AI Act conformity documentation and dedicated implementation support, while economy tiers compete on per-document processing rates. Cost compression in the mid-market intensifies as Intuit and Botkeeper automate high-volume bookkeeping workflows. Small and medium enterprises in Germany and France exhibit the highest price sensitivity, whereas Fortune 500 treasury functions prioritize compliance-grade platforms over unit economics.
Supply Chain Analysis
Regional distribution centers for GPU compute clusters concentrate in the United States, Ireland, and Singapore to satisfy GDPR data residency mandates and latency requirements for real-time fraud detection. Model training draws from proprietary audit datasets held by Deloitte and PwC partnership networks, plus synthetic financial document generators. Single-source vulnerability in NVIDIA's AI accelerator supply creates procurement bottlenecks for vendors building large language models. Distribution runs through multi-tenant SaaS platforms with localized edge inference nodes for banking-sector payroll applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial intelligence for accounting market compounds regulatory complexity into durable demand, with the EU AI Act's conformity assessment deadlines forcing procurement cycles across European corporate finance departments.
For Market Incumbents: Acquire specialized sustainability reporting startups to capture CSRD double materiality workflows before modular entrants consolidate. Defend against cloud-native bookkeeping platforms by embedding explainability documentation directly into Dynamics 365 and SAP S/4HANA integration layers. Capacity expansion in Frankfurt and Singapore data centers secures latency advantages for high-frequency transaction monitoring. For New Entrants and Emerging Players: German Mittelstand companies represent an underserved buyer archetype seeking per-seat AI bookkeeping tools priced below enterprise contract minimums. French PMEs in Île-de-France demonstrate parallel whitespace for consumption-based billing models displacing perpetual licenses. Channel partnerships with regional tax consultancy networks provide the most penetrable go-to-market angle against incumbent direct sales forces. For Investors and Strategic Acquirers: Consolidation pressure builds where explainability certification costs exceed standalone vendor R&D budgets, favoring acquisition of mid-tier audit automation specialists by platform conglomerates. Long-term viability hinges on regulatory moat depth rather than algorithmic performance alone. Watch the SEC's climate disclosure enforcement timeline as the inflection signal for sustainability-integrated reporting platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft embeds Copilot into Excel to capture enterprise forecasting workloads from specialized fintech vendors. |
| Regulatory Certification Investment | Deloitte documents algorithmic risk management protocols to satisfy EU AI Act conformity assessment deadlines ahead of competitors. |
| Strategic Partnership | Intuit leverages TurboTax ecosystem partnerships to distribute AI-driven tax compliance workflows across small business banking channels. |
| Acquisition of Specialist Firm | Oracle acquires edge computing startups to localize payroll inference for Swiss banking clients under GDPR cross-border restrictions. |
| Geographic Expansion | SAP SE expands Frankfurt data center capacity to serve Mittelstand demand for hybrid cloud-edge accounting deployments. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region's corporate finance technology procurement clusters. The research combines structured interviews with CFOs, treasury controllers, audit partners at Big Four networks, and cloud infrastructure procurement officers with secondary validation against SEC climate disclosure filings, EU AI Act implementation guidance, and IRS modernization program updates. Bottom-up vendor revenue triangulation against top-down enterprise software spending estimates anchors market size calculations.
Granularity-level modeling segments the market by deployment architecture, solution type, functional application, and end-user organization size across the projection horizon. Deployment modes distinguish multi-tenant SaaS from hybrid and edge configurations. Solution types separate document-processing intensity from analytical forecasting tools. CAGRs derive from regression analysis of historical procurement cycles against regulatory mandate timelines, incorporating GPU cost volatility and cross-border data transfer restriction scenarios.
Inputs from vendor financial disclosures and regulatory agency implementation schedules were available through the study window; gaps in private mid-market transaction pricing introduce uncertainty bands around small and medium enterprise penetration estimates. Forecasts reflect documented assumptions regarding EU AI Act enforcement intensity and SEC climate disclosure rule durability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
South Africa Forensic Accounting Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Bookkeeping Services Market