
 Argentina Accounting Software Market | 2026-2036
Argentina Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Accounting Software Market Insights
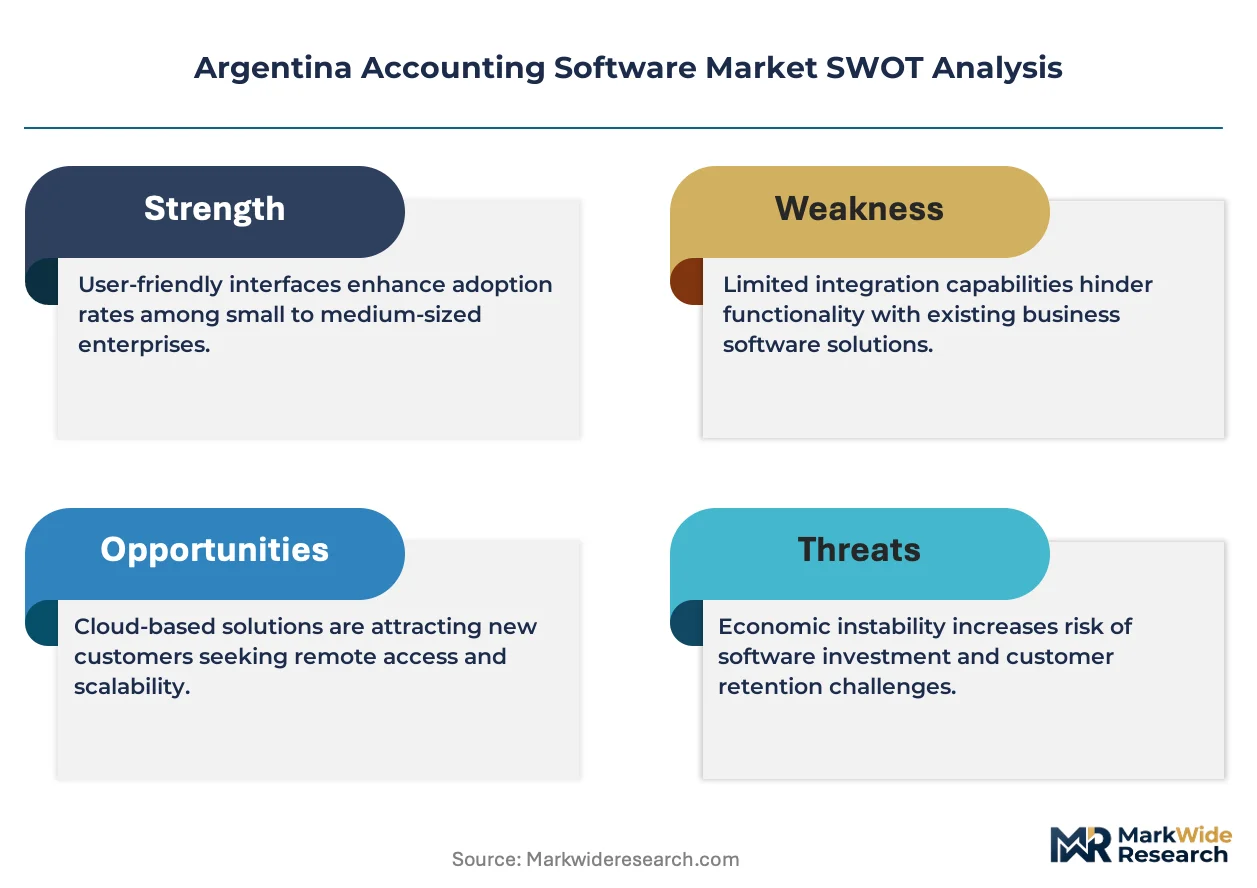
Subscription-based financing and asset-light SaaS licensing is reconfiguring competitive entry barriers for Argentine software vendors. SAP SE leverages deep ERP integration to anchor large-enterprise accounts in Buenos Aires. Xero Limited specializes in freelancer-friendly interfaces that sustain rapid onboarding cycles. Colppy competes through localized tax-code compliance that dominates mid-market procurement decisions.
Accounting software encompasses systems that automate ledger management, tax computation, and financial reporting through double-entry bookkeeping protocols and real-time bank reconciliation engines. Cloud-based deployment leads structural expansion due to lower upfront capital requirements and automatic AFIP compliance updates, while on-premises solutions retain margin pools among enterprises with strict data sovereignty requirements. The accountant user segment represents the fastest-growing category as independent practitioners consolidate client workflows onto unified platforms.
Argentina's Administración Federal de Ingresos Públicos mandates electronic invoicing and real-time tax reporting, forcing vendors to embed continuous regulatory updates. BIS-aligned data localization norms and AFIP's RG 4290/17 framework shape product architecture and hosting decisions. Stakeholders must monitor pending fiscal digitization decrees and cloud infrastructure subsidy programs to calibrate platform investments.
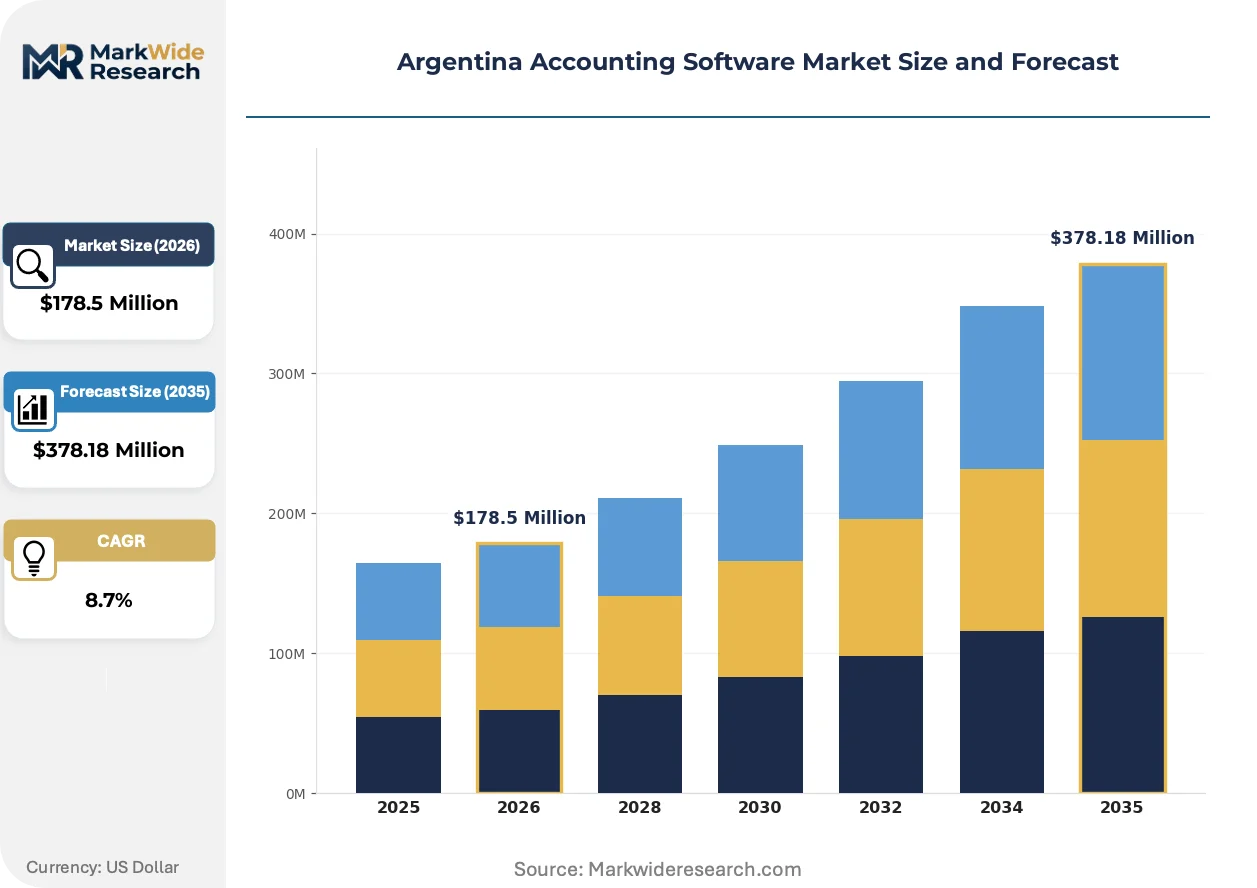
Market Dynamics
AFIP's electronic invoicing mandates are forcing continuous platform rearchitecture across Argentine software vendors, compressing development cycles while elevating compliance-as-a-service from feature to core value proposition.
Growth Catalysts
- AFIP RG 4290/17 Framework:Real-time tax reporting requirements compel SMEs to abandon spreadsheet-based workflows, creating forced-upgrade demand cycles that favor cloud-native vendors with embedded regulatory engines.
- SaaS Penetration in Córdoba:Asset-light subscription models reduce upfront capital barriers for regional accounting practices, accelerating platform consolidation among mid-market practitioners previously locked into perpetual-license legacy systems.
- Accountant Workflow Consolidation:Independent tax professionals serving multiple SME clients are unifying operations onto single platforms, generating network effects that pull adjacent client businesses onto compliant systems.
Market Restraints
- Data Localization Infrastructure Costs:BIS-aligned hosting requirements mandate domestic server deployment, inflating operational expenditures for foreign entrants and privileging established local providers with captive data center relationships.
- Peso Volatility:Currency instability compresses effective subscription revenue for vendors billing in local currency while eroding purchasing power for SME buyers evaluating dollar-denominated SaaS alternatives.
- Legacy On-Premises Lock-In:Large enterprises in Buenos Aires with strict data sovereignty protocols maintain substantial installed bases of perpetual-license systems, slowing cloud migration velocity and fragmenting addressable market development.
Strategic Opportunities
- Rosario Industrial Corridor:Underpenetrated manufacturing clusters in Santa Fe province present whitespace for verticalized accounting solutions targeting inventory-heavy operations with specialized cost-center modules.
- API-First Ecosystem Convergence:Integration between accounting platforms and neobanking infrastructure enables real-time cash flow forecasting, creating differentiated value propositions for treasury-intensive SME segments.
- Pending Fiscal Digitization Decrees:Anticipated AFIP expansion of electronic document mandates beyond invoicing into payroll and expense reporting will force secondary compliance upgrades across laggard market segments.
Industry Challenges
- Regulatory Velocity Talent Gap:Vendors struggle to recruit software engineers with simultaneous expertise in Argentine tax code interpretation and modern cloud architecture, delaying feature release timelines.
- Multi-Platform Client Integration:Accounting practices managing hybrid client bases across cloud and on-premises systems face operational friction in maintaining data consistency and audit trail integrity.
- AFIP Certification Timelines:Protracted approval processes for new platform releases create competitive windows where uncertified features cannot be marketed, compressing effective product launch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Accounting Software Market |
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $378.18 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premises, Cloud-Based, Hybrid, Mobile User Type: Small Businesses, Enterprises, Freelancers, Accountants Deployment Model: Public Cloud, Private Cloud, SaaS, Desktop Service Type: Subscription, One-Time License, Support, Consulting |
| Companies Covered | Microsoft Corporation, Xero Limited, SAP SE, Colppy, Zoho Corporation, Oracle Corporation, Intuit Inc., Nuvelar, The Sage Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Accounting Software Market Trends and Innovations
Real-time regulatory compliance is becoming the primary architectural constraint shaping product roadmaps, with vendors racing to embed continuous update mechanisms that transform static software into adaptive compliance infrastructure.
Cloud-native ledger architectures with embedded machine-learning reconciliation engines are hybridizing traditional double-entry bookkeeping with automated anomaly detection. Mid-market accounting practices in Buenos Aires are adopting these systems at accelerated cadences, compressing month-end close cycles from weeks to days while reducing manual intervention requirements.
AFIP's expanding electronic document mandate scope is reshaping platform data model requirements, forcing vendors to restructure core databases around real-time government submission protocols rather than internal reporting hierarchies. SME-facing vendors are responding by modularizing compliance layers, enabling faster adaptation to pending payroll and expense digitization decrees without core system overhauls.
Accountant-led platform selection is displacing direct SME procurement across the Buenos Aires-Córdoba corridor, with independent practitioners functioning as de facto distribution channels that consolidate multiple client licenses onto preferred systems. This channel concentration is most visible among tax professionals serving 15-50 client portfolios, where unified workflow management outweighs feature differentiation in vendor selection criteria.
Argentina Accounting Software Market Segmentation
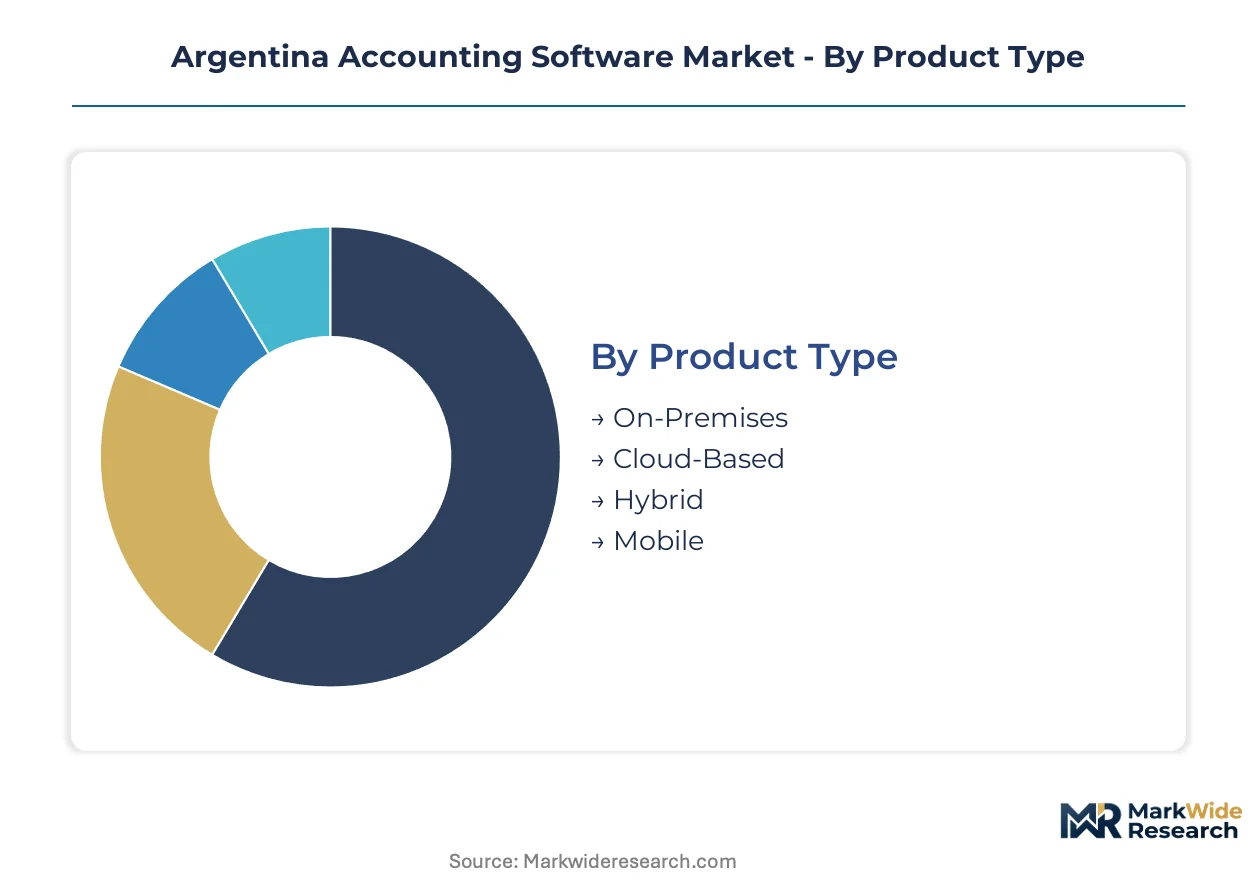
Segmentation in Argentina's accounting software market reveals how AFIP compliance mandates and peso volatility reshape purchasing patterns across deployment modes and customer archetypes. Vendors calibrate pricing architecture and feature depth to match divergent technical capabilities between Buenos Aires enterprises and Córdoba freelancers.
Product Type:
Use-case spectrum spans legacy data sovereignty requirements to mobile-first accessibility, with compliance automation as the unifying selection criterion.
- On-Premises:Perpetual-license systems deployed within client data centers serve large Buenos Aires enterprises with strict internal audit protocols. These installations retain margin pools among manufacturers and financial institutions subject to BIS-aligned data localization mandates, though AFIP update cycles impose heavier IT maintenance burdens than cloud alternatives.
- Cloud-Based:Multi-tenant SaaS architectures with embedded regulatory engines dominate SME procurement in the Buenos Aires-Córdoba corridor. Automatic AFIP compliance patches eliminate version fragmentation, while subscription financing accommodates peso-constrained cash flows for regional accounting practices consolidating multiple client workflows.
- Hybrid:Split deployments isolate sensitive ledger data on local servers while routing tax submissions through cloud gateways. Santa Fe industrial clusters adopt this architecture to satisfy both internal control requirements and real-time AFIP reporting obligations.
- Mobile:Smartphone-optimized interfaces with offline data entry and queued synchronization target field-based accountants serving dispersed SME clients across Mendoza agricultural zones.
The dominant share belongs to Cloud-Based solutions, while Mobile is closing the gap fastest as independent practitioners demand untethered workflow access.
User Type:
Customer archetypes range from solo freelancers to multi-entity enterprises, with procurement authority increasingly concentrating in accountant intermediaries rather than end users.
- Small Businesses:Owner-operated firms with 5-50 employees prioritize low-touch onboarding and automated bank reconciliation. These buyers concentrate in Córdoba's services economy, where SaaS penetration has compressed legacy spreadsheet migration timelines.
- Enterprises:Multi-division corporations require consolidated reporting across subsidiaries with divergent fiscal year-ends. Buenos Aires headquarters of multinational manufacturers drive demand for ERP-integrated modules with granular cost-center allocation.
- Freelancers:Solo practitioners need simplified tax estimation and electronic invoicing without complex general ledger overhead. This segment concentrates among Buenos Aires creative professionals and consultants billing international clients in foreign currency.
- Accountants:Independent tax professionals managing 15-50 client portfolios function as de facto distribution channels. Their platform selection criteria emphasize unified workflow management over feature differentiation, pulling adjacent SME clients onto preferred systems through network effects.
Accountants command the largest addressable volume through client consolidation, while Freelancers are expanding most quickly as gig economy participation rises.
Deployment Model:
Infrastructure choices reflect trade-offs between operational control and compliance velocity, with AFIP certification timelines favoring established hosting configurations.
- Public Cloud:Shared infrastructure with automatic scaling serves price-sensitive SMEs in Rosario's emerging industrial corridor. Domestic data center requirements elevate operational expenditures for foreign entrants lacking captive hosting relationships.
- Private Cloud:Single-tenant environments with dedicated resource allocation address data sovereignty concerns among Buenos Aires financial institutions. These deployments absorb higher per-seat costs to maintain audit trail isolation from co-tenancy risks.
- SaaS:Browser-delivered applications with continuous feature deployment dominate mid-market procurement. Automatic regulatory updates transform compliance from periodic project to embedded infrastructure, compressing development cycles for Córdoba-based vendors.
- Desktop:Locally installed software with manual update procedures retains installed base among legacy-dependent enterprises. AFIP mandate velocity threatens this segment as real-time reporting requirements outpace patch distribution capabilities.
SaaS holds the structural advantage, though Private Cloud is gaining share fastest among regulated industries.
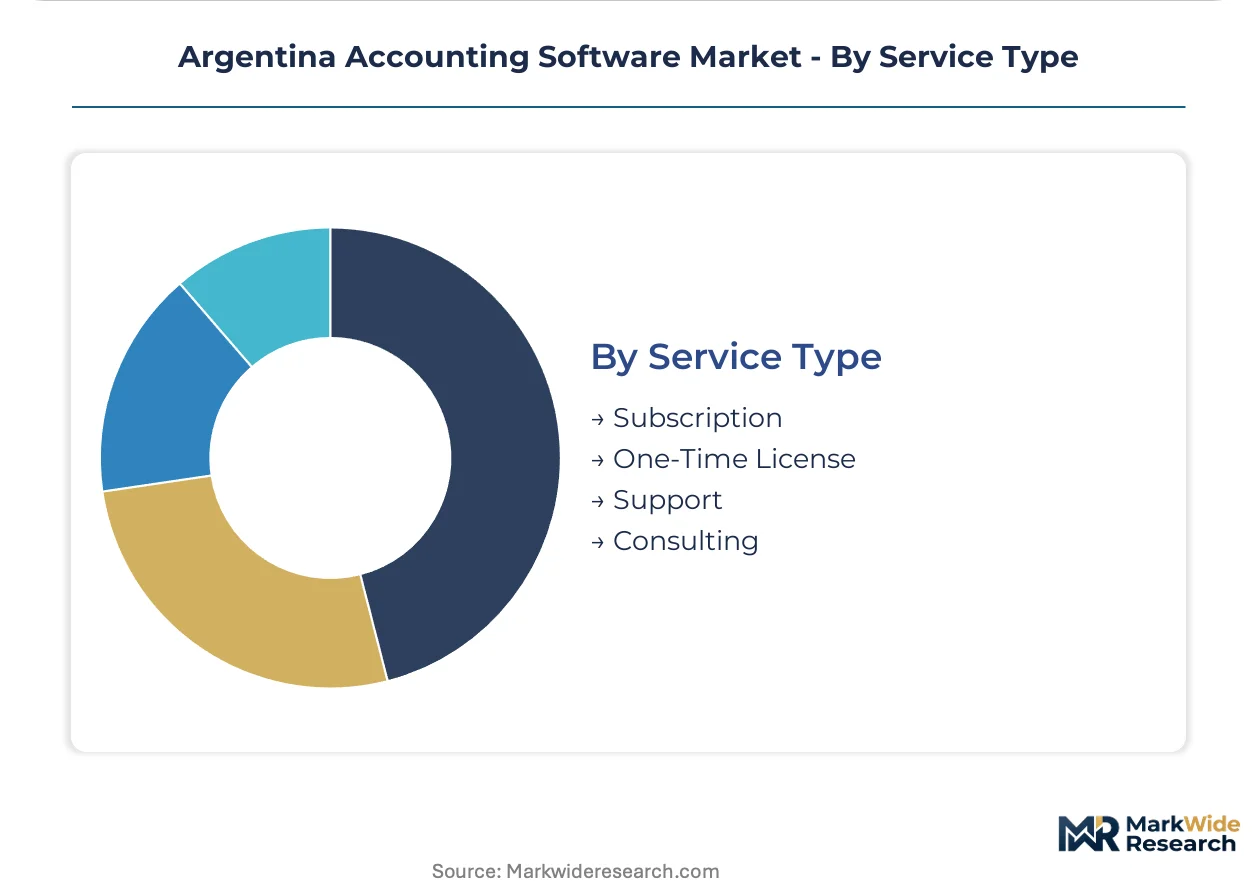
Service Type:
Revenue models align vendor incentives with client lifecycle stages, from initial compliance migration through ongoing regulatory adaptation.
- Subscription:Recurring revenue structures with tiered feature access reduce upfront capital barriers for peso-constrained buyers. These arrangements dominate Córdoba accounting practices transitioning from perpetual-license legacy systems.
- One-Time License:Perpetual purchase with annual maintenance options persists among Buenos Aires enterprises with capital budget cycles and internal IT capacity. Currency instability erodes effective renewal revenue for vendors billing in local pesos.
- Support:Technical assistance and troubleshooting services address AFIP integration failures and data migration complexities. Demand concentrates during regulatory transition periods when electronic mandate scope expands.
- Consulting:Implementation and workflow optimization engagements assist hybrid client bases managing cloud and on-premises system coexistence. Santa Fe manufacturers leverage these services to configure inventory-heavy cost-center modules.
Subscription generates the predominant revenue stream, while Consulting is climbing the fastest as regulatory complexity outstrips internal IT capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's accounting software trade dynamics reflect import dependency for enterprise-grade platforms alongside nascent export capability from Córdoba-based SaaS developers. Currency volatility distorts cross-border procurement decisions, while AFIP compliance requirements anchor domestic demand to locally certified solutions.
Buenos Aires Province
Metropolitan Buenos Aires concentrates multinational headquarters and financial institutions driving demand for ERP-integrated accounting modules. AFIP's real-time reporting mandates force continuous platform upgrades among enterprises in the capital's central business district. The city's accounting practices function as distribution channels, consolidating SME clients onto unified cloud platforms.
Córdoba
Córdoba's technology sector anchors Argentina's domestic SaaS development, with regional vendors serving mid-market accounting practices across the country's interior. The provincial government's innovation subsidies support cloud infrastructure investments that reduce latency for real-time AFIP submissions. Local software firms compete through localized tax-code compliance that dominates procurement decisions among regional SMEs.
Santa Fe
The Rosario industrial corridor generates demand for inventory-heavy accounting solutions targeting manufacturing cost-center allocation. Pending fiscal digitization decrees will extend electronic mandate scope into payroll processing for the province's agribusiness and heavy industry clusters. Hybrid deployment architectures satisfy both internal control requirements and real-time tax reporting obligations.
Mendoza
Mendoza's agricultural economy and wine export sector drive mobile-first accounting adoption among field-based accountants serving dispersed SME clients. Offline data entry with queued synchronization addresses connectivity gaps in rural production zones. The province's dollar-denominated export revenue cushions peso volatility impacts on software procurement budgets.
Argentina Accounting Software Market Competitive Landscape
On the supply side, the industry is bifurcated between global ERP incumbents and specialized local compliance vendors. Market structure reflects tiered competition where multinational platforms anchor large-enterprise accounts while regional specialists capture mid-market share through regulatory velocity. Three archetypes dominate: integrated suite providers, compliance-native local developers, and freelancer-focused SaaS platforms. Competitive moves center on API ecosystem expansion and accountant channel partnerships that generate client consolidation network effects.
Within the integrated suite tier, SAP SE and Oracle Corporation exemplify global vendors leveraging deep ERP integration to anchor multinational accounts in Buenos Aires. Among compliance-native specialists, Colppy occupies a position representing localized tax-code expertise that dominates mid-market procurement decisions. Xero Limited sits within the freelancer-focused vector, exemplifying rapid onboarding interfaces that sustain adoption among independent practitioners serving gig economy participants.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Xero Limited |
| SAP SE |
| Colppy |
| Zoho Corporation |
| Oracle Corporation |
| Intuit Inc. |
| Nuvelar |
| The Sage Group plc |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic data center infrastructure across the Buenos Aires-Córdoba corridor elevates hosting costs for foreign SaaS entrants while compressing margins for local vendors competing on AFIP compliance velocity. This utilization squeeze simultaneously hardens subscription pricing power among established providers with captive server relationships and forces asset-light competitors toward third-party infrastructure partnerships.
Pricing Analysis
Industrial OEM buyers anchor SaaS-tiered subscription structures that stratify across premium compliance bundles, standard workflow modules, and economy self-service tiers. Price differentiation hinges on AFIP certification depth and embedded regulatory update frequency, with premium tiers commanding spreads for real-time tax submission APIs. Cost compression in the economy tier is intensifying because regional accounting practices consolidate purchasing power through multi-client license aggregation. Freelancers and solo practitioners exhibit highest price sensitivity, while Buenos Aires financial institutions absorbing private cloud deployments show lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration for server hardware rests with Taiwanese and Chinese ODMs, while Argentine software development draws from domestic engineering talent pools in Córdoba and Rosario. Raw material dependencies span semiconductor components, lithium-ion backup power systems, and fiber-optic infrastructure. Single-source vulnerability concentrates in international cloud hyperscaler dependencies for secondary hosting failover. Distribution runs through accountant-led channel partnerships that consolidate SME procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is accelerating as API-first ecosystems converge accounting ledgers with neobanking infrastructure, creating interoperability moats that reshape competitive durability.
For Market Incumbents: Insulate core revenue streams by deepening vertical integration into regulatory compliance engines that automate AFIP mandate interpretation, neutralizing the talent gap threat that delays feature releases for cloud-native challengers. Fortify accountant channel control through exclusive workflow consolidation tools that embed multi-client portfolio management, raising switching costs for regional practices serving 15-50 SME accounts. For New Entrants and Emerging Players: Establish a beachhead in Rosario's underpenetrated industrial corridor, where manufacturing cost-center accounting modules remain underserved by horizontal platforms optimized for service-sector workflows. Prioritize mobile-first architectures with offline synchronization for Mendoza's field-based practitioners, leveraging queued data entry to circumvent rural connectivity gaps that fragment incumbent cloud delivery. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compliance-native local developers with embedded AFIP certification relationships and captive data center infrastructure, positioning these archetypes for durable cash flow quality across extended holding periods. Monitor pending fiscal digitization decree announcements as the critical inflection signal, with payroll and expense mandate expansions likely to trigger forced-upgrade demand cycles favoring regulatory-velocity leaders.| Strategic Initiative | Industry Significance |
|---|---|
| AFIP Compliance Engine Acquisition | Embedded regulatory velocity separates mid-market winners from laggards facing certification delays. |
| Accountant Channel Partnership Program | Unified workflow tools for multi-client practices generate network-effect client consolidation. |
| Neobanking API Integration | Real-time cash flow forecasting creates differentiated value for treasury-intensive SME segments. |
| Hybrid Deployment Architecture Launch | Split cloud-local configurations satisfy Santa Fe manufacturers' control and compliance requirements. |
| Mobile-First Field Platform Rollout | Offline-queued synchronization penetrates Mendoza's agricultural zones where connectivity fragments cloud delivery. |
Research Methodology
The analysis maps cloud-native SaaS architectures, on-premises legacy systems, hybrid deployments, and mobile-first platforms, each validated through CTOs at accounting practices, IT procurement officers at Buenos Aires financial institutions, platform engineers at Córdoba-based vendors, and AFIP certification specialists. Secondary triangulation draws from SEC filings of listed software providers, AFIP regulatory decree archives, hyperscaler capex disclosures for regional data center investments, and Argentine customs records for hardware imports. Bottom-up demand aggregation across user segments was cross-checked against top-down market sizing from subscription revenue disclosures.
Assumptions held fixed across the modeling period include AFIP mandate velocity, peso-dollar exchange rate volatility bands, and domestic data center capacity expansion trajectories, while variables tested encompass SaaS penetration rates, accountant channel concentration, and neobanking partnership density. Segmentation dimensions span deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from regression analysis of historical subscription growth trajectories against regulatory mandate implementation timelines, with inputs including electronic invoicing compliance deadlines and cloud infrastructure subsidy program enrollments.
Stress conditions across currency devaluation scenarios, data localization enforcement intensity, and legacy system migration friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of AFIP decree publication cadence, SaaS vendor certification timelines, and accountant practice consolidation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
France Forensic Accounting Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Canada Forensic Accounting Market
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
India Accounting Professional Services Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Tax Automation Software Market
Accounting and Taxation Services
UAE Forensic Accounting Market