
 North America Driving Vacation Market | 2026-2036
North America Driving Vacation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Driving Vacation Market Insights
Premium RV and adventure-grade SUV specifications is bifurcating the North America driving vacation market into experience-tiered segments. Enterprise Holdings leverages its neighborhood rental network to anchor last-mile trip origination in urban centers. Booking Holdings sustains inventory depth across independent campgrounds and boutique roadside lodging. Tripadvisor competes through user-generated route content that reduces planning friction for self-guided itineraries.
A North America driving vacation constitutes a self-directed leisure journey where travelers use rented or owned road vehicles to reach distributed attractions, typically spanning multiple overnight stops with average daily distances of 200-400 miles. The vehicle category shapes trip economics directly, as RVs command higher per-day spend but eliminate lodging costs while SUVs dominate booking volumes through rental fleet availability. Family-oriented national park circuits occupy the largest share of trip value, while solo traveler beach-to-urban routes represent the fastest-expanding margin pool. Duration-based segmentation reveals weekend trips as the volume base, though two-week itineraries generate disproportionate ancillary spending on equipment and experience add-ons.
The U.S. National Park Service manages access capacity through timed entry permits at Arches and Zion, directly constraining peak-season route demand. EPA emissions standards for rental fleet composition influence operator procurement timelines, while Transport Canada's commercial vehicle regulations affect cross-border RV licensing requirements. Stakeholders must monitor state-level EV infrastructure buildouts and campground electrification timelines to anticipate fleet turnover patterns and charging-access route design.
Market Dynamics
The U.S. Department of Transportation's infrastructure modernization programs and EV charging corridor deployments are reshaping route accessibility across the North America driving vacation market, creating new origination patterns and fleet turnover timelines.
Growth Catalysts
- EV Charging Infrastructure:Federal NEVI program funding accelerates corridor completion along Interstate highways, reducing range anxiety for electric SUV renters and expanding viable trip radii from urban gateways.
- National Park Access Permits:Timed entry systems at Arches and Zion redistribute visitor flows across shoulder seasons, extending the revenue window for adjacent rural lodging and equipment rental operators.
- Millennial Solo Travel:Remote work flexibility enables extended-duration trips among this demographic, driving demand for flexible booking platforms and experience-layered itineraries.
Market Restraints
- Fleet Procurement Costs:EPA emissions standards for rental fleet composition compress operator margins as internal combustion vehicle phase-out timelines accelerate capital replacement cycles.
- Cross-Border Licensing Friction:Transport Canada's commercial vehicle regulations create documentation complexity for U.S.-based RV operators serving Canadian route segments.
- Peak Season Capacity Hard Caps:Fixed infrastructure at high-demand national park gateways limits revenue scalability regardless of demand signals.
Strategic Opportunities
- Campground Electrification:State-level infrastructure buildouts create first-mover advantage for operators integrating EV-ready hookups at overnight stops.
- Adventure-Grade SUV Specifications:Convergence of overlanding equipment and factory off-road packages opens premium pricing tiers for rental fleet differentiation.
- Secondary Scenic Byway Activation:Underutilized routes in the U.S. Mountain West offer inventory expansion with lower land acquisition costs than primary corridor positioning.
Industry Challenges
- Charging Infrastructure Pacing:Fleet electrification timelines run ahead of rural corridor charging density, stranding asset deployment in high-trip-value regions.
- Permit System Integration:National Park Service timed entry APIs lack standardization, forcing manual booking reconciliation across fragmented reservation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Driving Vacation Market |
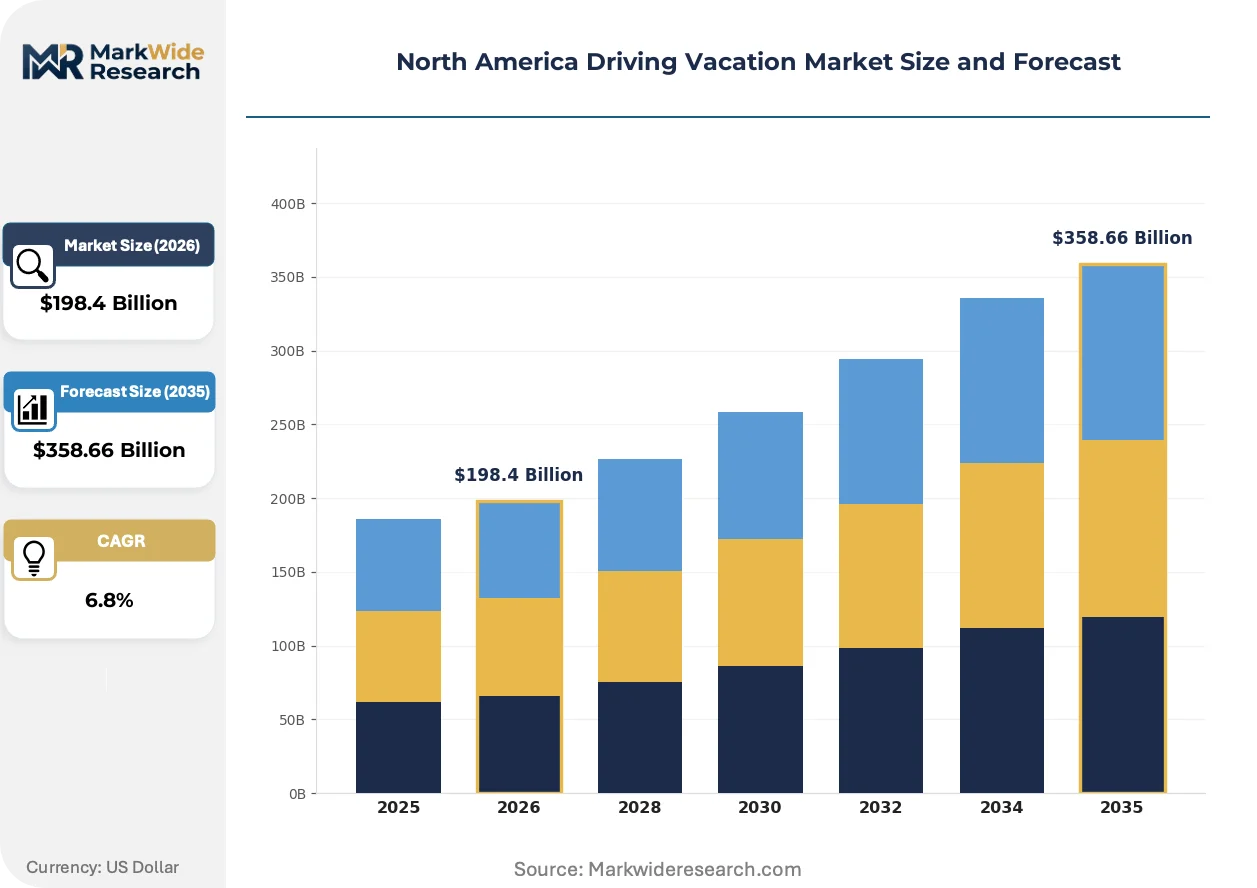
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $358.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Families, Couples, Solo Travelers, Groups Vehicle Type: Cars, SUVs, RVs, Vans Duration: Weekend, Week, Two Weeks, Month Attraction Type: National Parks, Beaches, Historical Sites, Urban Areas |
| Companies Covered | Expedia Group, Booking Holdings, Tripadvisor, Enterprise Holdings, Hertz Global Holdings, Alamo, Avis Rent A Car, Road Scholar, Adventures Overland, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Driving Vacation Market Trends and Innovations
Technology convergence and regulatory pressure are decomposing traditional trip planning and vehicle access models across the North America driving vacation ecosystem, creating new competitive dimensions around real-time adaptability.
Over-the-air vehicle update capabilities are decomposing the fixed-feature rental model. Adventure-grade SUV fleets now receive terrain-specific calibration downloads mid-rental, enabling operators to monetize capability unlocks during trip execution. Fleet managers at major airport hubs are adopting this architecture to reduce physical vehicle turnover while capturing ancillary revenue streams.
EPA emissions standards for rental fleet composition are compressing procurement timelines. Operators must accelerate capital deployment toward electrified or hybrid platforms ahead of prior depreciation schedules. The U.S. Mountain West route operators face the steepest reconfiguration burden given charging infrastructure gaps in high-elevation corridors.
Solo travelers are unbundling traditional package offerings in favor of modular itinerary assembly. Digital platforms enabling real-time campground availability and experience booking are displacing static pre-trip planning. This pattern concentrates among Millennial and Gen Z demographics originating from Denver and Salt Lake City urban centers.
North America Driving Vacation Market Segmentation
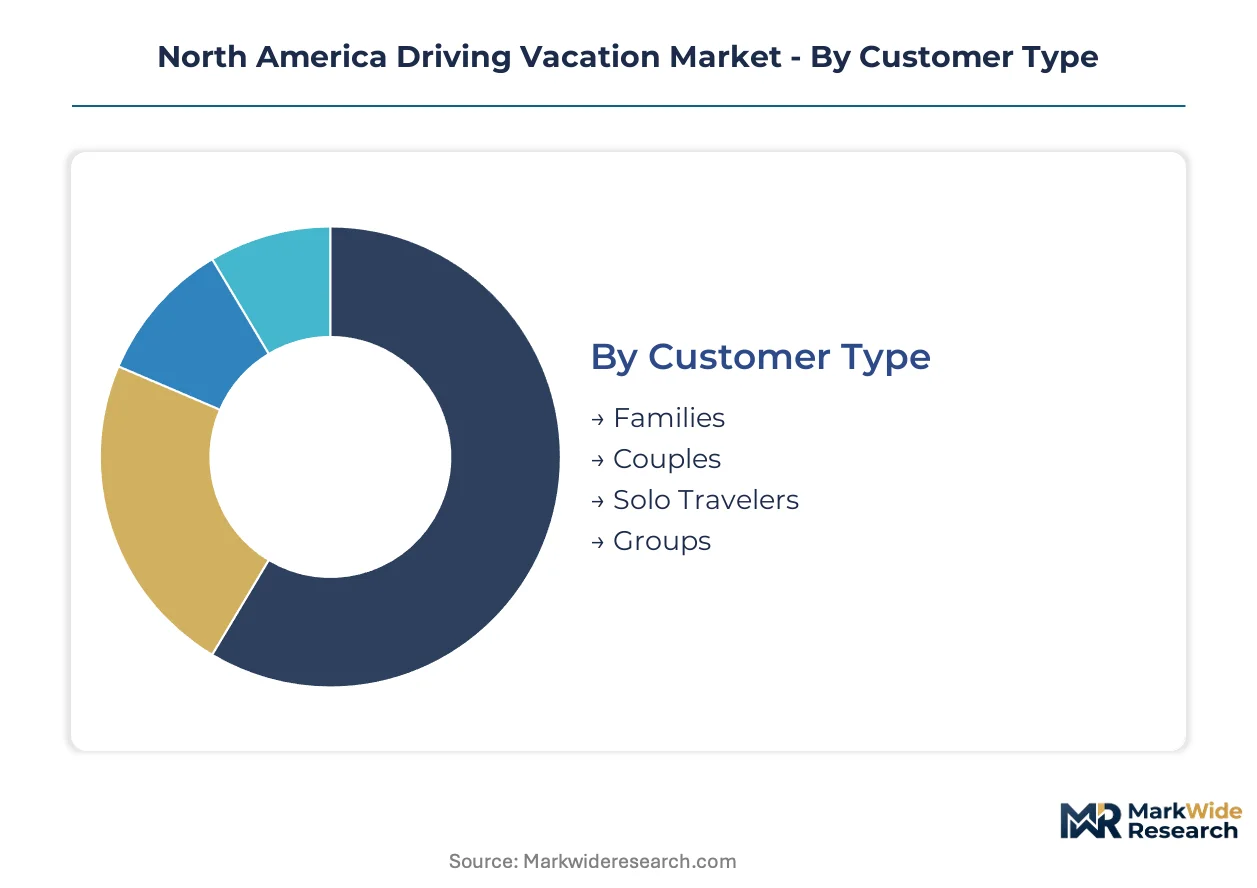
Vehicle category and trip duration shape revenue architecture differently in the North America driving vacation market. Customer composition determines ancillary spend intensity, while attraction proximity governs route density and lodging economics.
Customer Type:
Families command the highest per-trip expenditure through equipment rentals and multi-occupancy lodging, while solo travelers concentrate margin in experience-layered bookings.
- Families:Multi-generational units averaging 3.4 occupants generate peak equipment rental attach rates for bikes, kayaks, and camping gear. National park circuits in the U.S. Mountain West absorb the largest share of this segment's trip value, constrained by NPS timed entry permit availability at Arches and Zion.
- Solo Travelers:Remote-enabled professionals extending trips beyond traditional PTO windows. Denver and Salt Lake City urban gateways concentrate Millennial and Gen Z origination, with beach-to-urban routes climbing the fastest as flexible booking platforms displace static packages.
- Couples:Dual-income pairs prioritizing boutique roadside lodging over campground infrastructure.
- Groups:Coordinated friend networks splitting vehicle and accommodation costs across 4-6 travelers.
Families hold installed capacity in legacy booking systems. Solo travelers are rotating up the share rankings.
Vehicle Type:
Fleet composition determines capital intensity and pricing power, with electrification timelines forcing procurement recalibration.
- RVs:Self-contained units eliminating lodging costs while commanding $180-320 daily rental rates. EPA emissions standards compress operator margins as diesel platform phase-outs accelerate capital replacement ahead of prior depreciation schedules.
- SUVs:Rental fleet availability dominates booking volumes through airport hub distribution. Adventure-grade specifications with factory off-road packages open premium pricing tiers, though U.S. Mountain West operators face charging infrastructure gaps in high-elevation corridors.
- Cars:Economy-focused segments concentrated in coastal urban-to-beach routes.
- Vans:Converted platforms bridging car efficiency with RV sleeping capacity.
RVs hold installed capacity in national park adjacency. SUVs are rotating up the share rankings.
Duration:
Trip length stratifies ancillary revenue capture and platform engagement depth.
- Weekend:Friday-Sunday itineraries form the volume base, concentrated within 400-mile radii of major metropolitan areas. Equipment rental attach rates remain below extended-trip segments, though frequency drives loyalty program accumulation.
- Two Weeks:Fourteen-day itineraries generate disproportionate spending on overlanding equipment, guided experience add-ons, and flexible cancellation terms. Remote work flexibility enables this duration expansion among professional-class travelers.
- Week:Seven-day formats balancing PTO constraints with multi-stop route complexity.
- Month:Extended sabbatical structures concentrated among retiree and remote worker demographics.
Weekend trips hold installed capacity in fleet utilization algorithms. Two-week itineraries are rotating up the share rankings.
Attraction Type:
Geographic distribution of demand centers shapes route infrastructure investment and lodging supply.
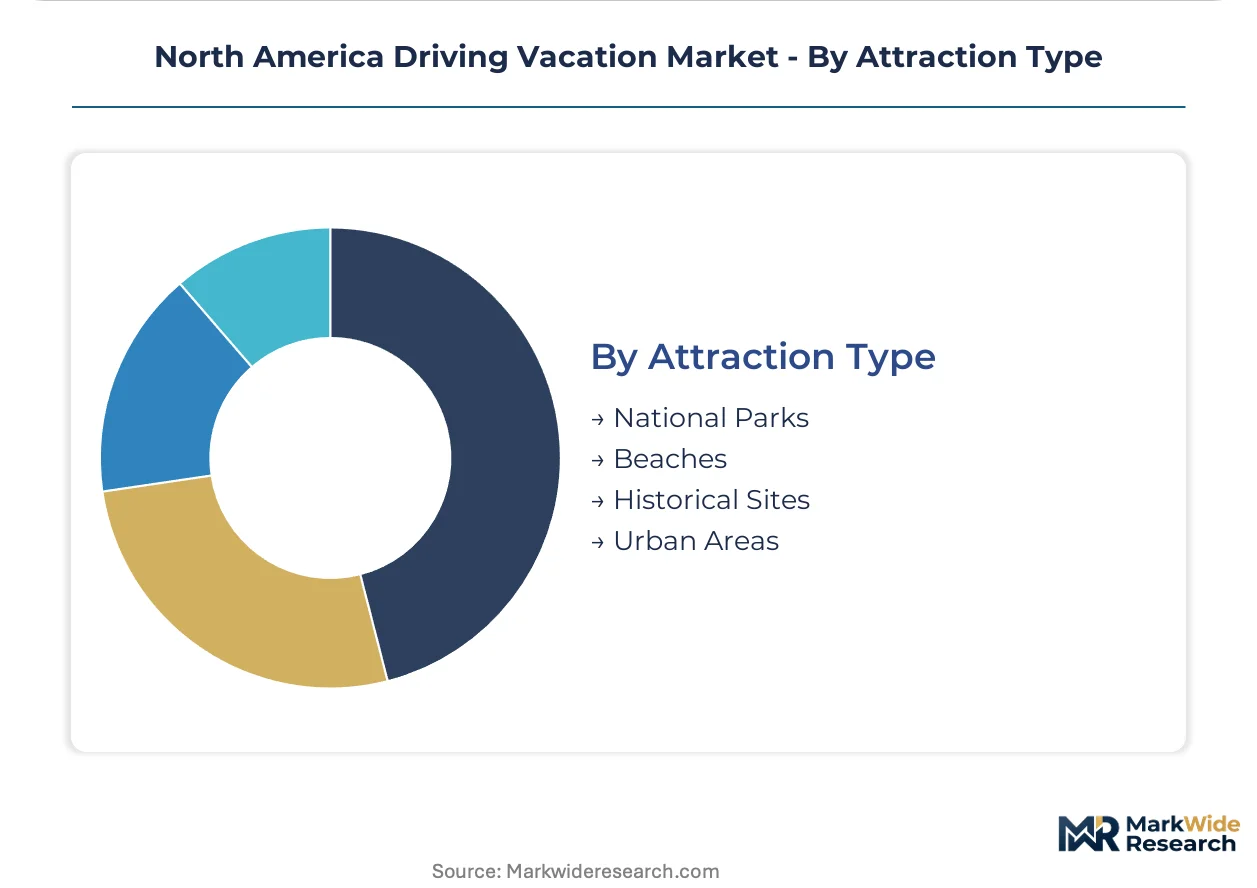
- National Parks:NPS-managed destinations in the U.S. Mountain West concentrate the largest share of trip value. Timed entry permits at Arches and Zion redistribute visitor flows across shoulder seasons, extending revenue windows for adjacent rural operators.
- Urban Areas:City center destinations anchor last-mile trip origination through neighborhood rental networks. Denver, Salt Lake City, and Phoenix gateway functions concentrate vehicle pickup and equipment staging.
- Beaches:Coastal corridors in California, Florida, and the Carolinas concentrate couple and group segment demand.
- Historical Sites:Route 66 and Civil War trail corridors attract retiree demographics with lower ancillary spend intensity.
National parks hold installed capacity in reservation system architecture. Urban areas are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of driving vacation expenditure, with cross-border flows into Canada and Mexico generating secondary revenue corridors. Import intensity concentrates in Canadian RV manufacturing components and Mexican hospitality services, while export-equivalent value flows through U.S.-based platform licensing and fleet management technology.
United States
Denver and Salt Lake City anchor Millennial and Gen Z origination clusters, with remote work flexibility extending average trip duration. The U.S. Department of Transportation's NEVI program accelerates EV charging corridor completion along Interstate highways, reducing range anxiety for electric SUV renters. The U.S. Mountain West concentrates national park adjacency demand, where timed entry permits at Arches and Zion redistribute visitor flows across shoulder seasons.
Canada
Cross-border RV traffic from U.S. origin points drives peak-season demand in British Columbia and Alberta gateway corridors. Transport Canada's commercial vehicle regulations create documentation complexity for U.S.-based operators serving Canadian route segments. The Rocky Mountain corridor between Calgary and Vancouver absorbs the largest share of international driving vacation value in the country.
Mexico
Baja California and the Yucatán Peninsula attract overland adventure segments seeking lower-cost extended itineraries. Mexican federal tourism infrastructure programs prioritize coastal highway modernization between Tijuana and Cabo San Lucas. The emerging Baja Overland Circuit concentrates new campground development and equipment rental staging points.
North America Driving Vacation Market Competitive Landscape
Concentration sits with platform aggregators and fleet operators that control inventory access and route origination infrastructure. The market structure bifurcates between asset-heavy vehicle operators and asset-light booking intermediaries, with limited vertical integration between the two tiers. Strategic archetypes include neighborhood rental network anchors, user-generated content platforms, and integrated hospitality aggregators. Dominant competitive moves encompass fleet electrification procurement and campground electrification partnerships.
Within the platform-aggregator tier, Booking Holdings and Expedia Group exemplify inventory depth strategies across independent campgrounds and boutique roadside lodging. Enterprise Holdings and Hertz Global Holdings occupy positions in fleet-based origination control, with neighborhood rental networks anchoring last-mile trip starts in urban centers. Tripadvisor represents user-generated route content archetypes that reduce planning friction for self-guided itineraries.
| Leading Market Players |
|---|
| Expedia Group |
| Booking Holdings |
| Tripadvisor |
| Enterprise Holdings |
| Hertz Global Holdings |
| Alamo |
| Avis Rent A Car |
| Road Scholar |
| Adventures Overland |
| Others |
Pricing and Supply Chain Analysis
RV fleet procurement lead times stretching 18-24 months compress operator margins while amplifying pricing power for manufacturers with confirmed delivery slots. This inventory pressure concentrates among U.S. Mountain West operators facing EPA emissions-driven fleet turnover timelines, forcing premium positioning on available units.
Pricing Analysis
Family vacation planners anchor pricing stratification across premium adventure-grade SUVs, standard crossover fleets, and economy compact segments. Price differentiation rests on factory off-road certification tiers and bundled equipment packages rather than base vehicle class alone. Cost compression in the standard tier intensifies as rental operators accelerate hybrid procurement ahead of depreciation schedules. Solo travelers exhibit lowest price sensitivity, prioritizing flexible cancellation terms over daily rate minimization.
Supply Chain Analysis
RV chassis inventory cycles of 90-120 days at major manufacturing hubs in Indiana and Ohio constrain fleet expansion velocity for regional operators. Component sourcing draws from Canadian aluminum suppliers, Mexican interior fabricators, and domestic drivetrain assemblers. Single-source vulnerability concentrates in specialized adventure-grade suspension systems from Tier 1 automotive suppliers. Distribution runs through airport hub staging facilities and neighborhood rental networks for last-mile vehicle positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in secondary scenic byway corridors, as Millennial and Gen Z solo travelers disintermediate traditional package operators through modular booking platforms.
For Market Incumbents: Shield core revenue by securing campground electrification partnerships ahead of state infrastructure buildout deadlines. Fleet operators should accelerate backward integration into EV-ready vehicle procurement channels to offset margin compression from accelerated EPA compliance timelines. Priority lever sits with timed entry permit API standardization to reduce manual booking reconciliation costs. For New Entrants and Emerging Players: Differentiate on real-time adaptability by targeting underactivated secondary routes in the U.S. Mountain West with lower land acquisition thresholds than primary corridor positioning. The most penetrable segment comprises remote-enabled professionals originating from Denver and Salt Lake City urban gateways seeking flexible-duration itineraries. Go-to-market angle emphasizes over-the-air vehicle capability unlocks monetized mid-trip. For Investors and Strategic Acquirers: Carve-out targets emerge from hospitality conglomerates divesting non-core campground portfolios to focus on urban lodging assets. Long-term viability favors operators controlling both fleet origination infrastructure and experience-layered booking platforms. Signal to watch is NEVI program corridor completion pace relative to operator electrification capex deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Campground Electrification Partnership | First-mover positioning on state-funded EV hookup infrastructure locks in premium overnight pricing power. |
| Adventure-Grade Fleet Specification | Factory off-road packages from OEMs enable tiered pricing separation from standard SUV rental commoditization. |
| Timed Entry Permit Integration | API standardization with NPS reservation systems reduces operational friction at Arches and Zion gateways. |
| Neighborhood Rental Network Expansion | Urban hub density in Denver and Salt Lake City captures Millennial and Gen Z origination clusters. |
| Over-the-Air Capability Monetization | Mid-rental terrain calibration downloads create ancillary revenue streams without physical fleet turnover. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with fleet procurement directors, campground operators, and digital platform product managers; and secondary validation through U.S. Department of Transportation NEVI disbursement records, National Park Service visitor statistics, and EPA emissions compliance filings. Bottom-up triangulation across vehicle category economics and top-down reconciliation against aggregate tourism expenditure patterns anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled vehicle type, customer segment, trip duration, and attraction proximity dimensions. CAGRs derived from segment-level demand elasticity coefficients applied to infrastructure deployment timelines and fleet turnover patterns. Forecast inputs incorporated NEVI corridor completion schedules and remote work penetration rates among professional-class demographics.
The analysis sits within stated boundaries; outcomes outside sustained federal infrastructure funding levels or accelerated EPA phase-out timelines would require recalibration. Forecasts reflect documented assumptions around EV charging density buildout and permit system standardization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
USA Sustainable Tourism Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
Airline Retailing Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Solo Ecotourism Market
Travel and Tourism
Wellness Tourism Market
Travel and Tourism
Vietnam Online Travel Market