
 Fintech-As-A-Service Platform Market | 2026-2036
Fintech-As-A-Service Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Fintech-As-A-Service Platform Market Foresight
API-first architecture is reconfiguring how financial products are assembled and distributed, replacing monolithic core banking systems with composable service layers. Stripe leverages extensive developer tooling to dominate checkout infrastructure across digital commerce. Adyen sustains unified platform positioning across payment acceptance, issuing, and treasury services. Marqeta specializes in card-issuing APIs that anchor modern credit and debit program deployment for neobanks and enterprises.
Fintech-as-a-Service refers to the delivery of modular financial capabilities—payment processing, lending origination, compliance verification, and risk scoring—through cloud-hosted APIs and SDKs that embed directly into third-party applications. These platforms typically operate on RESTful or GraphQL interfaces with sub-second latency requirements, enabling non-financial firms to launch regulated products without building proprietary banking infrastructure. Payment Processing leads service-type revenue due to high transaction velocity, while Compliance Management captures expanding margin pools as AML and KYC obligations intensify across jurisdictions. Cloud-Based deployment outpaces On-Premise alternatives as retail banks and credit unions prioritize elastic capacity over capital-intensive data center commitments.
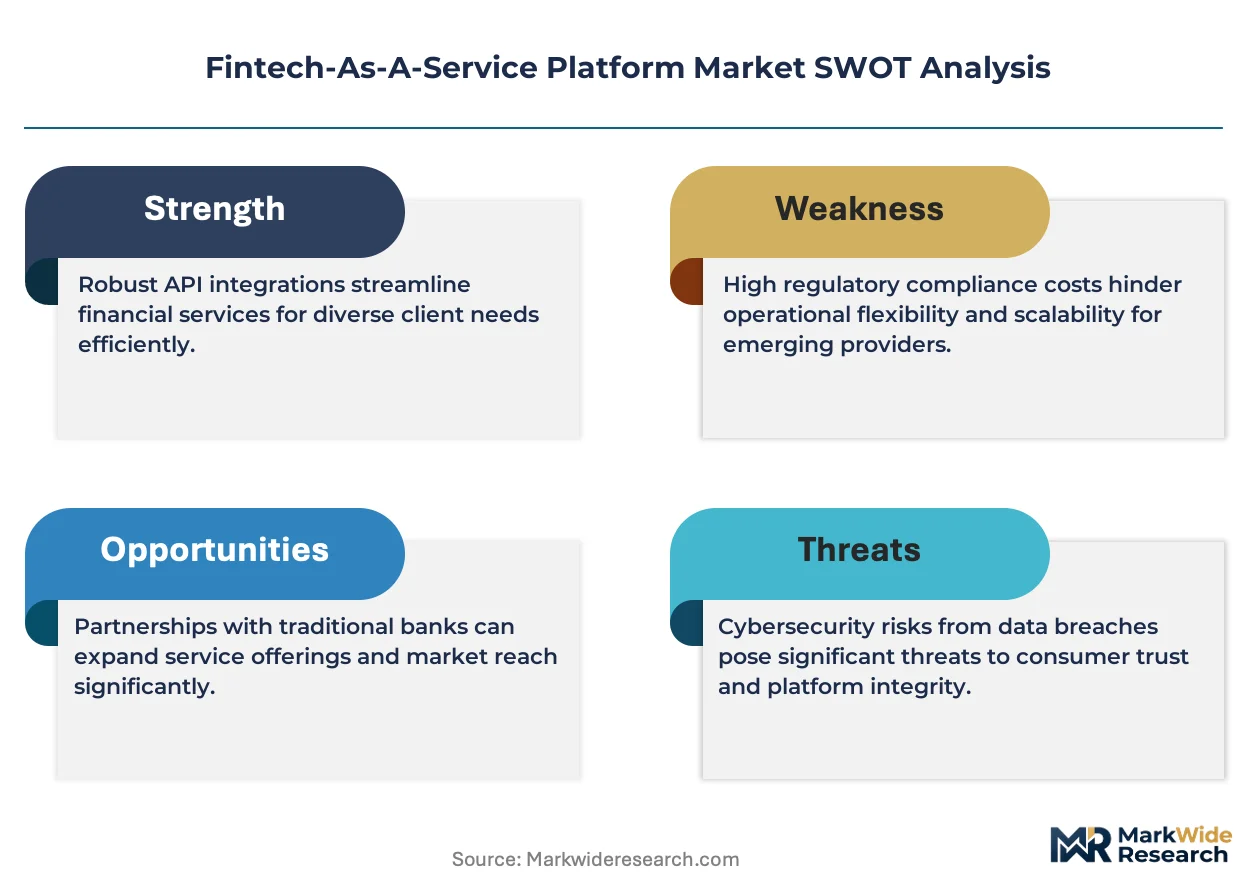
The US Office of the Comptroller of the Currency and the Consumer Financial Protection Bureau shape charter pathways and consumer protection standards that determine which fintech models achieve sustainable bank partnership status. In Europe, EBA guidelines on outsourcing and the Digital Operational Resilience Act impose strict continuity requirements on cloud-dependent service providers. Stakeholders must monitor how diverging national interpretations of bank-fintech affiliation rules affect cross-border API interoperability and licensing reciprocity.
Market Dynamics
API-first composability is dismantling monolithic banking infrastructure, forcing legacy core system vendors to rearchitect around microservices or cede ground to cloud-native challengers. This structural shift reconfigures value capture from software licenses toward per-transaction revenue pools.
Growth Catalysts
- PSD2 Open Banking Mandates:European data-sharing requirements compel retail banks to expose account interfaces through standardized APIs, accelerating third-party fintech integration timelines.
- Embedded Finance Adoption:Non-financial enterprises in e-commerce and mobility sectors now embed lending, insurance, and payment products directly into customer journeys.
- Cloud Infrastructure Elasticity:Retail banks and credit unions migrate from capital-intensive data centers to consumption-based cloud models, reducing time-to-market for new financial products.
Market Restraints
- Regulatory Fragmentation:Divergent national interpretations of bank-fintech partnership rules across the United States, United Kingdom, and Singapore create compliance multiplicity for cross-border platform operators.
- Core System Switching Costs:Legacy mainframe architectures at tier-one banks impose integration friction that slows API-layer adoption despite executive mandates.
- Specialized Talent Scarcity:Shortages of engineers proficient in both financial services compliance and cloud-native distributed systems constrain platform development velocity.
Strategic Opportunities
- Small Business Banking APIs:Underpenetrated merchant segments in India and Brazil present white space for working capital and treasury management services delivered through embedded interfaces.
- Regulatory Technology Convergence:Platforms that unify KYC, AML, and transaction monitoring through single API endpoints capture expanding compliance spend as jurisdictional obligations intensify.
- Real-Time Payment Rails:FedNow and equivalent instant settlement infrastructures in the United States and Europe enable new use cases in payroll, gig economy disbursements, and B2B liquidity management.
Industry Challenges
- Interoperability Complexity:Fragmented API standards across banking cores, card networks, and alternative payment methods force platform engineering teams to maintain multiple integration patterns.
- Operational Resilience Certification:European Digital Operational Resilience Act requirements impose strict continuity testing and incident reporting burdens on cloud-dependent service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fintech-As-A-Service Platform Market |
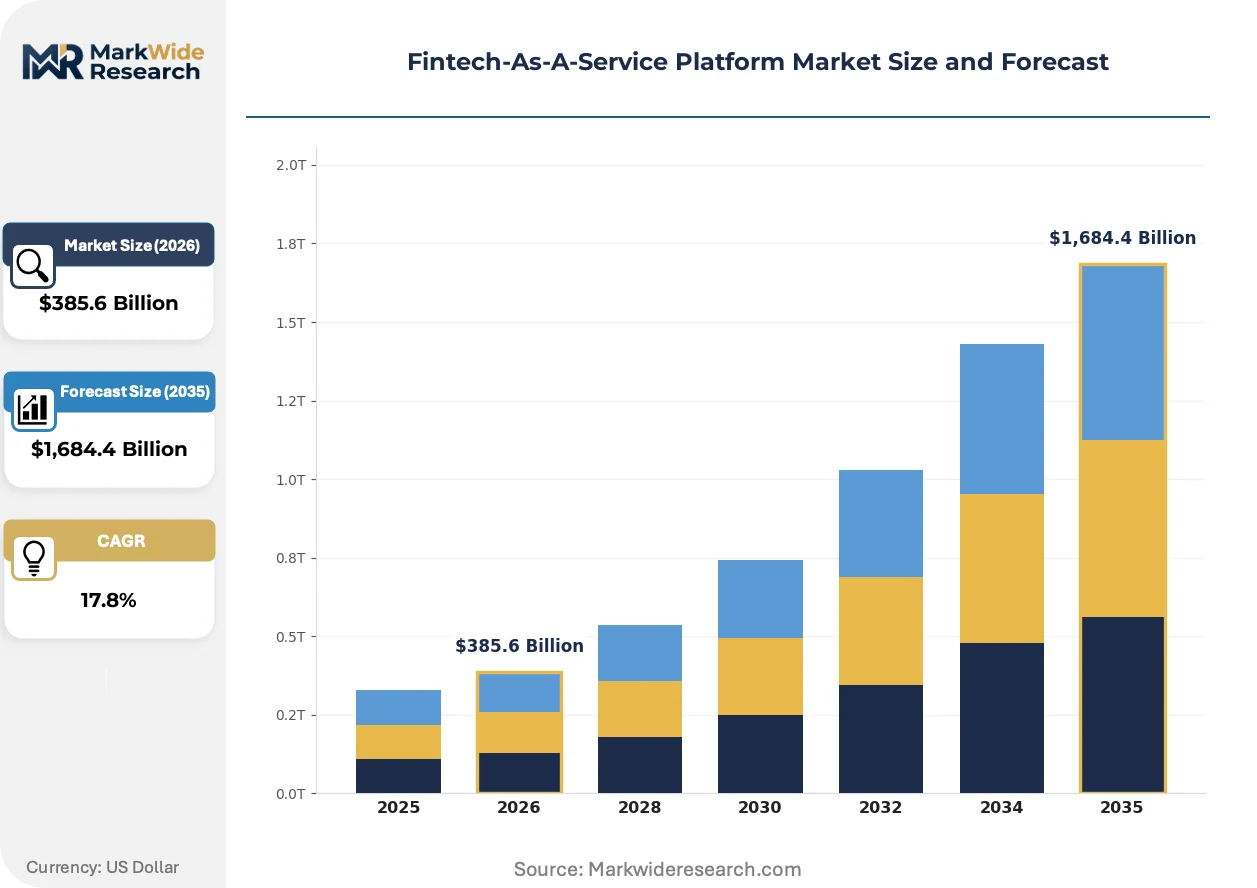
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $1,684.4 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Lending Solutions, Compliance Management, Wealth Management Deployment: Cloud-Based, On-Premise, Hybrid, Multi-Tenant End User: Retail Banks, Credit Unions, Insurance Firms, Investment Firms Solution: API Integration, Digital Banking, Risk Assessment, Fraud Detection |
| Companies Covered | Stripe, Adyen, PayPal Holdings, Inc., Block, Inc., Mastercard, Inc., Fiserv, Marqeta, Rapyd Financial Network Ltd., Plaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fintech-As-A-Service Platform Market Shifts & Advancements
Distributed ledger infrastructure and AI-native risk engines are converging with regulatory data frameworks to redefine how financial services authenticate, settle, and price transactions. These forces compress development cycles while elevating compliance automation requirements.
Tokenized deposit infrastructure is virtualizing correspondent banking relationships by enabling programmable settlement across distributed networks. Neobanks and treasury platforms are piloting these rails for cross-border B2B payments. The technology is virtualizing traditional nostro-vostro account structures into atomic settlement protocols that eliminate settlement risk and compress liquidity requirements.
The European Digital Operational Resilience Act mandates strict third-party risk management and incident reporting for critical ICT service providers supporting financial institutions. Platform vendors must now maintain comprehensive service continuity documentation and penetration testing regimes. Cloud-hosted fintech infrastructure in Frankfurt, Dublin, and Amsterdam faces the most immediate compliance adaptation timelines.
Enterprise procurement of financial infrastructure is consolidating around outcome-based pricing models that tie vendor compensation to transaction volume or customer acquisition metrics. Platform sales cycles now emphasize proof-of-concept deployments with revenue-share structures replacing upfront licensing. This shift is most pronounced among mid-market retailers and marketplace operators in the United States seeking to minimize capital commitment during product launch phases.
Fintech-As-A-Service Platform Market Segmentation
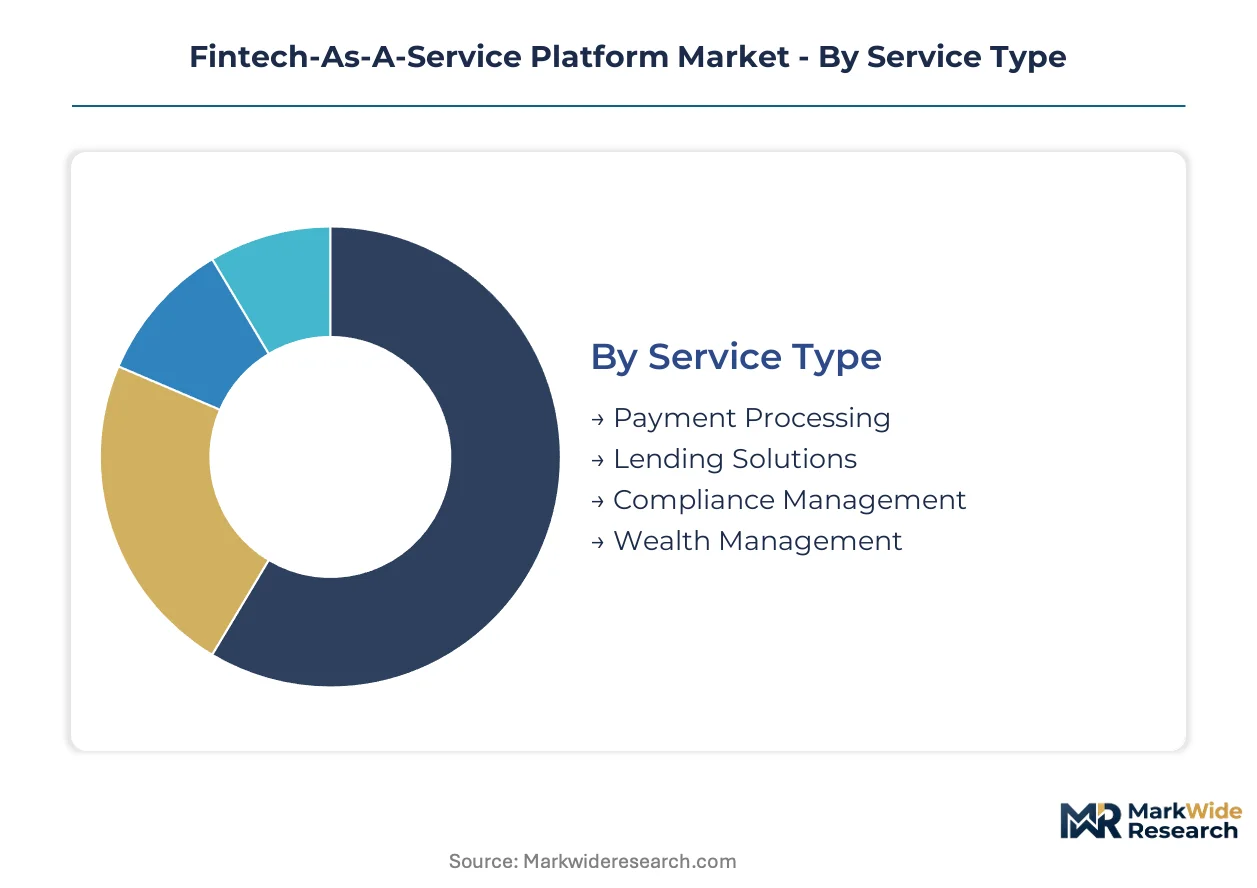
Modular service delivery demands precise segment alignment between infrastructure capabilities and institutional risk profiles. Platform vendors configure pricing and support intensity around deployment topology and regulatory exposure rather than uniform subscription tiers.
Service Type:
After-sales engineering intensity varies sharply across service categories, with compliance modules requiring continuous regulatory recalibration and payment rails demanding sub-second latency guarantees.
- Payment Processing:High-velocity transaction orchestration across card networks, ACH rails, and real-time settlement systems. Demand concentrates among United States neobanks and marketplace operators seeking unified acceptance infrastructure. Transaction volume economics and interchange optimization drive procurement decisions.
- Compliance Management:Automated KYC, AML screening, and sanctions monitoring delivered through policy-as-code engines. European retail banks under EBA outsourcing guidelines represent the primary demand cluster. Regulatory fragmentation across member states intensifies vendor certification requirements.
- Lending Solutions:Embedded credit origination and servicing APIs.
- Wealth Management:Portfolio construction and custody infrastructure for digital advisory platforms.
By volume, Payment Processing leads. By growth pace, Compliance Management is expanding most quickly.
Deployment:
Cost tier stratification separates capital-intensive on-premise commitments from consumption-based cloud alternatives, with hybrid architectures capturing institutions in mid-migration.
- Cloud-Based:Elastic compute and storage provisioned across AWS, Azure, or GCP regions with SOC 2 and PCI DSS attestation. United States credit unions prioritize this model to avoid data center CapEx. FedRAMP authorization status increasingly filters vendor shortlists.
- Hybrid:Sensitive workloads remain on-premise while customer-facing APIs deploy to public cloud. Tier-one retail banks in Germany and France favor this architecture under DORA continuity mandates. Data residency requirements in Frankfurt and Paris drive edge location specificity.
- On-Premise:Dedicated hardware installations in institutional data centers.
- Multi-Tenant:Shared infrastructure with logical isolation between clients.
Cloud-Based deployments dominate new procurement. Hybrid configurations are gaining share fastest among regulated incumbents.
End User:
Customer type determines integration complexity, with retail banks requiring core system connectivity and credit unions prioritizing out-of-box configurability.
- Retail Banks:Full-stack modernization spanning legacy core replacement and digital channel deployment. Institutions across the United States, United Kingdom, and Australia drive demand for API-first core adjacencies. Charter maintenance and OCC partnership compliance shape vendor selection.
- Credit Unions:Member-centric digital transformation with constrained IT staffing. NCUA-supervised institutions in the United States represent concentrated demand for managed service overlays. Shared branching networks amplify platform economies.
- Insurance Firms:Policy administration and claims payment modernization.
- Investment Firms:Trade execution and custody infrastructure for wealth platforms.
Retail Banks command the largest addressable spend. Credit Unions are climbing the fastest as cloud-native platforms penetrate community finance.
Solution:
Maturity gradients separate established API integration toolkits from emerging AI-native risk engines still proving production reliability.
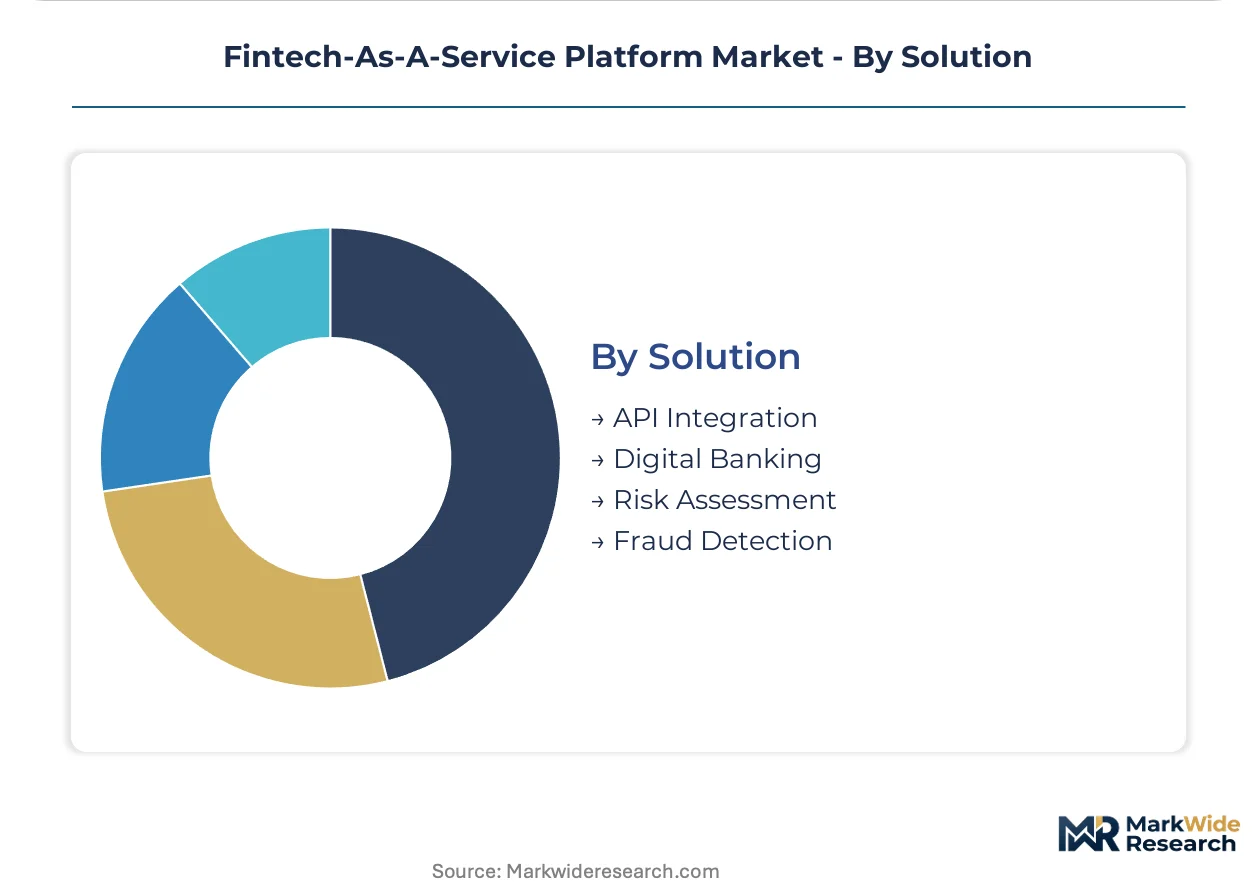
- API Integration:RESTful and GraphQL interfaces enabling composable financial product assembly. Developer experience tooling and SDK completeness differentiate vendors. Demand clusters among fintech builders in Singapore and United States venture-backed startups.
- Fraud Detection:Real-time transaction scoring using behavioral biometrics and device intelligence. E-commerce platforms and digital wallets in the United Kingdom and Brazil deploy these layers to manage chargeback exposure. Model drift monitoring and explainability requirements intensify under GDPR Article 22.
- Digital Banking:End-user mobile and web application frameworks.
- Risk Assessment:Credit scoring and underwriting automation engines.
API Integration holds the widest installed base. Fraud Detection is gaining share fastest as real-time payment adoption accelerates attack surface exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retail banks and neobanks drive the largest procurement volumes, while European institutions under PSD2 and DORA mandates accelerate cloud migration. Asian financial hubs in Singapore and India attract embedded finance deployments targeting underbanked merchant segments.
United States
The OCC and CFPB have clarified charter pathways for bank-fintech partnerships, compressing vendor procurement cycles. FedNow instant settlement infrastructure enables new payroll and B2B liquidity use cases. New York and San Francisco host the densest concentrations of API-first platform engineering talent.
United Kingdom
FCA open banking standards and PSD2 implementation have normalized account data sharing through standardized interfaces. The Digital Operational Resilience Act, as adopted into UK post-Brexit frameworks, imposes strict continuity testing on cloud-dependent providers. London's fintech cluster concentrates embedded finance engineering for e-commerce and mobility platforms.
Germany
BaFin outsourcing guidelines and DORA compliance timelines drive tier-one retail banks toward hybrid cloud architectures. Data residency requirements in Frankfurt and Paris edge locations filter vendor shortlists. Munich and Berlin anchor neobank API integration hubs serving DACH-region credit institutions.
Singapore
Monetary Authority of Singapore licensing frameworks for digital banking and payment services attract regional fintech headquarters. Project Guardian tokenization pilots are virtualizing correspondent banking relationships for cross-border B2B settlements. The city-state's regulatory sandbox hosts embedded finance proof-of-concepts for Southeast Asian market entry.
India
RBI account aggregator frameworks and UPI real-time payment rails enable working capital APIs for underpenetrated small business segments. The central bank's regulatory sandbox permits controlled testing of lending origination and compliance automation modules. Mumbai and Bangalore concentrate developer tooling for merchant-facing embedded finance deployments.
Fintech-As-A-Service Platform Market Competitive Landscape
Channel-controlling players compete with product-specialist players across payment processing, compliance management, and lending API segments. The vendor base stratifies into three tiers: full-stack platforms spanning acceptance through issuing, vertical specialists in card infrastructure or identity verification, and regional challengers targeting localized regulatory environments. Dominant competitive moves include strategic partnerships with retail banks seeking modular core replacements and geographic expansion through regulatory sandbox entry.
Among full-stack infrastructure providers, Stripe and Adyen exemplify the API-first archetype with extensive developer tooling ecosystems. Marqeta occupies a specialist position in card-issuing APIs that anchor modern credit and debit program deployment. These three companies represent contrasting strategic postures: unified platform breadth versus vertical depth in programmable card infrastructure.
| Leading Market Players |
|---|
| Stripe |
| Adyen |
| PayPal Holdings, Inc. |
| Block, Inc. |
| Mastercard, Inc. |
| Fiserv |
| Marqeta |
| Rapyd Financial Network Ltd. |
| Plaid |
| Others |
Supply & Pricing Matrix
Regulatory fragmentation across United States, United Kingdom, and Singapore jurisdictions creates compliance multiplicity that compresses margin pools for cross-border platform operators while simultaneously forcing supply chain localization into separate certification tracks. This structural chokepoint widens pricing spreads between tier-one full-stack vendors and regional specialists, as the latter absorb lower compliance overhead but face scale limitations in API throughput guarantees.
Pricing Analysis
Per-transaction cost-plus contracts indexed to monthly active user volumes dominate enterprise procurement, with interchange optimization and sub-second latency guarantees as tier differentiators. Pricing stratifies across premium, standard, and economy tiers based on SOC 2 certification grade and FedRAMP authorization status. Cost compression in the standard tier is intensifying because hyperscaler cloud infrastructure commoditizes base compute layers. Credit unions and community banks exhibit the highest price sensitivity, while tier-one retail banks prioritize compliance bundling over unit economics.
Supply Chain Analysis
Upstream feedstock in fintech infrastructure centers on cloud compute provisioning from AWS, Azure, and GCP regions, card network connectivity through Visa and Mastercard rails, and core banking system APIs from Fiserv and Jack Henry. The supply chain draws from United States hyperscaler dominance, Irish and German data residency clusters under DORA mandates, and Indian developer tooling ecosystems. Single-source vulnerability concentrates in card network switching and core system middleware. Distribution runs through direct enterprise sales teams and developer relations channels targeting neobank engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded finance penetration in non-financial verticals remains below saturation thresholds, with e-commerce and mobility platforms accelerating API integration timelines as a tailwind. This early-cycle expansion creates asymmetric return profiles for first-movers in compliance-automation convergence.
For Market Incumbents: Harden API gateway infrastructure against latency degradation as real-time payment volumes scale through FedNow and equivalent instant settlement rails. Consolidate position through backward integration into identity verification data sources, neutralizing Plaid-style disintermediation threats. Prioritize DORA certification maintenance in Frankfurt and Dublin edge locations to defend European credit union procurement relationships against regional challengers.
For New Entrants and Emerging Players: Underpenetrated small business merchant segments in India and Brazil present white-space for working capital APIs delivered through UPI and PIX real-time rails. Target credit union shared branching networks in the United States with managed compliance overlays that abstract NCUA examination complexity. Lead with revenue-share pricing structures that minimize customer capital commitment during product launch phases.
For Investors and Strategic Acquirers: DORA implementation timelines reshape the acquisition landscape by elevating operational resilience certification to a hard filter in European vendor shortlists. Position for five-to-ten year holding periods centered on platforms unifying KYC, AML, and transaction monitoring through single API endpoints. Monitor FedNow transaction volume disclosures as the critical inflection signal for payroll and B2B liquidity management adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Convergence | Single API endpoints for KYC, AML, and monitoring capture expanding compliance spend under EBA guidelines. |
| Hybrid Cloud Architecture Deployment | Frankfurt and Paris edge locations satisfy BaFin data residency requirements while enabling elastic capacity. |
| Real-Time Payment Rail Integration | FedNow connectivity unlocks payroll and gig economy disbursement use cases for neobank customers. |
| Developer Experience Platform Investment | RESTful and GraphQL SDK completeness differentiates vendor selection among Singapore fintech builders. |
| Embedded Finance Partnership Expansion | White-label lending APIs penetrate underbanked merchant segments in India through RBI sandbox authorization. |
Research Methodology
Initial hypotheses were tested against primary input from platform engineering leads, regulatory compliance officers, neobank product managers, and credit union IT directors and refined through secondary validation. Primary fieldwork encompassed structured interviews with API infrastructure vendors, retail bank partnership executives, and embedded finance deployers at e-commerce and mobility platforms. Secondary sources included SEC filings from publicly traded fintech infrastructure providers, EBA outsourcing guideline documentation, OCC charter pathway interpretations, and hyperscaler capex disclosures. Bottom-up transaction volume modeling and top-down addressable market sizing were triangulated to anchor projections.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled across service type, deployment topology, end-user institution category, and solution maturity tier. Cloud migration velocity among credit unions and tier-one bank core replacement timelines were incorporated as adoption curve inputs. CAGRs were derived from installed base penetration rates and average revenue per customer expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and venture capital deployment cycles would shift the trajectory of neobank formation and embedded finance investment. Forecasts reflect assumptions about regulatory clarity persistence in United States bank-fintech partnerships and DORA implementation uniformity across European member states. Cross-checking against disclosed API transaction volumes from major card networks and hyperscaler financial services vertical revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Singapore AI in Fintech Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Singapore Fintech Market
FinTech
Africa AI in Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
Latin America AI in Fintech Market
FinTech
MENA Fintech Market
FinTech
Global Fundraising Software Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
IT Financial Management Tools Market
FinTech
Financial App Market
FinTech
North America Fintech Market
FinTech
Australia Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Advanced Authentication in Financial Services Market