
 Men Shirts Market | 2026-2036
Men Shirts Market Size, Share, and Industry Trends Forecast 2026-2036
Men Shirts Market Insights
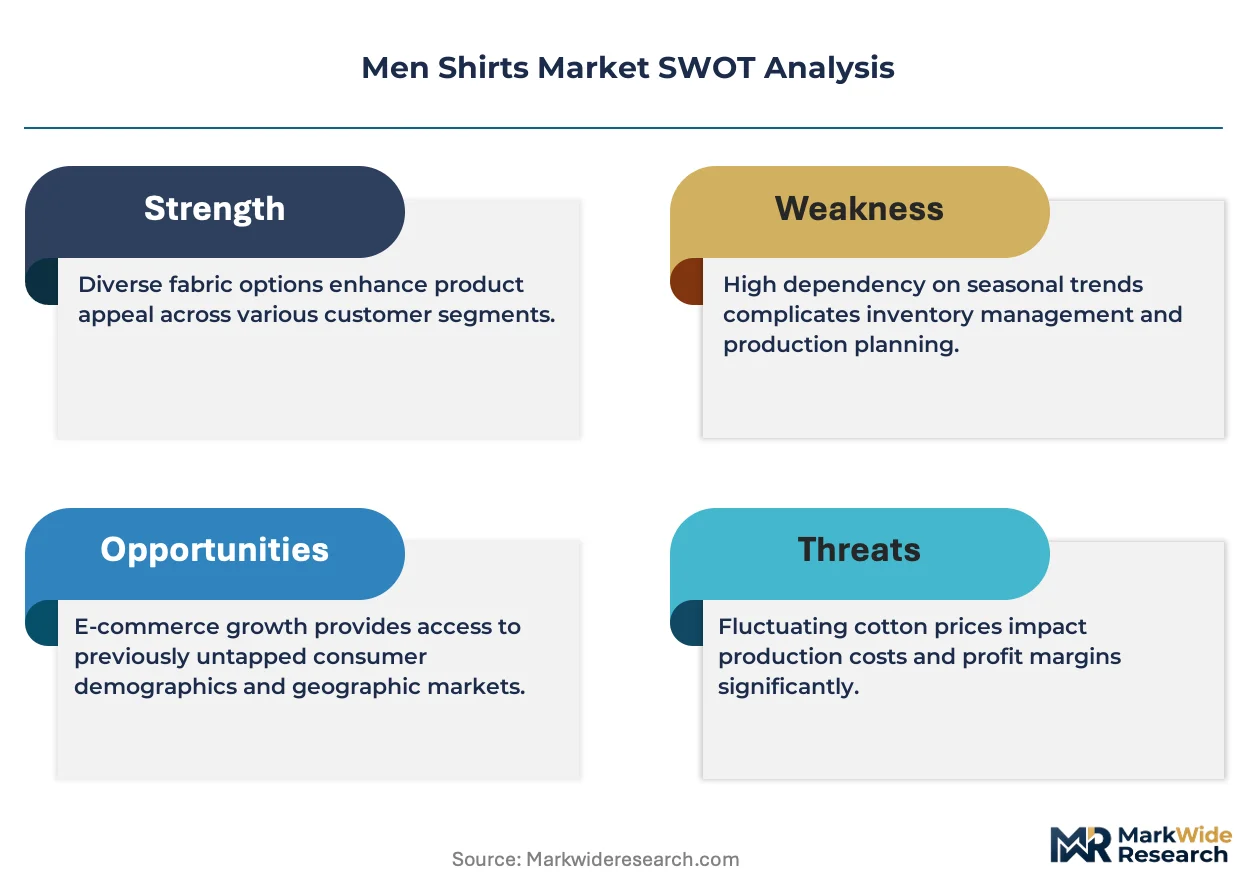
OEKO-TEX Standard 100 certification is reorganizing supplier eligibility across the men shirts supply chain, filtering out mills that cannot verify restricted substance compliance. Ralph Lauren leverages its vertical control over dye houses to sustain premium positioning in formalwear. Uniqlo anchors mass-market volume through direct partnerships with Japanese fabric innovators. Buck Mason differentiates via made-in-USA construction and limited-batch production cycles.
Men shirts encompass upper-body garments engineered with specific collar constructions, placket reinforcements, and armscye tailoring for occupational or social presentation. Cotton poplin and twill weaves dominate formal applications, while jersey knits serve casual and athletic functions through elastane integration for stretch recovery. Dress shirts command the highest margin pool in formalwear channels, whereas T-shirts drive volume through replenishment frequency among young adults. Slim fit styling is displacing traditional cuts in professional segments across Asia-Pacific markets.
REACH in Europe and OEKO-TEX globally constrain dyestuff chemistry and finishing treatments, elevating compliance costs for export-oriented manufacturers. The US EPA monitors wastewater discharge from textile finishing facilities, pressuring brands to certify supply chain partners or face import restrictions. Stakeholders must monitor how dual carbon targets in China and extended producer responsibility frameworks in the EU will reshape fiber sourcing decisions and regional production allocation.
Market Dynamics
REACH chemical compliance in Europe is filtering out non-compliant dye houses and forcing mills to verify restricted substance protocols, compressing supplier eligibility across the men shirts supply chain and elevating sourcing costs for export-oriented manufacturers.
Growth Catalysts
- Business-casual workplace policies:Corporate uniform programs in professional services and technology sectors are expanding formal shirt adoption among white-collar buyer segments seeking versatile office-to-evening garments.
- Organic cotton cultivation mandates:Agricultural incentives in India and Turkey are accelerating fiber transitions that meet OEKO-TEX Standard 100 certification requirements for European export markets.
- Guangdong manufacturing clusters:Domestic Chinese menswear brands are scaling vertically integrated production bases that reduce lead times and capture margin from design to finished goods.
Market Restraints
- Cotton price volatility:Climate-induced yield fluctuations in major growing regions are compressing margin predictability for mid-tier manufacturers dependent on long-staple fiber contracts.
- Supply concentration in Zhejiang province:Finished shirt production gravity centers on a single Chinese coastal region, creating vulnerability to port congestion and regional labor disruptions.
- REACH dyestuff restrictions:The ECHA's expanding list of restricted aromatic amines is forcing reformulation of conventional finishing treatments and elevating R&D expenditure for EU-bound exporters.
Strategic Opportunities
- Extended producer responsibility frameworks:The EU Green Deal's textile waste directives are creating first-mover advantage for brands building closed-loop recycling infrastructure and take-back programs.
- Direct-to-consumer digital channels:Made-to-measure platforms using 3D body scanning are capturing premium wallet share from traditional retail intermediaries in North American and European urban markets.
- Dual carbon targets in China:Beijing's 2030 emissions commitments are accelerating investment in solar-powered dyeing facilities and low-carbon logistics corridors for export manufacturing.
Industry Challenges
- Certification timeline compression:OEKO-TEX and GOTS audit backlogs are extending supplier onboarding cycles, delaying product launches for brands seeking verified sustainable positioning.
- Pattern-making automation integration:Legacy CAD systems in established manufacturing bases resist interoperability with AI-driven sizing algorithms, fragmenting quality consistency across production lots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Men Shirts Market |
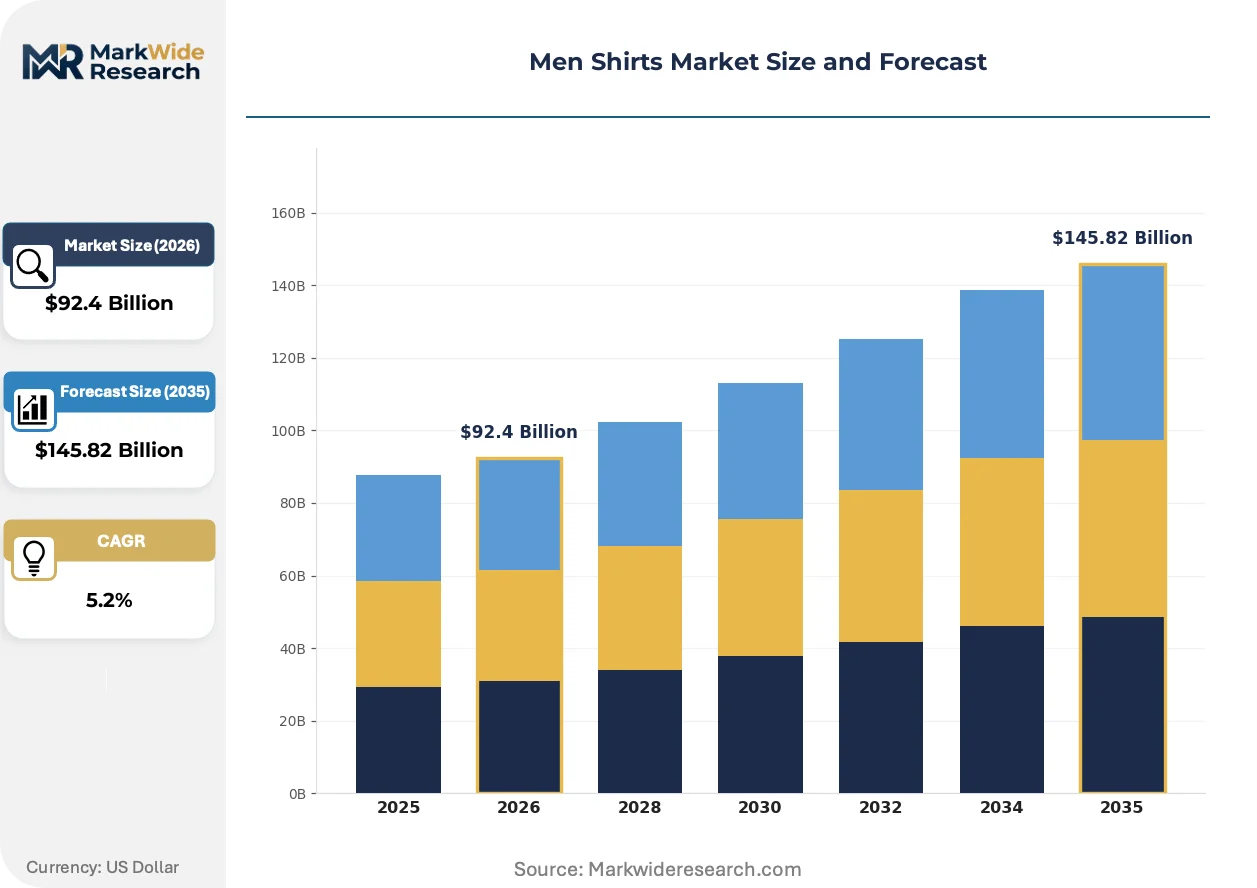
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $145.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dress Shirts, Polo Shirts, Casual Shirts Fabric: Cotton, Linen, Polyester, Blends Style: Formal, Casual, Athletic, Slim Fit Target Group: Young Adults, Professionals, Older Adults, Students |
| Companies Covered | Ralph Lauren, Brooks Brothers, Van Heusen, Paul Smith, Uniqlo, Bonobos, Buck Mason, Mack Weldon, Abercrombie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Men Shirts Market Trends and Innovations
Digital textile printing and bio-based finishing chemistry are compressing traditional production timelines while enabling mass customization at scale, fundamentally altering how shirt manufacturers balance inventory risk against consumer specificity.
Digital textile printing technology applies reactive dyes directly onto fabric without screen setup, eliminating minimum order quantities and enabling single-unit production runs. Young adult consumers in urban European markets are adopting personalized shirt platforms that deliver within 72 hours. This capability is miniaturizing the economic advantage of offshore batch manufacturing and enabling regional micro-factories to compete on speed rather than labor cost.
REACH authorization requirements under the EU Green Deal are phasing out per- and polyfluoroalkyl substances in water-repellent shirt finishes, compelling reformulation toward bio-based alternatives. German and Italian finishing houses are investing in plasma-based surface treatments that achieve comparable performance without fluorinated chemistry. Premium formalwear segments bear the highest compliance burden, passing elevated costs to corporate uniform buyers with mandated sustainability procurement policies.
Replenishment-driven purchasing among male consumers aged 18-34 is displacing seasonal wardrobe cycles, compressing design-to-shelf timelines and elevating the importance of core basic programs. Fast-fashion retailers in South Korea and Japan are responding with weekly drops of limited-color shirt SKUs rather than traditional seasonal collections. This behavioral shift concentrates volume in jersey-knit casual shirts while pressuring formalwear channels to justify higher price points through construction quality and certification transparency.
Men Shirts Market Segmentation
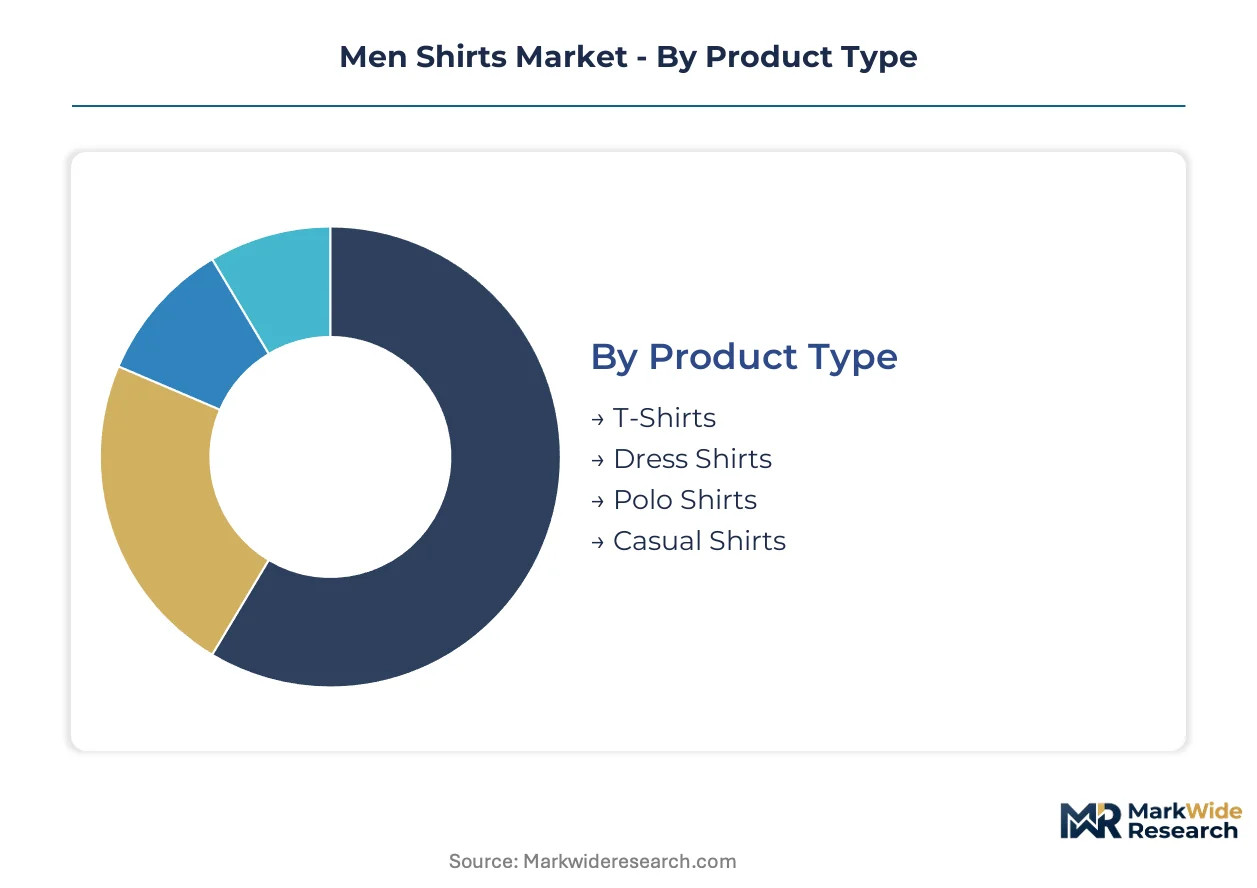
Men shirts segmentation reveals how fiber choices, styling preferences, and occupational requirements fragment procurement patterns across professional and casual buyer pools. Distinct compliance burdens and replenishment cycles govern each category's commercial dynamics.
Product Type:
Dress shirts anchor export manufacturing in Guangdong and Zhejiang provinces, while T-shirts concentrate domestic replenishment volume in North American and European fast-fashion channels.
- Dress Shirts:Structured collar constructions with fused interlinings and French placket reinforcements serve corporate uniform programs and business-casual workplace mandates. European REACH compliance requirements filter supplier eligibility for formalwear exporters serving professional services sectors in Germany and France.
- T-Shirts:Jersey-knit constructions with elastane integration for stretch recovery dominate replenishment purchasing among male consumers aged 18-34. Weekly drop cycles from South Korean and Japanese fast-fashion retailers compress design-to-shelf timelines for core basic programs.
- Polo Shirts:Pique knit constructions with ribbed collar and cuff details bridge office-to-casual transitions for technology sector dress codes.
- Casual Shirts:Button-down collars and single-needle stitching differentiate weekend and social presentation segments across urban European markets.
Dress shirts command the established base. The steepest expansion runs through T-shirts.
Fabric:
Cost tiers separate premium natural fibers from synthetic alternatives, with certification requirements determining eligibility for EU-bound export channels.
- Cotton:Long-staple varieties in poplin and twill weaves dominate formal applications requiring OEKO-TEX Standard 100 verification. Organic cultivation transitions in India and Turkey reshape fiber sourcing for European compliance markets.
- Blends:Cotton-polyester combinations optimize wrinkle resistance and price accessibility for mid-tier corporate uniform programs in North America.
- Linen:Bast fiber constructions with characteristic slub texture serve warm-climate professional and resort segments.
- Polyester:Petroleum-derived filament yarns enable performance moisture-wicking in athletic and outdoor applications.
Cotton holds the volume foundation. Blends are climbing the fastest on cost-performance optimization.
Style:
Application context determines construction specifications, with professional environments imposing stricter compliance and fit precision than casual or athletic use cases.
- Slim Fit:Darted back panels and higher armholes reduce excess fabric for contemporary professional silhouettes displacing traditional cuts across Asia-Pacific urban centers.
- Formal:Structured interlinings, convertible cuffs, and precise collar roll construction serve legal, financial, and consulting sector dress codes.
- Casual:Soft collar constructions and relaxed armscye tailoring accommodate remote work and hybrid office policies.
- Athletic:Gusseted underarms and stretch-integrated knits support range of motion for performance and commuter cycling segments.
Formal styling retains the premium margin pool. Slim fit gains share fastest on generational preference shifts.
Target Group:
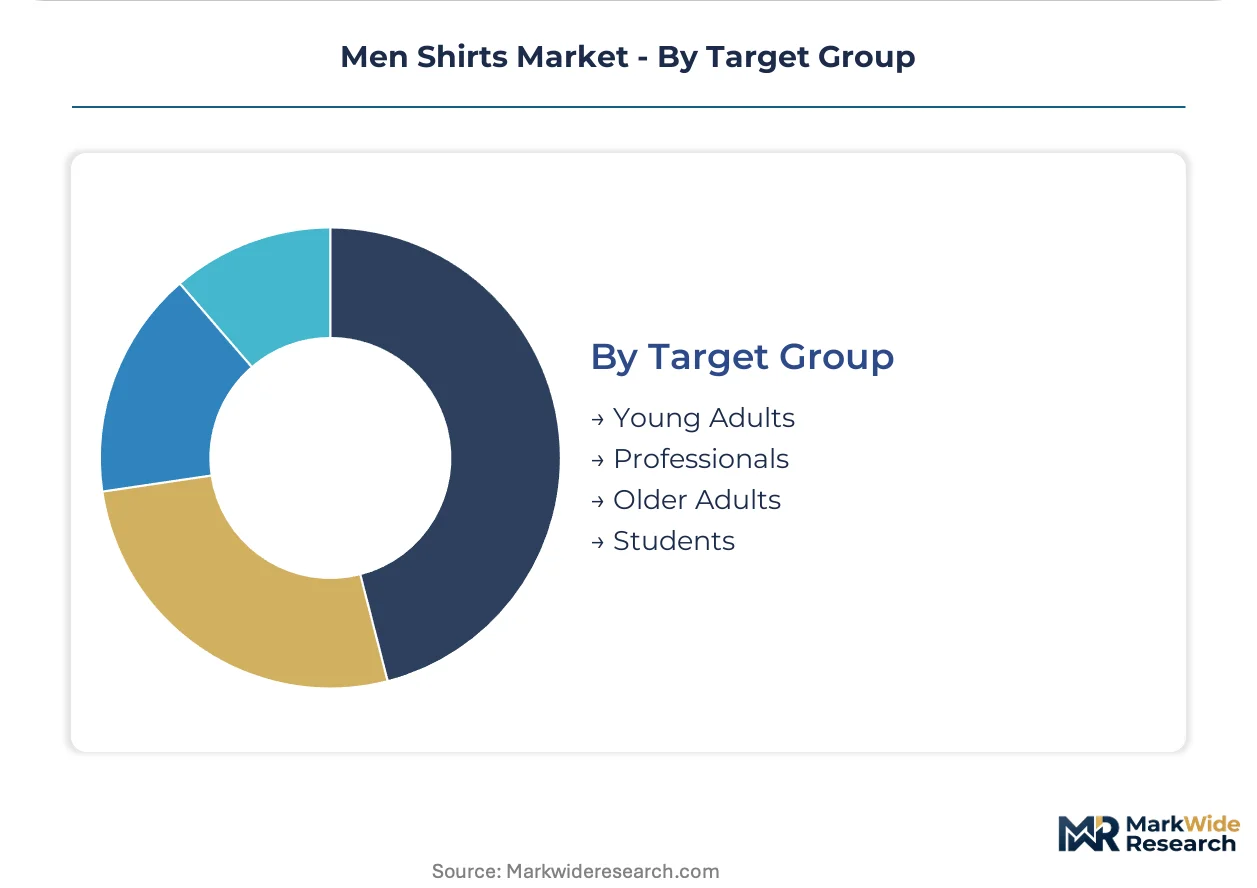
Customer type dictates replenishment frequency, price sensitivity, and certification transparency requirements across digital and traditional retail channels.
- Professionals:Corporate buyers with mandated sustainability procurement policies drive OEKO-TEX and GOTS verification requirements for formalwear volume.
- Young Adults:Replenishment-driven purchasing patterns compress seasonal cycles and elevate importance of core basic programs with rapid delivery logistics.
- Students:Price-accessible casual and athletic segments concentrate in back-to-school seasonal peaks with lower certification burden.
- Older Adults:Traditional fit preferences and higher quality durability expectations sustain premium natural fiber demand in established retail channels.
Professionals anchor the revenue base. Young adults show the steepest expansion trajectory on digital channel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific garment export throughput, channeling Zhejiang and Guangdong manufacturing output toward European and North American distribution hubs. Containerized shipping corridors from Ningbo-Zhoushan and Shenzhen lock in China's dominance of finished shirt logistics.
China
Domestic menswear brands scale vertically integrated production bases in Guangdong and Zhejiang provinces, compressing lead times from design to finished goods. Beijing's dual carbon targets under MEE oversight accelerate solar-powered dyeing facility investment. The Pearl River Delta manufacturing cluster captures margin through captive fabric mills and automated cutting floors serving export and domestic channels simultaneously.
United States
Corporate uniform procurement programs drive formal shirt volume through mandated sustainability certification requirements. The EPA monitors wastewater discharge from textile finishing facilities, pressuring brands to verify supply chain partners. Regional micro-factories in North Carolina and Los Angeles compete on speed-to-market using digital textile printing for made-to-measure platforms.
Germany
Professional services sectors in Frankfurt and Munich impose REACH compliance requirements on formalwear suppliers, filtering dye house eligibility. The ECHA's expanding restricted substance list forces reformulation of conventional finishing treatments. Bavarian and North Rhine-Westphalia finishing houses invest in plasma-based surface treatments eliminating fluorinated chemistry from water-repellent shirt production.
India
Agricultural incentives in Maharashtra and Gujarat accelerate organic cotton cultivation transitions meeting OEKO-TEX Standard 100 requirements. Tiruppur and Surat manufacturing clusters specialize in jersey-knit casual shirt production for European fast-fashion replenishment cycles. BIS fiber grading standards align with export certification demands from German and French retail buyers.
Japan
Fast-fashion retailers in Tokyo and Osaka deploy weekly drop cycles of limited-color shirt SKUs, compressing traditional seasonal collection timelines. METI circular economy guidelines pressure domestic brands to build closed-loop recycling infrastructure. Osaka-based fabric innovators partner directly with mass-market retailers to secure proprietary weave developments for core basic programs.
Men Shirts Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and channel strategy, producing a bifurcated structure where scale-driven conglomerates anchor mass-market volume while founder-led labels capture premium positioning through construction transparency. The vendor base organizes around three archetypes: heritage formalwear houses with vertical dye house control, fast-fashion platforms with direct fabric innovation partnerships, and domestic specialists leveraging made-in-origin construction claims. Competitive moves concentrate on backward integration into captive fabric supply and geographic diversification of manufacturing to reduce single-region concentration risk.
Within the heritage formalwear tier, Ralph Lauren and Brooks Brothers exemplify positioning built on decades of vertical control over finishing and dyeing operations. Uniqlo anchors the fast-fashion vector through direct partnerships with Japanese textile developers. Buck Mason represents the domestic specialist archetype, occupying a position defined by made-in-USA construction claims and limited-batch production cycles that differentiate against offshore manufacturing norms.
| Leading Market Players |
|---|
| Ralph Lauren |
| Brooks Brothers |
| Van Heusen |
| Paul Smith |
| Uniqlo |
| Bonobos |
| Buck Mason |
| Mack Weldon |
| Abercrombie |
| Others |
Pricing and Supply Chain Analysis
Organic cotton substitution for conventional long-staple fiber is simultaneously shifting cultivation geography toward Maharashtra and Gujarat while compressing margin predictability for mid-tier manufacturers locked into fixed-price contracts. This input transition elevates certification costs for EU-bound exporters and concentrates pricing power among vertically integrated mills with captive organic supply.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with OEKO-TEX Standard 100 verification commanding substantial premiums from corporate uniform buyers with mandated sustainability procurement policies. Three-tier pricing structure across premium, standard, and economy levels stratifies by construction quality, fiber grade, and compliance transparency. Pricing pressure stems from cotton price volatility driven by climate-induced yield fluctuations, compressing margins for manufacturers dependent on spot fiber markets. Young adult replenishment buyers exhibit highest price sensitivity, while professional services procurement shows lowest sensitivity due to sustainability mandate pass-through.
Supply Chain Analysis
Port congestion at Ningbo-Zhoushan and Shenzhen underwrites delivery risk for Zhejiang and Guangdong manufacturing clusters serving North American and European distribution hubs. Finished shirt production draws from China, India, and Bangladesh, with raw cotton sourcing resting on Indian, Turkish, and US agricultural output. Single-region concentration in coastal China creates vulnerability to labor disruptions and logistics bottlenecks. Distribution runs through containerized shipping corridors anchored by Shanghai export throughput, with regional micro-factories in North Carolina and Los Angeles competing on speed-to-market through digital textile printing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate uniform programs represent a service-attach opportunity where take-back and recycling programs expand faster than garment hardware sales, creating recurring revenue layers through closed-loop infrastructure.
For Market Incumbents: Consolidate dye house control through backward integration into captive finishing operations to defend against REACH compliance cost escalation filtering non-compliant suppliers. Acquire OEKO-TEX certified mills in India and Turkey to secure organic fiber supply and reduce China concentration exposure. Lock in multi-year corporate uniform contracts with embedded sustainability verification to anchor volume against fast-fashion replenishment compression.
For New Entrants and Emerging Players: Differentiate on made-to-measure speed using 3D body scanning platforms targeting urban European and North American professionals aged 25-40. Target the white-space between mass-market fast-fashion and heritage formalwear by offering certified sustainable construction at accessible price points. Pursue direct-to-consumer digital channels with 72-hour delivery promises to capture premium wallet share from traditional retail intermediaries.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive fabric supply and certification infrastructure. Long-term viability over the next decade hinges on closed-loop recycling capabilities and carbon-compliant manufacturing positioning. Monitor ECHA restricted substance list expansions as the primary inflection indicator for supplier eligibility compression and margin restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Dye Houses | REACH compliance costs filter non-verified mills, elevating vertically integrated players. |
| Direct-to-Consumer Digital Launch | 3D body scanning platforms capture premium wallet share from traditional retail intermediaries. |
| Sustainability Certification Investment | OEKO-TEX and GOTS verification unlocks corporate uniform procurement with mandated policies. |
| Regional Micro-Factory Expansion | Digital textile printing in North Carolina and Los Angeles competes on speed-to-market. |
| Closed-Loop Recycling Infrastructure | EU Green Deal textile waste directives create first-mover advantage for take-back programs. |
Research Methodology
The analysis maps dress shirts, T-shirts, polo shirts, and casual shirts, each validated through primary interviews with brand supply chain directors, textile mill procurement managers, corporate uniform program administrators, and fast-fashion category buyers. Secondary validation draws from customs export records, OEKO-TEX certification databases, ECHA restricted substance filings, and EPA wastewater discharge monitoring. Bottom-up volume estimates triangulate against top-down value projections across fiber type, construction method, and end-use application.
Consistency checks against external benchmarks validate output robustness across the projection horizon. Segmentation dimensions modeled include product type, fabric composition, styling preference, and target demographic cohort. CAGRs derive from historical shipment trajectories adjusted for regulatory compliance cost acceleration and organic fiber transition timelines. Forecast inputs incorporate REACH authorization timelines, dual carbon target implementation in China, and replenishment cycle compression among young adult consumers.
The analysis sits within stated boundaries; outcomes outside sustained certification audit capacity and stable cotton cultivation yields would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and corporate sustainability mandate penetration. Practitioners should keep alternative scenarios live as ECHA substance restrictions and China emissions commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Shirts and Blouses Market
Apparel & Footwear
Football Kits Market
Apparel & Footwear
Women's Socks Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Cosplay Costumes Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Outdoor Sports Apparel Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Jeans Market