
 Face Wash Market | 2026-2036
Face Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Face Wash Market Intelligence
Sulfate-free surfactant chemistry is rebalancing cost structures across mid-tier and premium formulations. L'Oréal S.A. leverages its integrated raw-material sourcing to control surfactant costs across European plants. Unilever PLC anchors volume production through scalable gel and foam platforms distributed in emerging markets. Shiseido Company, Limited differentiates through fermented ingredient technology developed at its Yokohama research center.
Face wash denotes a rinse-off cleansing preparation containing surfactants, emollients, and functional actives at pH 4.5–6.5, manufactured through cold-process emulsification or hot-mix homogenization to remove sebum, particulate matter, and cosmetic residues from facial skin. Foam formats dominate mass-market shelf space due to pump-dispenser convenience and per-use cost efficiency, while gel vehicles capture younger demographics seeking lightweight, non-comedogenic textures. Antibacterial formulations face regulatory headwinds from triclosan and triclocarban restrictions, redirecting R&D investment toward hydrating and exfoliating variants with acid-based actives.
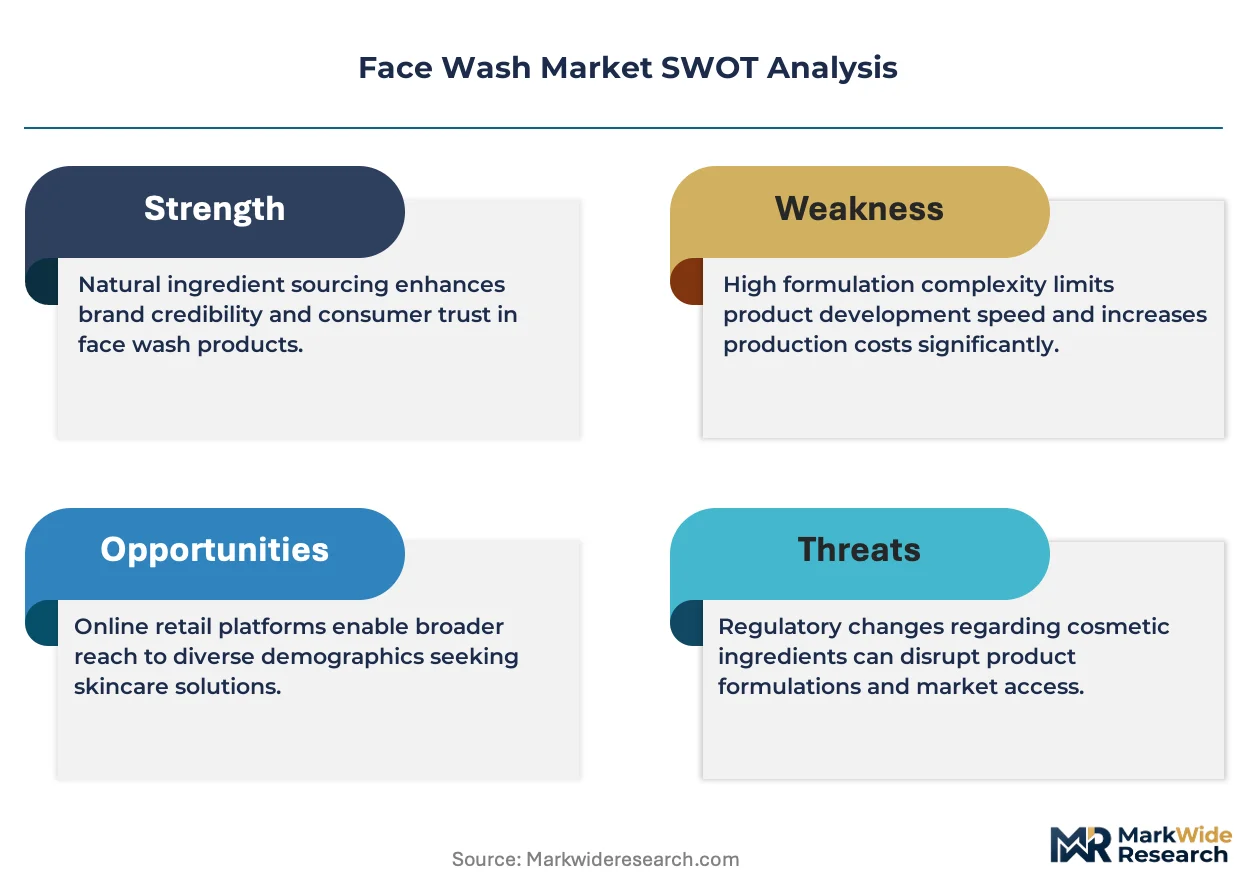
REACH governs surfactant and preservative approvals across Europe, forcing reformulation cycles that extend product development timelines. The FDA oversees cosmetic labeling and over-the-counter drug claims in the United States, creating compliance friction for brands positioning face wash as acne treatment. China's NMPA requires animal-testing alternatives for imported cosmetics, reshaping how multinationals validate new ingredient safety. Stakeholders must monitor regulatory divergence between jurisdictions to avoid portfolio fragmentation and duplicated clinical testing.
Market Dynamics
Sulfate-free surfactant chemistry is forcing a wholesale recalibration of formulation economics, as manufacturers absorb higher raw-material costs to meet EU Green Deal disclosure mandates and consumer clean-label expectations simultaneously.
Growth Catalysts
- EU Green Deal chemical transparency mandates:REACH framework revisions accelerate reformulation toward biodegradable surfactants, creating first-mover advantages for compliant suppliers.
- Fermented bioactive ingredient platforms:Biotechnology-derived actives replace synthetic alternatives in premium positioning, unlocking margin expansion in urban China and South Korea.
- South Korea's K-beauty export engine:Seoul-based innovation clusters drive gel-format adoption across Southeast Asian duty-free channels and cross-border e-commerce.
Market Restraints
- Surfactant input cost volatility:Coconut-derived glucosides and amino-acid-based cleansers trade at 40-60% premiums versus sulfates, compressing mid-tier brand margins.
- European regulatory timeline friction:ECHA substance evaluation cycles extend new-product registration by 18-24 months, freezing pipeline releases.
- Waterless cleansing balm substitution:Solid and anhydrous formats gain traction among zero-waste consumer segments in Germany and Nordic markets.
Strategic Opportunities
- India's tier-2 urban expansion:Surat, Indore, and Kochi present underpenetrated demand for sachet-format foam cleansers distributed through modern trade.
- China NMPA animal-testing waiver pathways:Alternative validation methods unlock accelerated entry for European and American brands previously excluded.
- Derma-cosmetic channel convergence:Dermatology clinic dispensing and telemedicine prescription flows create professional-grade positioning opportunities.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in acid-stable surfactant systems and microbiome-compatible preservation commands premium compensation in Shanghai and Singapore.
- Multi-jurisdiction dossier duplication:Divergent safety substantiation requirements between FDA, REACH, and NMPA force redundant toxicology testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Wash Market |
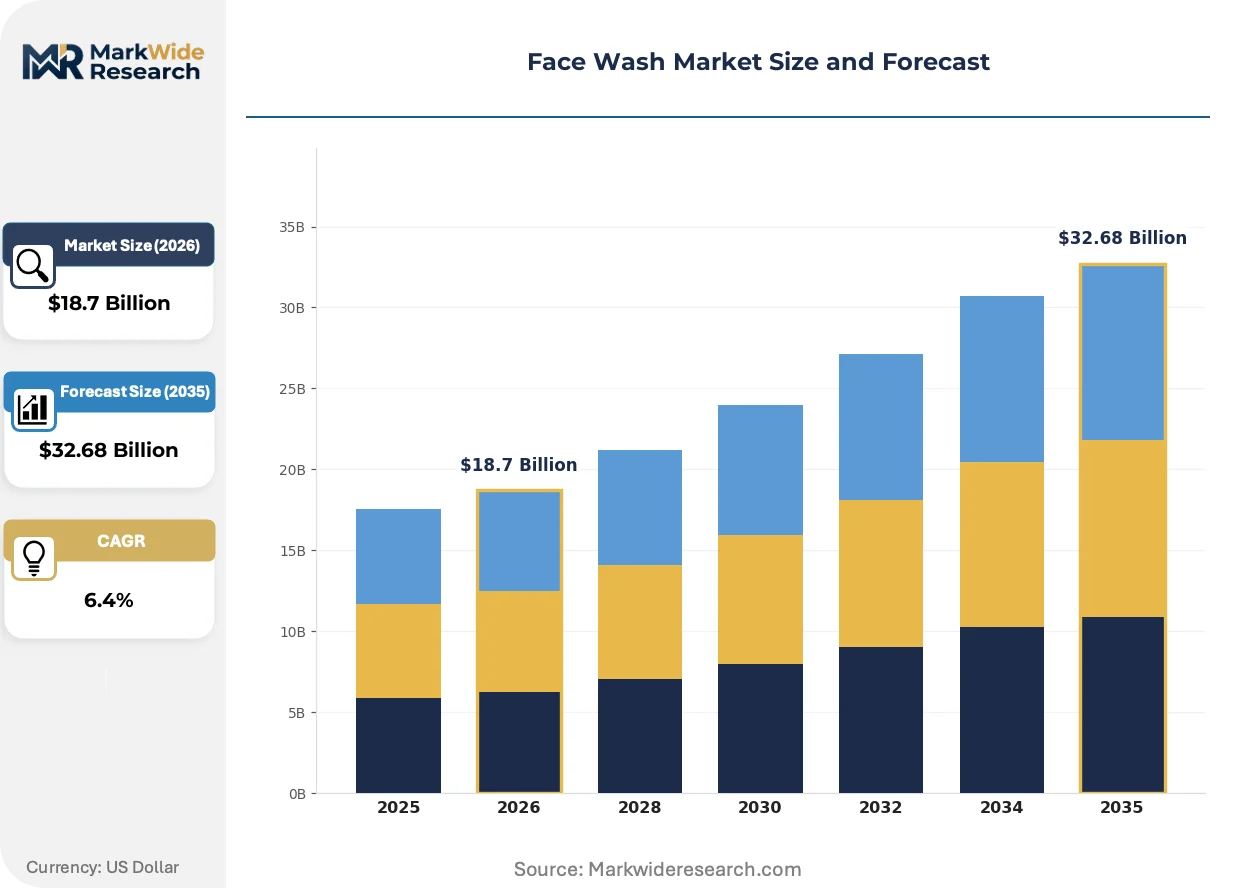
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Gel, Cream, Liquid Formulation: Organic, Antibacterial, Exfoliating, Hydrating End User: Teenagers, Adults, Men, Women Packaging Type: Tube, Bottle, Jar, Sachet |
| Companies Covered | Johnson & Johnson, Shiseido Company, Limited, The Procter & Gamble Company, Amorepacific Corporation, Kao Corporation, L’Oréal S.A., Beiersdorf AG, Estée Lauder Companies Inc., Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Wash Market Strategic Shifts & Innovations
Biotechnology and regulatory disclosure are converging to reshape competitive positioning, as transparency becomes a technical capability rather than a marketing claim.
Postbiotic fermentation technology is rewriting how functional actives are manufactured and validated. Japanese and South Korean suppliers now commercialize lysate-derived ceramides and peptide complexes at scale. Young adult consumers in Seoul and Tokyo adopt these formats three times faster than conventional synthetic alternatives, compressing R&D amortization cycles for originator firms.
REACH Annex XVII expansion tightens microplastic restrictions in rinse-off cosmetics, forcing polyethylene bead elimination and natural abrasive substitution. The European Chemicals Agency enforcement timeline pressures brands to reformulate exfoliating variants before 2027 compliance deadlines. Polish and Romanian manufacturing plants face the steepest retooling costs due to legacy equipment configurations.
Direct-to-consumer subscription models displace traditional retail replenishment cycles in North American and British urban markets. Trial-size customization and algorithmic skin-matching replace mass-market shelf selection. This channel shift concentrates customer acquisition spending on Meta and TikTok platforms, elevating digital-native challengers against established retail-dependent incumbents in Los Angeles and London postcodes.
Face Wash Market Segmentation
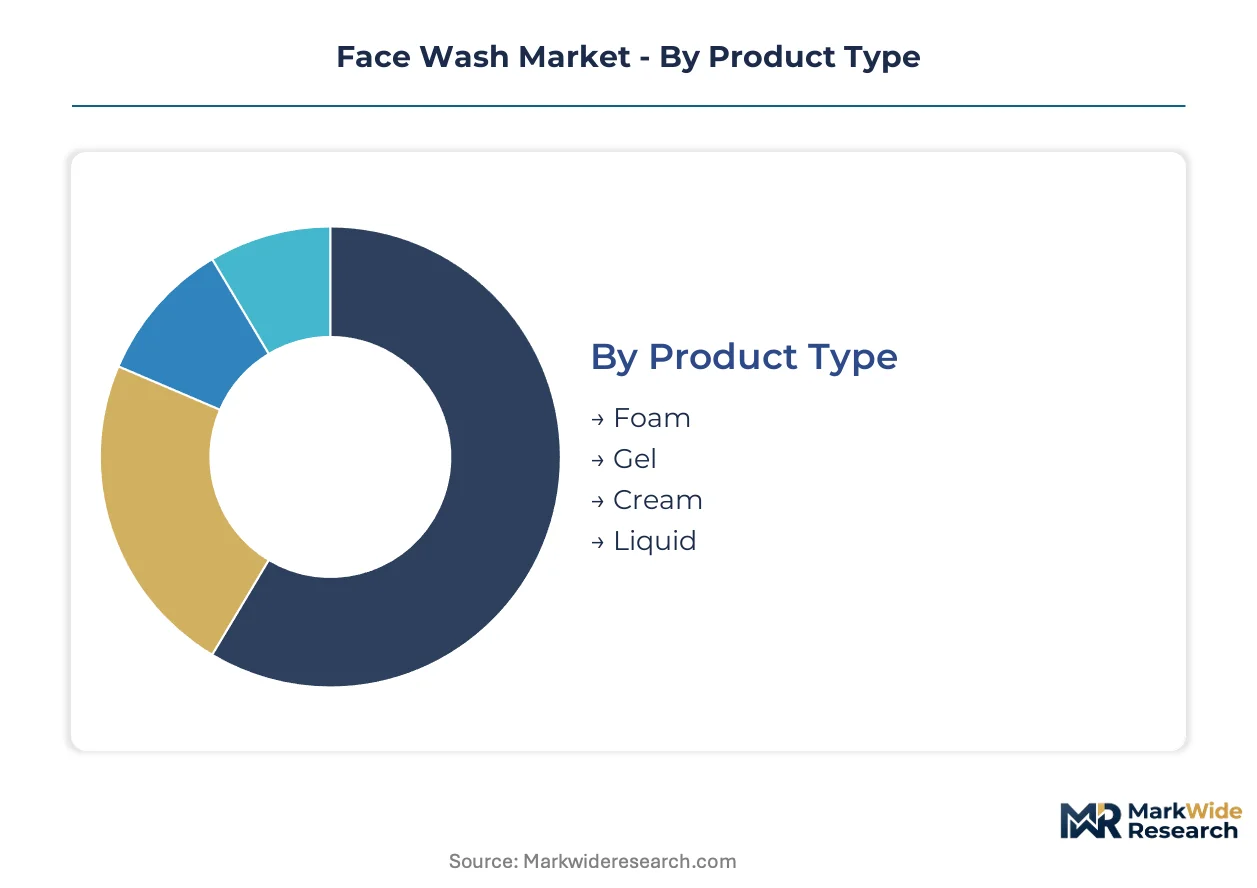
Face wash manufacturers align R&D investment and channel strategy against distinct usage occasions and buyer willingness-to-pay thresholds. Product format, ingredient positioning, demographic targeting, and packaging economics each create separable profit pools with divergent margin profiles.
Product Type:
Buyers in this category differentiate primarily by texture preference tied to skin type and climate conditions rather than price sensitivity alone.
- Foam:Pump-dispensed aerated formulations deliver surfactant-rich cleansing with minimal manual lathering. Demand concentrates in mass-market retail across humid Southeast Asian markets where lightweight residue-free rinsing drives repurchase frequency.
- Gel:Transparent, water-based vehicles incorporate carbomer or xanthan structuring agents for non-drip application. Young adult consumers in Seoul and Tokyo favor gel formats for their aesthetic minimalism and compatibility with layered skincare routines.
- Cream:Emulsion-based cleansers with elevated lipid content target mature skin segments and cold-climate usage. North American pharmacy channels stock cream variants for barrier-compromised skin conditions.
- Liquid:Free-flowing aqueous solutions require cotton pad or splash application, occupying niche positioning in professional salon dispensing and travel-size assortments.
Volume sits with Foam; growth tilts toward Gel.
Formulation:
Margin capture in this category depends on certification tier and active ingredient complexity rather than production scale.
- Organic:Plant-derived surfactant bases and natural preservation systems command certification premiums from ECOCERT or COSMOS. German and French buyers absorb price multiples for verified biodegradable ingredient decks.
- Antibacterial:Triclosan-free alternatives deploy benzoyl peroxide or tea tree oil actives under tightened FDA and REACH oversight. Reformulation costs have redirected investment toward non-medicated positioning.
- Exfoliating:Acid-based actives (salicylic, glycolic, lactic) replace physical microbeads under ECHA microplastic restrictions. South Korean manufacturers lead clinical validation for acid-stable surfactant systems.
- Hydrating:Hyaluronic acid and glycerin incorporation targets post-cleansing moisture retention. Urban Chinese consumers prioritize hydrating claims in tier-1 city department store purchases.
Organic formulations command the steepest price premiums; Exfoliating variants are climbing the fastest as polyethylene bead phase-outs accelerate.
End User:
Demographic targeting in this category reflects divergent media consumption patterns and retail channel preferences rather than fundamentally different skin biology.
- Adults:Primary revenue base spanning anti-aging and preventive skincare positioning. Demand concentrates in premium e-commerce subscriptions and dermatology clinic dispensing across the United States and China.
- Women:Traditional category anchor with established multi-step routine behavior. Japanese and South Korean mass-market innovation cycles prioritize female-targeted packaging aesthetics and fragrance profiles.
- Men:Simplified positioning emphasizing speed and convenience drives adoption in urban India and Brazil. Bar-format and 2-in-1 hybrid claims capture male buyers resistant to extended routines.
- Teenagers:Acne-focused messaging and influencer-driven trial dominate TikTok and Instagram acquisition strategies. Price-accessible sachet formats penetrate secondary cities in Indonesia and Vietnam.
Women generate current volume; Men represent the most steeply expanding trajectory as grooming routine formalization spreads.
Packaging Type:
Unit economics and distribution reach in this category hinge on primary pack format selection and refill infrastructure availability.
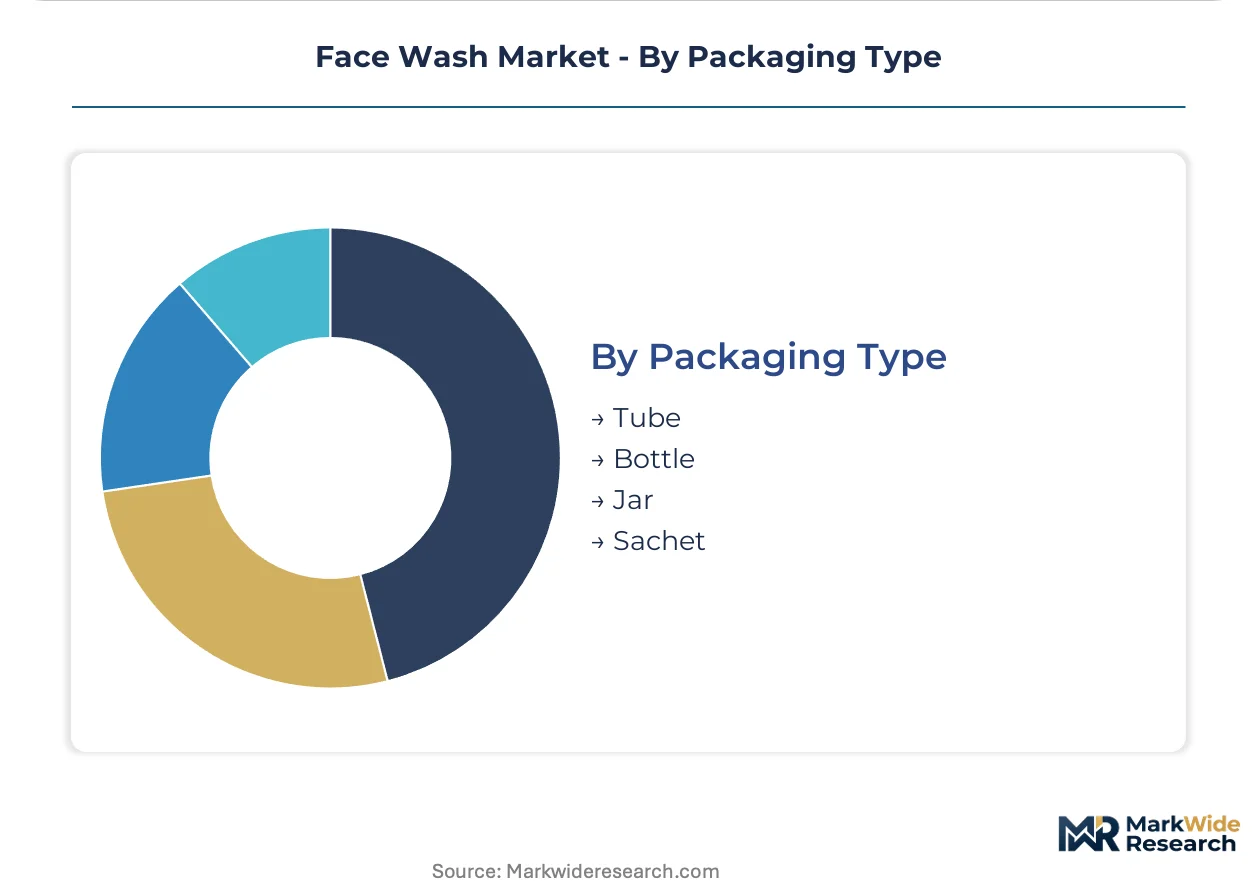
- Tube:Laminate or mono-material squeeze formats dominate mid-tier retail shelving for controlled dispensing. European supermarkets are transitioning tube stocks to recyclable mono-polymer structures under extended producer responsibility schemes.
- Bottle:PET or HDPE rigid containers with pump or flip-cap closures suit family-size and back-bar professional volumes. Refill pouch compatibility is becoming a design specification for premium bottle lines.
- Sachet:Single-use flexible film packets enable trial conversion and rural market penetration at minimal per-unit price points. Indian modern trade and traditional kirana channels rely on sachet economics for volume distribution.
- Jar:Wide-mouth rigid packaging for balm and cream formats supports finger-dip application. Aesthetic-driven jar selection concentrates in gift sets and premium countertop display.
Tube and Bottle split current volume; Sachet packaging is gaining share fastest in emerging market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for face wash concentrates in the United States, China, and South Korea, with each market exhibiting distinct formulation preferences and regulatory compliance requirements that reshape local competitive dynamics.
United States
FDA cosmetic labeling rules and over-the-counter drug claims for acne treatment create compliance friction for brands positioning face wash as therapeutic. Young adult consumers in Los Angeles and New York Metro drive subscription-based replenishment through direct-to-consumer channels. The Southeast corridor hosts contract manufacturing clusters serving mass-market foam and gel formats.
China
NMPA animal-testing waiver pathways for imported cosmetics accelerate entry for European and American brands previously excluded from mainland distribution. Tier-1 cities Shanghai and Beijing concentrate premium hydrating variant demand in department store channels. Surat and Indore in India present underpenetrated sachet-format opportunities for mass-market expansion.
South Korea
Seoul-based innovation clusters drive gel-format adoption across Southeast Asian duty-free channels and cross-border e-commerce. MFDS cosmetic safety standards align with K-beauty export requirements, streamlining regional market access. Busan-Ulsan manufacturing hubs supply fermented bioactive ingredients to premium positioning brands.
Germany
REACH Annex XVII microplastic restrictions force polyethylene bead elimination from exfoliating variants before 2027 deadlines. ECOCERT and COSMOS certification premiums attract biodegradable surfactant investment in Bavaria and North Rhine-Westphalia. Polish and Romanian legacy plants face steepest retooling costs under extended producer responsibility schemes.
India
BIS cosmetic standards and state-level manufacturing incentives support domestic production scale-up in Maharashtra and Gujarat. Modern trade penetration in Surat, Indore, and Kochi expands sachet-format foam cleanser distribution. Tier-2 urban markets exhibit underpenetrated demand relative to per-capita skincare spending growth.
Face Wash Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with mass-market foam formats consolidating around scale-driven multinationals while premium gel and fermented variants fragment among innovation-led regional champions. Three strategic archetypes dominate: integrated beauty conglomerates with captive raw-material sourcing, biotechnology-forward specialists leveraging fermentation platforms, and agile private-label suppliers serving retail channel consolidation. Competitive moves concentrate on M&A for ingredient technology access and capacity expansion in Southeast Asian manufacturing zones.
Within the integrated multinational tier, L'Oréal S.A., Unilever PLC, and Shiseido Company, Limited exemplify divergent sourcing and positioning strategies. L'Oréal S.A. anchors European production through controlled surfactant supply chains. Unilever PLC occupies scalable gel and foam platform distribution across emerging markets. Shiseido Company, Limited represents biotechnology specialization through Yokohama-based fermented ingredient development.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Shiseido Company, Limited |
| The Procter & Gamble Company |
| Amorepacific Corporation |
| Kao Corporation |
| L'Oréal S.A. |
| Beiersdorf AG |
| Estée Lauder Companies Inc. |
| Unilever PLC |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap surfactant specialists in Germany and South Korea anchor upstream supply, translating REACH compliance investments into pricing discipline that filters downstream to finished-formulation tiers.
Pricing Analysis
Volume tilts toward mass-market foam formats while margin capture concentrates in premium gel and fermented variants. Pricing stratifies across premium, standard, and economy tiers, with ECOCERT certification and acid-stable surfactant systems driving differentiation. Cost compression in mid-tier segments intensifies because coconut-derived glucosides trade at steep premiums versus legacy sulfates. Teenage buyers in Southeast Asian secondary cities exhibit highest price sensitivity, while urban Chinese consumers in tier-1 department stores absorb certification premiums with minimal elasticity.
Supply Chain Analysis
ECOCERT and COSMOS qualification gates restrict supplier pools for organic-positioned brands, compressing viable raw-material sources. Manufacturing concentrates in Germany, South Korea, and China, with surfactant production drawing from palm-derived and coconut-derived feedstocks. Single-source vulnerability runs through Malaysian and Indonesian oleochemical supply channels exposed to climate volatility. Distribution runs through modern trade retail in developed markets and sachet-format traditional trade in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII expansion has erected a cost-of-compliance moat that advantages incumbent players with dedicated regulatory affairs infrastructure and amortized toxicology dossiers.
For Market Incumbents: Deploy captive fermentation technology access to differentiate premium positioning against private-label challengers. Accelerate acid-stable surfactant R&D to capture exfoliating variant demand ahead of polyethylene bead phase-out deadlines. Consolidate tier-2 Indian distribution through sachet-format partnerships before regional champions lock kirana channel access.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian tier-2 cities offers white-space entry through sachet-format foam cleansers distributed via modern trade partnerships. K-beauty cross-border e-commerce channels present underpenetrated gel-format opportunities for biotechnology-forward positioning. Bypass capital-intensive manufacturing by sourcing fermented actives from Busan-Ulsan suppliers under tolling arrangements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with REACH-compliant European plants and idle capacity in Polish or Romanian manufacturing zones. Fermentation technology specialists with validated postbiotic platforms command scarcity premiums in acquisition markets. Monitor NMPA animal-testing waiver application volumes as inflection signal for European and American brand entry acceleration into Chinese premium channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Supply | L'Oréal's controlled European raw-material sourcing compresses cost volatility exposure. |
| Fermentation Platform Scale-Up | Shiseido's Yokohama R&D center accelerates postbiotic active commercialization timelines. |
| Sachet-Format Distribution Expansion | Unilever's scalable gel and foam platforms penetrate Indian tier-2 modern trade channels. |
| Direct-to-Consumer Subscription Launch | Algorithmic skin-matching displaces traditional retail replenishment in Los Angeles and London. |
| REACH Compliance Repositioning | Biodegradable surfactant investment ahead of 2027 microplastic deadlines captures first-mover certification. |
Research Approach
Independent corroboration across formulation chemists, regulatory affairs directors at multinational beauty conglomerates, procurement leads at surfactant suppliers, and modern trade category buyers underwrites the qualitative findings. Primary interviews with R&D heads at Seoul and Tokyo innovation clusters, combined with secondary validation from ECHA substance evaluation databases, REACH Annex XVII compliance filings, and customs-derived oleochemical trade flows, anchored supply-side assessments. Bottom-up triangulation across product-format volume estimates and top-down reconciliation against disclosed segment revenues validated market sizing.
Rate-of-change decomposition across the analysis window disaggregated value expansion into volume growth, mix shift toward premium tiers, and raw-material cost pass-through effects. Segmentation modeling spanned product type, formulation certification grade, end-user demographic, and packaging format, with regional regulatory clusters treated as distinct demand environments. CAGRs were derived from fitted trend lines applied to validated baseline estimates, incorporating surfactant input cost trajectories and channel-shift elasticity parameters specific to direct-to-consumer adoption curves.
Inputs from ECHA enforcement timelines and NMPA waiver pathway announcements were available through the study window; gaps in real-time tier-2 Indian consumption data introduce uncertainty bands around sachet-format projections. Forecasts reflect documented assumptions regarding REACH compliance cost pass-through and K-beauty export momentum. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Foundation Cream Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Hand Cream Market