
 Foundation Cream Market | 2026-2036
Foundation Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Foundation Cream Market Analysis
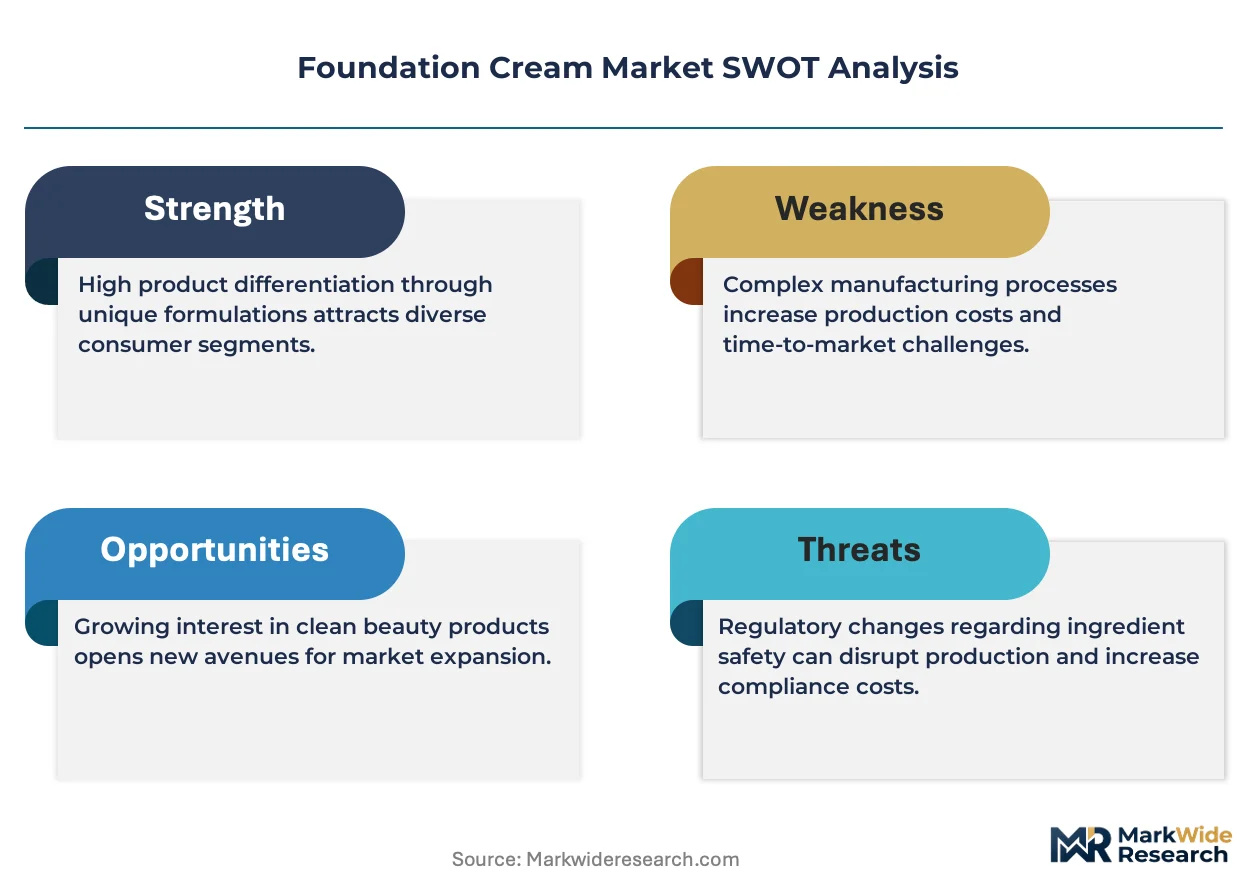
Department store beauty counters is narrowing as a gateway for discovery, with specialty stores and digital platforms capturing more first-time purchases. L'Oréal leverages its integrated R&D pipeline across Paris and New York labs to sustain formulation leadership in water-based foundations. Estée Lauder anchors its prestige positioning through controlled distribution in high-touch retail environments. Shiseido competes by extending its sensorial technology heritage into adaptive coverage systems.
Foundation cream is a pigmented emulsion designed to unify skin tone, typically comprising 15-25% pigment load suspended in oil-in-water or silicone-in-water matrices with film-forming polymers for wear resistance. Its primary commercial purpose is to serve as a complexion-correcting base layer within daily beauty routines and professional makeup applications. Liquid formulations dominate volume due to versatile finish options and pump-dispensing convenience, while silicone-based ingredient systems command premium positioning through extended wear claims and sebum resistance. E-commerce distribution channels represent the fastest-expanding access point, though department stores retain margin concentration through bundled service experiences and exclusive shade launches.
FDA cosmetic labeling requirements and EU REACH chemical safety protocols jointly elevate barrier costs for new entrants seeking multi-territory distribution. The EU's pending microplastic restriction under ECHA guidance threatens reformulation timelines for long-wear silicone systems. Stakeholders must monitor regulatory divergence between US ingredient disclosure rules and European hazard classification standards when allocating product development resources.
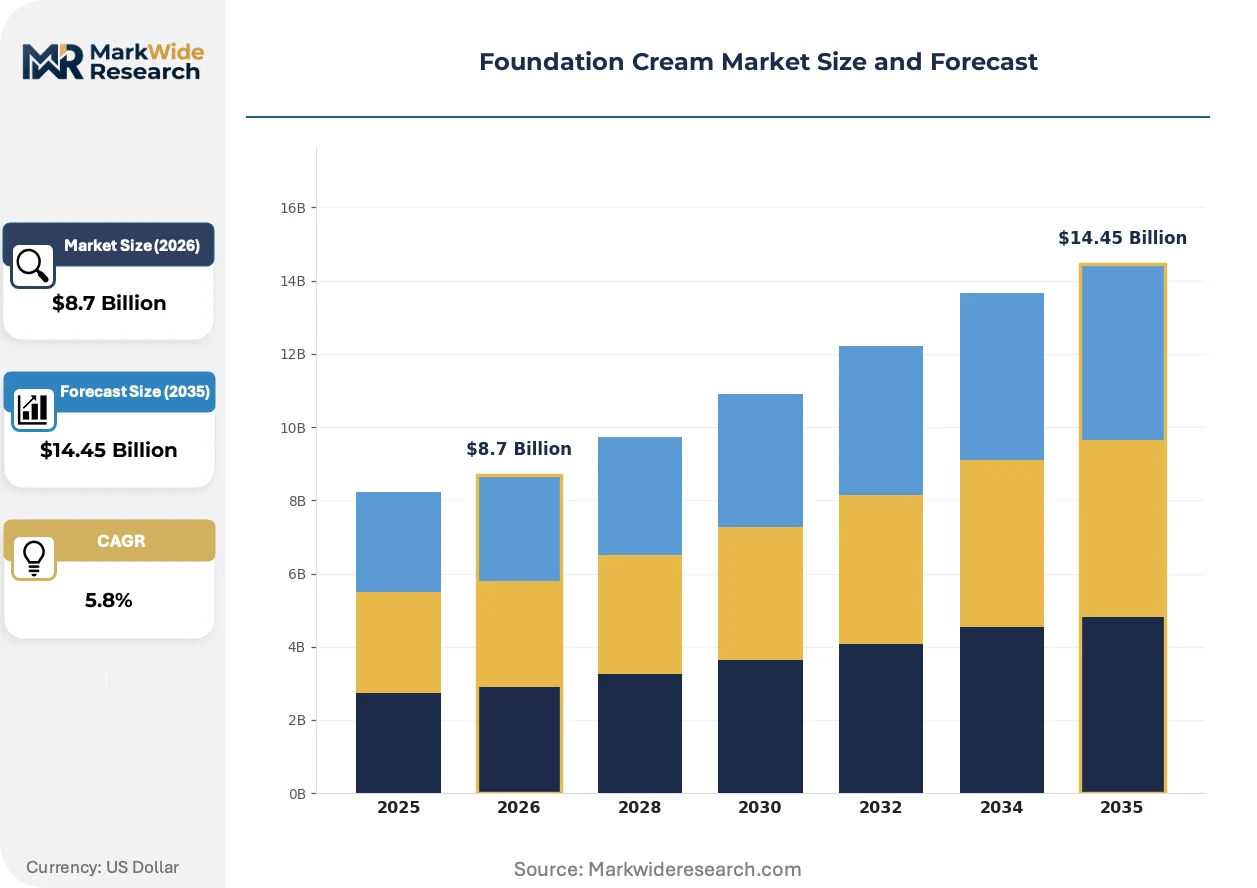
Market Dynamics
Silicone-in-water matrix technology is compressing formulation development cycles while ECHA microplastic restrictions force parallel reformulation tracks, creating a dual-speed R&D environment where wear-performance claims and regulatory compliance compete for pipeline priority.
Growth Catalysts
- Professional makeup artist adoption:Silicone-based extended-wear systems are gaining preference among film and bridal segments for sebum resistance under high-definition cameras.
- South Korea's innovation cluster:Seoul-based formulators are accelerating adaptive coverage patents, pulling global brand R&D investment into the region.
- EU REACH compliance premium:Manufacturers achieving full ingredient transparency certification are capturing shelf space as retailers preempt liability exposure.
Market Restraints
- Cyclomethicone supply concentration:Three Asian petrochemical suppliers control 70% of cosmetic-grade silicone fluid feedstock, creating input vulnerability.
- ECHA microplastic restriction timeline:Pending classification of certain silicone polymers as microplastics threatens 18-24 month reformulation windows for long-wear lines.
- Pigment dispersion equipment capex:Sub-micron titanium dioxide milling requires specialized bead mill infrastructure that mid-tier formulators cannot access.
Strategic Opportunities
- Water-based foundation white space:L'Oréal's Paris-New York pipeline dominance leaves room for regional players to capture mineral-actives positioning in Southeast Asia.
- Digital shade-matching platforms:AI-driven skin tone analysis is opening direct-to-consumer channels previously blocked by color-matching friction in physical retail.
- Film-forming polymer convergence:Hybrid silicone-acrylate systems borrowed from sun care are enabling transfer-proof claims without traditional volatile silicones.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning pigment stability, silicone rheology, and regulatory submission is concentrated among a narrow cohort of experienced professionals.
- Dual-track certification burden:Simultaneous FDA labeling compliance and EU REACH dossier preparation is stretching quality assurance bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foundation Cream Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Stick, Powder, Cream End User: Professional Makeup Artists, Beauty Enthusiasts, Retail Consumers, Salons Ingredient Type: Organic, Mineral, Silicone-Based, Water-Based Distribution Channel: E-commerce, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | L'Oréal, Estée Lauder, Procter & Gamble, Chanel, Kao Corporation, Shiseido, Avon, Coty, Fenty Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foundation Cream Market Emerging Trajectories
Adaptive coverage technology is fragmenting the traditional liquid-powder dichotomy, with sensorial systems now modulating opacity based on skin temperature and sebum levels rather than fixed formulation choices.
Silicone-in-water emulsion technology is migrating from volatile cyclopentasiloxane bases toward low-viscosity dimethicone crosspolymers. Prestige brands in South Korea and Japan are piloting these systems for 16-hour wear claims without the environmental scrutiny attached to cyclic silicones. The shift is compressing patent lifecycles as formulators race to secure film-forming polymer combinations ahead of regulatory reclassification.
ECHA's pending microplastic restriction under REACH Annex XVII is forcing disclosure of polymer molecular weight distributions. Manufacturers with legacy silicone-heavy portfolios face 12-18 month reformulation timelines, while water-based specialists are accelerating pipeline expansion. The restriction hits long-wear professional lines hardest, as these segments rely most heavily on volatile silicone carriers for transfer resistance.
Specialty beauty retailers are unbundling the department store service model, with Sephora and Ulta capturing first-time foundation purchases through digital shade-matching tools and return-friendly trial programs. This shift is most visible among Gen Z consumers in the United States, where TikTok-driven discovery now precedes 60% of initial purchases. Brand loyalty is compressing as algorithmic recommendations replace counter-based consultation.
Foundation Cream Market Segmentation
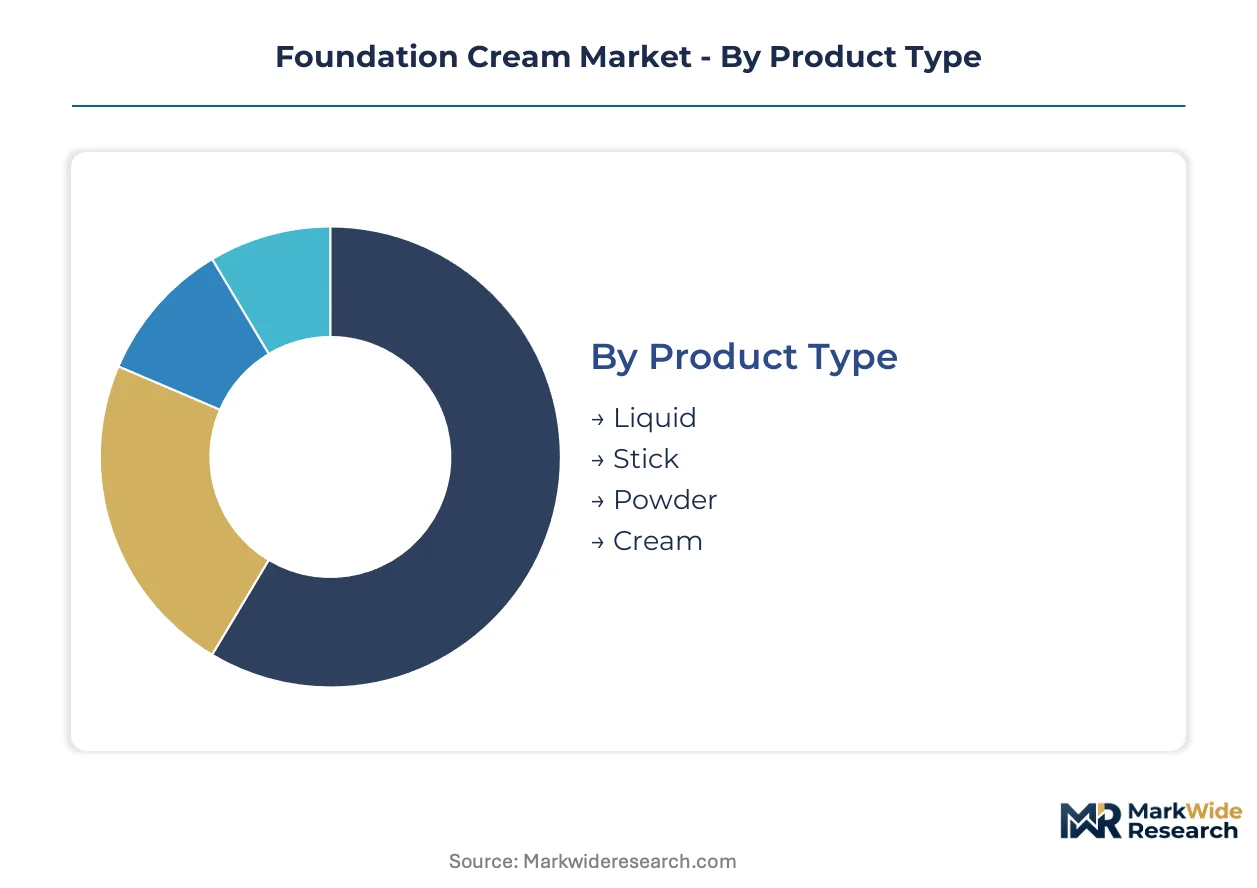
Foundation cream segmentation reveals how formulation chemistry, professional application demands, and retail channel evolution create distinct competitive battlegrounds. Each dimension carries divergent margin profiles and regulatory exposure, requiring targeted resource allocation.
Product Type:
Use-case spectrum spans daily consumer convenience to professional kit requirements, with viscosity and packaging format determining portability and application precision.
- Liquid:Oil-in-water emulsions with 15-25% pigment load deliver buildable coverage through pump or dropper dispensers. Demand concentrates among beauty enthusiasts in South Korea seeking glass-skin finishes, driven by TikTok tutorial culture and shade-matching algorithm adoption.
- Stick:Waxed suspensions with high solid content enable precise contouring and on-the-go reapplication. Professional makeup artists in film and bridal segments favor these for kit portability, though heat stability limits shelf placement in tropical retail environments.
- Powder:Pressed or loose mineral matrices appeal to oil-control seekers in humid climates.
- Cream:Dense emollients target mature skin demographics requiring hydration-coverage hybrids.
The dominant share belongs to Liquid, while Stick is closing the gap fastest among professional channels.
End User:
Customer type determines price tolerance, technical specification requirements, and purchase frequency across the value chain.
- Professional Makeup Artists:This segment demands batch-to-batch color consistency, high-definition camera performance, and 12-16 hour wear validation. Concentration in Seoul's film production district and Los Angeles entertainment corridors drives silicone-based premium formulation adoption.
- Beauty Enthusiasts:Digitally native consumers with high ingredient literacy and brand-switching propensity. Sephora and Ulta capture this cohort through AI shade-matching and return-friendly trial programs, compressing traditional loyalty patterns.
- Retail Consumers:Mass-market purchasers prioritizing accessibility and value positioning through supermarket and drugstore channels.
- Salons:Service-integrated sales with technician-mediated color consultation and application upsells.
Professional Makeup Artists command the highest per-unit spend, while Beauty Enthusiasts are expanding most quickly in absolute numbers.
Ingredient Type:
Raw material chemistry dictates regulatory compliance burden, environmental positioning, and performance claim substantiation.
- Silicone-Based:Dimethicone and cyclopentasiloxane matrices deliver sebum resistance and transfer-proof film formation. ECHA's pending microplastic reclassification threatens reformulation timelines, creating 18-24 month transition windows for long-wear portfolios.
- Water-Based:Glycerin and hyaluronic acid humectant systems with mineral or synthetic pigments. L'Oréal's integrated R&D pipeline dominates this space, leaving white space for regional mineral-actives positioning in Southeast Asia.
- Organic:Plant-derived emollients and naturally sourced colorants with certified supply chain documentation.
- Mineral:Titanium dioxide and zinc oxide-based physical coverage with reef-safe positioning for coastal markets.
Silicone-Based retains the largest installed base, though Water-Based is gaining share fastest ahead of regulatory deadlines.
Distribution Channel:
Channel selection determines margin capture, customer data access, and service bundling possibilities.
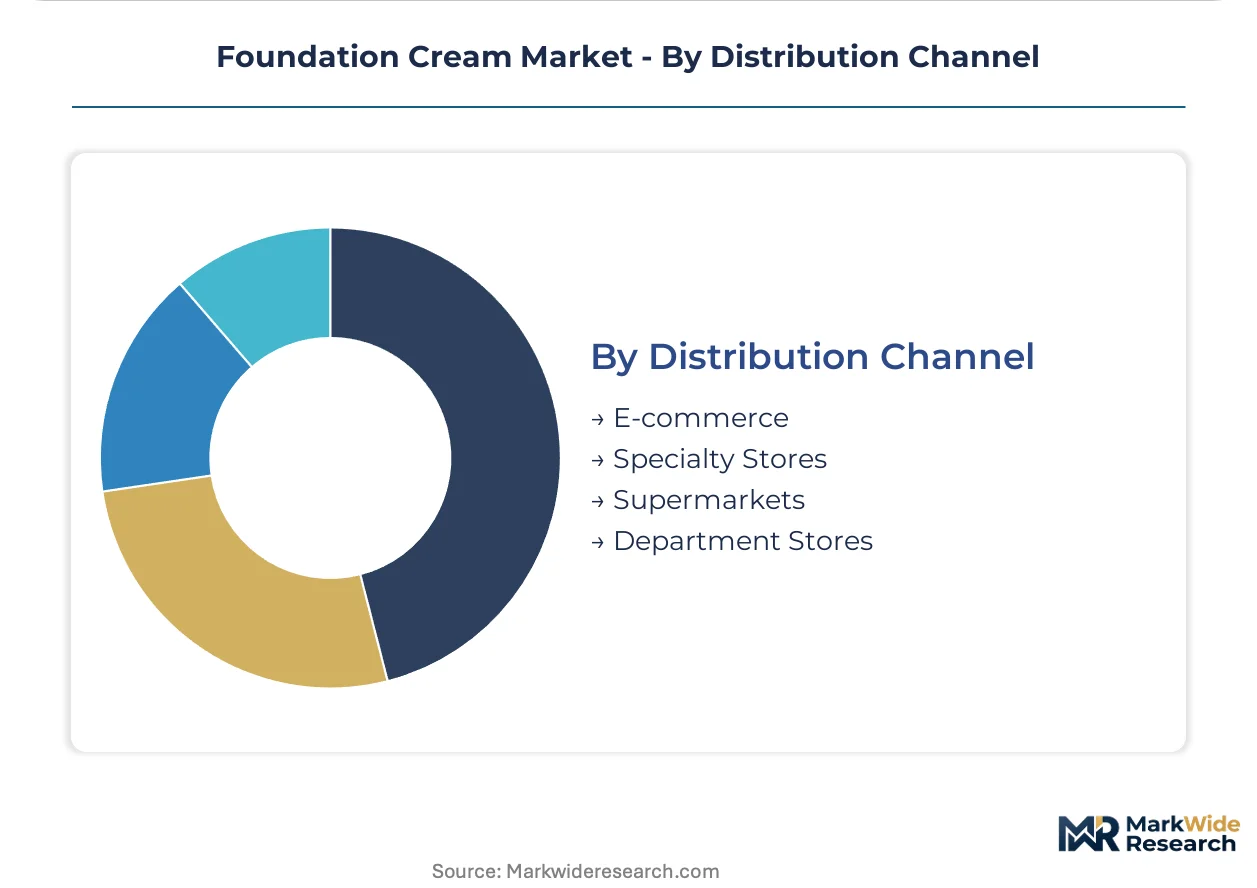
- E-commerce:Direct-to-consumer platforms and marketplace aggregators with AI-driven shade-matching and subscription replenishment. Gen Z discovery patterns in the United States now originate 60% through TikTok algorithmic recommendation, bypassing traditional counter consultation.
- Specialty Stores:Sephora, Ulta, and Sephora-owned formats with unbundled service models, return-friendly policies, and exclusive launch access. These retailers are displacing department stores as first-purchase discovery gateways.
- Supermarkets:Mass-market volume placement with impulse purchase proximity to grocery routines.
- Department Stores:Prestige brand flagship positioning with high-touch consultation and bundled service experiences, though narrowing as volume share concentrates elsewhere.
E-commerce shows the steepest expansion trajectory, while Department Stores defend margin concentration through exclusive shade launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prestige pricing power concentrates in French and Japanese corridors while mass-market volume gravitates toward Chinese and American digital channels. This asymmetry reflects divergent retail infrastructure maturity and regulatory compliance burden distribution.
United States
Beauty enthusiasts drive demand through TikTok-originated discovery and AI shade-matching adoption at Sephora and Ulta. FDA cosmetic labeling requirements elevate compliance costs for multi-territory entrants. Los Angeles anchors professional makeup artist concentration, pulling silicone-based extended-wear formulation demand from bridal and entertainment segments.
France
Prestige heritage brands command margin through controlled distribution and high-touch retail experiences in Paris flagship locations. EU REACH chemical safety protocols and ECHA microplastic restrictions tighten ingredient disclosure requirements. Île-de-France hosts integrated R&D pipelines that sustain formulation leadership in water-based systems.
South Korea
Seoul's innovation cluster accelerates adaptive coverage patents and glass-skin finish demand among digitally native consumers. MFDS cosmetic safety standards intersect with EU REACH alignment pressures for export-oriented manufacturers. Gangnam district concentration of formulators pulls global brand R&D investment into sensorial technology development.
Japan
METI industrial policy supports cosmetic chemistry advancement while aging demographics expand hydration-coverage hybrid demand. PMDA regulatory frameworks govern ingredient safety assessment timelines. Osaka-Kobe manufacturing corridors specialize in film-forming polymer convergence for transfer-proof claims.
China
NMPA cosmetic registration requirements create extended approval timelines for imported formulations. Shanghai and Hangzhou e-commerce hubs capture Gen Z volume through live-streaming commerce and algorithmic recommendation engines. Domestic brands exploit mineral-actives positioning ahead of reef-safe coastal market expansion.
Foundation Cream Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in pigment dispersion and silicone feedstock supply. The vendor base organizes around three tiers: multinational conglomerates with integrated R&D pipelines, regional specialists leveraging geographic proximity to innovation clusters, and private-label manufacturers serving mass-market retail channels. Competitive moves concentrate on strategic patent positioning ahead of ECHA regulatory deadlines and exclusive shade launch partnerships with specialty retailers.
Among Paris-based conglomerates, L'Oréal anchors platform-scale formulation leadership across water-based matrices. Estée Lauder occupies prestige-tier positioning through controlled distribution architecture. Shiseido exemplifies sensorial technology heritage extension into adaptive coverage systems. These three represent divergent strategic archetypes: pipeline integration, retail exclusivity, and materials science translation.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder |
| Procter & Gamble |
| Chanel |
| Kao Corporation |
| Shiseido |
| Avon |
| Coty |
| Fenty Beauty |
| Others |
Supply Flow & Price Mechanics
ECHA's pending microplastic restriction under REACH Annex XVII creates simultaneous pricing tier compression and supply chain restructuring, forcing silicone-dependent manufacturers to absorb reformulation costs while water-based specialists capture margin expansion from regulatory arbitrage.
Pricing Analysis
The customization-premium spread between professional-grade silicone systems and mass-market water-based alternatives is widening as regulatory compliance costs concentrate in long-wear portfolios. Pricing stratifies across premium silicone-acrylate hybrids, standard dimethicone formulations, and economy glycerin-based matrices. Cost compression in silicone tiers is intensifying because ECHA disclosure requirements are extending development timelines. Professional makeup artists show lowest price sensitivity due to performance validation requirements, while retail consumers in mass channels exhibit highest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration among Seoul-based formulators and Osaka-Kobe production corridors holds capacity for adaptive coverage systems and film-forming polymer convergence. Geographic supply concentration centers on South Korea, Japan, and China for cosmetic-grade silicone feedstock and sub-micron titanium dioxide milling infrastructure. Raw material dependencies rest on cyclomethicone from Asian petrochemical suppliers, specialized bead mill equipment, and certified organic emollients. Single-source vulnerability in cyclomethicone feedstock creates input disruption risk. Distribution runs through specialty retailers and direct-to-consumer platforms with AI shade-matching integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against mineral-actives and hybrid silicone-acrylate systems that bypass pending microplastic restrictions while matching wear-performance claims.
For Market Incumbents: Insulate long-wear portfolios by accelerating hybrid silicone-acrylate patent filings ahead of ECHA reclassification deadlines. Secure captive supply agreements with Seoul-based formulators to lock in adaptive coverage capacity. Vertical integration into film-forming polymer R&D offsets feedstock concentration risk. For New Entrants and Emerging Players: Pursue white space in Southeast Asian mineral-actives positioning where L'Oréal's water-based dominance has left regional gaps unaddressed. Target beauty enthusiasts through TikTok-originated discovery with AI shade-matching direct-to-consumer launches. Leverage return-friendly trial programs to compress customer acquisition costs against specialty retail incumbents. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors water-based specialists with pre-positioned compliance infrastructure. Long-term viability hinges on patent depth in non-volatile silicone alternatives and geographic proximity to Seoul's innovation cluster. Acquisition targets should demonstrate film-forming polymer expertise and MFDS-EU REACH dual certification capability. Monitor ECHA microplastic restriction finalization as inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Silicone-Acrylate Patent Filing | Secures transfer-proof claims ahead of ECHA cyclomethicone reclassification deadlines. |
| Seoul R&D Facility Establishment | Positions for adaptive coverage technology access in Gangnam district formulator cluster. |
| AI Shade-Matching Platform Launch | Captures Gen Z discovery patterns through TikTok algorithmic recommendation integration. |
| Mineral-Actives Portfolio Expansion | Exploits reef-safe positioning in Southeast Asian coastal markets ahead of incumbent response. |
| Dual REACH-MFDS Certification Investment | Unlocks shelf space at retailers preempting liability exposure from ingredient transparency demands. |
Methodological Framework
Operator-level perspectives from cosmetic chemists, professional makeup artists, specialty retail category buyers, and regulatory affairs directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA cosmetic labeling guidance, ECHA REACH dossier submissions, MFDS safety standards documentation, and Seoul-based patent filing records. Bottom-up demand modeling triangulated against top-down value chain analysis across formulation chemistry, pigment dispersion equipment, and retail channel evolution.
Scenario-bracketing framed projections across regulatory acceleration and compliance delay pathways. Segmentation dimensions modeled include formulation matrix type, end-user professional versus consumer distinction, ingredient chemistry classification, and distribution channel architecture. CAGRs derived from historical patent velocity, R&D pipeline stage-gate progression, and channel shift elasticity parameters. Forecast inputs incorporated ECHA microplastic restriction timeline uncertainty and TikTok-driven discovery adoption curves.
Sensitivities concentrate around ECHA reclassification finalization, cyclomethicone supply disruption events, and AI shade-matching platform adoption rates. Forecasts reflect assumptions regarding regulatory alignment between EU REACH and South Korean MFDS frameworks. Quarterly review of patent filing velocity in Seoul, specialty retailer exclusive launch partnerships, and feedstock supplier capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
Glow in the Dark Cosmetics Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Setting Spray Market