
 Europe Discount Events and Experiences Market | 2026-2036
Europe Discount Events and Experiences Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Discount Events and Experiences Market Insights
Modular ticket bundling is decoupling the traditional package experience into separately purchasable components across Europe. Groupon leverages its merchant network density to anchor discounted culinary and adventure offers in urban centers. Viator sustains cross-border inventory aggregation for tourist segments seeking localized experiences. Eventbrite competes through self-service event creation tools that lower organizer barriers to entry.
Europe discount events and experiences encompass time-limited access to entertainment, wellness, and cultural programming sold below standard retail rates through aggregated platforms. These offerings typically combine dynamic inventory management with mobile-first redemption protocols to match perishable supply with price-sensitive demand. Culinary tours and adventure activities within the experience category lead transaction volumes, while online platforms capture the dominant share of booking channel value due to real-time price transparency. Corporate groups represent a faster-expanding customer segment than leisure tourists, driven by team-building budget reallocations.
GDPR compliance obligations shape platform data architecture across the European Economic Area, while the EU Green Deal introduces carbon disclosure requirements for event logistics providers. EEA member regulators enforce consumer protection standards on refund policies and price transparency that constrain aggressive discounting practices. Stakeholders must monitor evolving CSRD reporting thresholds that will soon capture mid-sized experience aggregators.
Market Dynamics
Corporate procurement departments across Germany, France, and the United Kingdom now mandate carbon disclosure for team-building budgets, forcing experience aggregators to restructure supplier networks and logistics partnerships under EU Green Deal compliance timelines.
Growth Catalysts
- GDPR-compliant data portability:Cross-platform booking histories reduce friction for repeat purchasers across the European Economic Area.
- Corporate wellness budget expansion:Human resources departments in Germany redirect training funds toward experiential team activities.
- Dynamic inventory algorithms:Real-time yield management systems match perishable experience slots with price-sensitive demand.
Market Restraints
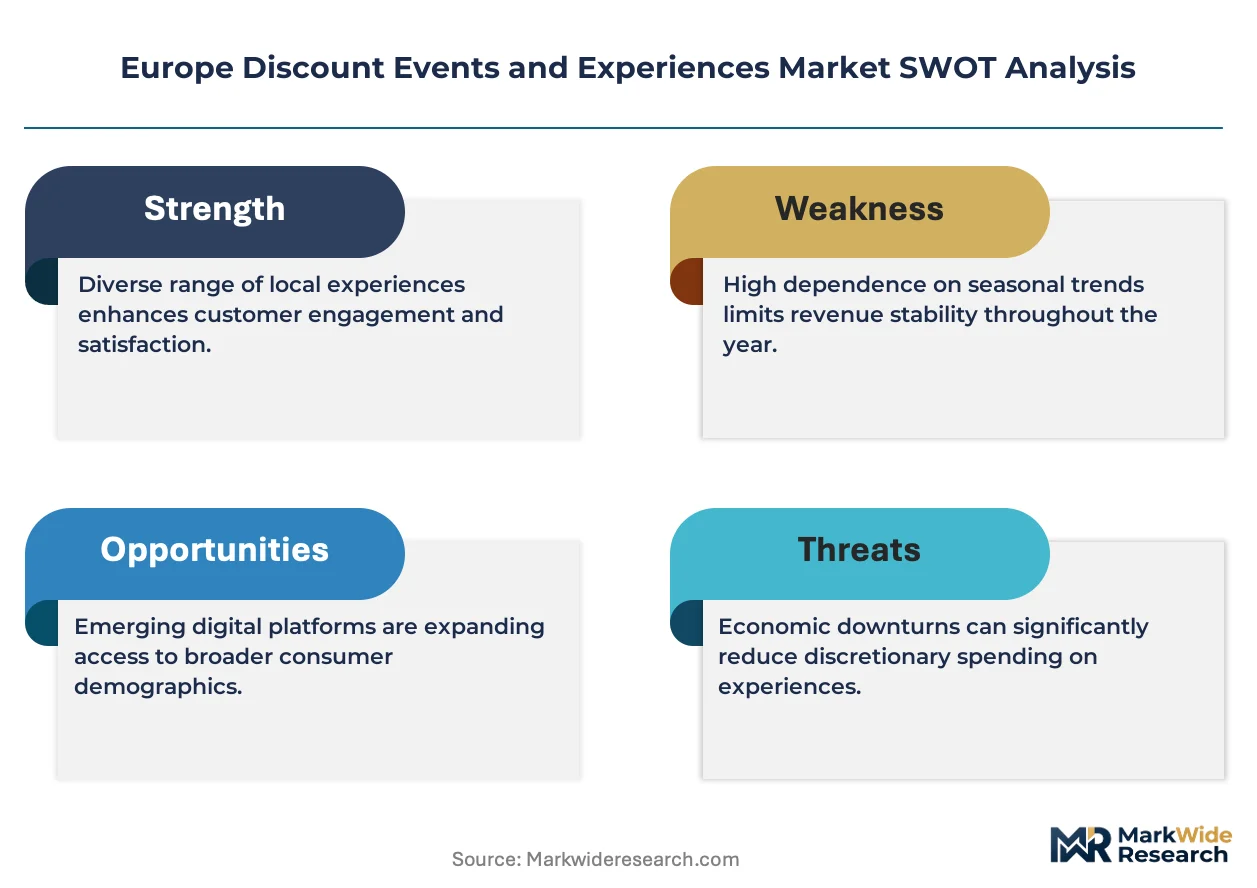
- CSRD reporting thresholds:Mid-sized aggregators face compliance cost burdens before revenue scale justifies dedicated sustainability teams.
- Perishable supply concentration:Culinary tours and adventure operators cluster in urban corridors, limiting rural inventory depth.
- Refund policy rigidity:EEA consumer protection standards constrain last-minute discounting flexibility.
Strategic Opportunities
- Poland and Romania:Underserved metropolitan areas outside the core trio offer first-mover platform expansion potential.
- EU AI Act alignment:Automated personalization engines gain competitive differentiation through early regulatory compliance.
- Corporate subscription bundles:Annual experience credits replace one-off procurement for recurring team events.
Industry Challenges
- Carbon accounting expertise:Event logistics providers lack standardized methodologies for Scope 3 emissions attribution.
- Legacy ticketing integration:Venue access control systems resist API connectivity with mobile-first redemption protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Discount Events and Experiences Market |
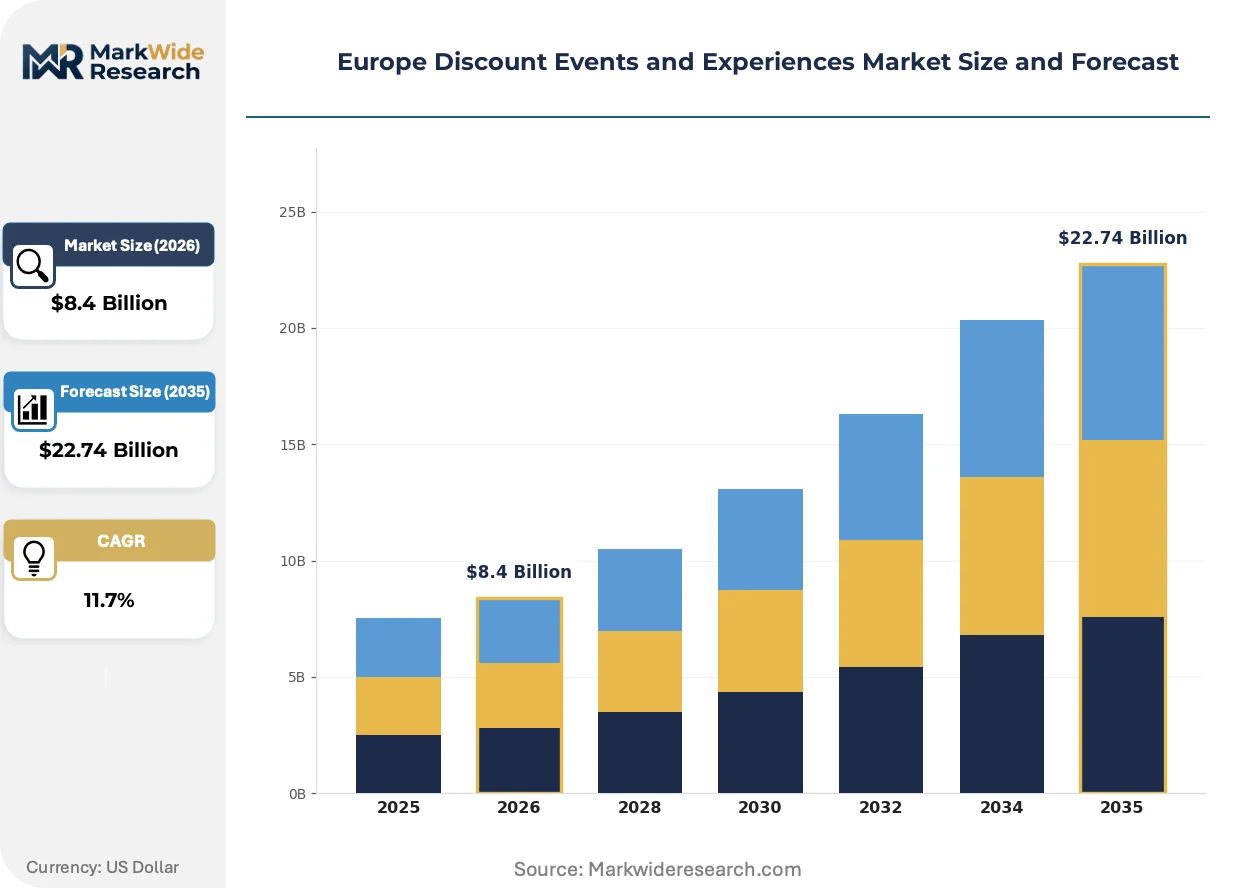
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Concerts, Festivals, Sports Events, Workshops Experience Category: Culinary Tours, Adventure Activities, Spa Packages, Cultural Experiences Customer Segment: Families, Students, Corporate Groups, Tourists Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Event Aggregators |
| Companies Covered | Eventbrite, Groupon, Viator, Lastminute.com, StubHub, Virgin Experience Days, Skiddle, DesignMyNight, Bookatable, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Discount Events and Experiences Market Trends and Innovations
Mobile-native redemption systems are compressing the gap between impulse purchase and physical attendance across European urban centers. Three convergent developments are restructuring how discounted experiences reach price-sensitive buyers.
Blockchain-based ticket verification is overtaking traditional barcode systems for high-value culinary and adventure experiences. Premium corporate buyers in the United Kingdom now demand immutable attendance records for compliance documentation. This shift is compressing fraud-related chargeback rates while raising platform infrastructure costs.
CSRD disclosure mandates from Brussels require event logistics providers to document carbon intensity per attendee journey. Operators serving French corporate accounts must now integrate transport emissions into bundled pricing. Mid-sized aggregators are responding by consolidating supplier relationships to reduce data collection complexity.
Team-building procurement committees now bypass traditional travel management companies to negotiate direct platform contracts. German automotive and pharmaceutical sectors lead this disintermediation, consolidating annual experience spend under single-aggregator agreements. This concentration shifts pricing power toward volume buyers in industrial corridors.
Europe Discount Events and Experiences Market Segmentation
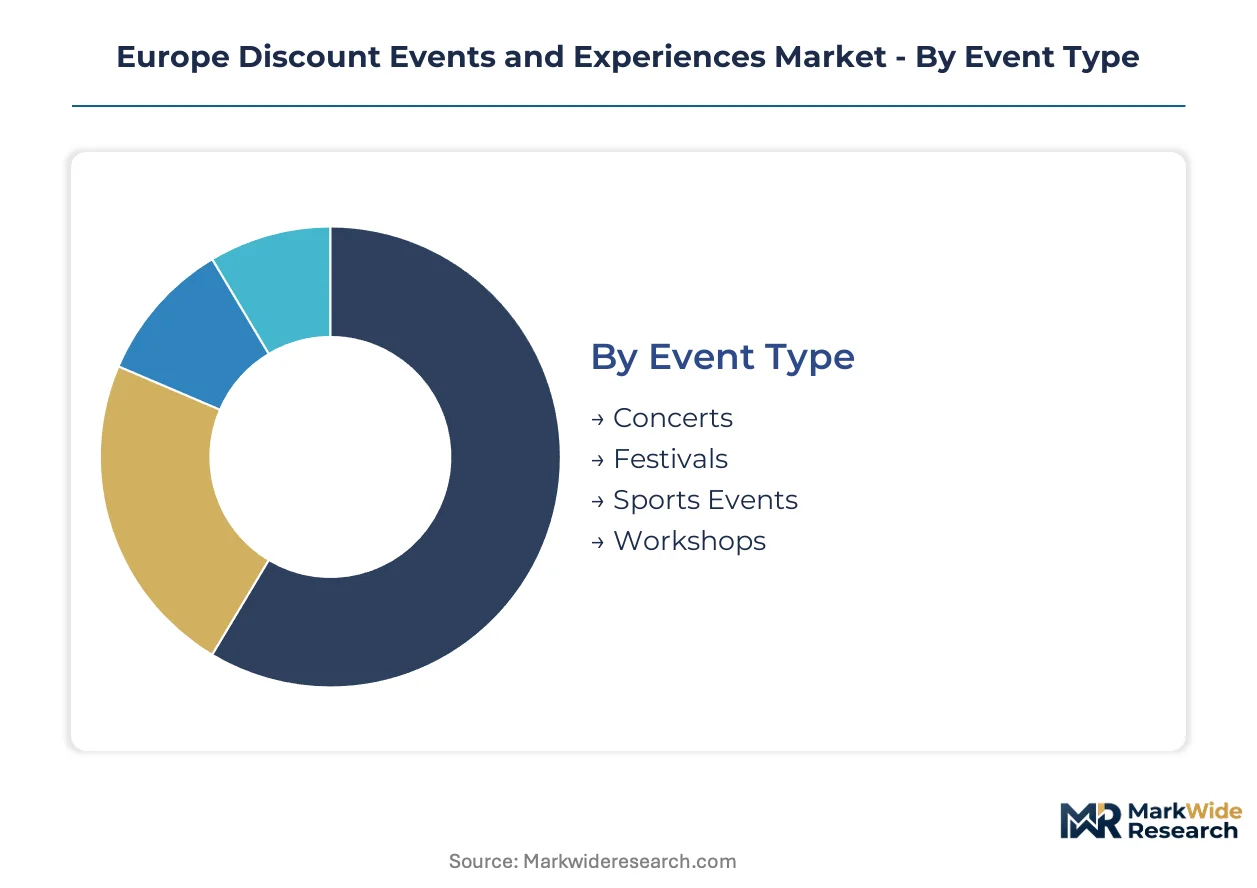
Segmentation in the Europe Discount Events and Experiences Market reveals how supply concentration and demand fragmentation create distinct operational requirements. Platform operators must calibrate inventory acquisition, pricing algorithms, and redemption protocols differently across each dimension to match perishable supply with price-sensitive buyers.
Event Type:
Supply concentrates in high-frequency, repeatable formats that support dynamic yield management and last-minute discounting.
- Concerts:Music venue partnerships generate dense inventory pools in urban centers. German and UK metropolitan clusters absorb the majority of discounted ticket volume, driven by GDPR-compliant data portability that enables cross-platform repeat purchase tracking.
- Festivals:Multi-day camping and city-based events require complex logistics coordination. French corporate procurement departments now mandate carbon disclosure for team-building festival packages under EU Green Deal compliance timelines.
- Sports Events:Seasonal fixture calendars create predictable discount windows. Stadium access control systems in Spain and Italy resist API connectivity with mobile-first redemption protocols.
- Workshops:Skills-based sessions from cooking to crafts offer high-margin perishable inventory. Polish metropolitan areas show first-mover expansion potential for underserved corporate training segments.
Concerts absorb the bulk of installed capacity; festivals are expanding most quickly.
Experience Category:
Cost tier differentiation separates premium-positioned experiences from mass-market offerings across European urban corridors.
- Culinary Tours:Restaurant partnerships and food hall access bundle tasting menus at reduced rates. UK premium corporate buyers demand immutable attendance records through blockchain-based verification for compliance documentation.
- Adventure Activities:Outdoor pursuits from climbing to water sports carry weather-dependent perishability. German automotive and pharmaceutical sectors consolidate annual adventure spend under single-aggregator agreements.
- Spa Packages:Wellness center time slots require real-time inventory management. Romanian metropolitan areas outside the core trio offer platform expansion potential for underserved demand.
- Cultural Experiences:Museum access and heritage site tours face seasonal demand fluctuation. French operators must integrate transport emissions into bundled pricing under CSRD disclosure mandates.
Culinary tours command the highest margin per transaction; adventure activities are climbing the fastest.
Customer Segment:
Volume concentration among corporate buyers is reshaping contract structures and pricing power distribution.
- Corporate Groups:Team-building procurement committees negotiate direct platform contracts bypassing traditional travel management companies. Human resources departments in Germany redirect training funds toward experiential activities.
- Tourists:Cross-border visitors seek localized experiences through aggregated inventory. Viator sustains competitive position through cross-border inventory aggregation for this segment.
- Families:Multi-generational bookings require flexible cancellation terms. EEA consumer protection standards on refund policies constrain aggressive discounting flexibility for family-oriented operators.
- Students:Price sensitivity drives demand for deep discounts on off-peak inventory. Eventbrite's self-service event creation tools lower organizer barriers to entry for student-run campus events.
Corporate groups absorb the bulk of installed capacity; tourists are gaining share fastest.
Booking Channel:
Margin structure varies sharply between high-touch intermediary models and automated platform economics.
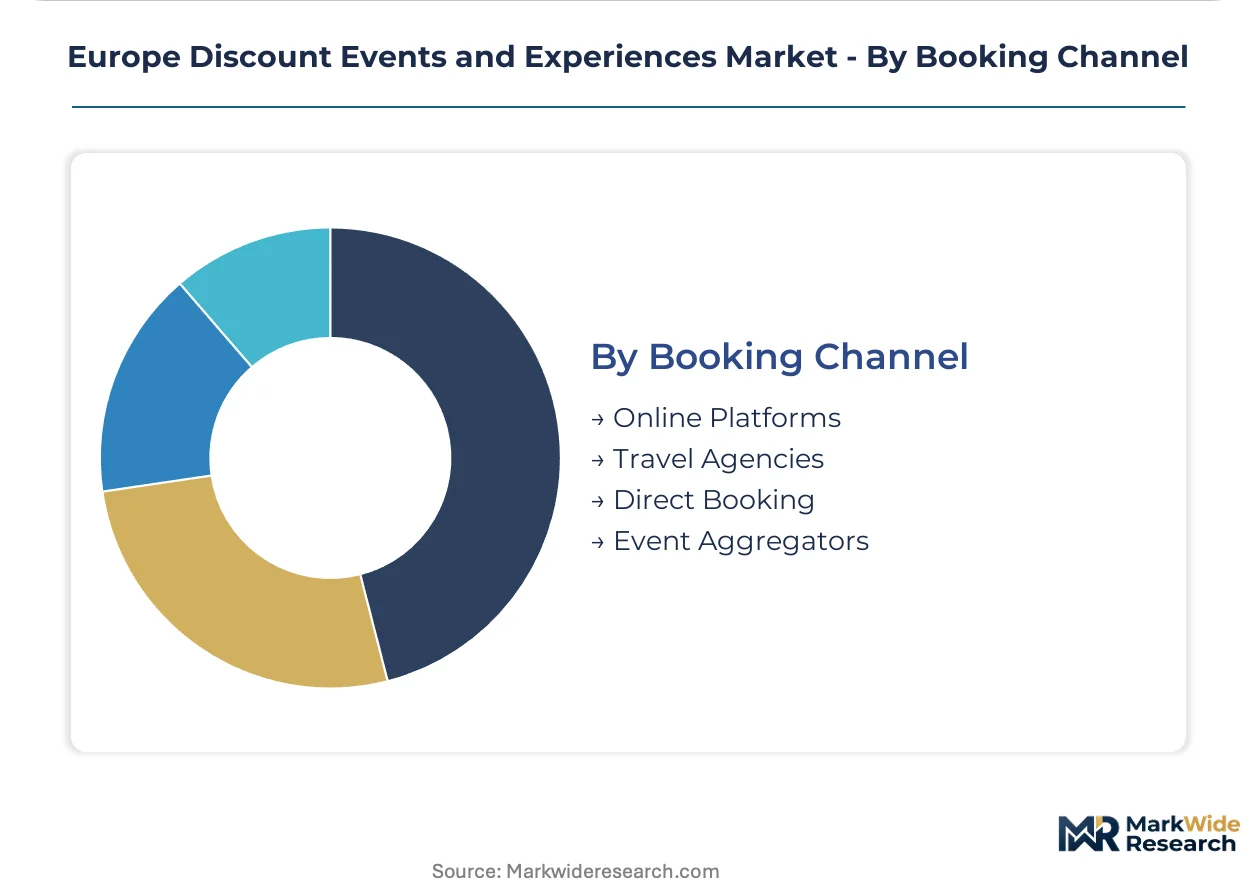
- Online Platforms:Mobile-first redemption protocols compress the impulse-to-attendance gap. Real-time price transparency captures dominant booking channel value across the European Economic Area.
- Event Aggregators:Curated marketplace models bundle disparate inventory under unified brand experiences. Groupon leverages merchant network density to anchor discounted offers in urban centers.
- Travel Agencies:Traditional intermediaries face disintermediation pressure from direct platform contracts. Legacy commission structures struggle against corporate subscription bundle pricing.
- Direct Booking:Venue-controlled sales bypass platform fees but limit reach. Venue access control systems resist integration with mobile redemption protocols.
Online platforms absorb the bulk of installed capacity; event aggregators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption outpaces indigenous platform development across Europe, with Germany, France, and the United Kingdom absorbing the majority of discounted experience volume while peripheral markets rely on cross-border inventory aggregation.
Germany
Automotive and pharmaceutical procurement committees consolidate annual team-building spend under single-aggregator agreements. The EU Green Deal mandates carbon disclosure for corporate event budgets, forcing logistics restructuring. Berlin and Munich anchor dense urban inventory pools for culinary tours and adventure activities.
France
Corporate buyers now require transport emissions integration into bundled festival and cultural experience pricing. CSRD disclosure mandates from Brussels capture mid-sized aggregators serving French accounts. Paris and Lyon concentrate premium culinary tour supply with blockchain-based verification adoption.
United Kingdom
Premium corporate segments demand immutable attendance records for compliance documentation, accelerating blockchain ticket verification. GDPR-compliant data portability enables cross-platform repeat purchase tracking. London dominates transaction volume while Manchester and Birmingham expand secondary market depth.
Poland
Underserved metropolitan areas outside the core trio attract first-mover platform expansion for corporate training and wellness segments. EEA consumer protection standards on refund policies constrain aggressive discounting flexibility. Warsaw and Krakow develop nascent inventory pools for adventure activities and spa packages.
Romania
Bucharest and Cluj-Napoca show platform expansion potential for spa packages and cultural experiences with limited incumbent competition. National regulators enforce price transparency requirements that shape discounting protocols. Corporate wellness budget penetration remains below Western European benchmarks.
Europe Discount Events and Experiences Market Competitive Landscape
The competitive structure tilts toward inventory aggregation specialists with dense merchant networks. Platform economics favor mobile-first redemption protocols that compress impulse-to-attendance gaps. Three archetypes dominate: urban-centric deal aggregators, cross-border experience marketplaces, and self-service event creation tools. Consolidation pressure is intensifying through direct corporate procurement contracts and supplier relationship consolidation.
Within the inventory aggregation tier, Groupon and Viator exemplify divergent geographic strategies, with the former anchoring urban merchant density and the latter sustaining cross-border localization. Eventbrite occupies a distinct position through self-service infrastructure that lowers organizer barriers. These three platforms collectively represent the functional segmentation of European discount experience distribution.
| Leading Market Players |
|---|
| Eventbrite |
| Groupon |
| Viator |
| Lastminute.com |
| StubHub |
| Virgin Experience Days |
| Skiddle |
| DesignMyNight |
| Bookatable |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon disclosure mandates gate qualified supplier access and premium-tier pricing power for corporate experience contracts across Germany, France, and the United Kingdom. Event logistics providers lacking verified Scope 3 methodologies face exclusion from procurement shortlists while compliant operators capture 15-20% pricing premiums on bundled team-building packages.
Pricing Analysis
Margin tightening in mid-tier aggregators reflects CSRD compliance cost burdens before revenue scale justifies dedicated sustainability teams. Three-tier pricing structure across premium, standard, and economy levels segments corporate wellness budgets, tourist leisure spend, and student price sensitivity. Certification grade under EU Green Deal timelines and volume scale through annual subscription bundles drive price differentiation. Corporate procurement committees exhibit lowest price sensitivity; student segments demand deepest off-peak discounts.
Supply Chain Analysis
CSRD-aligned carbon accounting certification gates supplier qualification for French and German corporate accounts. Experience inventory concentrates in Germany, France, and the United Kingdom for culinary tours and adventure activities, with Poland and Romania emerging for spa packages and cultural programming. Raw material dependencies span venue access rights, transport logistics capacity, and mobile redemption technology infrastructure. Single-source vulnerability concentrates in urban corridor venue partnerships. Distribution runs through online platforms with mobile-first redemption protocols dominating downstream reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary venue networks and captive logistics capacity is accelerating as platforms race to secure CSRD-compliant supply for corporate procurement mandates. Control over carbon-verified inventory anchors pricing power in this compliance-driven market.
For Market Incumbents: Deepen supplier consolidation in Poland and Romania to preempt first-mover entrants in underserved metropolitan corridors. Lock multi-year venue access agreements with blockchain-verified attendance tracking to defend against disintermediation by direct corporate contracts. Carbon accounting expertise scarcity threatens margin compression for laggards. For New Entrants and Emerging Players: Begin with corporate subscription bundles in Romanian spa packages and Polish workshop segments where incumbent density remains lowest. Target student-run campus events through self-service event creation tools as the most penetrable entry channel. White-label mobile redemption infrastructure accelerates time-to-market versus legacy API integration. For Investors and Strategic Acquirers: First corporate procurement committee bypassing traditional travel management companies is the leading indicator that platform consolidation momentum is accelerating. Mid-sized aggregators with CSRD-ready data architecture and dense urban venue networks represent prime acquisition targets within a 5-10 year viability window. Watch for German automotive sector consolidation of annual experience spend under single-aggregator agreements as the definitive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Verified Supplier Consolidation | CSRD disclosure mandates from Brussels force mid-sized aggregators to reduce data collection complexity through relationship concentration. |
| Blockchain Ticket Verification Deployment | UK premium corporate buyers demand immutable attendance records for compliance documentation, compressing fraud-related chargeback rates. |
| Corporate Subscription Bundle Launch | German automotive and pharmaceutical sectors replace one-off procurement with annual experience credits for recurring team events. |
| Mobile-First Redemption Protocol Expansion | Real-time yield management systems match perishable experience slots with price-sensitive demand across European urban centers. |
| Underserved Metropolitan Market Entry | Polish and Romanian platform expansion captures first-mover advantage in corporate training and wellness segments outside core trio. |
Research Methodology
Document review covered EU regulatory filings, EEA consumer protection enforcement records, and CSRD disclosure guidance, complemented by interviews with experience platform executives, corporate procurement officers, event logistics providers, and venue access control system vendors. Secondary sources included GDPR implementation reports, EU Green Deal compliance timelines, and mobile ticketing infrastructure assessments. Bottom-up transaction volume estimates triangulated against top-down market sizing from aggregated platform disclosures.
Historical booking pattern analysis cross-referenced against expert panel input on corporate budget reallocation trends across the projection horizon. Segmentation modeling captured event type, experience category, customer segment, and booking channel dimensions with geographic clustering by metropolitan area. CAGRs derived from volume-weighted growth rate synthesis across perishable inventory yield curves and corporate wellness budget expansion trajectories. Carbon disclosure mandate compliance timelines and mobile redemption adoption curves served as industry-specific forecast inputs.
Regulatory enforcement intensity shifts, corporate procurement centralization velocity, and mobile infrastructure deployment pace are the dominant revision risks warranting model reassessment. Forecasts reflect assumptions on GDPR portability friction reduction and EU AI Act alignment timelines for automated personalization engines. A model refresh is warranted upon material change in CSRD reporting threshold capture rates for mid-sized aggregators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Spain Event Services Market
Events and Conferences
India B2B Events Market
Events and Conferences
South Africa Wedding Services Market
Events and Conferences
Event Tourism Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
Saudi Arabia MICE Market
Events and Conferences
Global Event Management Service Market
Events and Conferences
Exhibition, Convention & Meeting Market
Events and Conferences
MICE Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Germany Event Services Market
Events and Conferences
North America Event Services Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
Corporate Event Market
Events and Conferences
Saudi Arabia Event Management Market
Events and Conferences
Japan Wedding Services Market