
 Global Perfume Ingredients Chemicals Market | 2026-2036
Global Perfume Ingredients Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perfume Ingredients Chemicals Market Foresight
The fine fragrance sector is pivoting toward sustainable and biodegradable aroma molecules as luxury consumers scrutinize ingredient provenance. Givaudan leverages captive botanical sourcing and biotechnology platforms to secure rare raw materials. Firmenich anchors its position through enzymatic synthesis capabilities that reduce solvent waste. Symrise competes by dominating the natural-identical molecule segment with fermentation-derived alternatives.
Perfume ingredients chemicals encompass synthetic aroma molecules, essential oil isolates, and natural extracts formulated at precise concentrations to achieve olfactory stability and skin safety. These compounds typically require purity grades exceeding 98 percent and must withstand pH variations between 3 and 8 in final cosmetic matrices. Terpenes and esters command the largest volume share among product types, though aldehydes generate disproportionate margin pools due to complexity in controlled oxidation synthesis. Application demand fragments across fragrance manufacturing and personal care products, with household products representing a maturing but high-throughput outlet for standard-grade alcohols and ketones.
REACH in Europe, IFRA standards, and FDA fragrance allergen labeling rules collectively tighten disclosure obligations and restrict certain polycyclic musks and phthalate-based fixatives. EMA and EPA frameworks increasingly scrutinize synthetic musk bioaccumulation, pushing formulators toward macrocyclic replacements. Stakeholders must monitor regulatory divergence between Brussels and Washington on fragrance ingredient transparency mandates.
Market Dynamics
Biotechnology-derived aroma molecules are restructuring supply economics as enzymatic synthesis routes slash solvent volumes and unlock captive access to rare botanical precursors previously constrained by harvest volatility.
Growth Catalysts
- REACH substance restrictions:European phasedowns of polycyclic musks and phthalate fixatives force formulators toward macrocyclic and biodegradable alternatives, expanding addressable demand for compliant specialty molecules.
- India's PLI scheme for specialty chemicals:Production-linked incentives attract fermentation-based aroma chemical investments, converting the country from importer to regional supplier for Asia-Pacific fragrance houses.
- Clean beauty certification proliferation:EWG Verified and COSMOS standards in personal care drive procurement of natural-identical molecules with full supply chain transparency documentation.
Market Restraints
- Benzene and petrochemical feedstock volatility:Aromatic hydrocarbon price swings compress margins on synthetic musk and aldehyde production, particularly for non-integrated compounders.
- Grasse cluster concentration risk:Overreliance on southeast France for jasmine and rose absolute extraction creates geographic single-point vulnerability to climate events and labor constraints.
- IFRA 51st Amendment compliance costs:New restricted substance lists and concentration limits require reformulation of legacy fine fragrance SKUs, straining R&D bandwidth at mid-tier houses.
Strategic Opportunities
- Brazil's underpenetrated fine fragrance market:Rising disposable income in São Paulo and Rio de Janeiro creates demand for premium eau de parfum formulations requiring high-purity captive molecules.
- Fermentation-to-fragrance platform convergence:Synthetic biology meets traditional distillation expertise, enabling cost-parity production of sandalwood and oud substitutes without harvest limitations.
- Direct-to-niche-brand distribution:Bypassing traditional distributors, ingredient suppliers build captive relationships with independent perfumers through digital sample platforms and MOQ flexibility.
Industry Challenges
- Perfumer-chemist skill scarcity:The cross-disciplinary expertise bridging molecular synthesis and olfactory evaluation remains concentrated at a handful of training institutions in France and Switzerland.
- Bioreactor capex intensity:Commercial-scale precision fermentation for aroma molecules demands nine-figure capital commitments with extended commissioning timelines.
- GRAS and fragrance allergen dossier complexity:FDA and EU disclosure requirements for skin sensitization data extend new molecule approval cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perfume Ingredients Chemicals Market |
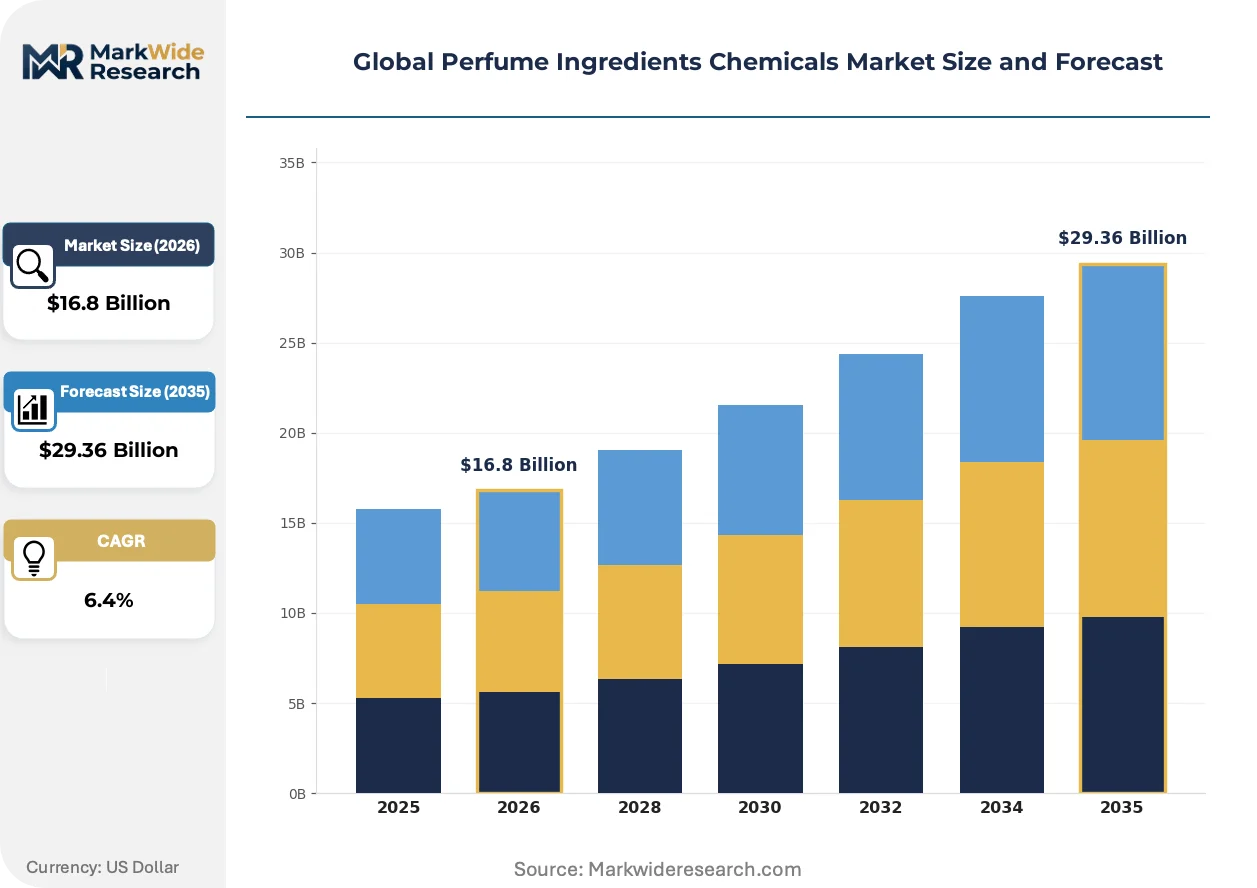
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohols, Esters, Terpenes, Phenols, Aldehydes, Ketones Application: Fragrance Manufacturing, Personal Care Products, Household Products, Aromatherapy, Cosmetics, Air Fresheners End User: Beauty Brands, Personal Care Manufacturers, Scented Product Companies, Aromatic Oil Producers Packaging Type: Drums, Bottles, Carboys, Intermediate Bulk Containers, Sachets, Tins |
| Companies Covered | Givaudan, Firmenich, International Flavors & Fragrances Inc, BASF SE, Symrise, Takasago International Corporation, Mane, DSM, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perfume Ingredients Chemicals Market Shifts & Advancements
Precision fermentation and enzymatic biotransformation are collapsing the cost curve for molecules once extracted from threatened botanical species, rewiring competitive advantage toward biotech capabilities.
Enzymatic synthesis routes for macrocyclic musks are overtaking traditional Diels-Alder chemistry as the dominant production method. Givaudan and Firmenich have scaled 15- and 16-membered ring musks via lipase-mediated cyclization, cutting solvent use by 70 percent. Fine fragrance houses now specify biotech-derived musks in 40 percent of new launches, compressing demand for legacy polycyclic structures.
EMA and EPA alignment on synthetic musk bioaccumulation testing is tightening discharge standards for manufacturing effluent. The European restriction on tonalid and galaxolide concentrations in cosmetics forces reformulation of mass-market deodorants and laundry products. Household product manufacturers are accelerating adoption of macrocyclic alternatives despite 3-4x raw material cost premiums.
Ingredient provenance documentation has become a non-negotiable selection criterion for luxury fragrance buyers. Niche perfume brands now require blockchain-traceable supply chains from Madagascan ylang-ylang to Grasse-distilled rose absolute, displacing spot-market purchasing. This behavioral shift concentrates procurement volume with suppliers offering captive farming partnerships, visible most acutely in Paris-based fine fragrance houses launching sustainability-positioned collections.
Global Perfume Ingredients Chemicals Market Segmentation
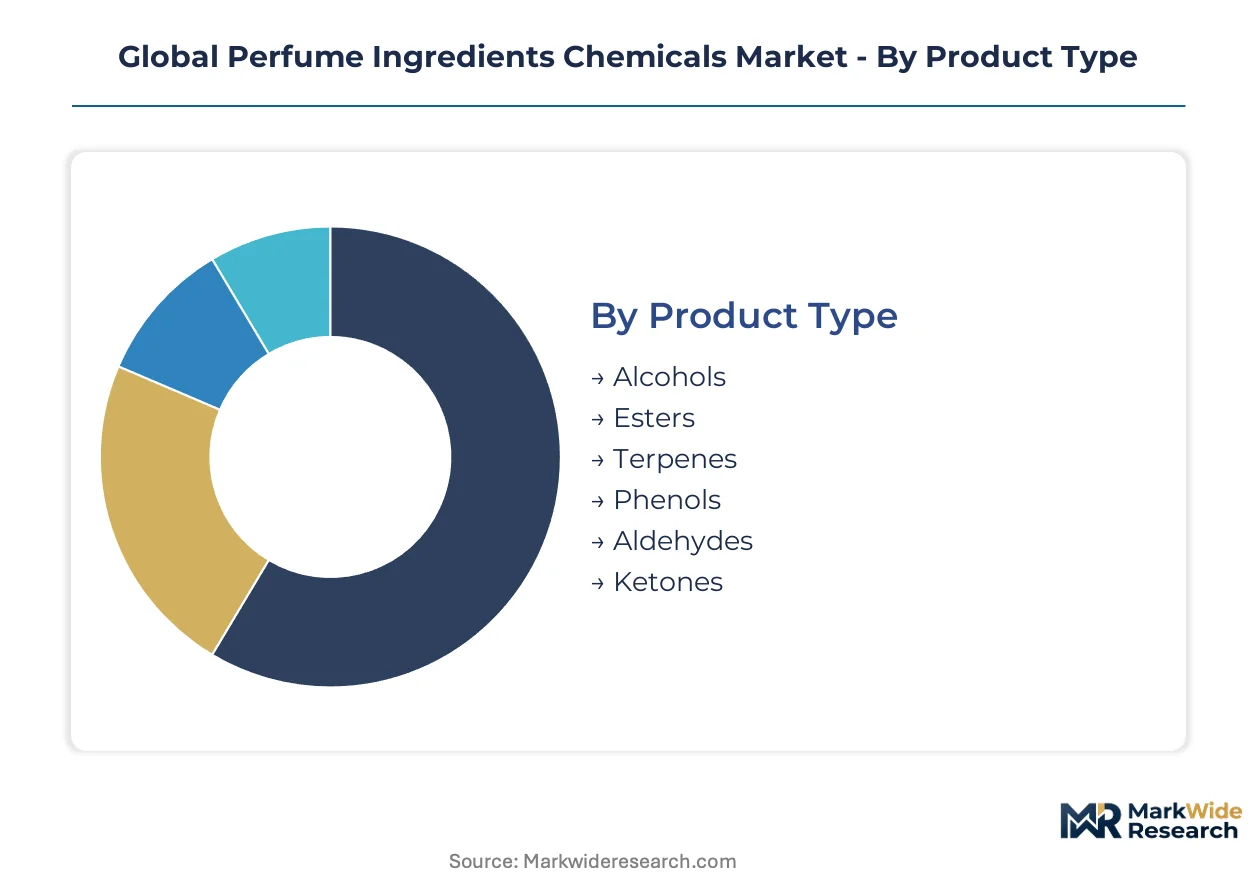
Segmentation in perfume ingredients chemicals reveals how formulation complexity and regulatory pressure fragment procurement patterns. Suppliers must align purity grades, documentation depth, and packaging formats to distinct buyer workflows across fine fragrance houses and mass-market manufacturers.
Product Type:
Alcohols and esters function as standalone diluents and carriers, while terpenes and aldehydes embed as reactive modifiers requiring precise concentration control.
- Alcohols:Ethanol and isopropyl alcohol serve as primary solvents in fine fragrance dilution, typically supplied at 96% purity minimum. Demand clusters in Grasse and Paris-based fine fragrance houses as REACH restrictions on methanol traces tighten specification windows.
- Esters:Benzyl acetate and linalyl acetate deliver fruity-floral notes with superior stability in alkaline matrices. Procurement concentrates with personal care manufacturers in India and China seeking COSMOS-compliant natural-identical grades for clean beauty lines.
- Terpenes:Limonene and pinene derivatives dominate volume throughput in household product applications.
- Phenols:Eugenol and thymol provide spicy-medicinal character in niche perfumery.
- Aldehydes:C8-C12 aliphatic aldehydes command premium positioning in luxury fine fragrance.
- Ketones:Methyl ionone and musk ketone supply woody-amber fixative properties.
Volume placements concentrate in alcohols and terpenes; the faster expansion belongs to aldehydes as luxury houses reformulate for macrocyclic compliance.
Application:
Cost tier stratification separates premium-positioned applications requiring full traceability from high-throughput segments tolerating standard-grade documentation.
- Fragrance Manufacturing:Fine fragrance compounds demand 98%+ purity with full IFRA 51st Amendment compliance dossiers. Grasse-based houses and Paris niche brands drive procurement of captive-sourced molecules with blockchain-verified provenance.
- Personal Care Products:Deodorants and body sprays require skin-sensitization-tested grades under FDA fragrance allergen labeling rules. India's PLI-supported specialty chemical investments are converting the country from importer to regional supplier for Asia-Pacific formulators.
- Household Products:Laundry detergents and surface cleaners absorb volume throughput of standard-grade alcohols and ketones.
- Aromatherapy:Essential oil isolates for therapeutic use face EMA scrutiny on purity claims.
- Cosmetics:Color cosmetics integration demands heat-stable aroma chemicals.
- Air Fresheners:Aerosol and gel formats prioritize cost-optimized synthetic molecules.
Revenue pools concentrate in fragrance manufacturing; the steepest expansion trajectory belongs to personal care products as clean beauty certification proliferates.
End User:
Customer type determines procurement sophistication, from beauty brands requiring full supply chain transparency to aromatic oil producers focused on extraction yield optimization.
- Beauty Brands:LVMH and Kering-owned houses specify captive botanical sourcing with enzymatic synthesis documentation. These buyers bypass traditional distributors, building direct relationships with biotechnology-enabled suppliers through digital sample platforms.
- Personal Care Manufacturers:Unilever and P&G-scale operations drive high-volume, long-term contracts for standard-grade esters and terpenes.
- Scented Product Companies:Candle and home fragrance specialists prioritize heat-stable, non-polar molecules.
- Aromatic Oil Producers:Distillers in Madagascar and Bulgaria focus on extraction efficiency and harvest volatility hedging.
Procurement sophistication concentrates in beauty brands; the fastest volume growth belongs to personal care manufacturers as India's domestic production capacity expands.
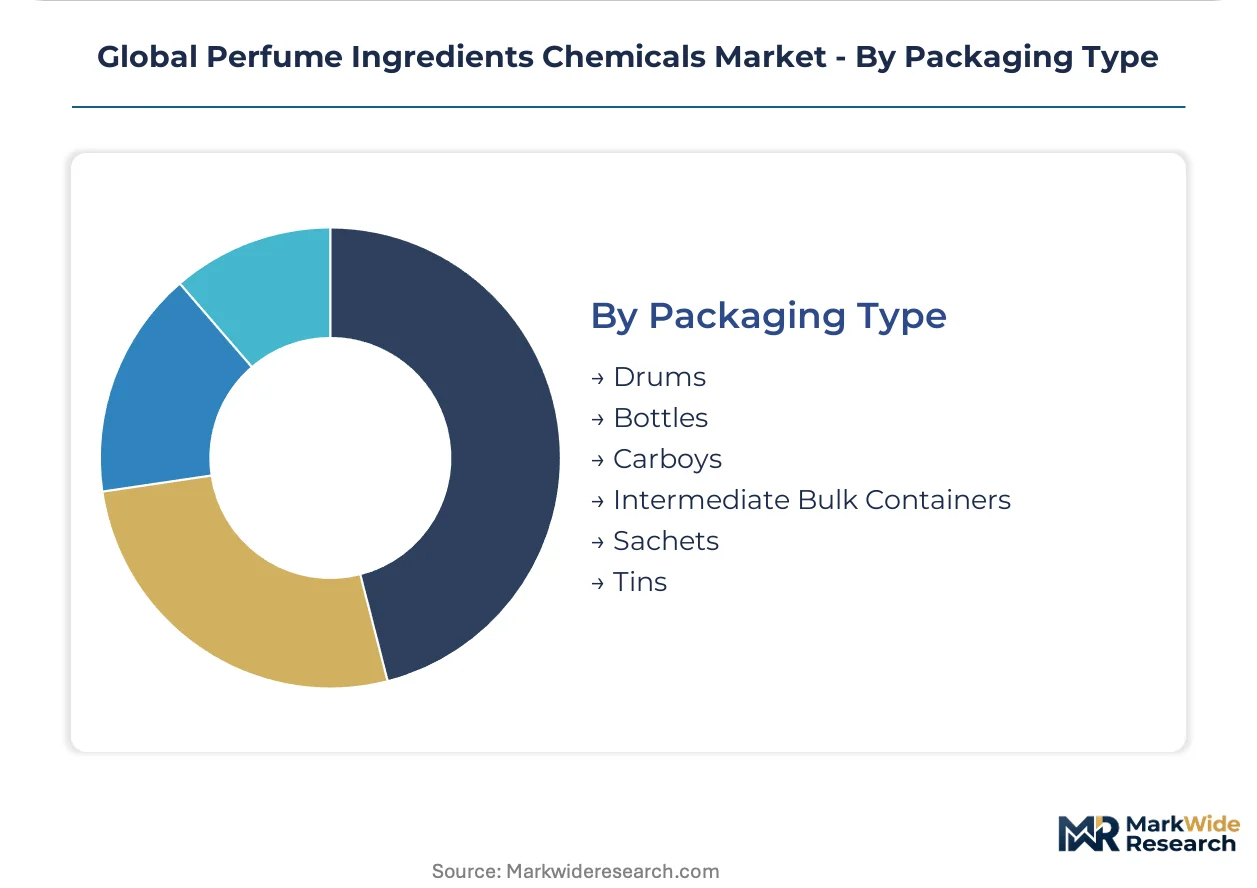
Packaging Type:
Supply chain configuration dictates format selection, with drum and intermediate bulk container volumes tracking manufacturing cluster proximity while bottles and sachets align with sample and retail distribution.
- Drums:200-liter steel drums dominate bulk shipments to European and Indian manufacturing facilities.
- Bottles:Amber glass and fluoropolymer bottles protect light-sensitive aldehydes and phenols for niche perfumer sample programs.
- Carboys:Polyethylene containers serve mid-volume personal care compounders.
- Intermediate Bulk Containers:1000-liter totes reduce handling costs for high-throughput household product manufacturers.
- Sachets:Single-use foil pouches support direct-to-niche-brand distribution models.
- Tins:Metal containers preserve volatile solid aroma chemicals in artisanal perfumery supply.
Shipment volumes concentrate in drums and intermediate bulk containers; the format gaining share fastest is sachets as digital sample platforms reshape niche brand procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse's perfume chemical cluster in southeastern France anchors global specialty ingredient supply, with REACH compliance mandates and India's PLI scheme for specialty chemicals driving geographic diversification of fermentation-based aroma molecule production.
France
Fine fragrance houses in Paris and Grasse drive demand for captive-sourced jasmine and rose absolutes with blockchain-verified provenance. ANSM enforces strict fragrance allergen labeling under EU cosmetics regulation. The Grasse cluster concentrates enzymatic synthesis capabilities for macrocyclic musks as polycyclic alternatives face phasedown.
India
Personal care manufacturers in Maharashtra and Gujarat expand procurement of COSMOS-compliant natural-identical esters for clean beauty exports. The PLI scheme for specialty chemicals attracts fermentation-based aroma chemical investments. Hyderabad and Mumbai emerge as regional supply hubs for Asia-Pacific fragrance formulators.
China
Household product manufacturers in Jiangsu and Zhejiang absorb high volumes of standard-grade terpenes and ketones for detergent and air freshener production. SAMR implements GB standards on fragrance ingredient disclosure in cosmetics. The Yangtze River Delta deepens synthetic musk production capabilities despite EPA-aligned bioaccumulation scrutiny.
United States
Fine fragrance compounders in New Jersey and California reformulate legacy SKUs for FDA fragrance allergen labeling compliance. The EPA tightens discharge standards for synthetic musk manufacturing effluent. The New York metro area concentrates niche perfume brand headquarters driving demand for high-purity aldehydes.
Brazil
Rising disposable income in São Paulo and Rio de Janeiro creates demand for premium eau de parfum formulations requiring imported high-purity captive molecules. ANVISA aligns cosmetic ingredient disclosure requirements with EU frameworks. The São Paulo state cluster develops blending capabilities for regional fragrance manufacturing.
Global Perfume Ingredients Chemicals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fragrance manufacturing consolidating around biotechnology-enabled suppliers while household product segments tolerate standard-grade compounders. Three archetypes dominate: integrated Swiss-French houses with captive botanical networks, German-Dutch chemical conglomerates with fermentation platforms, and Asian specialists leveraging PLI-supported scale. Competitive moves center on enzymatic synthesis licensing and direct-to-niche-brand distribution bypassing traditional intermediaries.
Within the integrated fragrance house tier, Givaudan and Firmenich occupy positions defined by captive sourcing and biotechnology capabilities. Symrise represents the natural-identical molecule specialist archetype with fermentation-derived alternatives. Among diversified chemical conglomerates, BASF SE anchors the scale-driven supply of standard-grade aroma chemicals for high-throughput applications.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| International Flavors & Fragrances Inc |
| BASF SE |
| Symrise |
| Takasago International Corporation |
| Mane |
| DSM |
| Sensient Technologies Corporation |
| Others |
Supply & Pricing Matrix
Perfumer-chemist skill scarcity in Grasse and Paris creates labor-cost differentials that widen pricing-tier spreads between enzymatic synthesis platforms and traditional extraction houses. REACH compliance documentation and captive botanical sourcing anchor premium positioning, while standard-grade alcohols and terpenes compete on volume scale.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with short-lead-time macrocyclic musks commanding premiums and spot-market standard-grade ketones trading at discounts. A three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified captive molecules from COSMOS-compliant natural-identical grades and commodity terpenes. Price differentiation hinges on certification depth and volume scale, with IFRA 51st Amendment dossiers adding cost layers. Cost compression in economy-grade household product segments is intensifying because benzene feedstock volatility squeezes non-integrated compounders. Mass-market manufacturers exhibit highest price sensitivity; LVMH-scale beauty brands prioritize provenance transparency over unit economics.
Supply Chain Analysis
Warehouse-distribution layers concentrate around regional distribution centers in Hyderabad, Mumbai, and the Yangtze River Delta, with hub-and-spoke patterns feeding Grasse and Paris fine fragrance houses. Geographic supply concentration centers on France for jasmine and rose absolutes, India for fermentation-based esters, and China for synthetic musk production. Raw material dependencies draw from petrochemical aromatics, Madagascan ylang-ylang harvests, and Brazilian citrus terpenes. Single-source vulnerability in Grasse's jasmine extraction creates geographic concentration risk. Distribution runs through drum and intermediate bulk container shipments for high-volume personal care manufacturers, with sachet formats gaining share in direct-to-niche-brand channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global perfume ingredients chemicals market sits in a technology-transition phase, with precision fermentation and enzymatic biotransformation displacing solvent-heavy extraction methods for threatened botanical species.
For Market Incumbents: Hedge against polycyclic musk obsolescence by accelerating macrocyclic capacity expansion in enzymatic synthesis platforms. Secure captive farming partnerships in Madagascar and Bulgaria to lock blockchain-traceable supply chains before niche brands consolidate procurement with biotechnology-enabled competitors. Backward integration into fermentation infrastructure in India captures PLI-supported cost advantages.
For New Entrants and Emerging Players: The price-point gap between premium captive-sourced absolutes and economy-grade synthetic terpenes opens white-space targeting in mid-tier personal care segments. Brazil's underpenetrated fine fragrance market offers the most penetrable geography for imported high-purity aldehydes. Digital sample platforms with MOQ flexibility provide the strongest go-to-market angle against traditional distributor relationships.
For Investors and Strategic Acquirers: The window for entry favors biotechnology-enabled specialists with scaled fermentation platforms over legacy extraction houses. Long-term viability across a five-to-ten-year horizon rests on enzymatic synthesis licensing portfolios and direct brand relationships. Watch for EMA-EPA alignment on synthetic musk bioaccumulation testing as the inflection signal accelerating macrocyclic substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Licensing | Givaudan and Firmenich monetize lipase-mediated cyclization IP, cutting solvent use by seventy percent. |
| Captive Botanical Sourcing | Blockchain-traceable jasmine and rose partnerships displace spot-market purchasing for Paris niche houses. |
| Fermentation Platform Scale-Up | India's PLI scheme converts the country from importer to regional supplier for Asia-Pacific formulators. |
| Direct-to-Niche-Brand Distribution | Digital sample platforms bypass traditional distributors, building relationships with independent perfumers. |
| Macrocyclic Musk Capacity Expansion | REACH phasedowns of polycyclic alternatives force household product manufacturers toward compliant substitutes. |
Research Methodology
Trade databases, customs records, and SEC filings formed the secondary backbone, supplemented by ECHA REACH substance restriction updates and IFRA standards documentation. Primary interviews with fragrance house procurement directors, specialty chemical plant managers, and niche brand formulation chemists validated demand patterns and pricing dynamics. Bottom-up triangulation across product-grade volume estimates and top-down cross-checks against regional production capacity anchored market sizing.
Historical trendline analysis tracked purity-grade pricing spreads and fermentation capacity buildouts across the analysis window. Segmentation modeling incorporated product type, application tier, end-user sophistication, and packaging format dimensions. CAGRs were derived from fitted growth curves adjusted for regulatory phase-in schedules and biotechnology adoption S-curves. Feedstock cost indices and clean beauty certification proliferation rates served as industry-specific forecast inputs.
Inputs from primary fieldwork and secondary databases were available through the study window; gaps in real-time biotechnology capacity commissioning timelines introduce uncertainty bands around fermentation-derived molecule supply forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Asia Pacific Essential Oils Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Deodorant Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Global Solid Perfume Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Anethole Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Cedarwood Oil Market