
 United States E-Commerce Market | 2026-2036
United States E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
United States E-Commerce Market Outlook
The gap between premium fulfillment and commodity logistics is broadening across the United States E-Commerce Market. Amazon sustains dominance through captive warehouse networks and same-day infrastructure. Walmart leverages its supercenter footprint for hybrid click-and-collect density. Wayfair specializes in oversized home goods logistics that commodity platforms struggle to replicate.
United States E-Commerce comprises digitally mediated transactions between buyers and sellers, executed through web-based storefronts or mobile applications with integrated payment gateways, inventory management systems, and last-mile fulfillment orchestration. Its primary commercial purpose is to reduce friction in product discovery, price comparison, and order fulfillment while capturing consumer behavioral data for demand forecasting. Electronics and home goods anchor transaction volume, though same-day delivery and subscription services represent the fastest-expanding delivery model segments where margin pools deepen through recurring revenue and inventory predictability. Beauty products within the product type dimension command premium pricing through influencer-driven discovery mechanics that standard electronics listings cannot replicate.
The FTC scrutinizes marketplace fee structures and data usage under evolving antitrust frameworks, while state-level sales tax nexus laws following South Dakota v. Wayfair compel platform collection obligations. The CFPB monitors buy-now-pay-later products embedded in digital checkout flows, tightening disclosure standards. Stakeholders must weigh compliance investments against the operational flexibility required to test emerging fulfillment models.
Market Dynamics
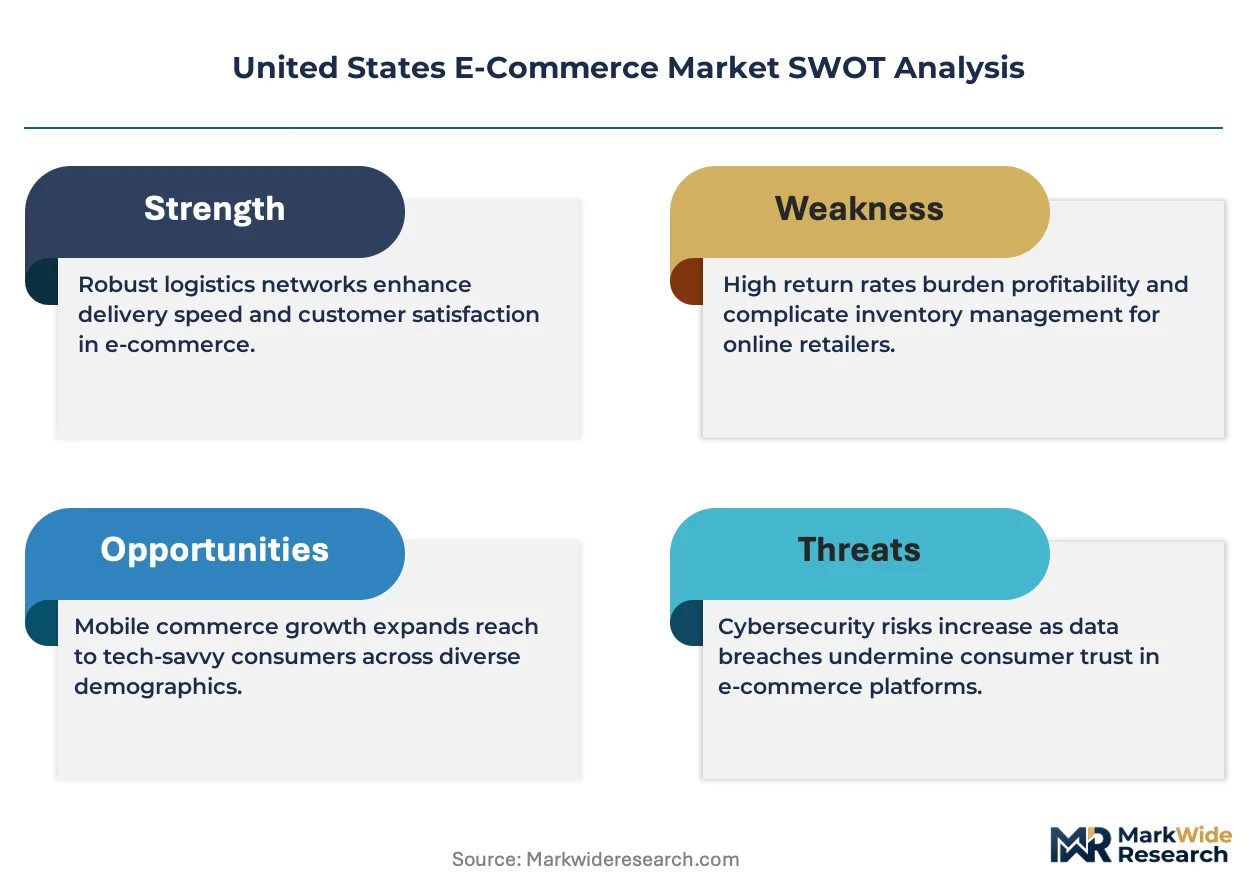
The FTC's antitrust scrutiny of marketplace fee structures is forcing sellers to rebuild unit economics around alternative fulfillment channels. Platform dependency risks now dominate strategic planning for mid-market retailers.
Growth Catalysts
- Same-Day Infrastructure:Micro-fulfillment centers within 10 miles of suburban households compress delivery windows. Texas and Florida metro corridors anchor this expansion.
- Buy-Now-Pay-Later Integration:CFPB disclosure standards legitimize embedded credit products. Digital checkout flows capture consumers previously excluded from traditional credit.
- Grocery Delivery Acceleration:Suburban household adoption of fresh food logistics creates recurring revenue pools. Cold chain capabilities differentiate platforms from commodity electronics sellers.
Market Restraints
- Platform Fee Compression:FTC scrutiny of marketplace take rates threatens seller profitability. Commission structures face downward pressure from regulatory intervention.
- Last-Mile Cost Density:Rural address dispersion inflates per-package delivery costs. Logistics networks struggle to achieve route efficiency outside urban cores.
- State Tax Nexus Complexity:Post-Wayfair collection obligations fragment compliance requirements. Multi-state sellers absorb administrative overhead from divergent filing rules.
Strategic Opportunities
- Hybrid Click-and-Collect:Supercenter footprints enable same-day pickup without last-mile delivery costs. Suburban shoppers value time certainty over home delivery.
- Oversized Home Goods Logistics:Specialty carriers capture margin pools that commodity platforms abandon. Furniture and appliance categories reward dedicated handling capabilities.
- Influencer-Driven Discovery:Beauty products command premium pricing through social commerce mechanics. Content-native purchasing reduces customer acquisition costs versus search advertising.
Industry Challenges
- Warehouse Labor Scarcity:Pick-and-pack operations compete for workers with transportation and hospitality sectors. Automation investments require capital deployment ahead of volume certainty.
- Inventory Forecasting Complexity:Demand signal fragmentation across mobile, web, and social channels degrades prediction accuracy. Bullwhip effects amplify through supplier networks.
- Returns Processing Economics:Free return policies convert to reverse logistics costs that erode category margins. Apparel and footwear segments absorb disproportionate processing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States E-Commerce Market |
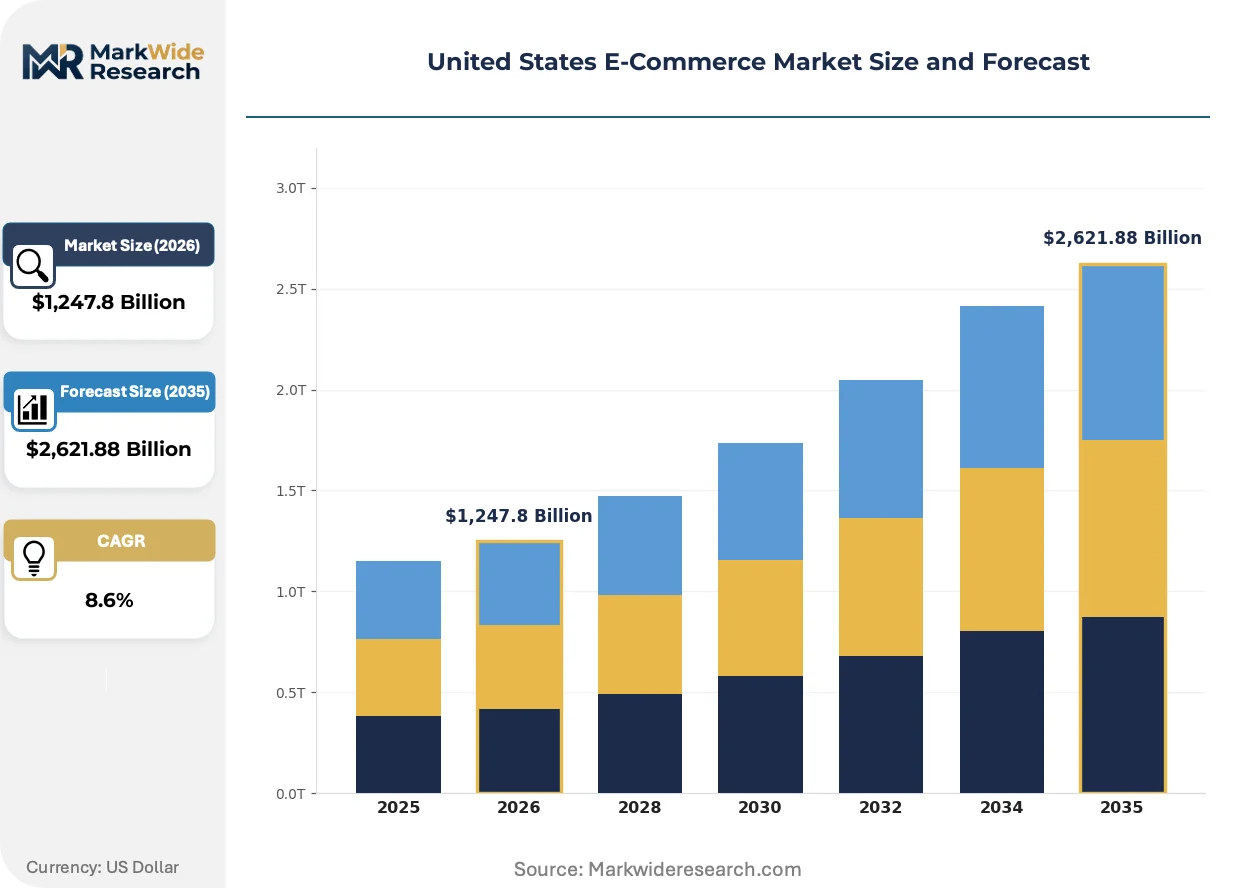
| Market Size in 2026 | $1,247.8 Billion |
| Market Size in 2035 | $2,621.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Apparel, Home Goods, Beauty Products Delivery Model: Doorstep Delivery, Click & Collect, Same-Day Delivery, Subscription Services Customer Type: Individual Consumers, Small Businesses, Enterprises, Nonprofits Payment Method: Credit Cards, Debit Cards, Digital Wallets, Bank Transfer |
| Companies Covered | Amazon, Walmart, Apple, eBay, Target, Wayfair, Best Buy, Costco Wholesale, Home Depot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States E-Commerce Market Strategic Shifts
Artificial intelligence is rewiring how inventory moves from manufacturer to doorstep. Predictive systems now anticipate demand before consumers complete search queries.
Micro-fulfillment robotics is modularizing warehouse operations into standardized cells. Grocery and electronics retailers deploy autonomous picking systems in suburban facilities. Capital deployment shifts from mega-distribution centers to distributed 50,000-square-foot nodes. This architecture compresses delivery radiuses without requiring full urban density.
The FTC's platform fee investigations are reshaping seller-platform contracts. Antitrust scrutiny threatens percentage-based commission structures that fund marketplace operations. Third-party sellers migrate toward direct-to-consumer channels with higher fixed costs but lower variable fees. Regulatory pressure concentrates most intensely in categories where Amazon captures majority transaction volume.
Subscription bundling is displacing transactional purchasing in consumable categories. Households consolidate replenishment decisions into single-platform relationships. Amazon Prime and Walmart+ capture recurring revenue that insulates against quarterly demand fluctuations. This behavioral shift concentrates most visibly in suburban markets with predictable consumption patterns and sufficient delivery density to support membership economics.
United States E-Commerce Market Segmentation
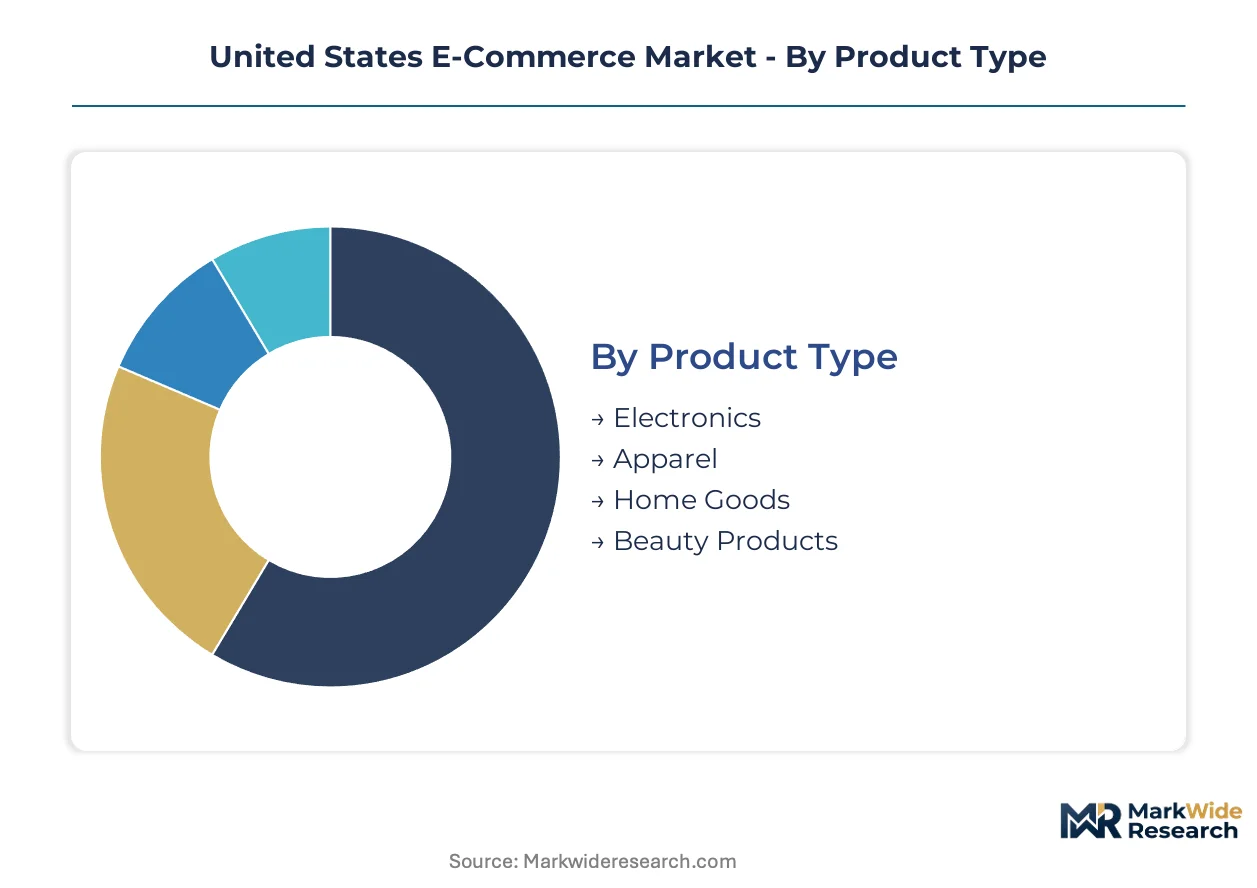
Segmentation reveals how fulfillment economics and payment infrastructure fragment across distinct commercial contexts in the United States E-Commerce Market. Each dimension carries unique regulatory exposure and margin architecture that shapes platform strategy.
Product Type:
Regulatory burden concentrates in beauty and electronics segments where FDA oversight and FCC certification requirements create compliance moats that commodity sellers cannot easily replicate.
- Electronics:FCC Part 15 certification mandates govern wireless-enabled devices sold through digital channels. Texas and Florida metro corridors concentrate demand for consumer electronics with same-day fulfillment expectations that strain inventory positioning.
- Beauty Products:FDA cosmetic labeling rules and ingredient disclosure requirements impose compliance costs that advantage established brands over marketplace arbitrageurs. Influencer-driven discovery mechanics on social platforms command premium pricing that standard search-based listings cannot match.
- Apparel:Returns processing economics dominate unit economics with free return policies converting to reverse logistics overhead. Size inconsistency across brands amplifies fulfillment complexity.
- Home Goods:Oversized dimensions require specialty carrier relationships that commodity platforms abandon. White-glove delivery services capture margin pools in furniture and appliance categories.
Electronics sits at the top of the volume ranking, with Beauty Products climbing the fastest.
Delivery Model:
Cost tier separation between premium speed and economy fulfillment determines which suburban households platforms can profitably serve.
- Same-Day Delivery:Micro-fulfillment centers within 10 miles of suburban households compress delivery windows through distributed inventory nodes. Cold chain capabilities differentiate grocery-focused platforms from electronics specialists.
- Subscription Services:Recurring revenue pools insulate against quarterly demand fluctuations through predictable replenishment patterns. Amazon Prime and Walmart+ concentrate membership economics in suburban markets with sufficient delivery density.
- Doorstep Delivery:Standard 2-3 day fulfillment remains the volume baseline where route efficiency determines per-package profitability. Rural address dispersion inflates costs outside urban cores.
- Click & Collect:Supercenter footprints enable same-day pickup without last-mile delivery costs. Time-certain retrieval appeals to suburban shoppers prioritizing schedule control over home delivery convenience.
Subscription Services command the highest customer lifetime value, with Same-Day Delivery expanding most quickly.
Customer Type:
Procurement complexity escalates from individual transaction simplicity to enterprise contract negotiation with divergent platform fee sensitivities.
- Individual Consumers:Price comparison behavior and promotional responsiveness dominate purchasing patterns. Buy-now-pay-later integration captures consumers excluded from traditional credit.
- Small Businesses:Platform dependency risks force strategic planning around alternative fulfillment channels as FTC scrutiny threatens percentage-based commission structures. Direct-to-consumer migration accelerates among mid-market sellers.
- Enterprises:Volume-based contract terms and customized procurement workflows require dedicated account management. Integration with enterprise resource planning systems creates switching costs.
- Nonprofits:Tax-exempt status verification and donation receipt requirements impose administrative overhead that platforms address through specialized checkout flows.
Individual Consumers anchor transaction volume, with Small Businesses gaining share fastest.
Payment Method:
CFPB disclosure standards reshape competitive positioning across embedded credit products and digital wallet infrastructure.
- Digital Wallets:Tokenized payment credentials reduce fraud liability while capturing behavioral data for demand forecasting. Platform-native wallets deepen customer lock-in through stored value mechanics.
- Credit Cards:Interchange fee economics and rewards program funding sustain incumbent dominance despite merchant cost pressure. Chargeback protection remains valued by risk-averse sellers.
- Debit Cards:Direct bank account linkage avoids credit qualification barriers for underbanked consumers. Real-time balance verification reduces transaction failure rates.
- Bank Transfer:Automated clearing house settlement minimizes processing costs for high-value transactions. Slower clearing times disadvantage time-sensitive purchases.
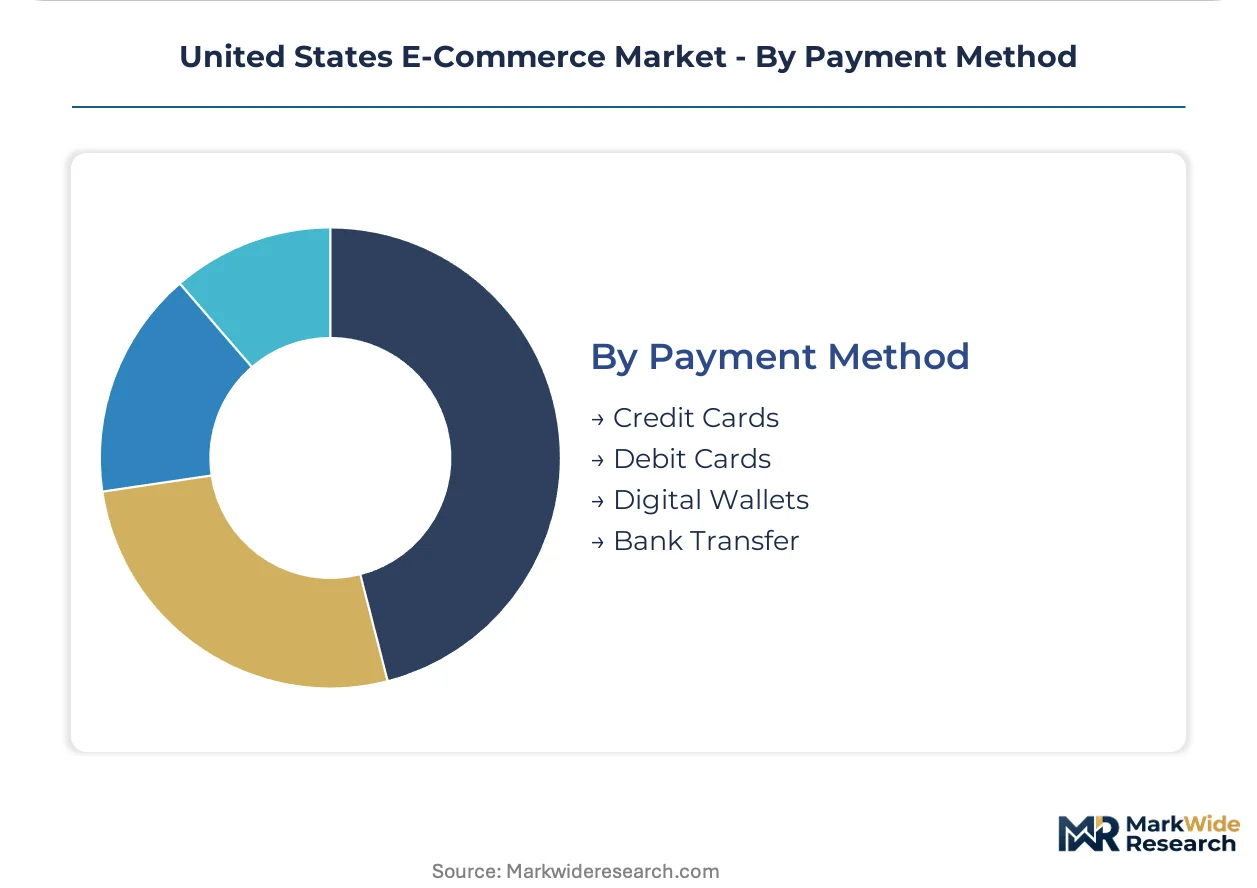
Credit Cards retain the highest transaction share, with Digital Wallets climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's grocery delivery infrastructure lags US density, while Mexico's cross-border logistics corridors concentrate e-commerce fulfillment investment near northern manufacturing zones.
Texas Metro Corridors
Houston and Dallas-Fort Worth anchor same-day fulfillment expansion through micro-fulfillment center deployment. The FTC's antitrust scrutiny of platform fees creates compliance overhead for third-party sellers operating across state lines. Cold chain capabilities in Austin and San Antonio differentiate grocery platforms from electronics-focused competitors.
Florida Urban Markets
Miami and Tampa Bay drive subscription service adoption among suburban households with predictable consumption patterns. State-level sales tax nexus laws following South Dakota v. Wayfair compel platform collection obligations for out-of-state sellers. The Orlando corridor concentrates beauty product fulfillment through influencer-driven social commerce mechanics.
California Coastal Megaregion
Los Angeles and San Francisco Bay Area logistics networks strain under warehouse labor scarcity and real estate cost pressure. The CFPB monitors buy-now-pay-later products embedded in digital checkout flows, tightening disclosure standards for credit-integrated platforms. San Diego's proximity to Tijuana creates cross-border fulfillment complexity for apparel and electronics categories.
New York Metro and Northeast Corridor
Greater New York and Boston anchor enterprise procurement workflows with customized ERP integration requirements. OSHA warehouse safety standards drive automation investment in pick-and-pack operations across New Jersey distribution hubs. Philadelphia's supercenter density enables hybrid click-and-collect penetration in suburban markets.
Pacific Northwest Cluster
Seattle and Portland concentrate same-day infrastructure investment from platforms with captive warehouse networks. The FTC's scrutiny of data usage reshapes seller-platform contracts for mid-market retailers. Boise and Spokane represent expansion targets where rural address dispersion inflates per-package delivery costs.
United States E-Commerce Market Competitive Environment
Top-tier vendors anchor nationwide fulfillment infrastructure, while mid-market specialists occupy category-specific logistics niches. The market structures around three player tiers: integrated platforms with captive supply chains, hybrid retailers leveraging physical footprints, and vertical specialists in oversized or regulated categories. Two strategic archetypes dominate: automation-heavy warehouse operators and supercenter-based click-and-collect networks. Competitive moves concentrate on micro-fulfillment densification and direct-to-consumer channel migration.
Among integrated platform operators, Amazon and Walmart exemplify divergent infrastructure strategies. Amazon represents the captive warehouse network archetype with same-day delivery density as the core competitive moat. Walmart occupies the hybrid physical-digital position, converting supercenter footprints into fulfillment nodes without last-mile cost absorption. Wayfair anchors the vertical specialist tier, demonstrating how dedicated handling capabilities in oversized home goods create defensible margin pools that commodity platforms abandon.
| Leading Market Players |
|---|
| Amazon |
| Walmart |
| Apple |
| eBay |
| Target |
| Wayfair |
| Best Buy |
| Costco Wholesale |
| Home Depot |
| Others |
Value Chain & Pricing Dynamics
Suburban household demand for same-day delivery windows is forcing platforms to deploy micro-fulfillment nodes within ten-mile radii, compressing delivery economics and reshaping how fulfillment tiers are priced. This proximity requirement fragments inventory positioning across distributed suburban facilities, elevating real estate and automation costs that platforms must recover through subscription bundling or premium speed surcharges.
Pricing Analysis
Capacity additions in Texas and Florida metro corridors are reshaping price floors for same-day fulfillment tiers. Three-tier pricing structure across premium, standard, and economy levels segments suburban households by delivery speed tolerance and subscription willingness. Price differentiation hinges on cold chain certification for grocery categories and white-glove handling for oversized home goods. Pricing pressure stems from FTC scrutiny of marketplace take rates threatening seller profitability. Individual consumers exhibit highest price sensitivity to subscription fees, while enterprise procurement contracts show least elasticity due to ERP integration switching costs.
Supply Chain Analysis
Dual-sourcing mandates from enterprise buyers and platform risk officers are compelling qualification of multiple fulfillment partners across redundant geographies. E-commerce logistics draws from China for electronics components, Vietnam for apparel manufacturing, and domestic US warehouse automation systems. Raw material dependencies span lithium-ion batteries for delivery fleet electrification, corrugated packaging from recycled pulp mills, and semiconductor chips for warehouse robotics. Single-source vulnerability concentrates in Amazon's captive warehouse network dominance. Distribution runs through hub-and-spoke parcel networks anchored by regional sortation centers, with final-mile density determining per-package profitability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States E-Commerce Market represents a late-cycle quality story where suburban household consolidation around subscription platforms favors incumbents with captive fulfillment density. Demand is shifting toward premium specifications in cold chain grocery and white-glove oversized delivery, segments where specialized handling commands margin premiums over commodity logistics.
For Market Incumbents: Deploy micro-fulfillment automation as the primary defensive lever against labor scarcity and route efficiency degradation. Consolidate suburban real estate positions in Texas and Florida corridors before competitor densification raises site acquisition costs. Fortify against FTC antitrust pressure by diversifying seller revenue streams beyond percentage-based commissions into fixed-fee logistics services and advertising products. For New Entrants and Emerging Players: AI-native demand forecasting tools offer wedge opportunity against incumbents struggling with inventory signal fragmentation across mobile, web, and social channels. Target rural address corridors in Pacific Northwest expansion markets where Amazon same-day density remains thin and per-package delivery costs inflate. Pursue vertical specialization in regulated categories—FDA-governed beauty products or FCC-certified electronics—where compliance moats deter commodity marketplace arbitrageurs. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing dedicated handling capabilities in oversized home goods and cold chain grocery logistics. Long-term viability favors platforms with hybrid physical-digital footprints converting supercenter density into fulfillment nodes without last-mile cost absorption. Monitor FTC enforcement actions against marketplace fee structures as inflection signal for seller migration toward direct-to-consumer channels and alternative fulfillment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Automation Deployment | Autonomous picking systems in 50,000-square-foot suburban nodes compress delivery radiuses without urban density requirements. |
| Direct-to-Consumer Channel Migration | Seller migration from marketplace dependency reduces variable commission exposure to FTC antitrust scrutiny. |
| Cold Chain Capability Buildout | Fresh food logistics differentiation captures recurring revenue pools that electronics-focused platforms abandon. |
| Hybrid Click-and-Collect Expansion | Supercenter footprints enable same-day pickup without absorbing last-mile delivery cost inflation. |
| Subscription Bundling Consolidation | Amazon Prime and Walmart+ membership economics insulate platforms against quarterly demand fluctuations. |
Study Parameters
Bottom-up suburban household demand modeling reconciled against top-down fulfillment infrastructure tracking forms the analytical core of this study. Primary interviews with warehouse operations directors, third-party seller platform managers, grocery supply chain executives, and last-mile logistics coordinators were cross-validated against secondary sources including FTC enforcement action filings, CFPB disclosure standard updates, SEC 10-K filings from publicly traded retailers, and commercial real estate transaction databases tracking micro-fulfillment site acquisitions. Top-down validation incorporated parcel volume data from regional carrier networks and cold chain capacity expansion announcements.
Historical trendline analysis of fulfillment cost structures and subscription adoption rates informed projection modeling across the analysis window. Segmentation dimensions include product type, delivery model, customer archetype, and payment method, with additional modeling of state-level sales tax nexus compliance burden. CAGRs were derived from logistic diffusion curves applied to same-day delivery penetration and grocery e-commerce adoption. Forecast inputs incorporated warehouse automation capex cycles and FTC regulatory enforcement probability assessments.
The model holds under continued suburban household formation and stable fuel cost environments; deviation in warehouse labor availability or interstate sales tax enforcement intensity would shift trajectory bounds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Germany E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
B2C E-Commerce Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Direct-To-Consumer Test Market