
 Consumer Packaged Goods (CPG) Market | 2026-2036
Consumer Packaged Goods (CPG) Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Packaged Goods (CPG) Market Insights
Southeast Asia is fragmenting as Vietnam, Indonesia, and Thailand add contract manufacturing capacity for multinational CPG brands. Procter & Gamble leverages its North American R&D infrastructure to sustain innovation pipelines in personal care. Nestlé anchors its growth strategy through backward integration into coffee and cocoa supply chains. Unilever competes aggressively on sustainability credentials across European retail channels.
Consumer packaged goods encompass formulated, packaged products sold through retail channels for frequent replenishment, including food and beverages with defined shelf-life specifications, personal care items with active ingredient concentrations, and household products with surfactant or disinfectant chemistries designed for domestic consumption. The food segment dominates absolute volume as private-label penetration compresses margins in mature Western markets. E-commerce as a distribution channel represents the fastest-growing fulfillment pathway, though supermarkets still control the bulk of replenishment-driven purchases. Health-conscious consumers within the consumer segment command premium price tiers and are displacing legacy formulations with clean-label alternatives.
FDA nutrition labeling requirements and EPA chemical safety assessments shape product composition and market access for goods sold in the United States. The EU Green Deal packaging regulations and REACH chemical restrictions force reformulation and material substitution across European portfolios. Stakeholders must monitor how divergent regulatory timelines between North America and Europe create compliance complexity for unified product platforms.
Market Dynamics
The EU Green Deal packaging regulations are forcing material transitions across European CPG portfolios while health-conscious consumers in India and Southeast Asia pull reformulation investments toward clean-label alternatives.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability requirements are accelerating substrate innovation across food and beverage portfolios, creating captive demand for biodegradable material suppliers.
- Urban middle-class expansion in India:Rising disposable incomes in tier-2 and tier-3 cities are pulling branded packaged goods penetration into previously underpenetrated household segments.
- E-commerce fulfillment infrastructure:Direct-to-consumer channel buildout is compressing replenishment cycles and enabling subscription-based household product models.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and polymer input costs swing with crude oil benchmarks, compressing margin visibility for household and personal care formulators.
- Supply concentration in Southeast Asian contract manufacturing:Vietnam, Indonesia, and Thailand now host disproportionate multinational CPG production, creating single-source vulnerability.
- REACH chemical restriction timelines:ECHA substance evaluations are forcing premature reformulation ahead of unified global standards, fragmenting product platforms.
Strategic Opportunities
- Underpenetrated rural India:Distribution infrastructure gaps in Bihar, Uttar Pradesh, and Madhya Pradesh leave branded packaged goods below 15 percent household penetration.
- AI-driven demand forecasting convergence:Machine learning inventory optimization is hybridizing with traditional replenishment models, enabling micro-fulfillment center placement.
- FSSAI clean-label incentives:Indian regulator certification programs for reduced-sugar and additive-free formulations are creating premium shelf positioning advantages.
Industry Challenges
- Reformulation talent scarcity:Food chemists with clean-label substitution expertise command 40 percent wage premiums, constraining R&D throughput.
- Legacy ERP integration friction:SAP and Oracle systems in incumbent CPG houses resist real-time data feeds from e-commerce and IoT shelf-monitoring deployments.
- Dual certification timelines:Simultaneous FDA nutrition label updates and EU packaging waste directive compliance are forcing parallel track investments without harmonized standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Packaged Goods (CPG) Market |
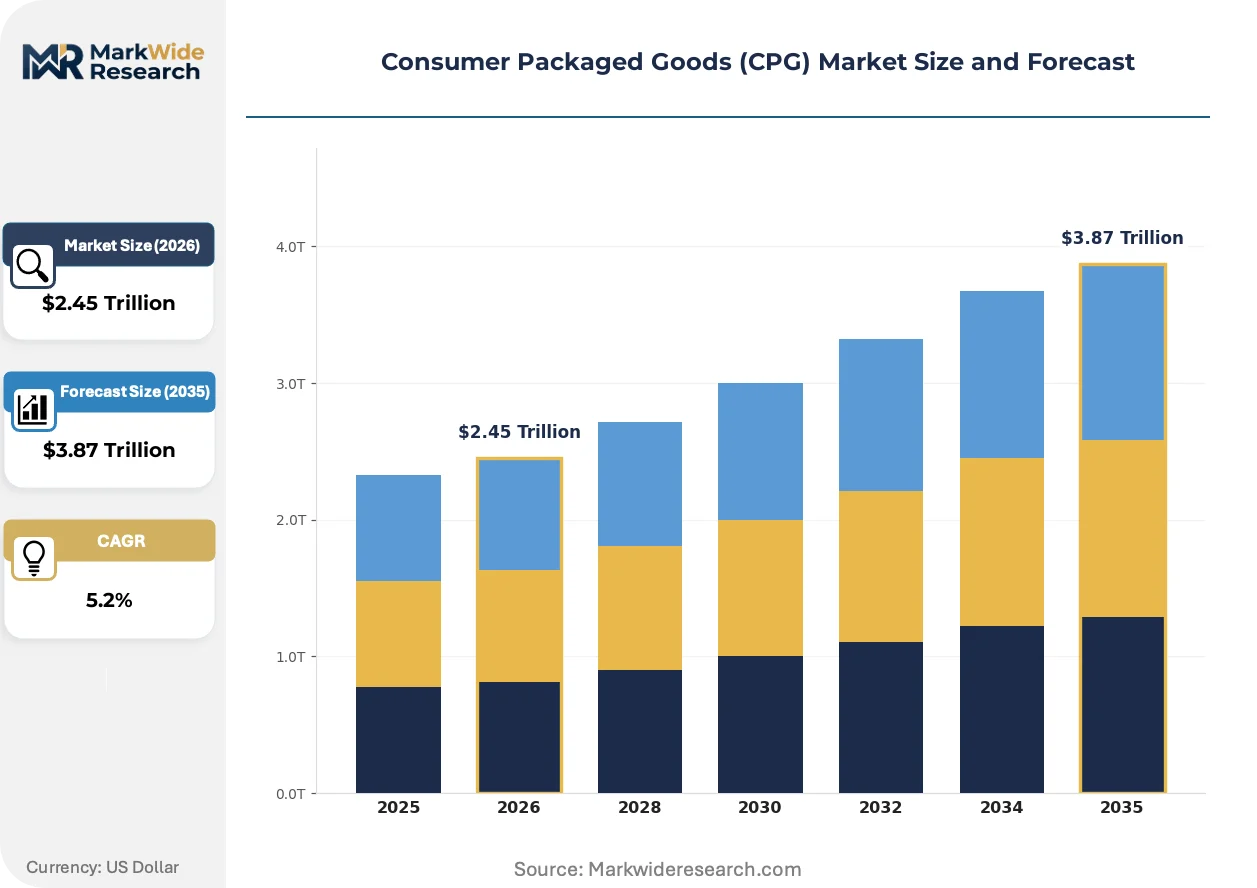
| Market Size in 2026 | $2.45 Trillion |
| Market Size in 2035 | $3.87 Trillion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverages, Personal Care, Household Products Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Wholesalers Price Tier: Premium, Mid-range, Budget, Value Consumer Segment: Health-conscious, Families, Millennials, Seniors |
| Companies Covered | PepsiCo, Colgate-Palmolive, Procter & Gamble, Mondelez International, Kraft Heinz, Nestlé, Coca-Cola, Reckitt, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Packaged Goods (CPG) Market Trends and Innovations
Active packaging technologies and AI-enabled supply chain orchestration are compressing product development cycles while regulatory divergence between North America and Europe forces dual-track compliance architectures.
Biodegradable barrier films are hybridizing conventional plastic performance with compostable end-of-life pathways. Premium food brands in Germany and France are adopting these substrates ahead of mandate deadlines. The technology is hybridizing cost structures across the value chain as material suppliers scale fermentation-based polymer production.
REACH substance restrictions and the EU Green Deal packaging waste directives are forcing synchronized reformulation and material substitution. ECHA evaluation timelines now outpace FDA safety assessments, creating asynchronous compliance windows. Personal care and household chemical segments are responding with European-first product launches and delayed US market entry.
Direct-to-consumer subscription models are displacing supermarket replenishment for personal care and household categories. Millennials and Gen Z buyers in urban India and Southeast Asian megacities are shifting volume toward curated delivery boxes. This channel rotation is most visible in skincare and premium detergent segments where brand loyalty transfers to algorithmic curation.
Consumer Packaged Goods (CPG) Market Segmentation
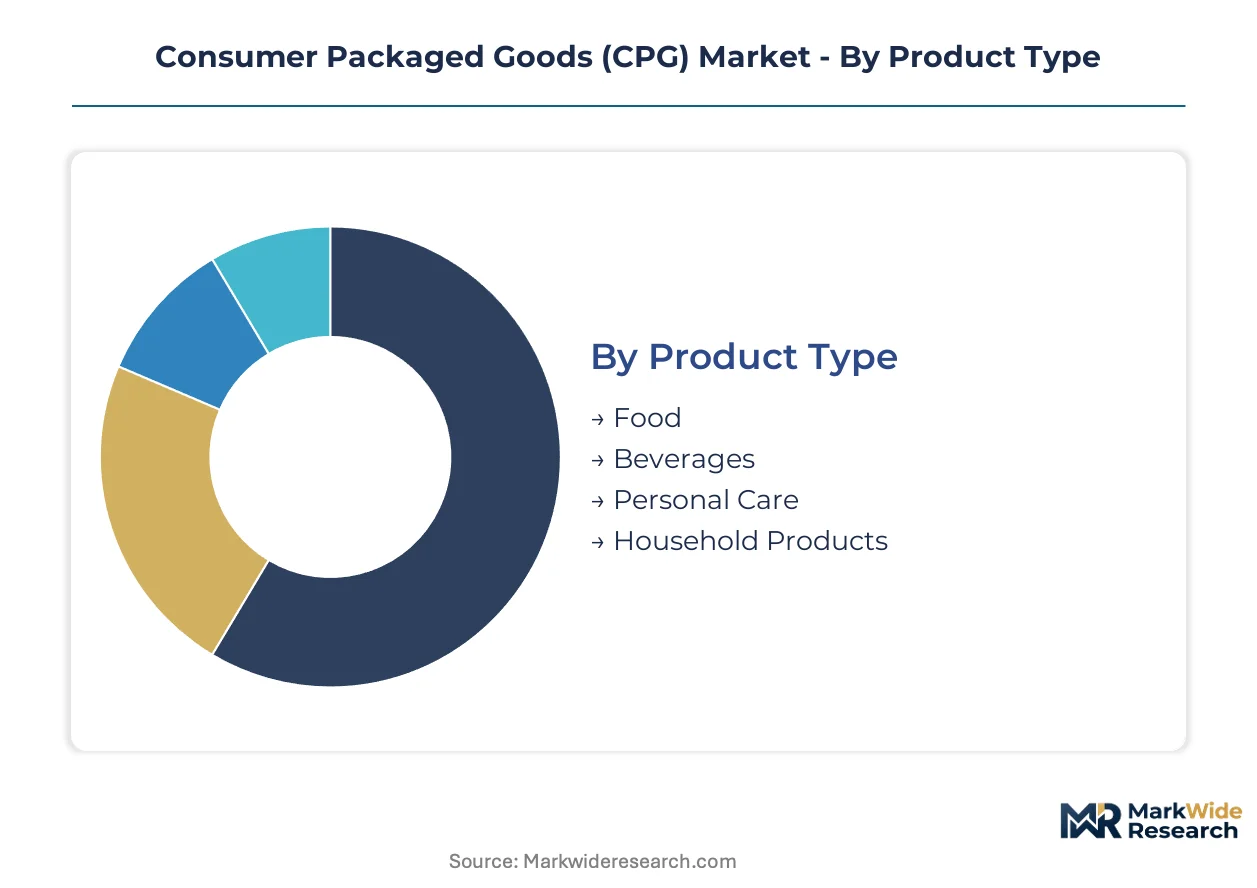
CPG segmentation reveals divergent replenishment rhythms and margin architectures. Food and beverage categories turn inventory weekly while personal care and household products stretch to monthly cycles. These velocity differences dictate working capital intensity and shelf-space negotiation leverage across retail formats.
Product Type:
Food categories compress replenishment cycles to days while household products extend to weeks, creating fundamentally different cash conversion profiles and distribution economics.
- Food:Shelf-stable and fresh formulations dominate absolute tonnage with defined expiration windows forcing rapid inventory turns. Clean-label reformulation concentrates demand in Germany and France where EU Green Deal packaging mandates accelerate substrate transitions. Private-label penetration compresses branded margin structures in mature Western markets.
- Beverages:Functional hydration and reduced-sugar portfolios command premium positioning through FSSAI clean-label certification in India. Urban middle-class expansion in tier-2 and tier-3 Indian cities pulls branded penetration into previously underpenetrated household segments. Refrigerated supply chains constrain geographic reach and concentrate production near demand clusters.
- Personal Care:Active ingredient concentrations and surfactant chemistries face REACH substance evaluation timelines that outpace FDA safety assessments. E-commerce subscription models displace supermarket replenishment among Millennials and Gen Z buyers in urban India and Southeast Asian megacities.
- Household Products:Disinfectant and surfactant formulations swing with petrochemical feedstock volatility that compresses margin visibility. Contract manufacturing concentration in Vietnam, Indonesia, and Thailand creates single-source vulnerability for multinational supply chains.
Food dominates installed base. Beverages is where expansion concentrates.
Distribution Channel:
Channel selection determines price realization and data capture depth, with digital-native pathways offering superior consumer analytics at the cost of fulfillment economics.
- Supermarkets:Control bulk replenishment-driven purchases through high-frequency traffic and impulse placement optimization. Shelf-space fees and promotional calendars compress net margins for emerging brands. EU Green Deal packaging waste directives force synchronized material transitions across European retail footprints.
- E-commerce:Direct-to-consumer fulfillment infrastructure compresses replenishment cycles and enables algorithmic curation for skincare and premium detergent segments. AI-driven demand forecasting hybridizes with traditional inventory models to enable micro-fulfillment center placement.
- Convenience Stores:Immediate consumption occasions command 20-40 percent price premiums over supermarket equivalents. Urban density in Indian and Southeast Asian megacities expands addressable store networks.
- Wholesalers:Bulk procurement relationships with institutional buyers and rural distributors in Bihar, Uttar Pradesh, and Madhya Pradesh bridge infrastructure gaps. Working capital requirements favor established players with balance sheet depth.
Supermarkets anchor volume throughput. E-commerce is climbing the fastest.
Price Tier:
Premium positioning requires demonstrable formulation differentiation or sustainability certification to justify price gaps in competitive retail environments.
- Premium:Clean-label credentials and biodegradable packaging command shelf positioning advantages through FSSAI certification programs in India. Health-conscious consumers displace legacy formulations with additive-free alternatives at 30-50 percent price elevation.
- Mid-range:Balances performance claims with accessibility for urban middle-class households in tier-2 Indian cities. Private-label encroachment narrows differentiation space.
- Budget:Volume scale and manufacturing efficiency defend position against input cost volatility. Concentration in Southeast Asian contract manufacturing optimizes landed cost structures.
- Value:Promotional depth and temporary price reduction programs drive trial and stock-up behavior. Margin compression limits R&D reinvestment capacity.
Premium captures margin expansion. Budget defends volume base.
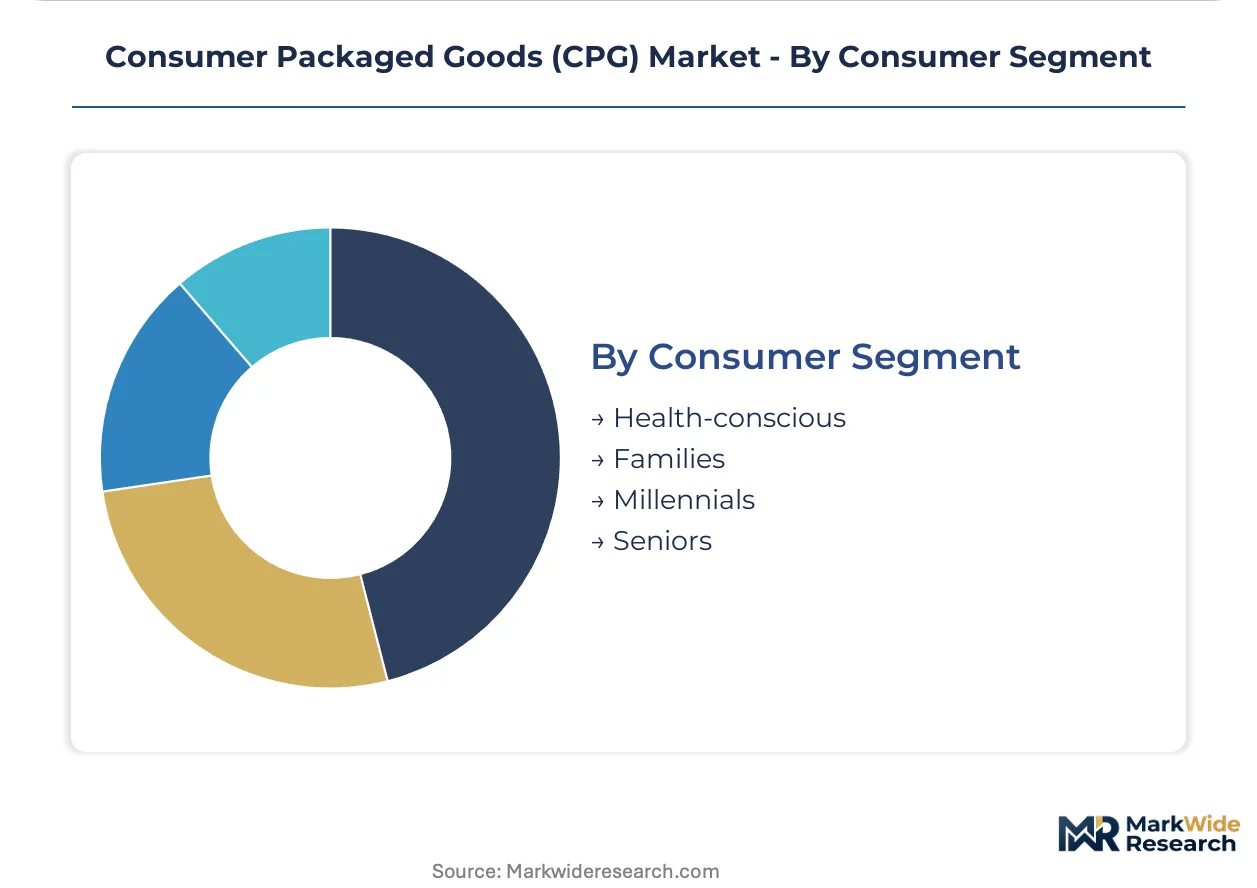
Consumer Segment:
Demographic targeting aligns product development pipelines with divergent media consumption and retail channel preferences.
- Health-conscious:Reformulation expertise scarcity constrains R&D throughput as food chemists command wage premiums for clean-label substitution capabilities. EU and Indian regulatory divergence on additive approvals fragments product platform strategies.
- Families:Bulk sizing and multi-pack configurations optimize household economics. Supermarket loyalty programs and promotional calendars anchor purchase behavior.
- Millennials:Subscription curation and sustainability credentials drive channel migration toward direct-to-consumer models. Algorithmic personalization transfers brand loyalty from manufacturer to platform.
- Seniors:Functional benefit clarity and packaging accessibility requirements shape formulation and design specifications. Pharmacy and convenience store proximity influences channel selection.
Health-conscious consumers anchor premium tier growth. Millennials are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing clusters in Vietnam, Indonesia, and Thailand now process substantial volumes for multinational brands. India absorbs investment as urbanization expands the addressable middle-class base. Regulatory divergence between the EU Green Deal and FDA timelines fragments product platform strategies across Atlantic markets.
United States
Health-conscious consumers command premium price tiers and displace legacy formulations with clean-label alternatives. FDA nutrition labeling requirements and EPA chemical safety assessments shape product composition and market access. E-commerce fulfillment infrastructure compresses replenishment cycles and enables subscription-based household product models in urban clusters.
Germany
EU Green Deal packaging mandates accelerate substrate innovation across food and beverage portfolios with captive demand for biodegradable material suppliers. REACH chemical restrictions force premature reformulation ahead of unified global standards. Premium food brands in German retail channels adopt biodegradable barrier films ahead of mandate deadlines.
India
Rising disposable incomes in tier-2 and tier-3 cities pull branded packaged goods penetration into previously underpenetrated household segments. FSSAI clean-label certification programs for reduced-sugar and additive-free formulations create premium shelf positioning advantages. Distribution infrastructure gaps in Bihar, Uttar Pradesh, and Madhya Pradesh leave branded packaged goods below 15 percent household penetration.
Vietnam
Southeast Asian contract manufacturing capacity expansion attracts multinational CPG production investment. Urban density in Vietnamese megacities expands convenience store networks commanding 20-40 percent price premiums over supermarket equivalents. Manufacturing concentration creates single-source vulnerability for multinational supply chains.
France
EU Green Deal packaging waste directives force synchronized material substitution across European portfolios. ECHA evaluation timelines outpace FDA safety assessments, creating asynchronous compliance windows. Premium food brands adopt biodegradable barrier films ahead of mandate deadlines through fermentation-based polymer production scaling.
Consumer Packaged Goods (CPG) Market Competitive Landscape
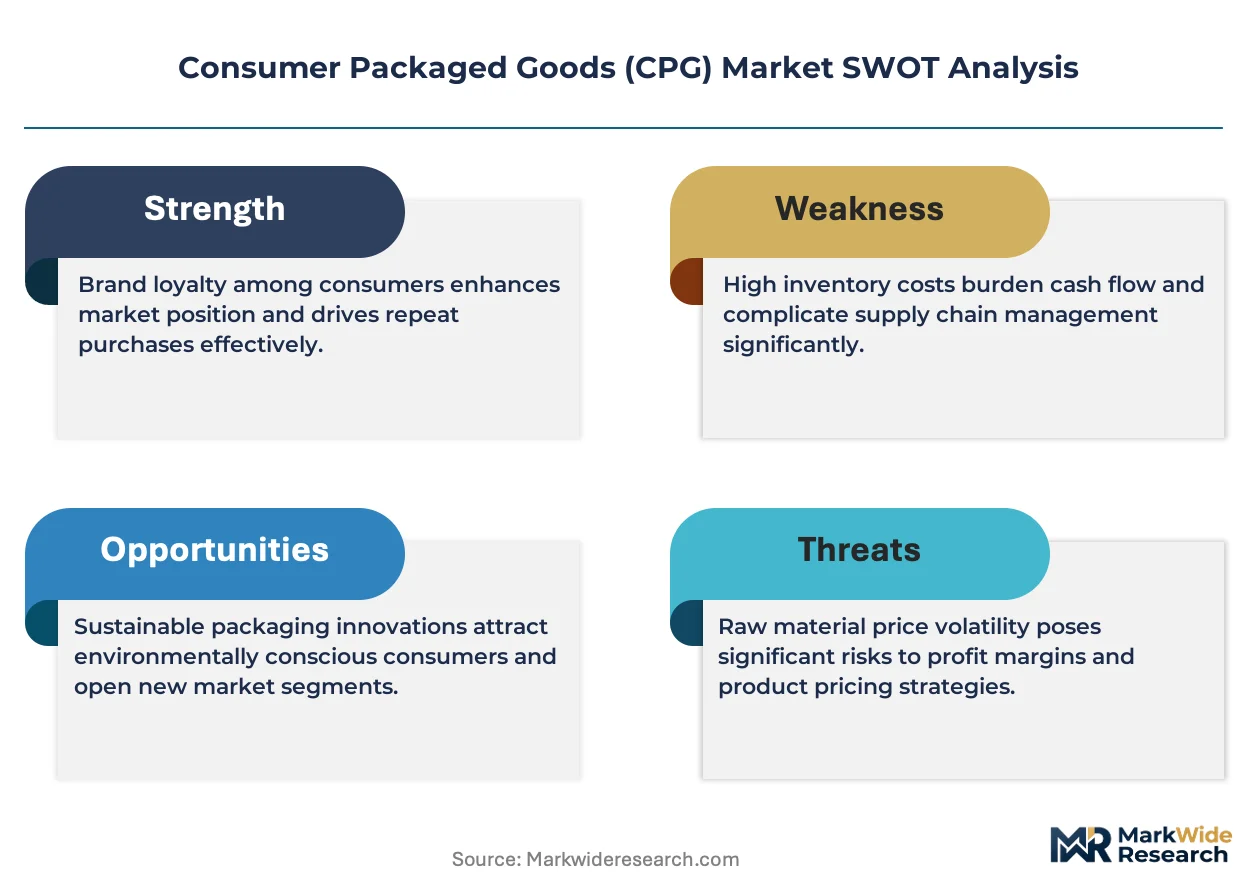
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The CPG market consolidates around diversified multinationals with cross-category portfolios spanning food, beverage, personal care, and household segments. Three archetypes dominate: scale-driven conglomerates with backward-integrated supply chains, sustainability-focused innovators competing on EU regulatory compliance, and regional specialists exploiting underpenetrated distribution gaps. Competitive moves concentrate on portfolio diversification into adjacent categories and strategic partnerships with contract manufacturers in Southeast Asian production clusters.
Among diversified conglomerates, Nestlé and Unilever exemplify scale-driven platform integrators with extensive supply chain footprints. PepsiCo occupies a position bridging beverage concentration with snack diversification. These anchors represent archetypal competitive positioning rather than exhaustive market coverage, with each sitting within distinct strategic postures on sustainability credentials and geographic reach.
| Leading Market Players |
|---|
| PepsiCo |
| Colgate-Palmolive |
| Procter & Gamble |
| Mondelez International |
| Kraft Heinz |
| Nestlé |
| Coca-Cola |
| Reckitt |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock volatility compresses margin visibility across household and personal care formulators, forcing simultaneous recalibration of pricing tier spreads and Southeast Asian contract manufacturing footprints. This input cost uncertainty widens premium-to-budget tier spreads while accelerating concentration in Vietnam, Indonesia, and Thailand production clusters.
Pricing Analysis
EU Green Deal packaging mandates dictate the pricing tier structure across European CPG portfolios. Three-tier pricing structure across premium, standard, and economy levels stratifies by biodegradability certification and clean-label density. Cost compression in budget tiers intensifies because private-label encroachment narrows differentiation space. Health-conscious consumers in Germany and France show least price sensitivity, while rural Indian households in Bihar and Uttar Pradesh exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Vietnam and EU markets dominates supply chain risk calculus for multinational CPG brands. Contract manufacturing concentrates in Vietnam, Indonesia, and Thailand, drawing from palm oil derivatives, fermentation-based polymers, and surfactant feedstocks. Single-source vulnerability intensifies as production scales in Southeast Asian clusters. Distribution runs through supermarket retail networks in mature markets and wholesaler bridges in rural India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supermarket consolidation across European retail channels shifts buyer power toward category managers, compressing net margins for emerging brands and forcing defensive repositioning.
For Market Incumbents: Pre-empt REACH substance evaluation timelines by accelerating European-first product launches ahead of asynchronous FDA assessments. Anchor backward integration into coffee and cocoa supply chains to defend against commodity volatility. Prioritize SAP and Oracle ERP modernization to enable real-time e-commerce data feeds. For New Entrants and Emerging Players: Establish a beachhead in underpenetrated rural India through wholesaler partnerships bridging Bihar, Uttar Pradesh, and Madhya Pradesh distribution gaps. Target FSSAI clean-label certification for premium shelf positioning. Deploy AI-driven demand forecasting to enable micro-fulfillment center placement ahead of incumbent legacy system upgrades. For Investors and Strategic Acquirers: The market sits at a regulatory divergence phase that favors sustainability-focused innovators with EU compliance architectures. Five-to-ten-year viability hinges on biodegradable material supplier scale and clean-label R&D throughput. Watch ECHA evaluation timeline acceleration against FDA harmonization delays as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | EU Green Deal compliance secures shelf access in German and French retail channels. |
| Direct-to-Consumer Launch | Subscription models capture Millennials and Gen Z buyers in urban Indian megacities. |
| Backward Integration | Captive supply of coffee and cocoa insulates Nestlé against commodity price swings. |
| Distribution Channel Expansion | Wholesaler partnerships penetrate below-15-percent household penetration in rural India. |
| Premium Tier Introduction | FSSAI certification commands 30-50 percent price elevation for additive-free formulations. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at retailers, channel sales heads, and supply planners anchored the qualitative base. Primary interviews combined with secondary validation from Nielsen retail audit data, customs records, SEC 10-K filings, and EU regulatory filings. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation converged on segment-level outputs.
Scenario-bracketing around regulatory timeline divergence and petrochemical price volatility informed projection boundaries across the analysis window. Segmentation dimensions modeled include product type, distribution channel, price tier, and consumer segment with regional regulatory cluster overlays. CAGRs derived from historical velocity patterns and elasticity-adjusted demand curves, incorporating FSSAI certification adoption rates and EU packaging mandate compliance trajectories as industry-specific inputs.
Sensitivities concentrate around REACH evaluation acceleration, crude oil benchmark volatility, and Indian rural infrastructure buildout pace. Forecasts reflect documented assumptions on regulatory harmonization timelines and middle-class expansion trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
North America Functional Pet Treat Market
Consumer Goods
Women's Suits and Ensembles Market
Consumer Goods
West Africa Cigarettes Market
Consumer Goods
Fully Automatic Dishwasher Market
Consumer Goods
Middle East and Africa Smartphones Market
Consumer Goods
Roll-Your-Own Tobacco Products Market
Consumer Goods
North America Deodorants Market
Consumer Goods
Italy Vegan Cosmetics Market
Consumer Goods
China Eyelash Serum Market
Consumer Goods
Tobacco Products Market
Consumer Goods
North America Personal Care Appliances Market
Consumer Goods
Global Professional Hair Care Market
Consumer Goods
Nail Art Tools and Accessories Market
Consumer Goods
Global Facial Cleanser Market
Consumer Goods
Smart Fridge Market
Consumer Goods
Footwear Manufacturing Machinery Market