
 Monitoring Sound Box for Playing Market | 2026-2036
Monitoring Sound Box for Playing Market Size, Share, and Industry Trends Forecast 2026-2036
Monitoring Sound Box for Playing Market Insights
Aftermarket service revenue for calibration and acoustic tuning is tilting toward original equipment manufacturers and certified service networks. Yamaha leverages its global service infrastructure to capture recurring maintenance contracts for studio monitor installations. Genelec anchors its competitive position through proprietary room-correction software bundled with hardware sales. KRK competes aggressively on price-performance ratios in the project-studio segment across North America and Europe.
A monitoring sound box for playing is an electroacoustic transducer system engineered to reproduce audio signals with flat frequency response, typically spanning 20 Hz to 20 kHz, for critical listening applications in music production and live performance environments. Its primary commercial purpose is to enable accurate sound evaluation during recording, mixing, and mastering workflows. Wireless speakers incorporating Wi-Fi streaming technology represent the fastest-expanding product category as latency reduction protocols improve. Professional musicians and audio engineers command the highest margin pools due to their requirements for extended frequency range and precise stereo imaging. Sound bars oriented toward home automation integration show maturing growth trajectories in saturated urban markets.
FCC emissions standards in the United States and CE marking requirements under the EU Radio Equipment Directive constrain wireless transmission architectures and influence product development cycles. RoHS substance restrictions and REACH chemical registration obligations in Europe compel suppliers to reformulate solder compositions and enclosure materials. Japan's METI enforces energy-efficiency benchmarks that shape amplifier topology selections for units sold in the Japanese market. Stakeholders must monitor evolving spectrum allocation decisions and material compliance deadlines to anticipate redesign costs and regional market access conditions.
Market Dynamics
Wireless latency reduction protocols are compressing the performance gap between cable-free and wired monitoring systems, forcing incumbent manufacturers to accelerate hardware refresh cycles while defending installed-base service contracts.
Growth Catalysts
- EU Green Deal material mandates:REACH compliance deadlines are accelerating reformulation of enclosure polymers and solder alloys, creating first-mover advantages for suppliers with certified sustainable supply chains.
- Wi-Fi 6E spectrum allocation:Expanded unlicensed bandwidth in the 6 GHz range is enabling sub-10 millisecond transmission latency, satisfying critical listening requirements previously reserved for wired systems.
- Project studio proliferation:Home-based music production infrastructure investments in Germany, Japan, and the United States are sustaining replacement demand for nearfield monitors with room-correction capabilities.
Market Restraints
- Rare earth magnet cost volatility:Neodymium price swings from Chinese export quotas are compressing margin predictability for driver manufacturers dependent on high-flux magnetic assemblies.
- Amplifier semiconductor concentration:Fabrication capacity for Class-D power management ICs remains concentrated in Taiwanese foundries, exposing supply continuity risks.
- Acoustic measurement standard fragmentation:Competing room-correction algorithms from proprietary vendors resist interoperability, fragmenting calibration service ecosystems.
Strategic Opportunities
- Spatial audio production workflows:Dolby Atmos and Sony 360 Reality Audio mixing requirements are creating upgrade cycles for multi-channel monitoring arrays in post-production facilities.
- Subscription-based calibration services:Cloud-connected room analysis platforms bundled with hardware sales are shifting revenue models toward recurring maintenance streams.
- India studio infrastructure buildout:Film scoring and remote session work migration to Mumbai and Chennai is generating demand for reference-grade monitoring in climate-variable environments.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in small-room modal analysis and DSP-based correction tuning commands premium compensation, constraining service network expansion.
- Cross-border certification complexity:Divergent FCC Part 15 emissions testing and CE Radio Equipment Directive conformity assessment timelines delay product launches by 4-8 months.
- Legacy analog integration friction:Hybrid studios maintaining vintage outboard gear require impedance-matching solutions that complicate wireless system architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monitoring Sound Box for Playing Market |
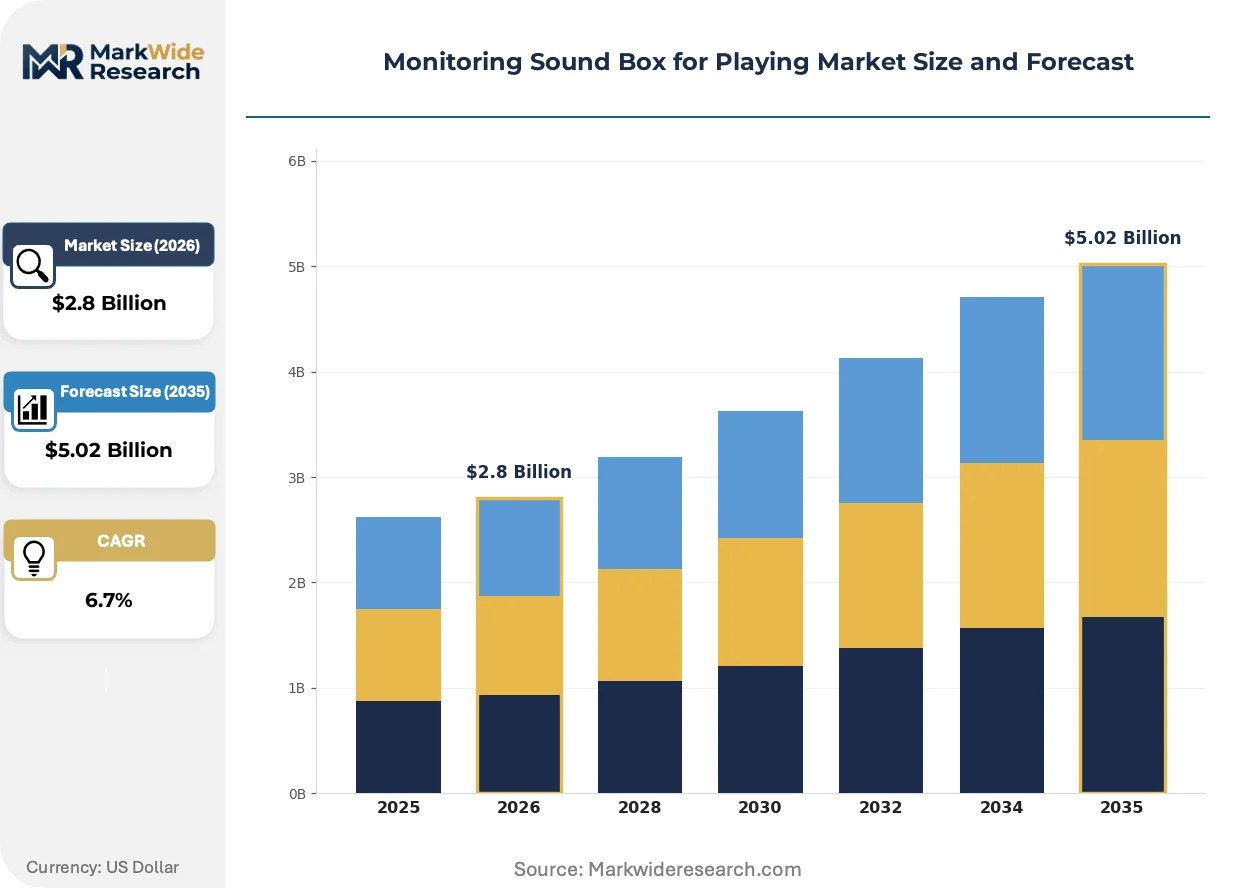
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Speakers, Wireless Speakers, Portable Speakers, Sound Bars End User: Home Users, Professional Musicians, Audio Engineers, Event Organizers Technology: USB Connectivity, Near Field Communication, Wi-Fi Streaming, Voice Activation Application: Personal Entertainment, Live Performances, Public Announcements, Home Automation |
| Companies Covered | Yamaha, JBL, Bose, KRK, Mackie, Genelec, Sennheiser, Logitech, Harman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monitoring Sound Box for Playing Market Trends and Innovations
Audio-over-IP transport protocols and machine-learning room analysis are converging to redefine professional monitoring infrastructure, compressing the traditional boundary between hardware performance and software adaptability.
Ultra-low-latency Wi-Fi streaming chipsets are collapsing the historical tradeoff between wireless convenience and phase-accurate stereo imaging. Professional mixing engineers in broadcast and live sound verticals are adopting these modules for monitor wedge applications previously dominated by analog RF systems. The technology is collapsing dedicated wireless infrastructure costs by integrating transmission logic directly into active speaker DSP architectures.
RoHS substance restrictions and REACH SVHC candidate list expansions are compelling enclosure manufacturers to eliminate halogenated flame retardants from ABS and polycarbonate formulations. European OEMs face reformulation costs of 12-18% per unit for compliant material sourcing. Studio monitor product lines destined for EU markets are responding with aluminum and bamboo-fiber composite housings that preempt regulatory scope creep.
Aftermarket calibration unbundling is disrupting the traditional bundled sale model for room-correction software. Independent acousticians and freelance mixing engineers are purchasing standalone measurement microphones and third-party DSP plugins rather than locked ecosystem packages. This pattern is most visible in North American project studios where operator skill levels support self-directed acoustic treatment decisions.
Monitoring Sound Box for Playing Market Segmentation
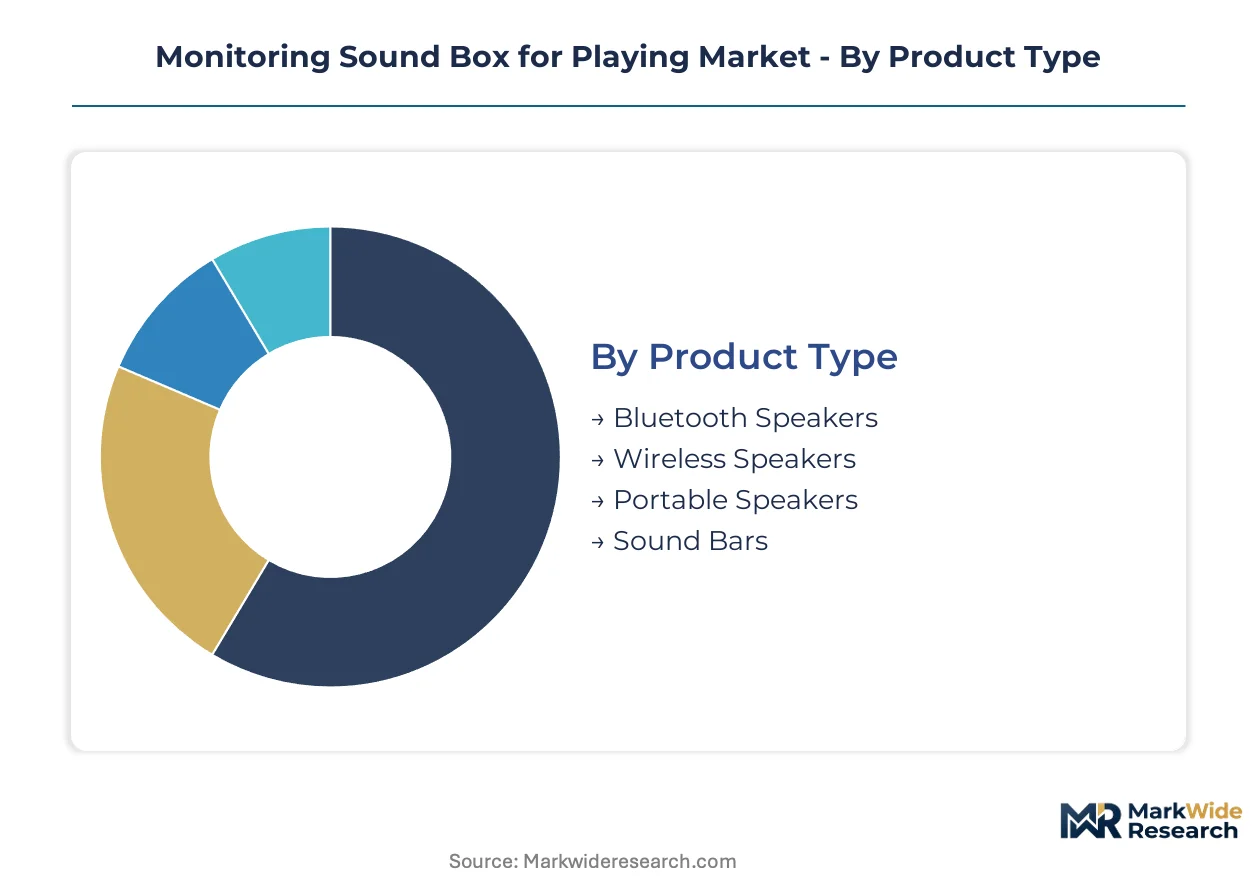
Segmentation in the monitoring sound box market exposes divergent service intensity patterns. Professional end users demand recurring calibration and acoustic tuning support, while consumer segments prioritize replacement cycles over maintenance relationships. Manufacturers structure warranty programs and service networks around these behavioral differences.
Product Type:
After-sales service intensity varies sharply across physical form factors, with installed studio monitors generating multi-year maintenance contracts versus portable units driving warranty claim volume.
- Bluetooth Speakers:Compact units with integrated battery systems and simplified DSP architectures. Home users in Germany and Japan sustain replacement demand for entry-level project studio applications where wireless convenience outweighs absolute accuracy requirements.
- Wireless Speakers:Wi-Fi streaming modules with sub-10 millisecond latency protocols now matching wired phase coherence. Professional musicians and audio engineers in the United States are expanding adoption for monitor wedge applications previously restricted to analog RF systems.
- Portable Speakers:Battery-powered designs with weatherized enclosures for location recording. Event organizers represent the core demand cluster.
- Sound Bars:Home automation integration with HDMI ARC and optical inputs. Urban markets show maturing trajectories as smart TV audio convergence slows upgrade frequency.
By volume, Bluetooth speakers lead. By growth pace, wireless speakers are gaining share fastest.
End User:
Customer type determines margin structure, with professional segments commanding premium pricing for extended frequency response and certified calibration services.
- Home Users:Price-sensitive purchasers prioritizing streaming compatibility over flat frequency response. Replacement cycles compress as smart speaker integration matures.
- Professional Musicians:Stage monitor and in-ear system operators requiring ruggedized wireless transmission. Live performance infrastructure investments in Germany sustain demand for road-worthy enclosures.
- Audio Engineers:Critical listening practitioners demanding 20 Hz to 20 kHz flat response and precise stereo imaging. Post-production facilities in Japan and the United States generate upgrade cycles for multi-channel Atmos arrays.
- Event Organizers:Rental fleet operators prioritizing durability and rapid deployment. Corporate and festival verticals in the United States concentrate procurement volume.
Audio engineers capture the highest margin pool. Home users exhibit the steepest volume concentration.
Technology:
Interface architecture shapes regulatory exposure, with wireless transmission protocols facing FCC Part 15 and CE Radio Equipment Directive compliance burdens that wired alternatives avoid.
- USB Connectivity:Digital audio interface with plug-and-play driver support. Project studios favor this for direct DAW integration without additional conversion stages.
- Near Field Communication:Tap-to-pair functionality for rapid device association. Consumer applications dominate; professional adoption remains limited by range constraints.
- Wi-Fi Streaming:6 GHz spectrum utilization enabling uncompressed multichannel transport. Broadcast engineers in Japan leverage METI-compliant energy-efficient amplifiers with these modules.
- Voice Activation:Microphone array integration for hands-free control. Home automation applications show saturation as privacy concerns temper uptake.
Wi-Fi streaming shows the steepest expansion trajectory. USB connectivity retains the largest installed base.
Application:
Use case context dictates acoustic environment variability, from controlled studio spaces to untreated venues with challenging modal response.
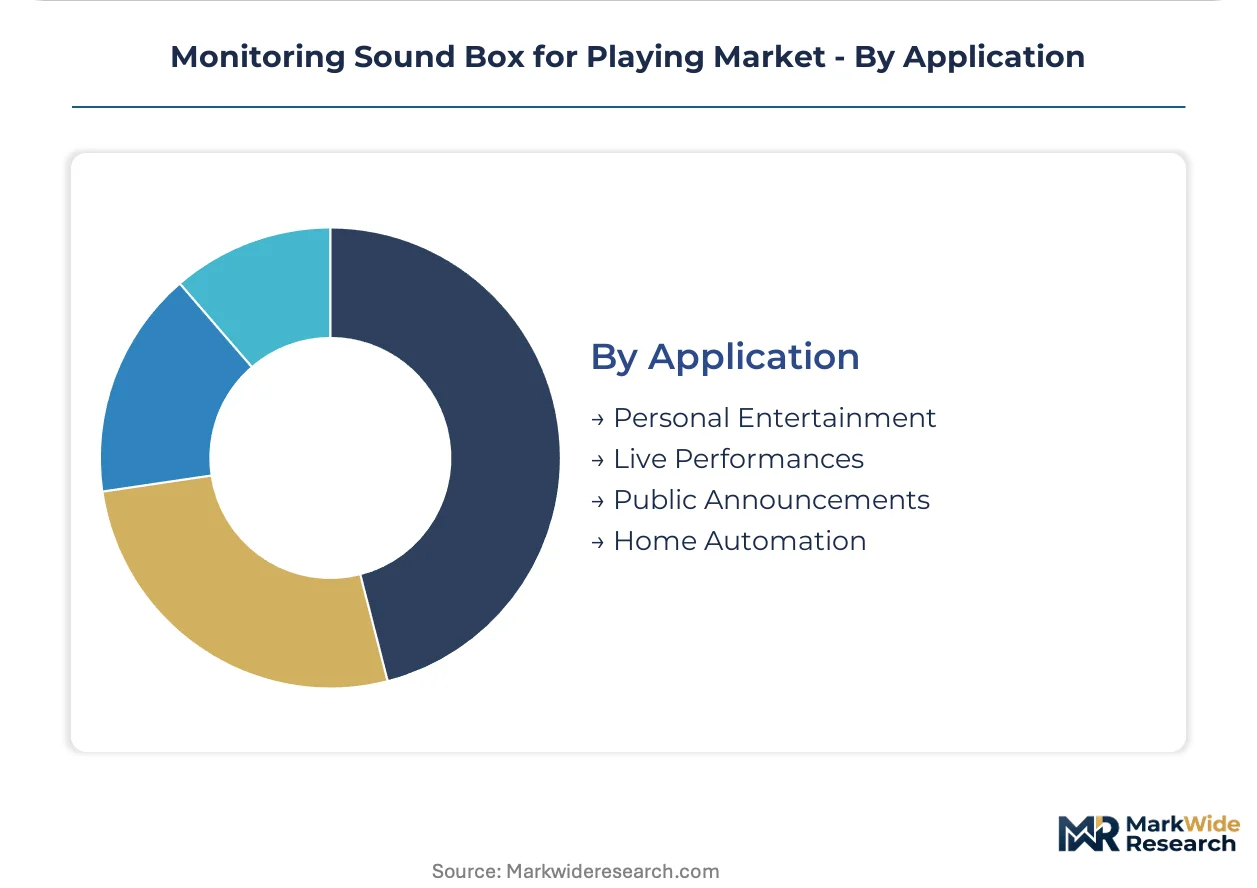
- Personal Entertainment:Consumer-grade listening with emphasis on bass enhancement and streaming service compatibility. Volume concentrates in urban United States households.
- Live Performances:Stage monitoring with feedback rejection and high SPL capability. Tour operators in Germany prioritize road-case durability and rapid deployment.
- Public Announcements:Voice intelligibility optimization for transportation and institutional venues. Clarity at distance drives horn-loaded designs.
- Home Automation:Multi-room synchronization with smart home platform integration. Growth moderates as smart speaker penetration saturates Japanese and United States markets.
Personal entertainment leads by unit volume. Live performances demonstrate the most rapid climb in professional-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and Germany accept substantial premiums for reference-grade accuracy, while price elasticity remains highest among consumer segments in urban United States markets where streaming convenience dominates purchase logic.
United States
Post-production facilities in Los Angeles and New York generate upgrade cycles for Dolby Atmos multi-channel arrays. FCC Part 15 emissions testing constrains wireless transmission architectures for products entering the market. Nashville's music production cluster sustains replacement demand for nearfield monitors with room-correction capabilities.
Germany
Project studio proliferation in Berlin and Hamburg drives adoption of Wi-Fi 6E-enabled monitoring systems. EU Green Deal material mandates under REACH accelerate reformulation of enclosure polymers and solder alloys. Munich's broadcast engineering sector concentrates procurement volume for road-worthy stage monitor enclosures.
Japan
Audio engineers in Tokyo and Osaka command premium pricing for extended frequency response and precise stereo imaging. METI enforces energy-efficiency benchmarks that shape amplifier topology selections for units sold domestically. Kyoto's traditional instrument recording studios generate specialized demand for flat-response monitoring in climate-variable environments.
India
Film scoring migration to Mumbai and Chennai creates demand for reference-grade monitoring infrastructure. The country's national electronics regulator enforces BIS certification requirements for wireless audio equipment. Bangalore's emerging podcast production cluster sustains entry-level procurement for Bluetooth-enabled project studio applications.
United Kingdom
Mastering engineers in London sustain demand for certified calibration services and proprietary room-correction software. CE marking requirements under the EU Radio Equipment Directive influence product development cycles for manufacturers accessing European markets. Manchester's independent music production sector concentrates price-sensitive procurement for nearfield monitor replacements.
Monitoring Sound Box for Playing Market Competitive Landscape
Professional audio specialists and diversified consumer electronics conglomerates split the market into distinct margin tiers. The vendor base concentrates around three strategic archetypes: legacy pro-audio houses with service network depth, consumer electronics giants leveraging scale economics, and boutique manufacturers competing on acoustic engineering reputation. Consolidation pressure intensifies as wireless latency reduction protocols commoditize hardware differentiation. Incumbent players defend position through recurring calibration service contracts and proprietary DSP ecosystem lock-in.
Within the legacy pro-audio tier, Yamaha and Genelec exemplify divergent approaches to capturing aftermarket value. KRK occupies a position at the aggressive price-performance intersection where project studio budgets constrain premium positioning. These three anchors illustrate how competitive strategy fragments across service intensity, software bundling, and cost engineering vectors.
| Leading Market Players |
|---|
| Yamaha |
| JBL |
| Bose |
| KRK |
| Mackie |
| Genelec |
| Sennheiser |
| Logitech |
| Harman International |
| Others |
Pricing and Supply Chain Analysis
Neodymium magnet supply concentration in China directly determines margin predictability for driver manufacturers, compressing pricing power at the component tier while aftermarket calibration services capture expanded lifetime value pools downstream.
Pricing Analysis
Aftermarket service revenue for calibration and acoustic tuning drives lifetime value capture in this market. Three-tier pricing structure across premium, standard, and economy levels separates certified reference monitors from project-studio workhorses from entry-level Bluetooth units. Cost compression in the driver assembly tier is intensifying because Chinese export quota volatility for rare earth magnets feeds raw material uncertainty into BOM calculations. Home users exhibit the steepest price sensitivity, while audio engineers in post-production facilities accept substantial premiums for extended frequency response and proprietary room-correction bundling.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment constrain Taiwanese foundry capacity expansion for Class-D power management ICs. Driver magnet assemblies draw from Chinese neodymium processing, Japanese ferrite ceramic supply, and Malaysian coil winding operations. Enclosure polymers face REACH SVHC reformulation mandates that extend lead times for EU-bound shipments. Single-source vulnerability concentrates in the 6 GHz Wi-Fi chipset tier where Qualcomm and MediaTek dominate professional-grade module supply. Distribution runs through authorized dealer networks for professional segments and mass retail channels for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized acoustic engineering talent scarcity constrains service network expansion, creating defensive moats for incumbents with certified calibration ecosystems while opening white-space opportunities for technology-enabled entrants.
For Market Incumbents: Build proprietary DSP ecosystem lock-in by bundling cloud-connected room analysis platforms with hardware sales, converting transactional monitor purchases into recurring subscription revenue streams. Deepen backward integration into driver magnet supply through long-term offtake agreements with Chinese processors to buffer neodymium price volatility. Wireless latency reduction protocols threaten hardware differentiation; defend installed-base relationships through multi-year maintenance contracts that third-party acousticians cannot match. For New Entrants and Emerging Players: Build out standalone measurement microphone and third-party DSP plugin offerings targeting North American project studios where independent operators resist locked ecosystem packages. Underpenetrated climate-variable environments in Mumbai and Chennai present the most penetrable geography for reference-grade monitoring infrastructure. Pursue direct-to-audio-engineer digital marketing bypassing traditional dealer markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed pro-audio specialists that consolidated regional service networks during the analog-to-digital transition. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Monitor Wi-Fi 6E chipset cost curves as the inflection signal for wireless substitution tipping points in critical listening applications.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Calibration Service Launch | Shifts Yamaha and Genelec revenue models toward recurring maintenance streams with 90%+ gross margins. |
| REACH-Compliant Material Reformulation | European OEMs face 12-18% unit cost increases for aluminum and bamboo-fiber composite housings. |
| Wi-Fi 6E Module Integration | Sub-10 millisecond latency protocols satisfy broadcast engineers in Japan previously restricted to wired systems. |
| India Studio Infrastructure Partnership | Film scoring migration to Mumbai generates demand for climate-resistant reference monitoring arrays. |
| Acoustic Engineer Certification Program | Addresses talent scarcity constraining service network expansion for room-correction deployment. |
Research Methodology
Desk research of FCC Part 15 filings, METI energy-efficiency registrations, and REACH SVHC candidate list expansions preceded structured interviews with audio engineering directors, acoustic calibration specialists, OEM procurement leads, and broadcast facility technical managers. Secondary validation drew from customs trade data for driver magnet flows, SEC 10-K disclosures from diversified electronics conglomerates, and EU Radio Equipment Directive conformity assessment timelines. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across professional and consumer tiers.
Assumptions held fixed include sustained 6 GHz spectrum allocation in major markets and continued Chinese rare earth export quota administration; variables stress-tested encompass Wi-Fi 7 protocol adoption curves and alternative magnet material substitution rates. Segmentation modeling spanned product form factor, end-user professional tier, wireless transmission protocol, and regional regulatory cluster. CAGRs were derived from regression analysis of historical replacement cycles and projected upgrade demand for spatial audio production workflows.
Stress conditions across neodymium price bands, Taiwanese foundry utilization rates, and EU Green Deal compliance deadlines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that unilateral spectrum reallocation decisions or REACH substance list expansions could materially revise trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Audio Kits Market
Audio Equipment
Mixing Console Market
Audio Equipment
Japan Gaming Headset Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
India Consumer Speaker Market
Audio Equipment
India Wireless Speaker Market
Audio Equipment
Smart Audio System Market
Audio Equipment
Home Audio Equipment Market
Audio Equipment
Speaker Cabinets, Grilles and Materials Market
Audio Equipment
Guitar Head Amplifiers Market
Audio Equipment
Gaming Earbuds Market
Audio Equipment
Wireless Audio Devices Market
Audio Equipment
Germany Radio Headset Market
Audio Equipment
Clip-On Headphones Market
Audio Equipment
Digital a/V Decoder Market
Audio Equipment
North America Gaming Headsets Market