
 Audio Interface Market | 2026-2036
Audio Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Interface Market Intelligence
The capability gap between high-volume, low-cost manufacturing and specialized, high-margin DSP-accelerated hardware is reorganizing the competitive landscape. Universal Audio leverages its proprietary UAD platform to dominate the premium studio segment. In contrast, Behringer competes aggressively on price through its massive production scale. Focusrite sustains its market leadership by offering a wide range of interfaces for both entry-level and professional users.
An audio interface is an external hardware device that facilitates the conversion of analog audio signals into digital data for computer processing. These units contain preamplifiers and analog-to-digital converters, often supporting high-resolution formats like 24-bit/192kHz. USB-based products command the largest market share due to their universal compatibility and ease of use. Within applications, music production remains the core segment, while podcasting and live performance represent the fastest-growing areas of adoption by musicians and sound engineers.
Compliance with electromagnetic compatibility standards, such as FCC regulations in the United States and CE marking in Europe, is mandatory for market access. The EU's RoHS directive also influences material selection and supply chain management by restricting hazardous substances in electronic equipment. Future product differentiation will hinge on integrating lower latency drivers, superior converter technology, and expanded software-hardware ecosystem value.
Market Dynamics
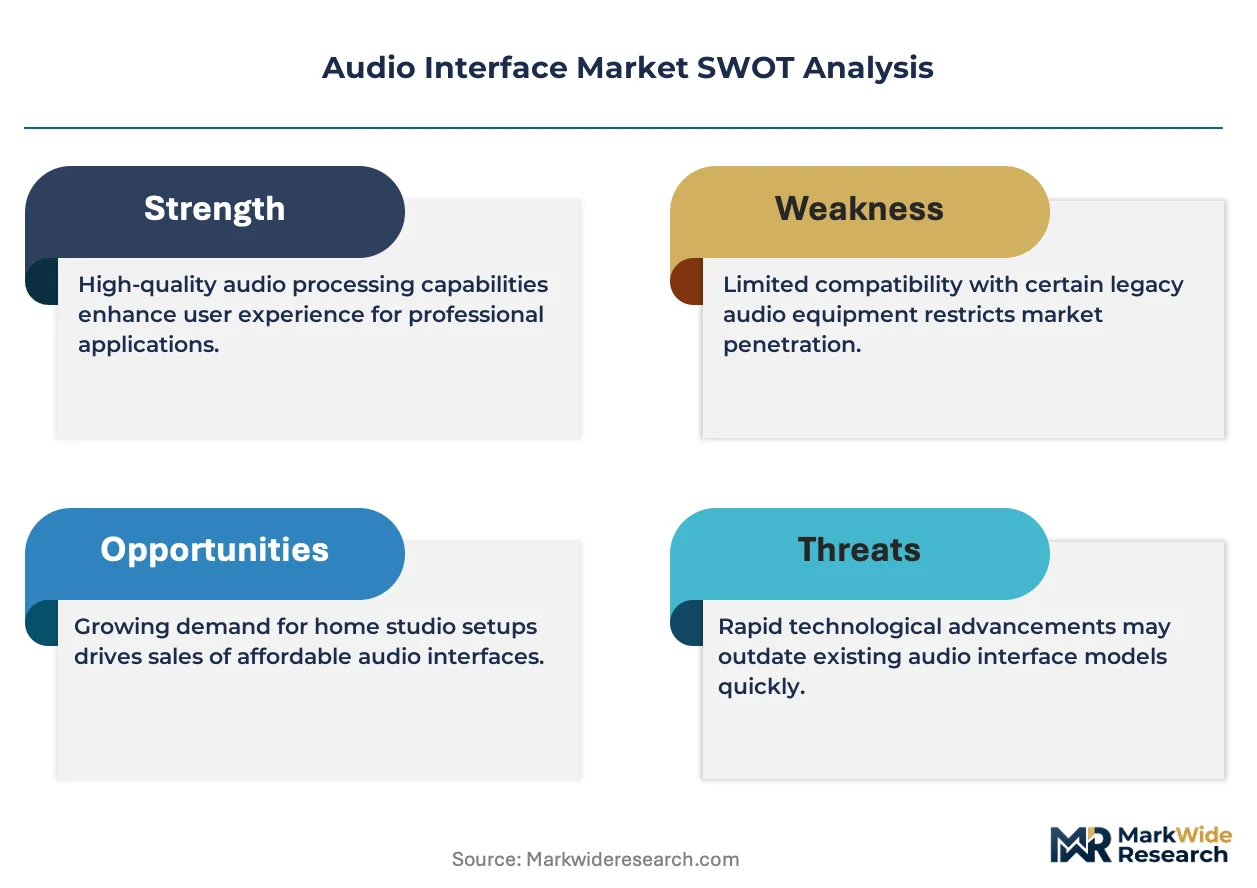
The widespread adoption of high-bandwidth connectivity standards, particularly USB-C and Thunderbolt, is the central force reshaping the audio interface market. This technological democratization fuels demand from an expanding base of content creators, from home studios to professional podcasting networks.
Growth Catalysts
- Creator Economy Expansion:The growth of podcasting and video streaming platforms creates sustained demand for user-friendly, high-fidelity audio capture devices among semi-professional and prosumer content creators across North America and Europe.
- Onboard DSP Acceleration:Onboard Digital Signal Processing allows for zero-latency monitoring with effects, a critical feature for professional recording artists and producers that drives upgrades from non-DSP units.
- Home Studio Proliferation:A structural shift toward remote work and independent music production, particularly in the United States and Germany, accelerates investment in professional-grade home studio equipment, including multi-channel interfaces.
Market Restraints
- Converter Chip Scarcity:Supply chain concentration for high-performance analog-to-digital (A/D) and digital-to-analog (D/A) converter chips creates vulnerability to price volatility and allocation constraints, impacting production schedules for manufacturers.
- Driver and Software Instability:Inconsistent driver performance and software compatibility issues, especially across different operating systems and digital audio workstations, can lead to high support costs and damage brand reputation among professional users.
- Integrated Device Substitution:The growing capability of digital mixers and standalone field recorders with built-in USB audio interface functionality presents a substitution threat, particularly in live sound and location recording applications.
Strategic Opportunities
- Immersive Audio Production:The rise of spatial audio formats like Dolby Atmos for music and gaming creates a need for interfaces with higher channel counts and specialized monitoring outputs, opening a new premium product category.
- Networked Audio Integration:Integrating standards like Dante or AVB into mid-tier interfaces offers a pathway to serve educational institutions and small-to-medium-sized performance venues, expanding beyond the traditional studio.
- Eco-Design Mandates:Proactively designing products that comply with future-state EU eco-design regulations and right-to-repair initiatives can become a competitive advantage for accessing European institutional and government tenders.
Industry Challenges
- Electromagnetic Compatibility Compliance:Navigating complex testing protocols for FCC and CE marking for high-speed digital devices is a significant engineering and administrative burden that can delay market entry for new products.
- Software Ecosystem Lock-in:The reliance on proprietary DSP platforms and bundled software creates challenges for third-party plugin developers and can limit interoperability, a growing concern for users with multi-brand setups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Interface Market |
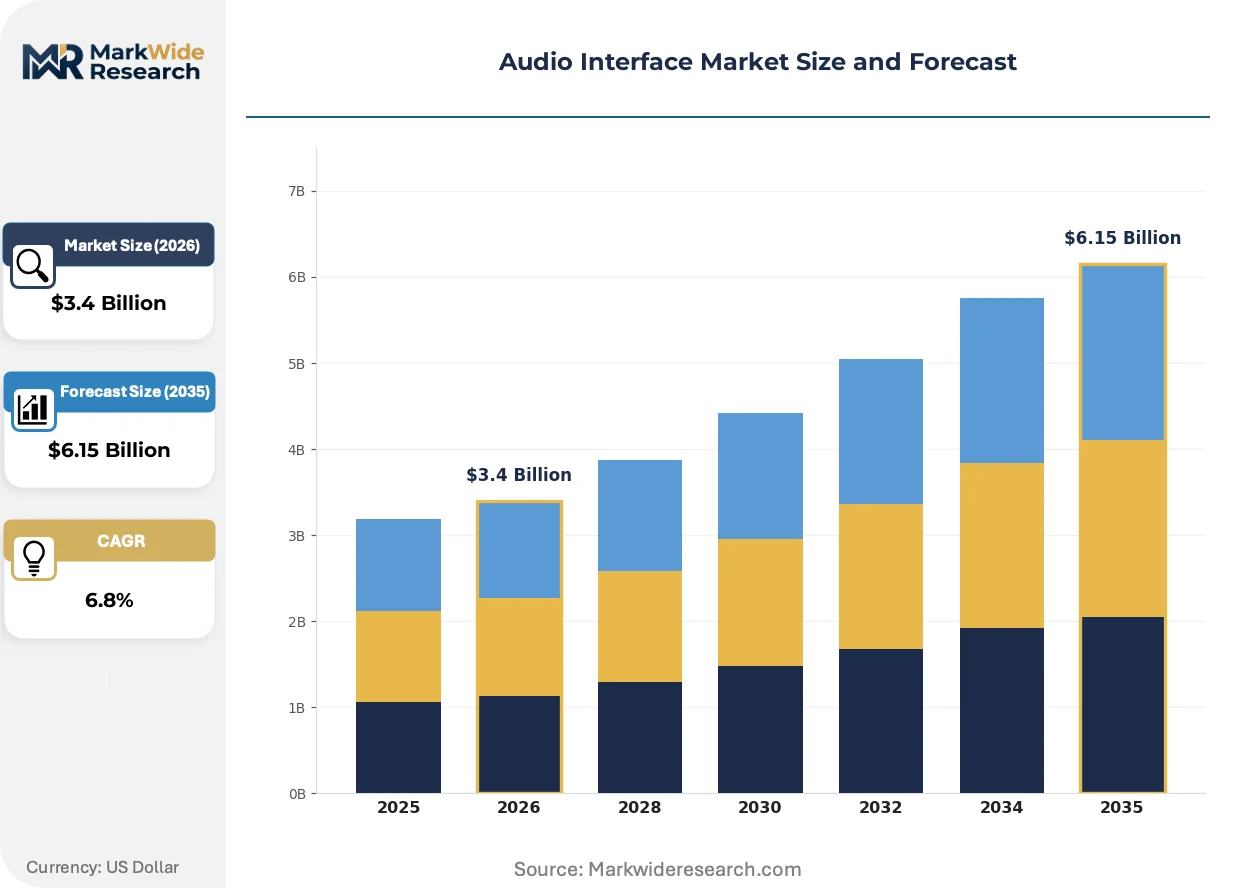
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB, Thunderbolt, FireWire, PCIe, Dante, MADI Connectivity: XLR, TRS, RCA, ADAT, S/PDIF, MIDI Application: Music Production, Podcasting, Live Performance, Broadcasting, Film Scoring, Voice-over End User: Musicians, Sound Engineers, Radio Stations, Recording Studios, Post-production Houses, Audiovisual Professionals |
| Companies Covered | Audient, M-Audio, Focusrite, SSL, IK Multimedia, Universal Audio, Behringer, Antelope Audio, RME, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Interface Market Strategic Shifts & Innovations
Software ecosystems are fundamentally altering the value proposition of audio interface hardware. The focus is shifting from standalone converter quality to the depth and exclusivity of the bundled software, plugins, and DSP-powered workflows that define the user experience.
The adoption of the USB-C connector unifies physical connectivity but creates divergence in underlying protocol support. Devices can support basic USB 2.0 or advanced Thunderbolt 4 protocols via the same port. This dual-protocol reality is fragmenting the market into distinct performance tiers, forcing buyers to scrutinize specifications beyond the connector.
Compliance with the European Union's RoHS directive dictates material selection for electronic equipment, restricting hazardous substances like lead in solder. This regulation requires significant supply chain verification and investment in alternative materials. Manufacturers targeting the German and French markets are most affected, often redesigning products to meet these environmental standards.
A shift from perpetual software licenses to subscription models for bundled DAWs and plugins is underway. This model disrupts the traditional one-time purchase value proposition, making the ongoing cost of ownership a key factor in the hardware decision. The trend is most pronounced among entry-level creators in the United States, who are accustomed to subscription services.
Audio Interface Market Segmentation
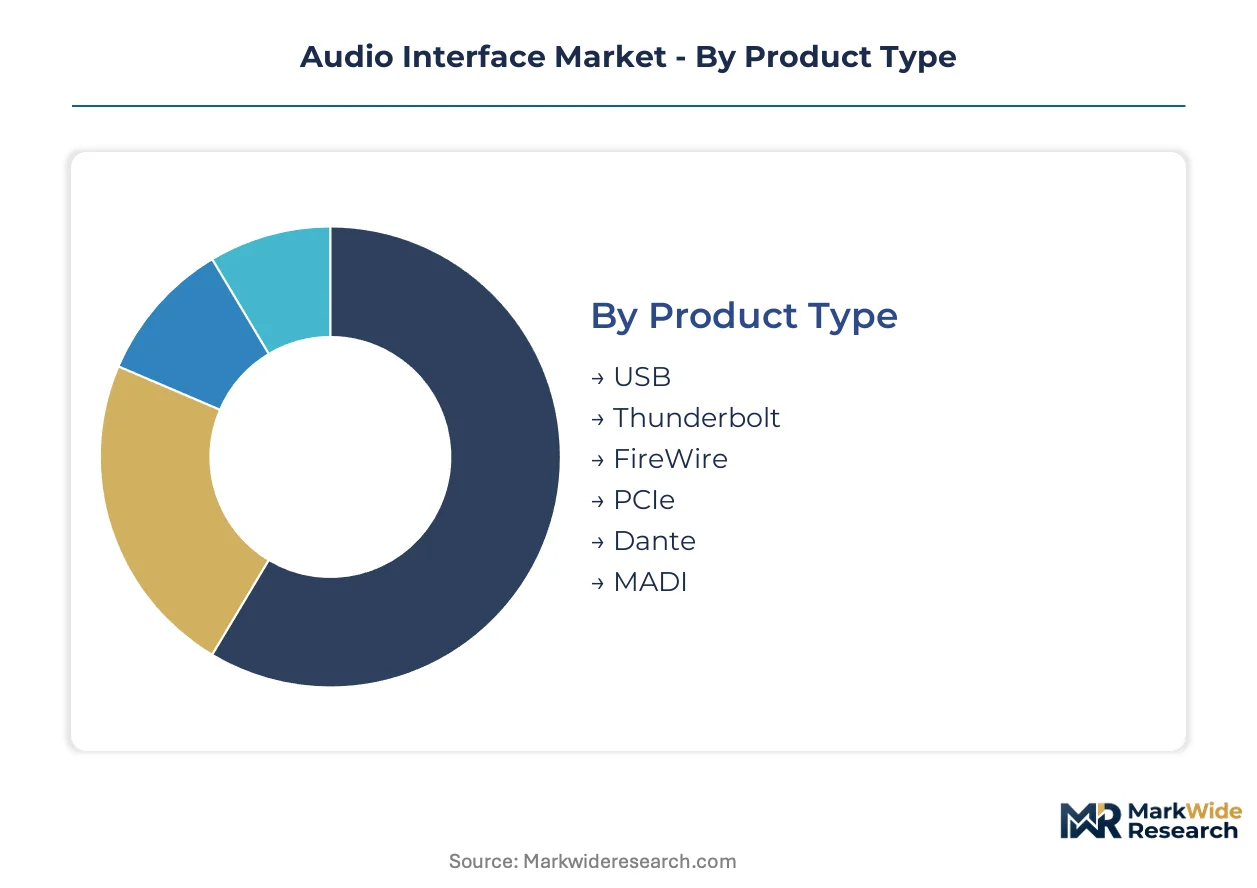
Understanding the distinct segments within the audio interface market is critical for manufacturers to tailor product development and market strategies. This segmentation analysis provides a granular view of how technologies, connectivity standards, applications, and user types shape demand and competitive dynamics.
Product Type:
The diverse product types of audio interfaces are distributed through distinct sales channels, serving varied user needs.
- USB:These interfaces leverage universal serial bus technology for data transfer, offering broad compatibility across computing platforms. Demand concentrates among home studio users and content creators in North America, driven by ease of use and widespread device support.
- Thunderbolt:Utilizing Intel's high-speed data transfer protocol, Thunderbolt interfaces provide extremely low latency and high channel counts for professional applications. Recording studios and post-production houses in Germany prioritize these units for their demanding workflow requirements.
- FireWire:Once prevalent for its low-latency performance, FireWire interfaces now occupy a niche market, primarily supporting legacy systems.
- PCIe:Internal PCI Express cards offer the lowest latency and highest channel counts, favored by high-end professional studios for maximum performance.
- Dante:This network audio protocol enables high-channel-count audio over standard Ethernet networks, serving live sound and broadcast environments.
- MADI:Multichannel Audio Digital Interface provides high-channel digital audio transfer over long distances, common in large-scale professional installations.
By volume, USB products lead. By growth pace, Thunderbolt interfaces represent the fastest-growing trajectory.
Connectivity:
Different connectivity options cater to specific customer segments, from home users to professional studios.
- XLR:These three-pin connectors are the industry standard for balanced microphone and line-level signals, ensuring signal integrity in professional recording environments. Demand for XLR inputs is universal across all professional and semi-professional audio users, particularly in the United States.
- TRS:Tip-Ring-Sleeve connectors handle balanced line-level signals, common for connecting studio monitors, synthesizers, and outboard gear. Musicians and sound engineers value TRS for its versatility in routing various audio signals within a studio setup.
- RCA:Consumer-grade unbalanced connectors are typically found on entry-level interfaces for connecting consumer audio equipment.
- ADAT:This optical format provides eight channels of digital audio over a single cable, used for expanding input/output counts on interfaces.
- S/PDIF:Sony/Philips Digital Interface Format carries two channels of digital audio, often used for connecting digital effects units or CD players.
- MIDI:Musical Instrument Digital Interface ports enable communication between digital musical instruments and computers, essential for electronic music production.
Each connection type offers unique advantages, determining its suitability for specific audio workflows.
Application:
Demand concentration for audio interfaces varies significantly across different applications.
- Music Production:This application involves recording, editing, and mixing musical performances, forming the core demand for multi-channel interfaces and high-quality preamps. Professional studios and independent artists globally drive this segment, seeking pristine audio capture.
- Podcasting:Recording and editing spoken word content for online distribution drives demand for user-friendly interfaces with clear microphone inputs and simple monitoring. Content creators in the United States and Europe increasingly adopt dedicated audio interfaces for improved sound quality.
- Live Performance:Interfaces facilitate routing audio from instruments and microphones to front-of-house systems and recording devices during concerts.
- Broadcasting:Radio and television studios utilize interfaces for transmitting high-fidelity audio signals for live and pre-recorded programming.
- Film Scoring:Composers and sound designers employ interfaces for recording instruments and integrating virtual instruments into film soundtracks.
- Voice-over:Recording professional voice narration for commercials, audiobooks, and corporate videos requires interfaces with high-quality microphone preamps.
These application areas directly influence the required channel counts and feature sets of audio interface hardware.
End User:
End-user segments often dictate the acceptable price points and margin structures for audio interface manufacturers.
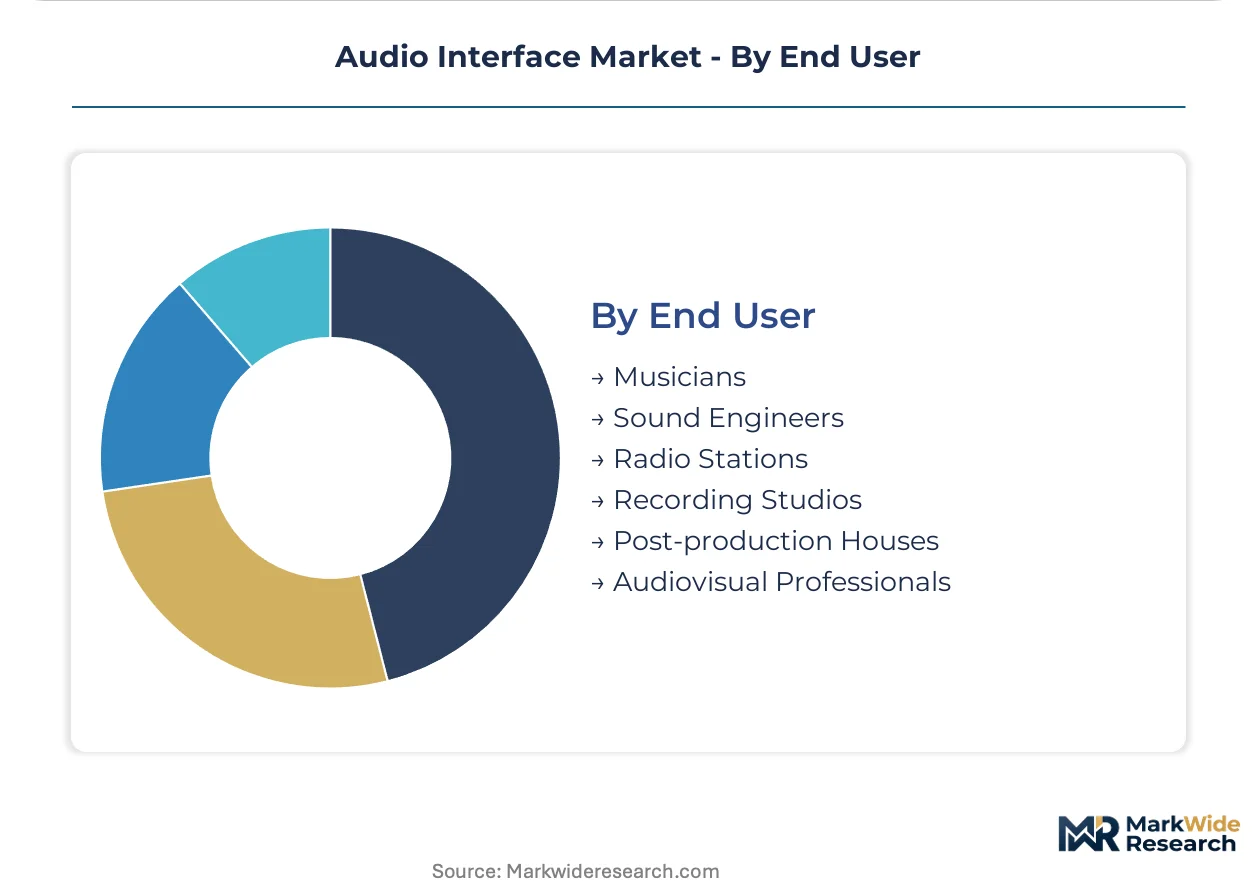
- Musicians:This broad category includes hobbyists, semi-professional artists, and professional session players who require interfaces for recording instruments and vocals. Independent musicians across North America and Europe represent a substantial and expanding user base.
- Sound Engineers:Professionals responsible for recording, mixing, and mastering audio in studios or live environments demand high-performance, multi-channel interfaces with robust drivers. Recording studios in Germany rely on specialized engineers to manage complex audio setups.
- Radio Stations:Broadcasting entities use interfaces for integrating studio microphones, playback systems, and broadcast consoles.
- Recording Studios:Commercial and project studios invest in a wide range of interfaces to accommodate diverse client needs and production scales.
- Post-production Houses:Facilities specializing in audio for film, television, and games require interfaces for dialogue editing, sound design, and mixing.
- Audiovisual Professionals:These users integrate audio interfaces into larger AV systems for events, installations, and corporate presentations.
Future innovation in audio interfaces will increasingly target the specific workflow demands of these distinct end-user groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry characterizes the audio interface market, with premium demand in the United States contrasting with volume-driven manufacturing in Asia. Significant variations in market maturity and regulatory environments shape product adoption and competitive strategies. This dynamic influences both hardware development and software ecosystem integration across continents.
United States
The United States drives demand for user-friendly, high-fidelity audio capture devices, particularly from the expanding creator economy and home studio proliferation. FCC regulations mandate electromagnetic compatibility for all electronic devices sold within the country. Major media production hubs in Los Angeles and New York City concentrate professional studio investment and innovation in multi-channel interfaces.
Germany
German professional and semi-professional users prioritize Thunderbolt interfaces for demanding studio workflows, reflecting the country's large media production industry. CE marking compliance is mandatory for market access, influencing material selection and design for European distribution. Recording studios in Berlin and Munich rely on specialized engineers managing complex audio setups.
Japan
Japan exhibits strong demand for high-resolution audio formats and superior converter technology, particularly among audiophiles and music producers. METI guidelines influence electronic product design and material sourcing within the country. Tokyo's vibrant music scene and extensive post-production houses drive innovation in compact, high-performance audio interfaces.
China
China's market experiences robust growth in entry-level and mid-tier audio interfaces, fueled by a rapidly expanding content creation segment. GB standards ensure product safety and quality for domestic consumption and export. Manufacturing centers in Shenzhen and Guangzhou support massive production scales for consumer-grade audio equipment.
Audio Interface Market Key Industry Players
Concentration sits with specialized hardware manufacturers offering proprietary DSP platforms and premium features, alongside volume-driven players competing on price and accessibility. The market exhibits a tiered structure, with a few dominant brands in the professional segment and numerous smaller players in the entry-level space. Strategic archetypes include innovation-led premium providers, cost-efficient mass producers, and broad-portfolio generalists. Companies are increasingly focusing on strategic partnerships to expand software ecosystems and portfolio diversification to capture new user segments.
On the premium-tier vector, Universal Audio exemplifies leadership in DSP-accelerated hardware, anchoring advanced studio workflows with its proprietary platform. In contrast, Behringer represents the aggressive price-point segment, leveraging massive production scale for broad market penetration across diverse user groups. Focusrite, a UK-based entity, occupies a significant position as a generalist, offering a comprehensive range of interfaces for both entry-level and professional user needs. These companies collectively illustrate the market's stratification by performance and cost-effectiveness.
| Leading Market Players |
|---|
| Audient |
| M-Audio |
| Focusrite |
| SSL |
| IK Multimedia |
| Universal Audio |
| Behringer |
| Antelope Audio |
| RME |
| Others |
Cost & Logistics Intelligence
Massive production scale across consumer electronics manufacturing underpins global audio interface supply, dictating price floors for entry-level units and influencing component availability for specialized hardware. This scale shapes both supply concentration and competitive pricing across all tiers.
Pricing Analysis
Configured-to-order pricing for high-channel, DSP-accelerated interfaces contrasts sharply with standard pricing for mass-market USB units. The dominant pricing structure is tiered premium-mid-economy, reflecting performance and feature sets. Price differentiation stems from converter quality and software ecosystem depth, with brand premium also playing a role. Pricing pressure stems from aggressive competition in the entry-level segment, particularly from manufacturers in China. Entry-level content creators in North America exhibit the highest price sensitivity, while professional studios in Germany prioritize performance over cost.
Supply Chain Analysis
Converter chip scarcity creates a critical chokepoint for high-performance audio interfaces, impacting production schedules globally. Geographic supply concentration for these specialized A/D and D/A chips centers on Taiwan and South Korea. Key component dependencies include digital signal processors, high-speed connectivity controllers, and specialized preamplifier ICs. Single-source vulnerability for advanced silicon represents a significant structural risk. Distribution runs through a mix of online retailers, pro audio dealers, and direct-to-consumer channels, with regional variations in channel dominance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market capability scarcity exists in integrating advanced DSP with robust, low-latency driver development, which represents a significant barrier to entry for new players. This gap creates opportunities for focused investment.
For Market Incumbents: Fortify proprietary DSP platforms and software ecosystems to deepen user lock-in, countering the threat of integrated device substitution. Invest in next-generation converter technology and lower-latency driver R&D to maintain performance leadership. Control over critical component supply, such as high-performance A/D and D/A converters, offers a strategic lever against supply chain volatility.
For New Entrants and Emerging Players: Lead with niche applications like immersive audio production or networked audio integration, targeting underserved segments. Focus on user-friendly interfaces with robust, cross-platform driver support to penetrate the semi-professional content creator market in Europe. A strong go-to-market angle involves bundling high-value, third-party software plugins that are not tied to proprietary DSP platforms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among companies offering subscription-based software bundles or UAD-like DSP platforms. Long-term viability favors entities capable of vertically integrating key component production or securing exclusive supply agreements for high-performance chips. The signal to watch is the adoption rate of spatial audio formats, indicating a shift towards higher channel count interface demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand DSP-Accelerated Ecosystem | Enhances competitive differentiation and user loyalty through unique processing capabilities. |
| Secure Converter Chip Supply | Mitigates production risks and ensures consistent availability of high-performance units. |
| Develop Immersive Audio Solutions | Captures new premium product categories driven by spatial audio formats like Dolby Atmos. |
| Integrate Networked Audio Protocols | Opens new market segments within educational institutions and performance venues for mid-tier products. |
| Invest in Eco-Design Compliance | Positions products favorably for future EU tenders and strengthens brand reputation among environmentally conscious buyers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and technical specifications. This approach involved extensive interviews with recording engineers, music producers, hardware designers, and pro audio retailers. The analysis triangulates these insights to form a comprehensive market perspective.
Segmentation dimensions modeled include product type, connectivity, application, and end-user, along with an industry-specific focus on DSP acceleration capabilities. This framework projects market evolution across the analysis window. Compound Annual Growth Rates (CAGRs) were derived from historical data analysis and projected demand trends, with key forecast inputs including content creation growth rates and technological adoption curves.
The analysis sits within stated boundaries; outcomes outside significant shifts in global semiconductor supply or major regulatory changes would require recalibration. Forecasts reflect assumptions regarding technological progression and market dynamics. Practitioners should keep alternative scenarios live as component availability and connectivity standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Professional Audio-Visual Systems Market
Audio Equipment
Germany Radio Headset Market
Audio Equipment
Gaming Headsets and Gaming Headphones Market
Audio Equipment
Wireless Audio Products Market
Audio Equipment
India Wireless Speaker Market
Audio Equipment
United States Gaming Headsets Market
Audio Equipment
Portable Audio Amplifier Market
Audio Equipment
Electronic Drums Market
Audio Equipment
Japan Gaming Headset Market
Audio Equipment
Digital a/V Decoder Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Amps & Effects Market
Audio Equipment
Monitoring Sound Box for Playing Market
Audio Equipment
Professional Microphones Market
Audio Equipment
Gaming Earbuds Market
Audio Equipment
Commercial Microphone Market