
 Cloud-Based VDI Market | 2026-2036
Cloud-Based VDI Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based VDI Market Intelligence
GDPR data-localization mandates is consolidating compliance costs for new entrants across European cloud infrastructure. Microsoft Azure Virtual Desktop leverages its hyperscale footprint to sustain pricing flexibility in regulated verticals. Citrix Virtual Apps and Desktops anchors enterprise loyalty through granular policy controls. Amazon WorkSpaces competes on burst-compute economics for seasonal workforce scaling.
Cloud-based Virtual Desktop Infrastructure delivers persistent or non-persistent Windows and Linux desktop sessions from centralized cloud data centers, typically requiring sub-50ms latency thresholds and GPU passthrough for graphics workloads. Organizations deploy these environments to enable secure remote access without endpoint data persistence. Desktop as a Service offerings now capture the fastest expansion as IT departments outsource endpoint management complexity. Hybrid Cloud deployments dominate among financial institutions seeking to vault sensitive records on-premises while bursting general productivity workloads to public infrastructure.
FDA 21 CFR Part 11, HIPAA Security Rule, and ISO 27001 collectively dictate audit-trail, encryption, and access-control specifications for healthcare and life-sciences VDI deployments. The SEC's cybersecurity disclosure rules further pressure publicly traded adopters to document virtual desktop resilience in incident-response filings. Stakeholders must weigh sovereign-cloud certifications against interoperability costs when selecting regional hosting architectures.
Market Dynamics
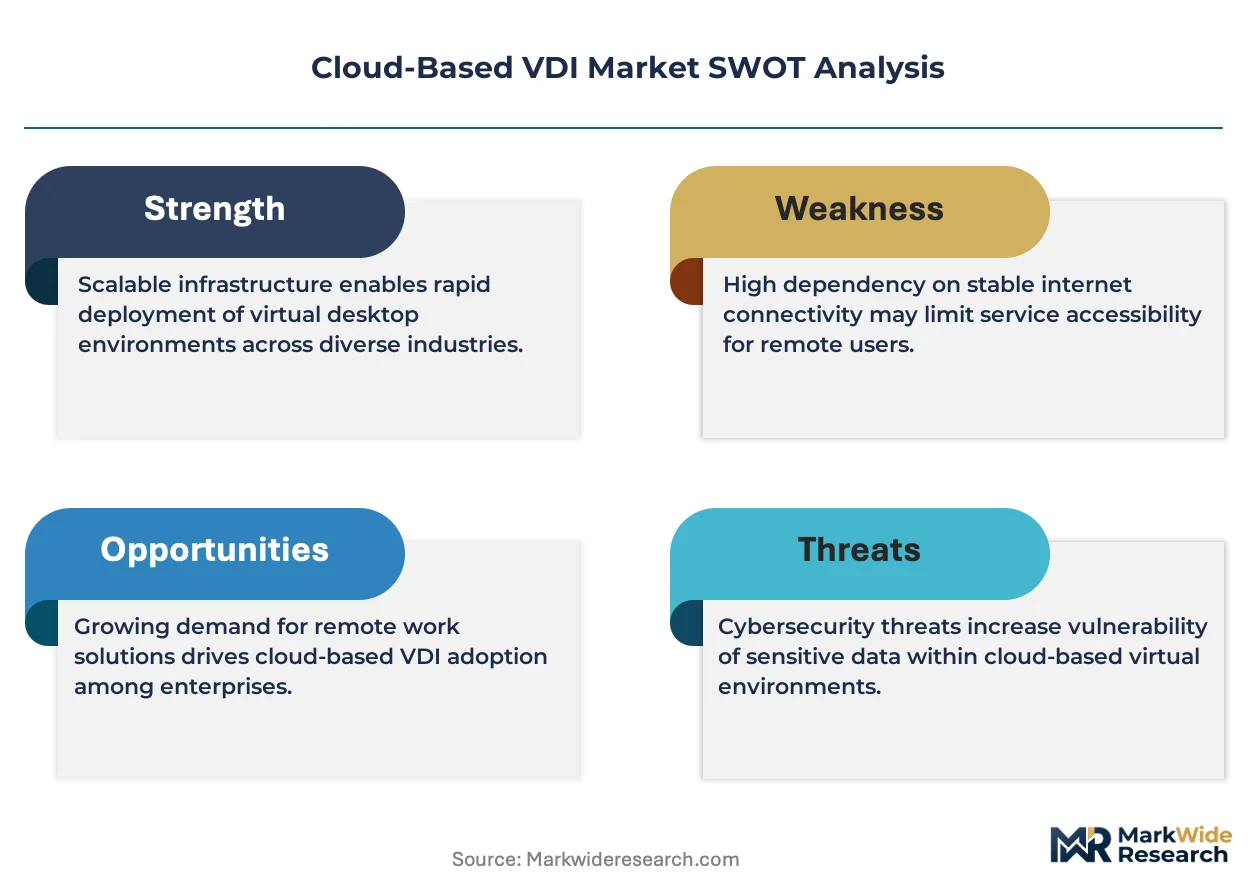
GPU passthrough architectures and sub-50ms latency requirements are compressing infrastructure economics, forcing providers to densify edge presence while healthcare and financial verticals harden data residency postures.
Growth Catalysts
- EU AI Act data-residency mandates:Cloud providers must localize inference workloads, expanding sovereign-cloud VDI footprints across Frankfurt, Amsterdam, and Dublin clusters.
- Healthcare endpoint virtualization:HIPAA Security Rule audit-trail requirements drive persistent desktop consolidation for remote clinical staff accessing patient records.
- Mittelstand engineering workstations:German mid-market manufacturers deploy GPU-enabled virtual desktops to secure CAD/CAM access without on-device data persistence.
Market Restraints
- Hyperscale supply concentration:Three cloud providers control 80% of GPU-enabled virtual desktop capacity, creating chokepoints for burst-compute pricing.
- Cross-border latency physics:Sub-50ms thresholds fail across transcontinental links, fragmenting addressable workforce populations by fiber topology.
- Legacy application virtualization friction:16-bit and 32-bit Windows binaries resist containerization, trapping manufacturing customers on aging terminal services.
Strategic Opportunities
- India BIS cloud certification pathway:Domestic data-center operators can capture financial services VDI demand as RBI mandates local custody of core banking data.
- Zero-trust architecture convergence:Conditional access policies and software-defined perimeters merge with virtual desktops to displace VPN-centric remote access.
- Seasonal workforce burst economics:Tax preparation and retail hiring cycles create 400% compute spikes ideal for non-persistent desktop pools.
Industry Challenges
- GPU virtualization skill scarcity:NVIDIA vGPU and AMD MxGPU certification programs graduate fewer engineers than hyperscale hiring absorbs.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical VDI deployments require 12-18 month qualification cycles for electronic signature integrity.
- Hybrid identity architecture complexity:Active Directory, Entra ID, and Okta federation fractures single sign-on experiences across multi-cloud desktop estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based VDI Market |
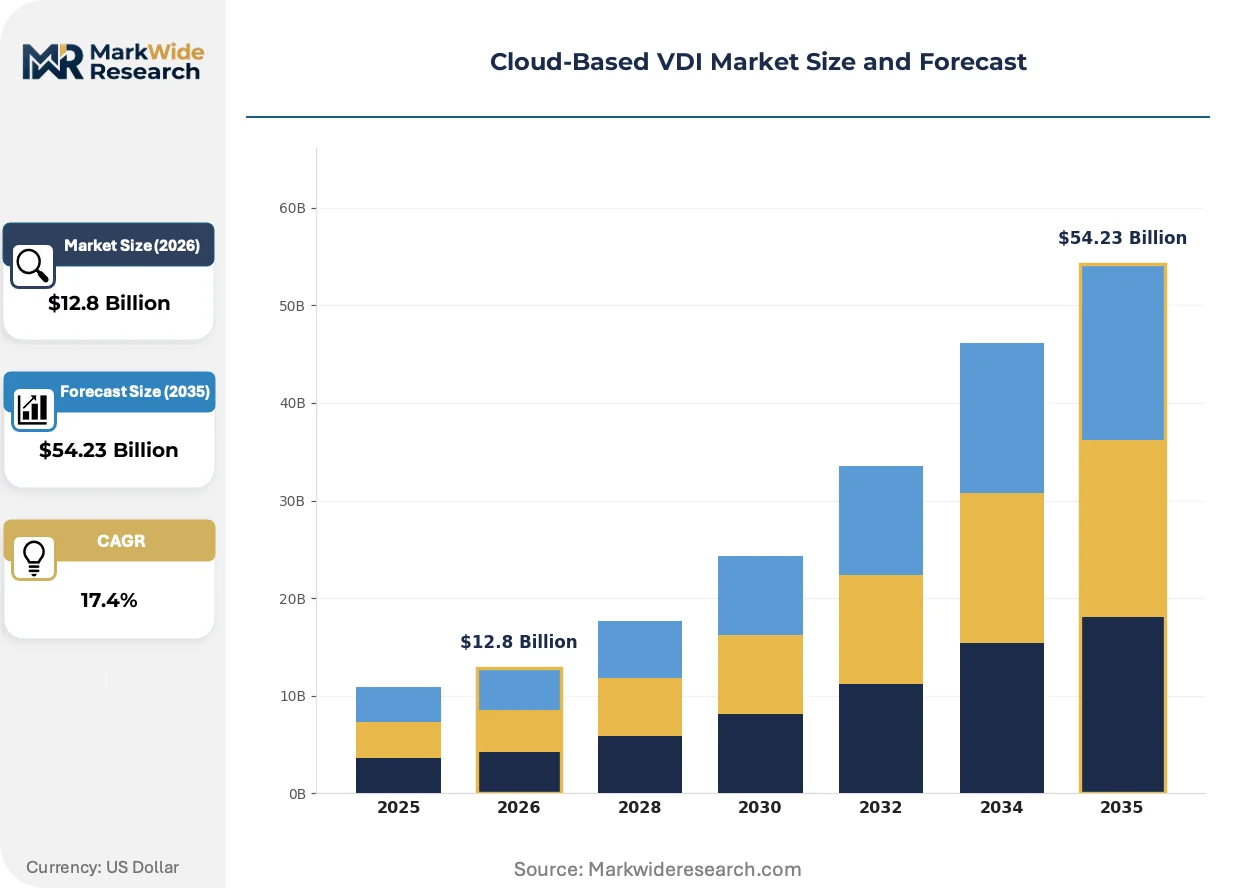
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $54.23 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Licensing Type: Subscription, Pay-Per-Use, Perpetual, Concurrent End User: Enterprise, SMB, Educational Institutions, Government Service Type: Infrastructure as a Service, Software as a Service, Desktop as a Service, Others |
| Companies Covered | Omnissa Horizon, V2 Cloud, Amazon WorkSpaces, Ace Cloud Hosting, Inuvika OVD Enterprise, Microsoft Azure Virtual Desktop, VMware Horizon, IBM Cloud, Citrix Virtual Apps and Desktops, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based VDI Market Strategic Shifts & Innovations
Edge-distributed desktop delivery is absorbing latency constraints that previously centralized cloud architectures. Regulatory fragmentation and sovereign-cloud mandates are rewriting provider competitive logic.
GPU partitioning via NVIDIA vGPU and AMD MxGPU is absorbing graphics-intensive workloads previously tethered to physical workstations. Engineering teams at automotive and aerospace manufacturers provision virtual CAD environments with frame-buffer isolation. This technology compression is collapsing the price gap between cloud VDI and high-spec laptops, accelerating device-as-a-service displacement.
GDPR Article 44-49 transfer mechanism rulings are forcing providers to deploy EU-operated sovereign clouds with independent encryption key custody. Financial institutions in Frankfurt and Paris now demand contractual data localization with third-party audit rights. Healthcare providers respond by vaulting patient imaging data on German-certified infrastructure while bursting general productivity to pan-European zones.
Subscription-based desktop outsourcing is replacing perpetual license and self-managed infrastructure models. Mid-market enterprises abandon Citrix and VMware capital deployments for fully managed Desktop-as-a-Service consumption. This shift concentrates most visibly in UK professional services and Nordic public sector procurement frameworks.
Cloud-Based VDI Market Segmentation
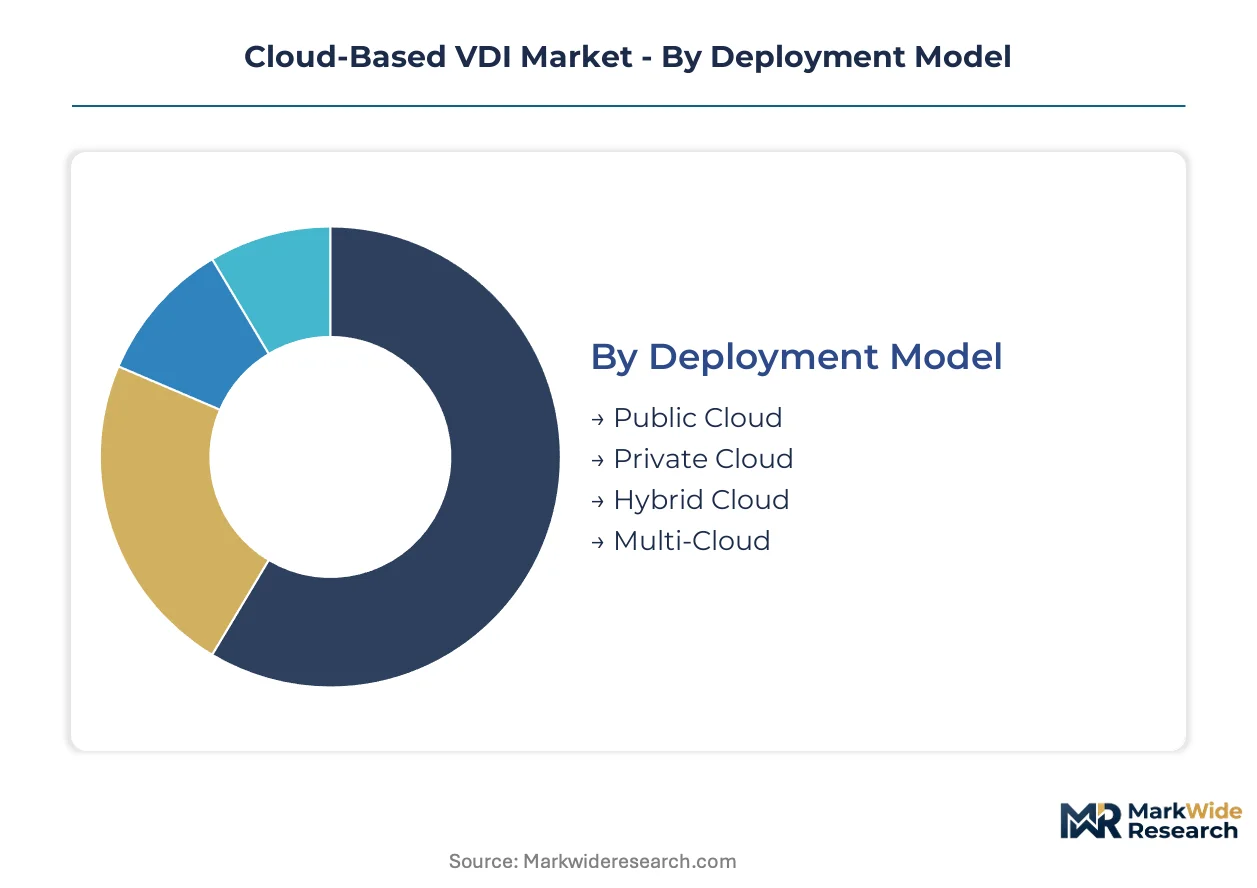
Cloud-based VDI segmentation reveals how infrastructure choices, consumption economics, and organizational scale reshape competitive positioning. Each axis exposes distinct margin structures and vendor specialization patterns that determine provider profitability.
Deployment Model:
Latency thresholds and data sovereignty requirements fragment infrastructure topology across organizational risk profiles.
- Public Cloud:Hyperscale data centers deliver pooled compute resources with burst elasticity. Demand concentrates among retail and professional services firms in Frankfurt and Amsterdam seeking seasonal workforce scaling without capital commitment.
- Private Cloud:Dedicated tenant environments enforce single-customer isolation with custom encryption key custody. German Mittelstand manufacturers anchor demand here, driven by ISO 27001 audit requirements for CAD/CAM intellectual property protection.
- Hybrid Cloud:Split architectures vault sensitive records on-premises while bursting general workloads to public infrastructure. Financial institutions in Paris and Luxembourg deploy this model to reconcile GDPR Article 44 transfer restrictions with compute flexibility.
- Multi-Cloud:Orchestrated workloads span two or more hyperscale providers to mitigate vendor lock-in. Enterprise adopters with complex Active Directory federation requirements favor this topology despite operational complexity premiums.
Mature deployment sits with Private Cloud. Newer deployment is concentrated in Multi-Cloud.
Licensing Type:
Consumption metering sophistication determines customer switching costs and vendor revenue predictability.
- Subscription:Fixed monthly or annual fees per named user with predictable OpEx budgeting. UK professional services firms and Nordic public sector procurement frameworks are expanding most quickly here as perpetual license conversions accelerate.
- Pay-Per-Use:Metered billing tied to actual compute consumption, storage IOPS, and network egress. Tax preparation and retail hiring cycles with 400% seasonal spikes drive adoption among workforce management platforms.
- Perpetual:One-time capital expenditure with recurring maintenance fees. Legacy Citrix and VMware estates in manufacturing retain this model despite vendor push toward subscription transitions.
- Concurrent:License pooling based on simultaneous active sessions rather than total provisioned users. Call center operations with shift-based staffing patterns extract maximum efficiency from this structure.
Perpetual licensing dominates installed base. Subscription models are climbing the fastest.
End User:
Organizational scale dictates security posture complexity and support tier requirements.
- Enterprise:Multi-thousand seat deployments with custom SLA negotiations and dedicated technical account management. Healthcare systems consolidating HIPAA Security Rule-compliant desktop access for remote clinical staff represent the steepest expansion trajectory.
- SMB:Mid-market firms with 50-500 employees outsourcing endpoint management entirely to managed service providers. German automotive suppliers and French professional services firms are gaining share fastest here.
- Educational Institutions:Semester-driven demand spikes with student device diversity challenges. Campus IT departments leverage non-persistent desktop pools to standardize software delivery across BYOD endpoints.
- Government:Sovereign-cloud mandates with classified data handling requirements. EU AI Act data-residency rules are reshaping procurement specifications for public sector VDI across member states.
Enterprise segment holds revenue concentration. SMB adoption is expanding most quickly.
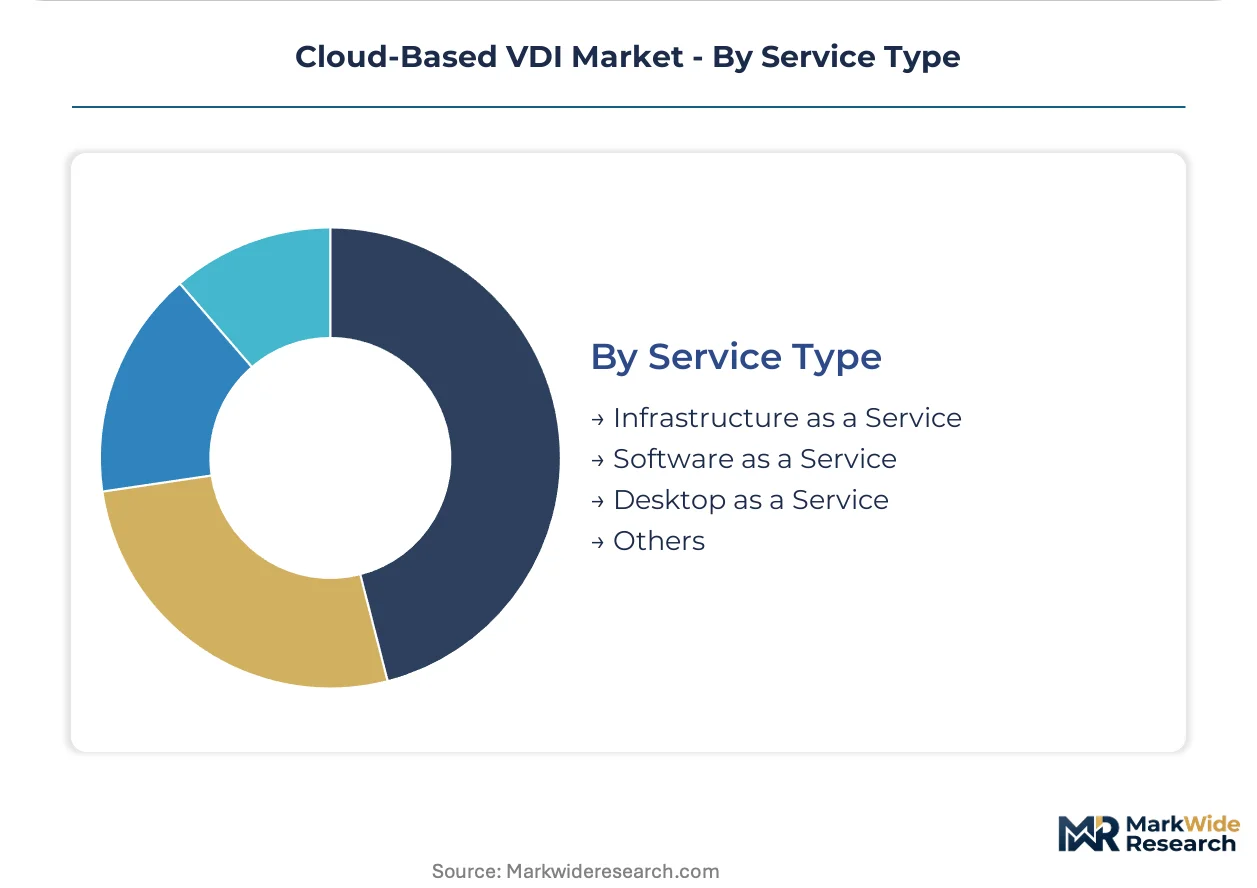
Service Type:
Abstraction layer depth determines customer operational burden and provider margin capture.
- Infrastructure as a Service:Raw compute, storage, and networking resources with customer-managed virtualization layers. Engineering teams with specialized GPU passthrough requirements retain control through this model.
- Software as a Service:Fully managed application delivery without desktop session management. Point solutions for specific productivity suites compete here with broader VDI platforms.
- Desktop as a Service:Complete desktop environment outsourcing including image management, patching, and user support. Mid-market enterprises abandoning self-managed Citrix estates are driving the fastest growth in this category.
- Others:Emerging delivery models including containerized workspaces and browser-isolated application streaming. Experimental deployments in software development environments test these architectures.
IaaS retains technical-user preference. Desktop as a Service is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Rhine-Main metropolitan region anchors European cloud infrastructure concentration through data-center tax incentives and GDPR-compliant hosting clusters. Sovereign-cloud certifications and EU AI Act data-residency mandates are reshaping provider site selection across national boundaries.
Germany
Mittelstand manufacturers in Baden-Württemberg and Bavaria drive GPU-enabled virtual desktop demand for secure CAD/CAM access. The country's Federal Office for Information Security (BSI) enforces ISO 27001 and C5 cloud certification requirements. Stuttgart's automotive engineering corridor hosts specialized sovereign-cloud zones for intellectual property protection.
United States
Healthcare systems and financial services firms anchor enterprise VDI deployment across the Northeast and West Coast. HIPAA Security Rule and SEC cybersecurity disclosure rules dictate audit-trail and incident-response documentation standards. Northern Virginia's data-center alley sustains hyperscale concentration for burst-compute economics.
United Kingdom
Professional services firms and public sector procurement frameworks accelerate Desktop-as-a-Service adoption. The UK Information Commissioner's Office enforces GDPR-derived data localization expectations post-Brexit. London's financial district maintains hybrid cloud architectures for trading-floor resilience.
India
Domestic data-center operators capture financial services demand as the Reserve Bank of India mandates local custody of core banking data. Bureau of Indian Standards (BIS) cloud certification pathways enable indigenous provider competition. Mumbai and Bangalore clusters expand GPU-enabled workstation capacity for software development outsourcing.
France
Healthcare providers and defense contractors prioritize sovereign-cloud deployments with independent encryption key custody. The National Commission for Information Technology and Civil Liberties (CNIL) enforces strict data residency interpretations. Paris-Saclay's research cluster hosts specialized academic VDI for sensitive scientific computing workloads.
Cloud-Based VDI Market Key Industry Players
US-based hyperscale providers anchor the infrastructure tier; European specialists and open-source platforms hold differentiated positions in sovereign-cloud segments. Market structure consolidates around three dominant compute providers controlling GPU-enabled capacity, with fragmentation persisting in managed services and vertical-specific deployments. Strategic archetypes include hyperscale platform operators, legacy virtualization incumbents, and emerging sovereign-cloud specialists. Competitive moves center on edge data-center densification and subscription-model transitions away from perpetual licensing.
Within the hyperscale platform tier, Microsoft Azure Virtual Desktop and Amazon WorkSpaces exemplify infrastructure dominance through global footprint and burst-compute pricing flexibility. VMware Horizon occupies a position bridging enterprise legacy estates and modern cloud delivery, representing the incumbent virtualization archetype facing subscription transition pressure. Citrix Virtual Apps and Desktops anchors the granular policy-control segment for regulated verticals requiring deep compliance instrumentation.
| Leading Market Players |
|---|
| Omnissa Horizon |
| V2 Cloud |
| Amazon WorkSpaces |
| Ace Cloud Hosting |
| Inuvika OVD Enterprise |
| Microsoft Azure Virtual Desktop |
| VMware Horizon |
| IBM Cloud |
| Citrix Virtual Apps and Desktops |
| Others |
Cost & Logistics Intelligence
GPU accelerator costs cascade through cloud VDI pricing tiers as hyperscale providers negotiate volume commitments with NVIDIA and AMD, compressing margins for regional sovereign-cloud operators serving German Mittelstand manufacturers. Frankfurt-based data centers absorb interconnection fees that inflate per-desktop pricing for latency-sensitive CAD/CAM workloads against burst-compute spot offerings from Northern Virginia clusters.
Pricing Analysis
Short lead-time provisioning commands premium pricing in cloud VDI markets as healthcare systems facing HIPAA audit deadlines pay surcharge rates for sub-72-hour deployment windows. Three-tier pricing structure across premium GPU-enabled, standard persistent, and economy non-persistent tiers reflects certification grade differentiation with ISO 27001 and BSI C5 compliance. Price differentiation stems from data residency guarantees and burst elasticity terms. SMB segments exhibit highest price sensitivity, while financial institutions in Luxembourg accept premium positioning for sovereign-cloud contractual terms.
Supply Chain Analysis
Cross-border fiber latency costs fragment cloud VDI supply economics as trans-Atlantic and Asia-Pacific bandwidth pricing varies by submarine cable landing proximity. Taiwan, South Korea, and the United States anchor GPU semiconductor fabrication for NVIDIA and AMD accelerator supply. Raw material dependencies span silicon wafers, HBM memory stacks, and specialized cooling substrates. Single-source vulnerability concentrates in NVIDIA vGPU software licensing. Distribution runs through hyperscale direct sales, managed service provider channels, and systems integrator partnerships serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based VDI markets sit at a technology-transition inflection as Desktop-as-a-Service consumption models displace perpetual Citrix and VMware capital deployments across mid-market enterprises. GPU virtualization and edge-distributed delivery architectures are displacing centralized data-center terminal services.
For Market Incumbents: Extend sovereign-cloud certification coverage into France and India to preempt regulatory fragmentation, while consolidating GPU allocation contracts against hyperscale hiring pressure that drains NVIDIA vGPU engineering talent. Defensive positioning requires backward integration into edge data-center real estate in Stuttgart and Munich corridors. For New Entrants and Emerging Players: Launch via managed service provider channels targeting German automotive suppliers with sub-500 seat GPU-enabled workstation deployments, a white-space segment underserved by hyperscale direct sales. Tax preparation and retail seasonal workforce platforms represent the most penetrable application vertical for non-persistent desktop pool economics. For Investors and Strategic Acquirers: BIS cloud certification announcements by Indian domestic operators signal the leading indicator that RBI-mandated core banking data localization is creating viable acquisition targets. Long-term viability centers on sovereign-cloud specialists with independent encryption key custody and multi-cloud orchestration capabilities. Watch for EU AI Act enforcement actions as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Cloud Certification Expansion | BSI C5 and ANSSI compliance unlocks German and French public sector procurement frameworks. |
| GPU-Enabled Workstation Service Launch | NVIDIA vGPU passthrough captures automotive and aerospace CAD/CAM displacement from physical workstations. |
| Managed Service Provider Channel Partnership | Mid-market SMB outsourcing accelerates Desktop-as-a-Service conversion from legacy Citrix estates. |
| Edge Data-Center Densification | Sub-50ms latency compliance expands addressable workforce populations in fiber-constrained regions. |
| Zero-Trust Architecture Integration | Conditional access policy convergence displaces VPN-centric remote access in financial services. |
Research Approach
Multi-period observation of hyperscale capex disclosures, sovereign-cloud certification timelines, and GPU supply allocation patterns anchored the trend analysis, supplemented by interviews with cloud infrastructure architects, healthcare IT security officers, German automotive engineering procurement leads, and managed service provider operations directors. Secondary validation drew from SEC 10-K filings, EU AI Act regulatory texts, BIS cloud certification documentation, and RBI circulars on data localization. Bottom-up desktop deployment estimates triangulated against top-down infrastructure capacity assessments.
Segment-weighting approaches distributed value projections across deployment model, licensing type, and end-user scale dimensions, with vertical-specific adjustments for healthcare HIPAA compliance and financial services GDPR Article 44 transfer restriction impacts. CAGRs were derived from elasticity-adjusted demand curves and infrastructure capacity expansion schedules. GPU virtualization adoption rates and sovereign-cloud procurement velocity served as industry-specific forecast inputs throughout the modeling period.
Regulatory enforcement delays, hyperscale supply concentration chokepoints, and legacy application virtualization friction are the dominant revision risks that could compress or extend projected adoption trajectories. Stakeholders should weight assumptions against their own operating context and compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Top 10 Cloud Technologies Market
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud Data Quality Radar Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Cloud-Enabling Technology Market
Cloud Technology
Cloud Engineering Market
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Colombia Information Technology (IT) Market