
 Global Dyslexia Treatment Market | 2026-2036
Global Dyslexia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dyslexia Treatment Market Foresight
Special education schools is realigning the demand profile for dyslexia interventions, pulling investment toward curriculum-integrated platforms and away from standalone consumer tools. Pearson PLC leverages its institutional distribution network to dominate K-12 contract channels across multiple continents. Lindamood-Bell Learning Processes specializes in intensive in-person therapy protocols that command premium pricing from affluent families and private learning centers. Teva Pharmaceutical Industries Ltd. competes in the adjunct pharmacotherapy segment where comorbid attention disorders expand addressable prescriptions.
Dyslexia treatment encompasses structured literacy instruction, neuroplasticity-based cognitive training, assistive reading technologies, and targeted pharmaceutical interventions designed to improve phonological processing, working memory, and reading fluency in individuals with specific learning disabilities. Educational software and cognitive training platforms lead product-type revenue contribution due to recurring subscription models and scalable deployment, while assistive devices maintain steady replacement-cycle demand powered by text-to-speech and optical character recognition advances. Therapy programs in phonological awareness and reading skills enhancement capture disproportionate margin pools because certified practitioner delivery creates pricing power and reduces direct competition from pure software alternatives.
FDA neuropharmacology review standards, EMA pediatric investigation plans, and WHO rehabilitation service guidelines collectively shape clinical trial investments and product labeling claims across jurisdictions. The EU AI Act and FDA software-as-medical-device frameworks are forcing platform developers to document algorithmic decision pathways and efficacy validation before reimbursement eligibility. Stakeholders must monitor evolving digital therapeutics coding decisions by Medicare, NHS England, and German statutory health insurers to determine which delivery modes achieve sustainable payment pathways.
Market Dynamics
Universal screening mandates in United States, Germany, and Australia are restructuring procurement pathways for dyslexia interventions, pulling purchasing authority from individual families toward district-level administrators and institutional procurement committees.
Growth Catalysts
- Universal Screening Mandates:United States Department of Education guidance and German federal state education frameworks now require systematic early literacy assessment in primary grades, institutionalizing demand for validated assessment tools.
- FDA Software-as-Medical-Device Pathway:The FDA's evolving framework for digital therapeutics creates regulatory clarity for cognitive training platforms seeking reimbursement eligibility through established medical device channels.
- Neuroplasticity Research:Advances in functional MRI and longitudinal intervention studies strengthen evidence bases for structured literacy and cognitive training protocols, accelerating insurance coverage negotiations.
Market Restraints
- Practitioner Certification Bottlenecks:Limited availability of certified Orton-Gillingham and Lindamood-Bell therapists creates supply constraints that cap service delivery capacity regardless of software scalability.
- Reimbursement Fragmentation:German statutory health insurers, NHS England, and United States Medicare maintain inconsistent coding for digital therapeutics versus in-person therapy, complicating revenue model predictability.
- Hardware Refresh Cycles:Assistive device replacement demand tied to school district capital budgets introduces procurement delays that decouple revenue from clinical need.
Strategic Opportunities
- India K-12 Expansion:Central Board of Secondary Education inclusion policies and rising private school enrollment create addressable demand for English-language literacy intervention platforms.
- EMA Pediatric Investigation Plans:Structured pharmacotherapy trials for comorbid attention disorders in dyslexic populations open regulatory pathways for adjunctive pharmaceutical indications.
- Teletherapy Platform Convergence:Integration of synchronous video delivery with adaptive algorithmic content personalization enables geographic extension of certified practitioner reach into underserved rural markets.
Industry Challenges
- Algorithmic Transparency Requirements:EU AI Act documentation standards for educational software create compliance burdens that extend product development timelines and elevate legal review costs.
- Interoperability with Legacy School Information Systems:District-level procurement committees demand seamless data exchange with existing student information platforms, forcing custom integration work that erodes margin on standard deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dyslexia Treatment Market |
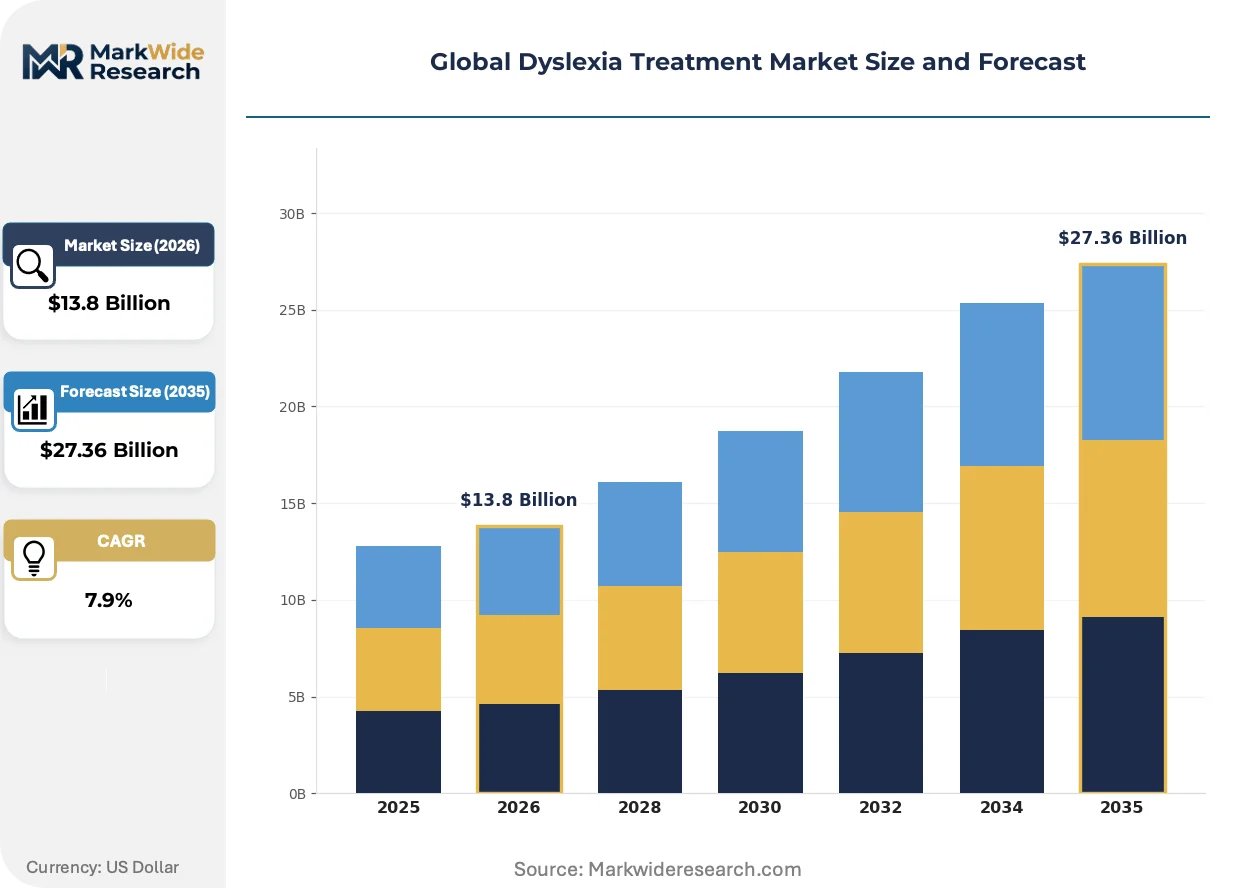
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $27.36 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Educational Software, Assistive Devices, Therapy Programs, Learning Tools, Cognitive Training Platforms Therapy Area: Reading Skills Enhancement, Writing Improvement, Phonological Awareness, Comprehension Development, Oral Language Coaching End User: Special Education Schools, Speech Therapists, Learning Centers, Pediatric Clinics, Tutoring Services Delivery Mode: In-Person Sessions, Online Platforms, Mobile Applications, Home-Based Programs, Blended Learning |
| Companies Covered | Cogmed, Learning Ally, Pfizer, Inc., Novartis AG, Speechify Inc., Pearson PLC, Kurzweil Education, Teva Pharmaceutical Industries Ltd., Lindamood-Bell Learning Processes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dyslexia Treatment Market Shifts & Advancements
Artificial intelligence is restructuring competitive advantage in dyslexia intervention, compressing the gap between standardized curriculum delivery and personalized adaptive pacing while forcing traditional publishers to rearchitect legacy assessment architectures.
Adaptive algorithmic assessment platforms are absorbing the diagnostic functions previously performed by human psychoeducational evaluators, enabling real-time difficulty calibration based on response pattern analysis. United States school districts with universal screening mandates are deploying these tools at scale for Tier 1 intervention triage. The technology is absorbing market share from standalone standardized testing products by embedding continuous formative assessment within daily instructional workflows.
EMA pediatric investigation plans and FDA neuropharmacology review standards are tightening evidentiary requirements for pharmacological interventions targeting comorbid conditions in dyslexic populations. Trial sponsors must now demonstrate cognitive outcome measures beyond symptom reduction, elevating protocol complexity and extending development timelines. Adjunct pharmacotherapy segments in Germany and United States face compressed commercialization windows as regulatory scrutiny intensifies.
District procurement committees are consolidating vendor relationships around integrated platform ecosystems that combine assessment, intervention, and progress monitoring within single contractual frameworks. Standalone assistive technology vendors without curriculum integration capabilities face displacement from preferred vendor lists. This concentration is most visible in Australian state education departments and large United States public school systems where total-cost-of-ownership evaluations favor unified deployments over best-of-breed point solutions.
Global Dyslexia Treatment Market Segmentation
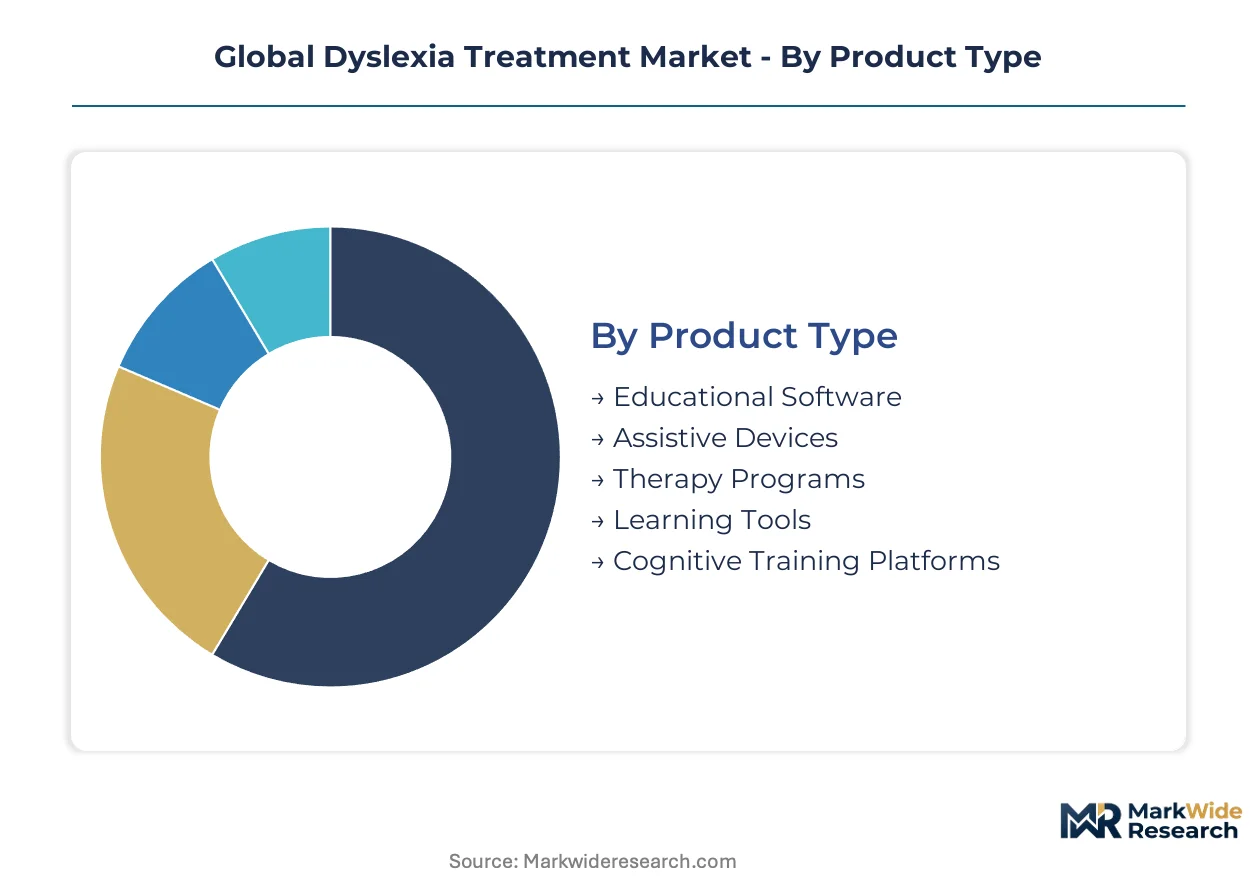
Dyslexia treatment market segmentation reflects divergent capital requirements across software development, hardware manufacturing, and certified service delivery. Procurement patterns vary sharply between institutional buyers seeking scalable platforms and families prioritizing intensive practitioner-led intervention.
Product Type:
Capital intensity peaks in cognitive training platforms requiring FDA software-as-medical-device validation and clinical trial investment, while educational software demands ongoing R&D spend for adaptive algorithm development.
- Educational Software:Cloud-based literacy platforms with subscription monetization dominate K-12 contract channels. District-level procurement committees in the United States and Germany favor curriculum-integrated deployments with student information system interoperability.
- Cognitive Training Platforms:Neuroplasticity-based interventions require substantial upfront validation spend to secure EMA pediatric investigation plans and FDA neuropharmacology alignment. Reimbursement eligibility through Medicare and NHS England coding decisions determines commercial viability.
- Assistive Devices:Text-to-speech and optical character recognition hardware tied to school district capital budget cycles.
- Therapy Programs:Certified practitioner delivery models with premium pricing from Orton-Gillingham and Lindamood-Bell protocols.
- Learning Tools:Supplementary manipulatives and printed materials with lower development barriers.
Educational software absorbs the bulk of installed capacity; cognitive training platforms are expanding most quickly.
Therapy Area:
Margin concentration follows certification scarcity, with phonological awareness and reading skills protocols commanding premium pricing due to limited certified practitioner supply.
- Phonological Awareness:Structured literacy interventions targeting sound-symbol correspondence form the evidence base for insurance coverage negotiations. United States universal screening mandates institutionalize demand for validated protocols.
- Reading Skills Enhancement:Fluency and accuracy training absorbs the largest share of district intervention budgets. Australian state education departments and German federal state frameworks prioritize early-grade literacy outcomes.
- Writing Improvement:Transcription and composition support with growing integration into digital platforms.
- Comprehension Development:Higher-order cognitive processing interventions often bundled with oral language coaching.
- Oral Language Coaching:Expressive and receptive language support delivered through speech therapists and learning centers.
Reading skills enhancement captures the largest revenue pool; phonological awareness shows the steepest expansion trajectory as screening mandates broaden early identification.
End User:
Procurement authority is consolidating around institutional buyers with multi-year contract capacity, displacing fragmented individual family purchasing.
- Special Education Schools:Dedicated institutions with established special education funding frameworks in the United States and Australia drive curriculum-integrated platform adoption. Total-cost-of-ownership evaluations favor unified vendor ecosystems.
- Learning Centers:Private facilities serving affluent families with premium intensive therapy protocols. Geographic concentration in urban United States clusters and German metropolitan areas.
- Speech Therapists:Individual practitioners with limited scale but strong referral relationships to pediatric clinics.
- Pediatric Clinics:Medical settings where comorbid attention disorder diagnoses expand pharmacotherapy adjacency.
- Tutoring Services:Fragmented local providers with variable certification standards and pricing power.
Special education schools anchor volume demand; learning centers generate the highest per-client revenue.
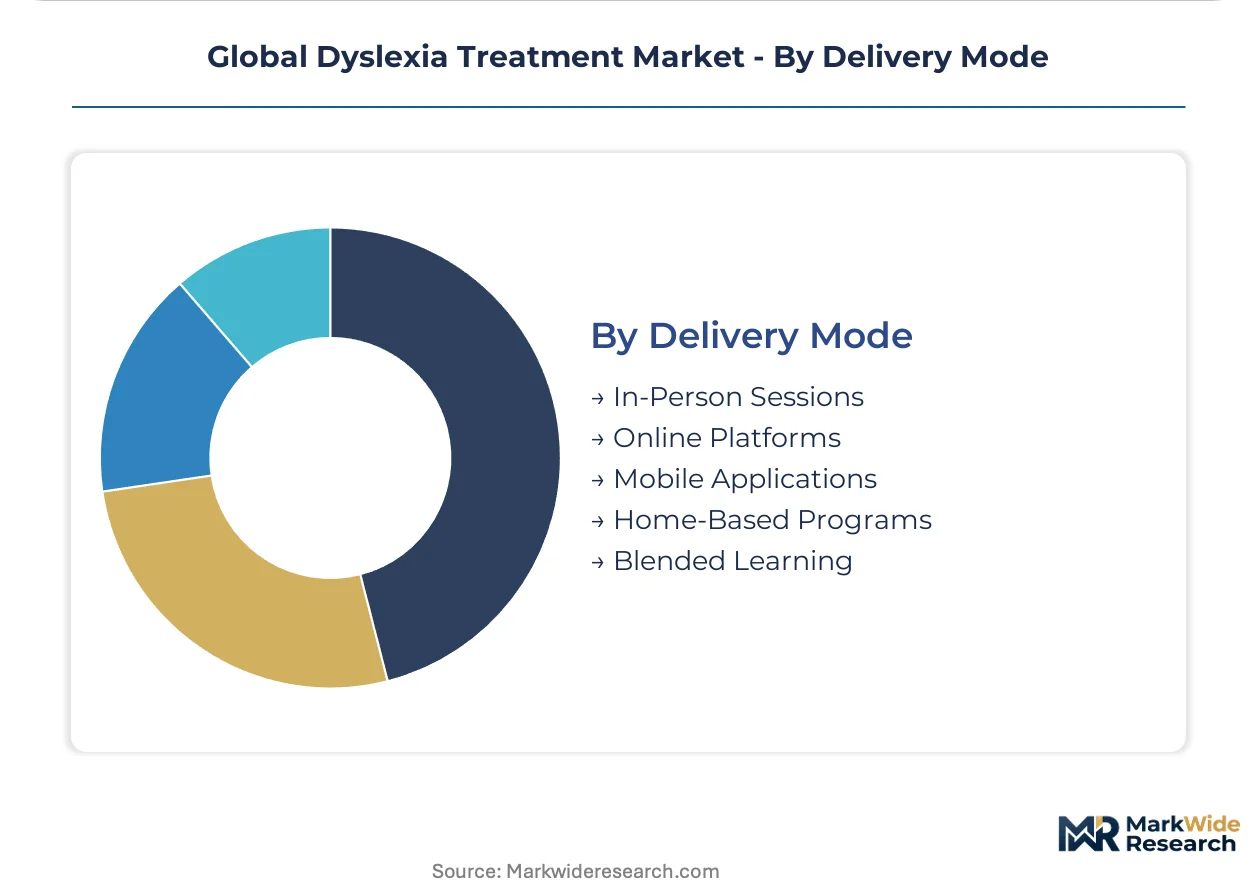
Delivery Mode:
Technology infrastructure investment separates scalable platforms from capacity-constrained in-person delivery, with regulatory frameworks determining reimbursement eligibility.
- Online Platforms:Synchronous and asynchronous delivery enabling geographic extension into underserved rural markets. EU AI Act algorithmic documentation requirements and FDA software-as-medical-device frameworks shape compliance spend.
- Blended Learning:Integration of in-person certified practitioner sessions with adaptive algorithmic content personalization. Australian state education departments and large United States public school systems favor this model for Tier 2 intervention.
- In-Person Sessions:Traditional delivery with supply constraints from Orton-Gillingham and Lindamood-Bell certification bottlenecks.
- Mobile Applications:Consumer-facing tools with limited institutional procurement traction.
- Home-Based Programs:Parent-delivered interventions with variable fidelity and outcome documentation.
Online platforms command the largest development investment; blended learning is gaining share fastest as procurement committees prioritize unified ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Dubai and Singapore concentrate regional headquarters for educational technology vendors serving adjacent markets. Special economic zones in Ireland and the Netherlands attract pharma R&D operations targeting EMA pediatric investigation pathways. These zones create regulatory arbitrage for companies seeking faster market access across multiple jurisdictions.
United States
Universal screening mandates in primary grades institutionalize district-level procurement for validated assessment platforms. FDA software-as-medical-device frameworks create reimbursement pathways for digital therapeutics seeking Medicare coding eligibility. Boston and Austin metropolitan clusters host concentrated cognitive training platform development operations serving K-12 contract channels.
Germany
Federal state education frameworks mandate systematic early literacy assessment, pulling purchasing authority toward institutional procurement committees. Statutory health insurers maintain evolving digital therapeutics reimbursement codes that determine commercial viability for cognitive training platforms. Munich and Hamburg metropolitan areas concentrate assistive technology distribution operations serving Central European markets.
Australia
State education departments prioritize early-grade literacy outcomes through unified vendor ecosystem contracts covering assessment, intervention, and progress monitoring. TGA medical device frameworks shape regulatory requirements for software-based therapeutic platforms. Sydney and Melbourne urban clusters host specialized learning centers delivering premium intensive therapy protocols to affluent families.
India
Central Board of Secondary Education inclusion policies and rising private school enrollment create addressable demand for English-language literacy intervention platforms. BIS standards for educational software shape product certification requirements for domestic market entry. Bangalore and Hyderabad technology corridors host adaptive algorithm development operations serving K-12 platform deployments.
United Kingdom
NHS England coding decisions for digital therapeutics versus in-person therapy determine revenue model predictability for platform developers. GDPR and EU AI Act documentation standards create compliance burdens extending product development timelines. London and Cambridge clusters concentrate neuroplasticity research operations strengthening evidence bases for insurance coverage negotiations.
Global Dyslexia Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement committees consolidating vendor relationships around integrated platform ecosystems. The vendor base separates into three tiers: multinational educational publishers with established distribution networks, pharmaceutical companies pursuing adjunct pharmacotherapy indications, and specialized therapy providers with certified practitioner delivery models. Strategic moves concentrate on M&A activity absorbing standalone assistive technology vendors and technology licensing partnerships enabling student information system interoperability.
Within the educational publishing tier, Pearson PLC anchors institutional distribution capabilities across multiple continents. Among specialized therapy providers, Lindamood-Bell Learning Processes exemplifies premium intensive in-person delivery models commanding pricing power from affluent families. Teva Pharmaceutical Industries Ltd. occupies a position in the adjunct pharmacotherapy segment where comorbid attention disorders expand prescription addressability.
| Leading Market Players |
|---|
| Cogmed |
| Learning Ally |
| Pfizer, Inc. |
| Novartis AG |
| Speechify Inc. |
| Pearson PLC |
| Kurzweil Education |
| Teva Pharmaceutical Industries Ltd. |
| Lindamood-Bell Learning Processes |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate qualified supply for cognitive training platforms and premium-tier pricing access for vendors documenting decision pathways. District procurement committees in the United States and Germany now require compliance documentation as a contractual precondition, bifurcating the vendor base between certified premium providers and excluded economy-tier alternatives.
Pricing Analysis
Short lead-time delivery of certified Orton-Gillingham practitioner training commands substantial premiums from learning centers facing supply bottlenecks, while spot inventory of unverified educational software trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and student information system interoperability depth. Cost compression in economy-tier software subscriptions is intensifying because cloud infrastructure commoditization erodes differentiation. Learning centers show least price sensitivity due to affluent family demand, while public school districts with fixed special education budgets exhibit highest sensitivity.
Supply Chain Analysis
Workforce availability for certified Lindamood-Bell therapists concentrates supply constraints in the United States and Australian metropolitan clusters, with Munich and Hamburg serving Central European distribution hubs. Software development draws from Bangalore and Hyderabad engineering corridors, while hardware manufacturing feeds from Chinese and Taiwanese component suppliers. Single-source vulnerability runs through FDA-validated cognitive training platform developers with exclusive algorithmic IP. Distribution runs through institutional procurement committees and direct-to-learning-center channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive algorithmic assessment platforms are displacing legacy standardized testing products, restructuring competitive advantage around real-time personalization capabilities.
For Market Incumbents: Extend platform ecosystem integration to absorb standalone assistive technology vendors before procurement committees consolidate preferred vendor lists. Backward integration into certified practitioner training programs addresses Orton-Gillingham supply bottlenecks that cap service delivery capacity. Channel control through exclusive student information system interoperability agreements raises switching costs for district customers. For New Entrants and Emerging Players: FDA software-as-medical-device pathway in the United States opens a window for cognitive training platforms seeking Medicare reimbursement eligibility through established medical device channels. White-space targets include rural teletherapy extension and India K-12 private school English-language literacy platforms. Go-to-market through speech therapist referral networks leverages existing pediatric clinic relationships. For Investors and Strategic Acquirers: NHS England digital therapeutics coding decisions are the leading indicator that reimbursement model predictability will consolidate around platform vendors with integrated assessment-intervention-monitoring capabilities. Long-term viability favors acquisition targets with FDA or EMA validation spend already sunk and proprietary adaptive algorithms. Signal to watch is German statutory health insurer formulary inclusion announcements.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Submission | Structured pharmacotherapy trials for comorbid attention disorders open regulatory pathways in Germany. |
| Student Information System Integration Partnership | Seamless data exchange with Pearson and district platforms secures preferred vendor status. |
| Teletherapy Platform Geographic Expansion | Synchronous video delivery extends certified practitioner reach into underserved rural United States markets. |
| Certified Practitioner Training Program Acquisition | Captive supply of Orton-Gillingham therapists removes capacity constraints on premium service delivery. |
| EU AI Act Compliance Documentation Investment | Algorithmic decision pathway transparency satisfies procurement preconditions in German federal state frameworks. |
Research Methodology
Multi-period observation of universal screening mandate adoption rates, digital therapeutics reimbursement coding decisions, and certified practitioner supply constraints anchored the trend analysis, supplemented by interviews with K-12 district procurement officers, special education curriculum directors, cognitive training platform CTOs, Orton-Gillingham certification body administrators, and German statutory health insurer formulary managers. Secondary validation drew from FDA 510(k) filings, EMA pediatric investigation plan submissions, NHS England technology appraisal guidance, German federal state education framework documents, and Australian state education department tender records. Bottom-up installed base estimates triangulated against top-down special education funding allocation models.
Input-output matrices mapped educational software subscription flows, cognitive training platform validation spend requirements, assistive device replacement cycles, and therapy program delivery capacity across product type, therapy area, end user, and delivery mode segmentation dimensions. CAGRs were derived from regression analysis of historical procurement volume against screening mandate implementation timelines and reimbursement code expansion patterns. Forecast inputs incorporated neuroplasticity research publication velocity and district-level platform consolidation trajectories.
The model assumes a particular technology adoption path for adaptive algorithmic assessment; alternative pathways for human psychoeducational evaluator retention would alter the outlook. Forecasts reflect assumptions regarding FDA software-as-medical-device pathway stability and EMA pediatric investigation plan timeline predictability. Material deviation in Medicare digital therapeutics coding decisions or German statutory health insurer reimbursement policy shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Education Apps Market
Education & Training
E-Learning Market
Education & Training
Global Exam Management Software Market
Education & Training
Asia-Pacific Corporate Training Market
Education & Training
Micro Learning Platform Market
Education & Training
Education Technology and Smart Classrooms Market
Education & Training
Asia-Pacific School Furniture Market
Education & Training
Qatar Private K12 Education Market
Education & Training
Digital English Learning Market
Education & Training
US Life Coaching Market
Education & Training
Technical and Vocational Education Market
Education & Training
Specific Gravity Bench Apparatus Market
Education & Training
Global Gamification in Education Market
Education & Training
School Management System Market
Education & Training
Higher Education Market
Education & Training
Global Alumni Management Software Market