
 Personal Development Market | 2026-2036
Personal Development Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Development Market Intelligence
Workforce soft-skill shortages is unwinding traditional hiring pipelines and forcing employers into structured development programs. FranklinCovey anchors its position through curriculum-based leadership training delivered across Fortune 500 boardrooms. Skillsoft competes via a cloud-native content library spanning compliance, technology, and business skills. Dale Carnegie Training sustains century-old brand equity in face-to-face persuasion and communication workshops now ported to hybrid delivery.
Personal development encompasses structured interventions—assessment instruments, curated curricula, facilitated coaching, and habit-tracking protocols—designed to measurably advance individual capabilities, well-being, or career trajectory. These programs typically incorporate psychometric diagnostics, spaced-repetition learning architectures, and accountability mechanisms to ensure behavioral transfer. Coaching and online courses command the deepest margin pools as corporations substitute scalable digital modules for costly in-person retreats. Self-paced delivery dominates volume growth because learners and HR buyers alike prioritize schedule flexibility over synchronous instruction.
The U.S. Department of Labor's Workforce Innovation and Opportunity Act eligibility criteria, the EU's CSRD human-capital disclosure requirements, and Japan's METI-guided reskilling subsidies collectively shape procurement standards and program design. ISO 30414 is accelerating demand for verifiable skill-outcome metrics that vendors must embed to retain enterprise contracts. Stakeholders should monitor how credential-recognition frameworks evolve, since interoperability between corporate learning records and formal academic credit will determine which platforms capture long-term user loyalty.
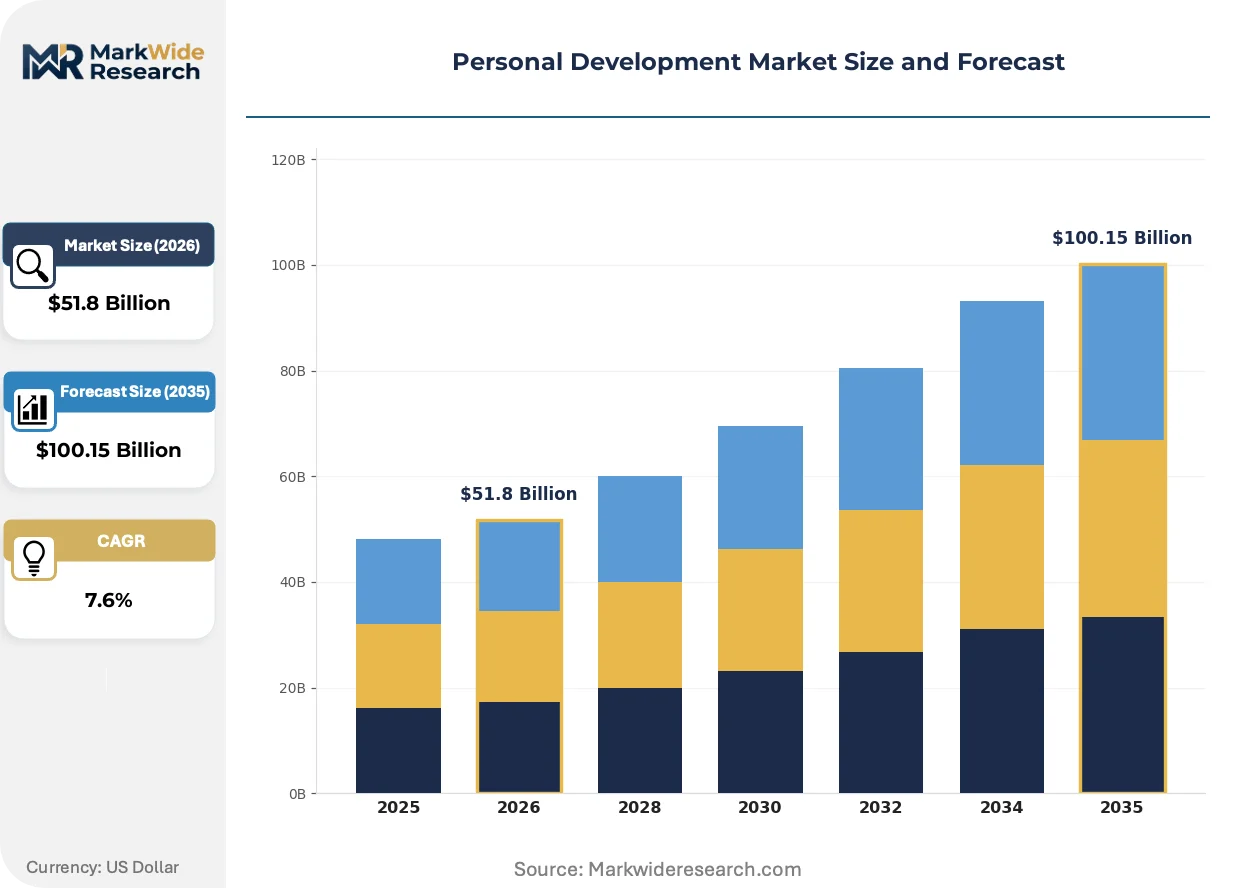
Market Dynamics
ISO 30414 human-capital disclosure mandates are forcing employers to document measurable skill outcomes, transforming personal development from discretionary spending into auditable compliance infrastructure. This regulatory pressure is compressing vendor selection cycles and privileging platforms with embedded analytics.
Growth Catalysts
- Workforce soft-skill shortages:Employers facing collapsed hiring pipelines are redirecting recruitment budgets into structured leadership coaching and digital upskilling programs.
- CSRD human-capital disclosure requirements:European Union mandates now compel listed companies to report training investments and outcomes, expanding addressable market for outcome-verification tools.
- Cloud-native content architectures:Scalable delivery models are collapsing per-learner marginal costs and enabling enterprise-wide rollouts previously blocked by budget constraints.
Market Restraints
- Outcome measurement opacity:Behavioral transfer from training to workplace performance lacks standardized metrics, complicating procurement justification and renewal decisions.
- Credential interoperability gaps:Corporate learning records remain disconnected from formal academic credit systems, limiting individual learner willingness to pay premium prices.
- Synchronous delivery cost structures:Facilitated coaching and in-person workshops carry fixed labor costs that resist the scale economies achieved by self-paced modules.
Strategic Opportunities
- Japan's METI-guided reskilling subsidies:Government-funded workforce transformation programs are creating procurement channels for verified skill-development providers.
- Artificial intelligence and psychometric convergence:Adaptive diagnostic engines paired with personalized curriculum pathways are opening premium pricing tiers for hyper-customized interventions.
- Embedded habit-tracking protocols:Integration with workplace productivity software is creating continuous engagement models beyond traditional course completion.
Industry Challenges
- Instructional design talent scarcity:Shortages of professionals capable of translating behavioral science into scalable digital curricula are constraining product pipeline velocity.
- Legacy HRIS integration complexity:Enterprise buyers demand seamless data flows into existing human-resource information systems, requiring costly custom development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Development Market |
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $100.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Books, Online Courses, Workshops, Coaching Customer Type: Individuals, Corporations, Educational Institutions, Nonprofits Delivery Mode: In-Person, Virtual, Hybrid, Self-Paced Focus Area: Professional Growth, Personal Wellness, Skill Development, Leadership |
| Companies Covered | Skillsoft, Coachhub, FranklinCovey, Sharpist, DDI (Development Dimensions International), Dale Carnegie Training, CrossKnowledge, Elevate Leadership, Center for Creative Leadership, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Development Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how capabilities are diagnosed, delivered, and verified. Three distinct vectors are compressing traditional delivery models and creating new competitive moats around data-rich platforms.
Adaptive learning algorithms are supplanting static curriculum sequencing in enterprise deployments. Fortune 500 learning-and-development departments are piloting AI-driven personalization at accelerating rates. This technology is compressing time-to-competency metrics and threatening providers locked into fixed-content libraries.
The EU's Corporate Sustainability Reporting Directive is mandating granular human-capital disclosures across listed employers. Procurement departments are now requiring vendors to supply pre-formatted outcome data compatible with CSRD templates. Mid-market European enterprises are responding by consolidating supplier relationships toward platforms with embedded compliance tooling.
Subscription fatigue among individual learners is fragmenting demand toward micro-credential and pay-per-outcome models. Self-paced digital coaching is displacing annual membership programs in the direct-to-consumer channel. This behavioral pivot is most visible in the United States, where individual spending on virtual coaching had previously outpaced other national markets.
Personal Development Market Segmentation
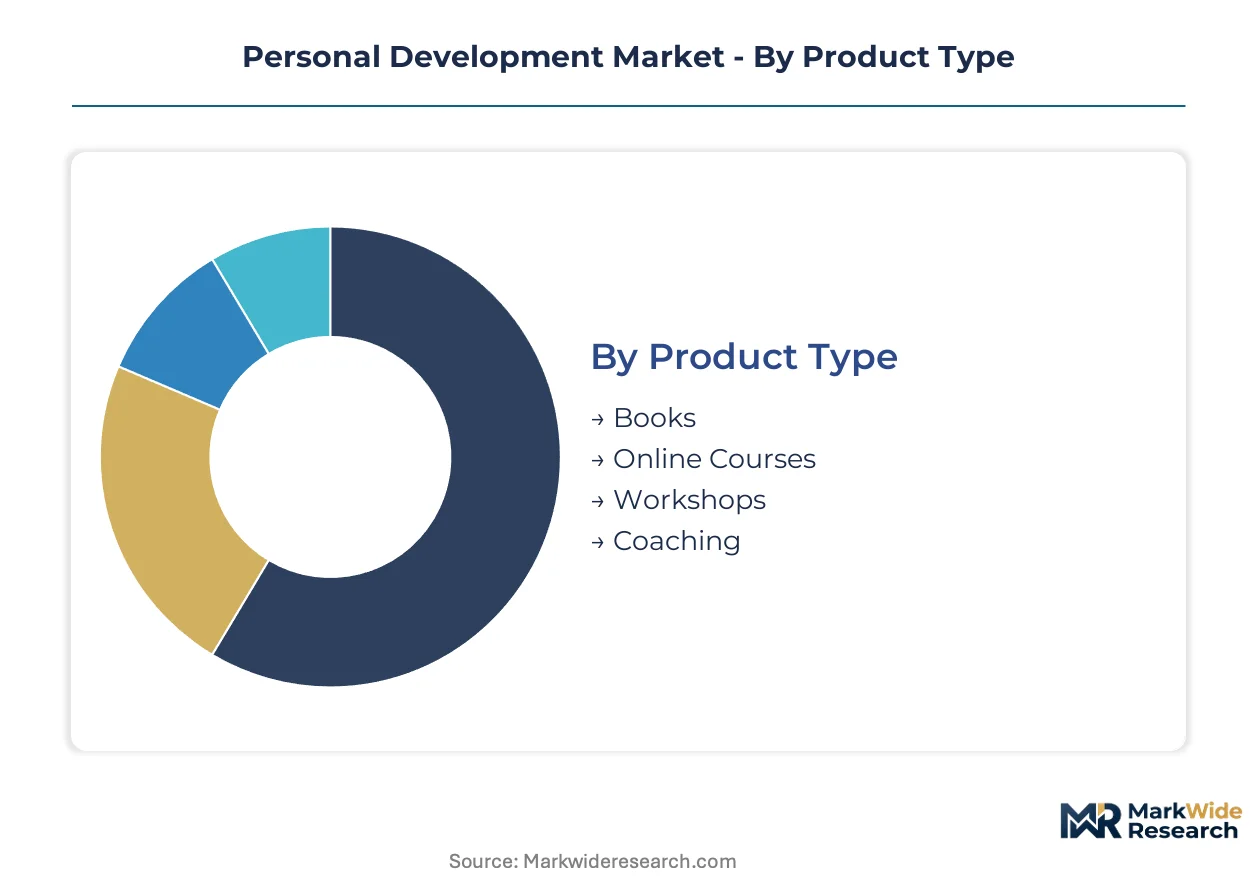
Personal development procurement splits sharply between individual subscription channels and enterprise contract vehicles. Channel economics determine which formats scale profitably and which remain trapped in labor-intensive delivery models.
Product Type:
Channel distribution varies dramatically by format—scalable digital products flow through app stores and enterprise learning platforms, while facilitated services rely on direct sales teams and certified practitioner networks.
- Books:Traditional print and digital formats anchor the mass-market entry point. Consumer demand clusters through Amazon Kindle and Audible channels in the United States, where individual spending on self-improvement content outpaces other national markets.
- Online Courses:Modular video curricula with embedded assessments and completion certificates. Corporate learning management system integrations dominate B2B procurement, driven by ISO 30414 human-capital disclosure mandates requiring verifiable skill-outcome documentation.
- Workshops:Time-bounded facilitated sessions delivered synchronously. Fixed labor costs constrain scale; hybrid delivery models are compressing per-session economics while preserving engagement depth.
- Coaching:One-to-one or small-group facilitated development relationships. Premium pricing tiers persist through executive sponsorship, though AI-augmented coaching platforms are displacing annual retainer models in mid-market accounts.
Online courses dominate installed base. Coaching is where expansion concentrates.
Customer Type:
Procurement authority and budget cycles differ materially across buyer categories, shaping vendor sales motion design and contract structuring.
- Individuals:Direct-to-consumer purchasers exercising discretionary spend. Subscription fatigue is fragmenting demand toward micro-credential and pay-per-outcome models, particularly visible in U.S. virtual coaching markets.
- Corporations:Enterprise learning-and-development departments with formal budget lines. CSRD human-capital disclosure requirements in the European Union are expanding addressable market for outcome-verification tools among listed companies.
- Educational Institutions:Universities and vocational programs integrating soft-skill modules into degree pathways. Credential interoperability gaps with formal academic credit systems limit pricing power.
- Nonprofits:Mission-driven organizations with constrained procurement capacity. Workforce Innovation and Opportunity Act eligibility criteria in the United States shape program design and funding access.
Corporations command the deepest contract values. Individuals represent the broadest addressable population.
Delivery Mode:
Cost structure and margin profile hinge on synchronous labor requirements versus automated content delivery infrastructure.
- In-Person:Physical presence workshops and coaching sessions. Fixed venue and facilitator costs resist the scale economies achieved by digital alternatives; demand is compressing toward premium executive contexts.
- Virtual:Synchronous remote delivery via video conferencing platforms. Cloud-native architectures collapsed per-learner marginal costs and enabled enterprise-wide rollouts previously blocked by travel budgets.
- Hybrid:Blended synchronous and asynchronous components. Fortune 500 learning departments are piloting this format at accelerating rates to balance engagement depth with schedule flexibility.
- Self-Paced:Asynchronous content consumption with learner-controlled progression. This format is climbing the fastest as HR buyers and individual learners alike prioritize flexibility over scheduled instruction.
Self-paced delivery dominates volume growth. Hybrid models are gaining share fastest in enterprise accounts.
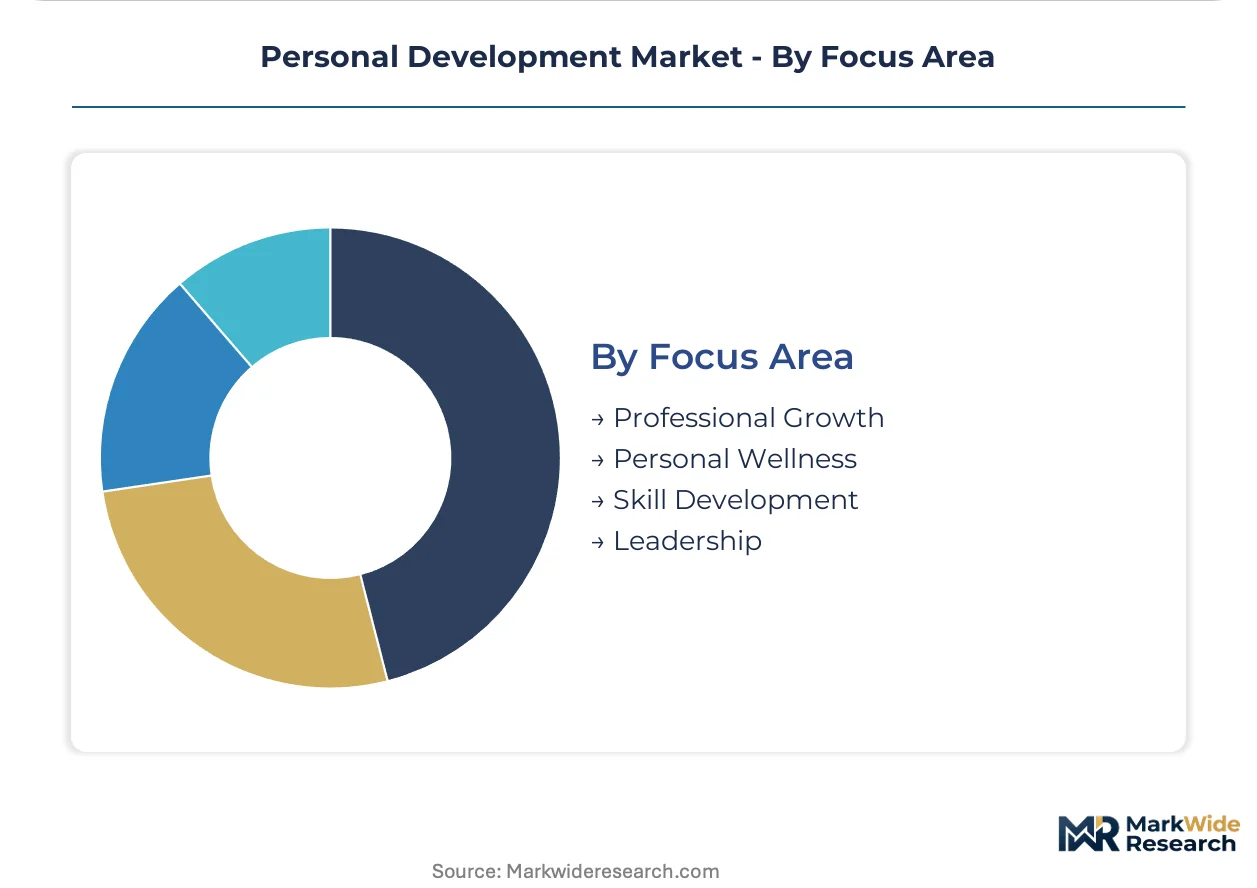
Focus Area:
Regulatory and labor-market pressures are tilting procurement priority toward measurable professional outcomes over general wellness content.
- Professional Growth:Career trajectory advancement including promotion readiness and role transitions. Japan's METI-guided reskilling subsidies are creating procurement channels for verified providers in this category.
- Personal Wellness:Stress management, mindfulness, and work-life integration. Direct-to-consumer subscription models face headwinds from fatigue, though employer-sponsored wellness budgets show resilience.
- Skill Development:Technical and soft-skill acquisition with demonstrable competency markers. Workforce soft-skill shortages are redirecting recruitment budgets into structured programs with embedded analytics.
- Leadership:Executive and managerial capability building. Curriculum-based approaches anchor Fortune 500 deployments, with AI-driven personalization now compressing time-to-competency metrics.
Skill development commands the steepest expansion trajectory. Leadership retains the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes individual virtual coaching subscriptions, while European and Asian markets emphasize employer-mandated compliance-driven programs.
United States
Enterprise learning budgets and individual subscription spending for virtual coaching outpace other national markets. The Department of Labor's Workforce Innovation and Opportunity Act eligibility criteria shape program design and funding access for workforce development providers. New York and California metro areas concentrate demand for executive coaching and digital upskilling platforms serving Fortune 500 headquarters.
Germany
Industrial employers redirect recruitment budgets into structured leadership development as hiring pipelines tighten for technical roles. The country's national employment regulator and EU CSRD human-capital disclosure requirements compel documented skill investments from listed companies. Bavaria and Baden-Württemberg host dense clusters of automotive and machinery firms piloting AI-driven personalization for management training.
Japan
Corporate HR departments rank leadership coaching among top discretionary spends amid demographic workforce contraction. METI-guided reskilling subsidies create procurement channels for verified skill-development providers serving manufacturing and service sectors. Tokyo and Osaka anchor demand for hybrid delivery models blending traditional face-to-face instruction with cloud-native content architectures.
United Kingdom
Financial services and professional services firms drive demand for measurable professional outcomes over general wellness content. CSRD-aligned disclosure expectations and national corporate governance codes pressure employers to document training investments. London's Square Mile and Canary Wharf concentrate executive coaching contracts with premium pricing tiers sustained by C-suite sponsorship.
India
Technology sector expansion and services export growth fuel demand for soft-skill development and English communication training. National skill development missions and state-level workforce transformation programs expand addressable market for structured interventions. Bangalore and Hyderabad host dense concentrations of IT services firms integrating digital upskilling into employee retention strategies.
Personal Development Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier combines curriculum libraries with embedded analytics and compliance tooling, while specialists concentrate on single modalities like coaching or assessment instruments. Three archetypes dominate: platform aggregators with cloud-native architectures, legacy training providers with hybrid delivery capabilities, and AI-native entrants with adaptive diagnostic engines. Competitive moves center on strategic partnerships for HRIS integration and portfolio diversification into adjacent skill-verification services.
Within the legacy training tier, Dale Carnegie Training exemplifies century-old brand equity now ported to hybrid delivery, while FranklinCovey occupies a position anchoring curriculum-based leadership programs across Fortune 500 boardrooms. Skillsoft represents the platform-aggregator archetype with cloud-native content spanning compliance, technology, and business skills. These three companies illustrate how vendor selection cycles compress toward providers with pre-formatted outcome data compatible with emerging disclosure mandates.
| Leading Market Players |
|---|
| Skillsoft |
| Coachhub |
| FranklinCovey |
| Sharpist |
| DDI (Development Dimensions International) |
| Dale Carnegie Training |
| CrossKnowledge |
| Elevate Leadership |
| Center for Creative Leadership |
| Others |
Cost & Logistics Intelligence
ISO 30414 human-capital disclosure standards gate both vendor qualification and price differentiation in enterprise personal development procurement. Compliance-verified platforms command premium positioning while non-compliant providers face margin compression from compressed renewal cycles.
Pricing Analysis
Long-term enterprise offtake agreements dominate corporate learning procurement, with annual subscriptions and project-based coaching retainers filling residual demand. Price differentiation rests on embedded analytics depth and CSRD-compatible outcome reporting, with AI-augmented platforms capturing premium tiers. Cost compression in self-paced modules intensifies as cloud-native architectures collapse per-learner delivery costs. Individual learners exhibit highest price sensitivity, while Fortune 500 L&D departments prioritize verifiable ROI over unit economics.
Supply Chain Analysis
The United States and Germany anchor curriculum development and instructional design talent pools for leadership training content. India and the Philippines feed customer success and coaching operations through business process outsourcing networks. Raw material dependencies center on licensed psychometric instruments, cloud infrastructure from hyperscalers, and certified facilitator networks. Single-source vulnerability concentrates in proprietary assessment IP held by established publishers. Distribution runs through enterprise LMS integrations, direct sales teams, and certified practitioner channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of instructional designers capable of translating behavioral science into scalable digital curricula constrain product velocity across the competitive landscape. This capability gap separates platforms with embedded AI personalization from legacy providers trapped in fixed-content libraries.
For Market Incumbents: Consolidate curriculum libraries through selective acquisition of assessment-instrument specialists to deepen moats around proprietary diagnostics. Fortify HRIS integration capabilities to defend against AI-native entrants threatening time-to-competency metrics. Prioritize embedded compliance tooling for CSRD and ISO 30414 disclosure templates to compress competitor vendor selection cycles.
For New Entrants and Emerging Players: Differentiate on adaptive diagnostic engines paired with pay-per-outcome pricing models that align vendor incentives with measurable skill transfer. Target mid-market European enterprises consolidating supplier relationships toward platforms with pre-formatted human-capital disclosure data. Deploy product-led growth motions through freemium psychometric assessments that convert to paid coaching subscriptions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified professional services parents where personal development units lack strategic priority despite embedded enterprise relationships. Long-term viability favors platforms combining curriculum depth with outcome-verification infrastructure over pure coaching marketplaces. Monitor credential interoperability frameworks as the signal for which learning records will capture sustained individual willingness to pay.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Personalization Engine | Adaptive algorithms compress time-to-competency metrics for Fortune 500 L&D departments. |
| CSRD Compliance Tooling Integration | Pre-formatted outcome data templates secure procurement from EU listed companies. |
| HRIS Platform Partnership | Seamless data flows into Workday and SAP SuccessFactors reduce enterprise friction. |
| Micro-Credential Marketplace Launch | Pay-per-outcome models counter subscription fatigue in direct-to-consumer channels. |
| Psychometric IP Acquisition | Proprietary assessment instruments create switching costs in executive coaching segments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with chief learning officers, HRIS integration specialists, instructional design directors, and coaching platform operators; and secondary validation through SEC 10-K filings, EU CSRD disclosure databases, corporate learning budget surveys, and ISO certification registries. Bottom-up sizing of enterprise contract values and individual subscription flows triangulated against top-down market aggregation from national workforce development expenditure reports.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning delivery mode, customer type, focus area, and geographic regulatory cluster. CAGRs derived from trend extrapolation of enterprise learning budget growth rates and individual virtual coaching spend patterns, cross-referenced against METI subsidy disbursement trajectories and WIOA funding allocations.
Material uncertainties — regulatory enforcement intensity for human-capital disclosures, AI diagnostic accuracy validation, and credential interoperability adoption — sit outside the modeled envelope. Forecasts reflect assumptions about sustained employer investment in measurable skill development and stable cloud infrastructure cost curves. Recalibration cycles align with material shifts in ISO 30414 adoption rates and EU CSRD audit findings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Leadership Development Program Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
Firefighter Simulator Training Services Market
Professional Development and Training
Global Virtual Training and Simulation Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
RPA Platform Training Market
Professional Development and Training
North America IT Training Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
US Life Coaching Market