
 Motorcycle Cooling Helmets Market | 2026-2036
Motorcycle Cooling Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Cooling Helmets Market Analysis
Modular helmet configurations with detachable cooling inserts is repositioning buyer choice away from fixed-system designs toward upgradeable platforms. Bell Helmets leverages its motorsport heritage to anchor premium positioning in thermoelectric segments. Shoei Co Ltd sustains R&D intensity around multi-density EPS liners with integrated airflow channels. Arai Helmet Ltd specializes in handcrafted fiberglass shells that accommodate aftermarket ventilation modules without compromising structural integrity.
Motorcycle cooling helmets incorporate active or passive thermal management systems—evaporative pads, forced-air channels, or Peltier elements—into standard protective headgear to reduce rider heat stress during operation. Polycarbonate shells dominate unit economics for commuter-grade products, while carbon fiber concentrates margin pools in sport and touring categories where weight reduction amplifies cooling efficiency. Full-face designs lead volume due to enclosed-chamber airflow optimization, yet modular configurations represent the fastest-growing product type as urban riders seek climate adaptability across trip durations. The delivery personnel end-user segment is displacing traditional rider classifications in Asia-Pacific procurement channels.
DOT certification in the United States, ECE 22.06 in Europe, and ISI marking under India's BIS framework collectively shape product standards for impact resistance and ventilation port geometry. These regulations constrain design freedom but create compliance-based differentiation that rewards manufacturers with in-house testing laboratories. Stakeholders must monitor evolving thermal comfort metrics in helmet standards, as regulators in tropical markets begin incorporating heat-stress thresholds alongside traditional impact criteria.
Market Dynamics
The transition from passive ventilation to active thermoelectric cooling systems is restructuring competitive advantage around thermal engineering capabilities rather than shell manufacturing scale. ECE 22.06 certification requirements in Europe and ISI marking mandates in India are forcing simultaneous redesign of impact structures and airflow geometry, compressing product development timelines for legacy helmet producers.
Growth Catalysts
- ECE 22.06 thermal comfort clauses:European helmet standards now incorporate heat-stress thresholds alongside impact criteria, accelerating material upgrades toward Peltier-enabled designs across German and Italian manufacturing bases.
- Urban logistics density in Southeast Asia:Professional delivery fleets in Vietnam, Indonesia, and Thailand are standardizing ventilated headgear procurement as gig-economy rider volumes expand.
- Polycarbonate shell cost curves:Commuter-grade thermoplastic production scaling in India is lowering entry barriers for cooling-equipped helmet categories previously confined to premium carbon fiber segments.
Market Restraints
- Carbon fiber supply concentration:Sport and touring helmet margins depend on Toray and Hexcel fiber allocations concentrated in Japanese and US supply chains, exposing producers to aerospace demand competition.
- Battery thermal runaway risks:Active cooling systems with integrated power sources face extended UN 38.3 lithium-cell certification timelines that delay product launches by 8-14 months.
- Modular retrofit substitution:Aftermarket ventilation modules compatible with legacy full-face designs threaten replacement-cycle revenue for integrated-system manufacturers.
Strategic Opportunities
- BIS thermal comfort mandate expansion:India's Bureau of Indian Standards is evaluating heat-stress metrics for ISI certification, creating first-mover advantage for thermoelectric-equipped suppliers in Mumbai and Bangalore distribution channels.
- Swappable battery ecosystem convergence:Integration with two-wheeler battery swap networks like Gogoro and Sun Mobility is enabling helmet cooling systems to draw power without onboard cells.
- Direct-to-fleet procurement platforms:Logistics aggregators are bypassing traditional retail channels, creating volume contracting opportunities unmediated by helmet specialty distributors.
Industry Challenges
- Multi-physics simulation talent scarcity:Computational fluid dynamics expertise for optimizing forced-air channel geometry competes with automotive and aerospace hiring pools.
- Dual certification synchronization:Achieving concurrent DOT impact approval and ECE 22.06 thermal compliance requires parallel testing tracks that strain in-house laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Cooling Helmets Market |
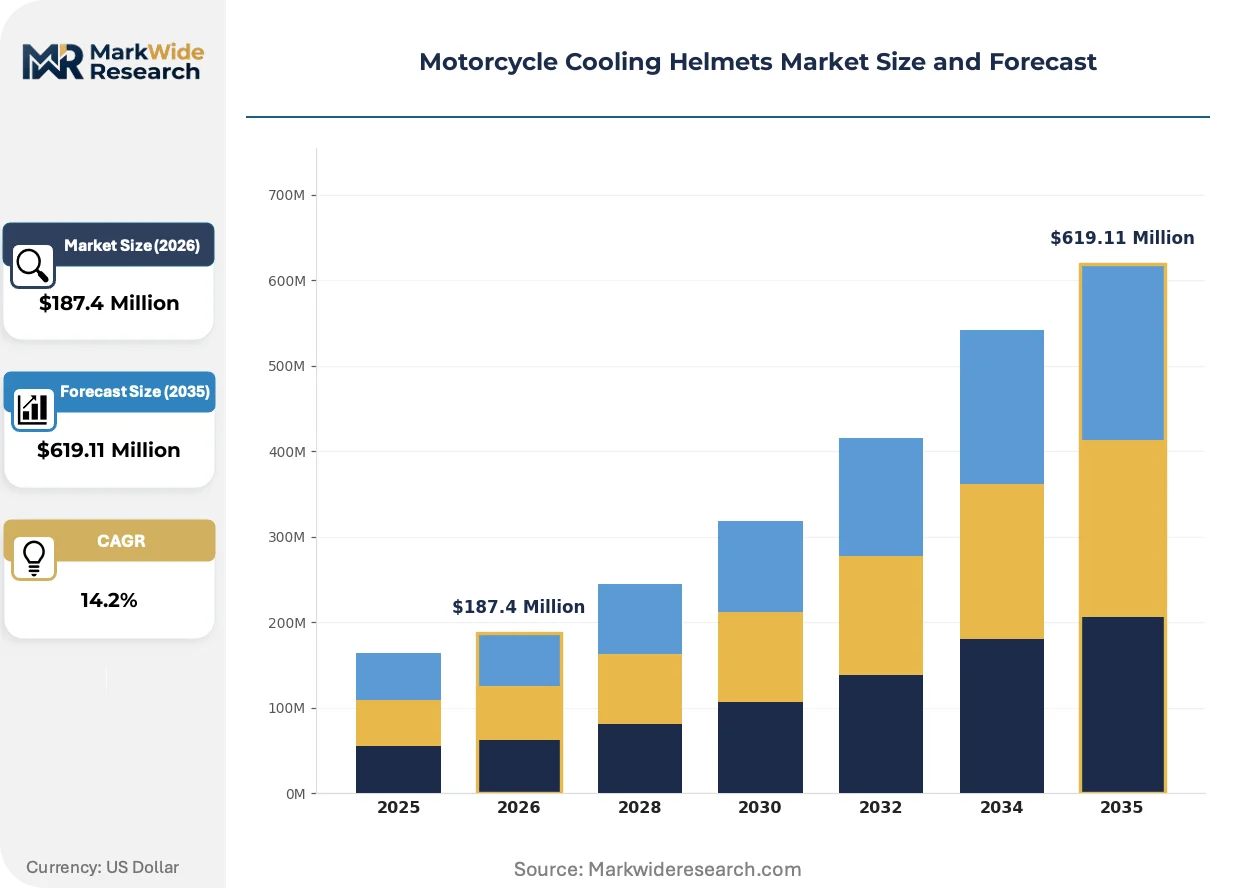
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Face, Modular, Open Face, Half Helmet Cooling Technology: Evaporative Cooling, Active Ventilation, Thermoelectric, Passive Cooling End User: Riders, Delivery Personnel, Sport Enthusiasts, Commuters Material: Polycarbonate, Fiberglass, Carbon Fiber, Composite |
| Companies Covered | Bell Helmets, Shoei Co Ltd, Arai Helmet Ltd, HJC Helmets, AGV, Scorpion Sports Inc, Nolan Helmets, LS2 Helmets, Shark SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Cooling Helmets Market Emerging Trajectories
Active thermal management is migrating from aftermarket accessory to factory-integrated specification, driven by regulatory heat-stress metrics and fleet procurement standardization. This shift favors suppliers with captive electronics assembly capability over pure protective-gear specialists.
Thermoelectric Peltier arrays embedded in crown liners are automating temperature regulation previously managed through manual vent adjustment. Southeast Asian delivery fleets are adopting these systems fastest, with Indonesian and Vietnamese logistics operators specifying active cooling in bulk purchase agreements. The technology is automating rider comfort optimization and compressing differentiation timelines for passive-ventilation legacy products.
REACH substance restrictions on halogenated flame retardants are forcing EPS liner reformulation across European supply chains. Manufacturers must validate new intumescent chemistries without compromising multi-density impact absorption. Modular helmet platforms with detachable cooling inserts face the steepest requalification burden, as port geometry changes trigger full ECE 22.06 retesting.
Fleet procurement managers are consolidating vendor relationships around integrated safety-and-comfort specifications rather than discrete helmet purchases. Direct contracting with manufacturers is displacing traditional distributor intermediaries in India and Southeast Asia. This concentration is most visible in Bangalore and Jakarta, where logistics aggregators negotiate annual volume agreements covering thousands of cooling-equipped units.
Motorcycle Cooling Helmets Market Segmentation
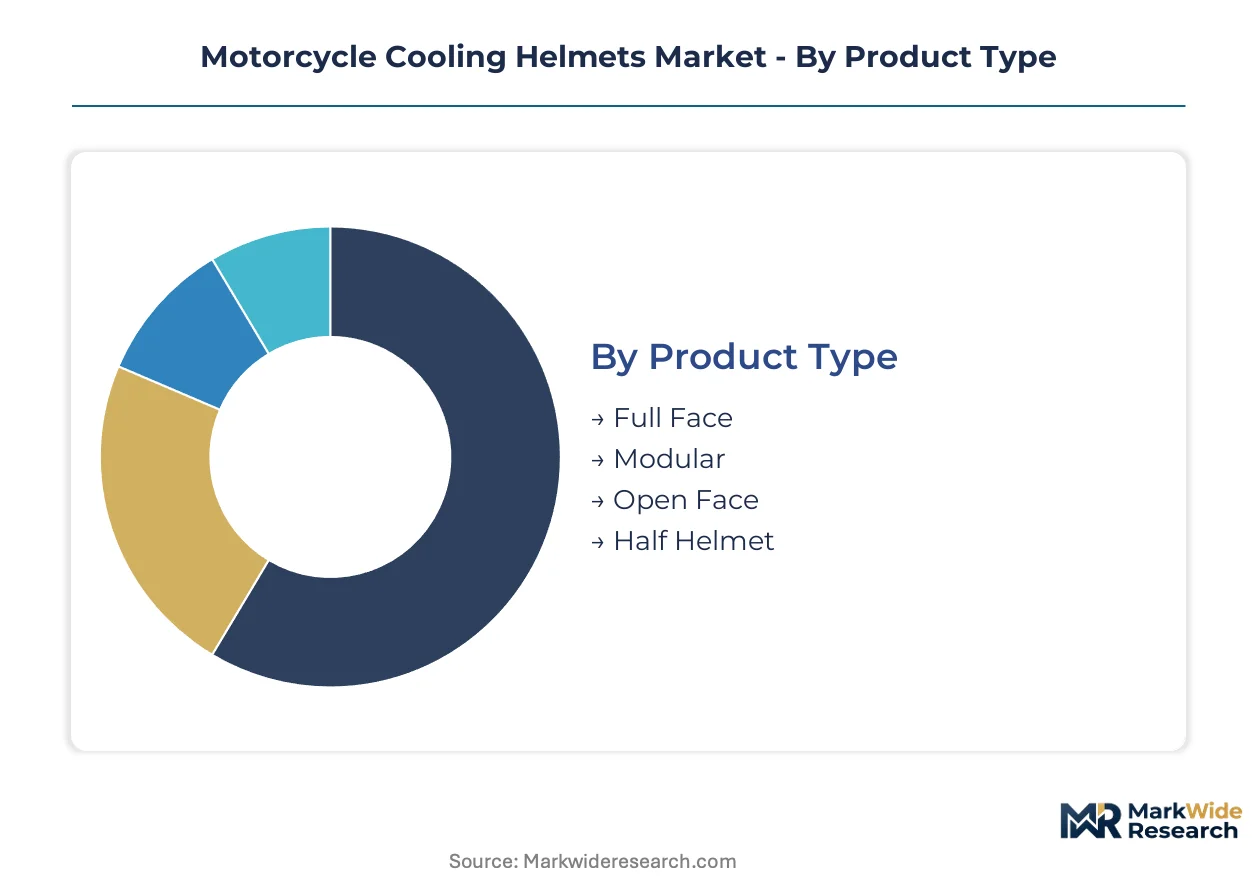
Segmentation in motorcycle cooling helmets reveals how capital allocation, regulatory compliance, and end-use intensity fragment manufacturing priorities across protective headgear categories. Suppliers must match shell material investments to cooling system complexity while navigating divergent certification requirements for commuter versus professional fleet applications.
Product Type:
Capital intensity escalates with ventilation system integration complexity, as enclosed-chamber airflow optimization demands precision tooling for duct geometry and seal tolerances.
- Full Face:Enclosed shell architecture with integrated chin-bar ventilation channels and crown-mounted exhaust ports. Demand concentrates among Indian long-distance commuters facing severe summer heat exposure on National Highway corridors, where sustained airflow prevents heat exhaustion during multi-hour rides. ECE 22.06 thermal comfort clauses are accelerating factory-integrated active cooling specifications in German and Italian manufacturing bases.
- Modular:Hinged chin-bar designs with detachable cooling inserts that accommodate aftermarket thermoelectric upgrades. Vietnamese and Indonesian delivery fleets are standardizing these configurations for climate adaptability across variable trip durations in tropical urban logistics networks. The format reduces inventory complexity for fleet managers specifying single SKUs with modular thermal options.
- Open Face:Three-quarter coverage shells relying on natural airflow without forced ventilation channels. Popular among European urban scooter operators where moderate climates reduce active cooling necessity.
- Half Helmet:Minimal coverage designs with basic passive ventilation through shell perforations. Dominates price-sensitive Indian commuter segments where BIS ISI certification focuses on impact protection rather than thermal metrics.
Most installed capacity flows through Full Face designs. Expansion is steepest in Modular configurations.
Cooling Technology:
Cost tier stratification separates premium thermoelectric systems from commodity passive ventilation, with mid-tier active ventilation capturing volume in emerging market fleet procurement.
- Thermoelectric:Peltier element arrays embedded in crown liners with automated temperature regulation via sensor feedback loops. Bangalore-based logistics aggregators specify these systems in annual volume contracts covering thousands of units, drawn to precise heat-stress management for rider retention in peak summer months. UN 38.3 lithium-cell certification timelines extend product launches by 8-14 months, concentrating supply among manufacturers with captive electronics assembly.
- Active Ventilation:Battery-powered or vehicle-tethered forced-air systems with variable-speed channel flow. Thai delivery platforms are adopting these fastest where Gogoro and Sun Mobility swap networks enable helmet power draw without onboard cells.
- Evaporative Cooling:Hydrophilic pad inserts activated by water absorption, requiring periodic rehydration. Dominates Southeast Asian informal retail channels for cost-constrained individual riders.
- Passive Cooling:Static vent geometry and EPS channel design without powered components. Retains share in European touring segments where ECE 22.06 impact structures already optimize natural airflow.
Volume concentrates in Passive Cooling for individual retail. Thermoelectric systems are climbing the fastest among fleet procurement channels.
End User:
Application intensity determines replacement cycle frequency and specification rigor, with professional use cases demanding integrated safety-comfort standards absent from recreational segments.
- Delivery Personnel:Professional riders operating 8-12 hour shifts in gig-economy logistics networks. Jakarta and Bangkok fleet managers negotiate direct manufacturer contracts bypassing traditional helmet distributors, specifying thermoelectric-equipped units with swappable battery compatibility. Heat-stress liability concerns are driving thermal comfort metrics into procurement scorecards alongside impact ratings.
- Commuters:Daily two-wheeler travelers in Indian metropolitan areas facing seasonal replacement cycles due to pad degradation and vent clogging. Polycarbonate shell economics dominate this segment, with polycarbonate cost curves in Indian manufacturing lowering entry barriers for cooling-equipped categories.
- Sport Enthusiasts:Track and canyon riders prioritizing weight reduction and aerodynamic stability. Carbon fiber shell premiums concentrate margin pools here, though aerospace fiber allocation competition from Toray and Hexcel supply chains constrains volume scaling.
- Riders:General recreational category encompassing weekend touring and casual urban mobility. Fragmented across all cooling technologies with lowest specification consistency.
Procurement volume flows through Commuters. Delivery Personnel represents the fastest-growing specification tier.
Material:
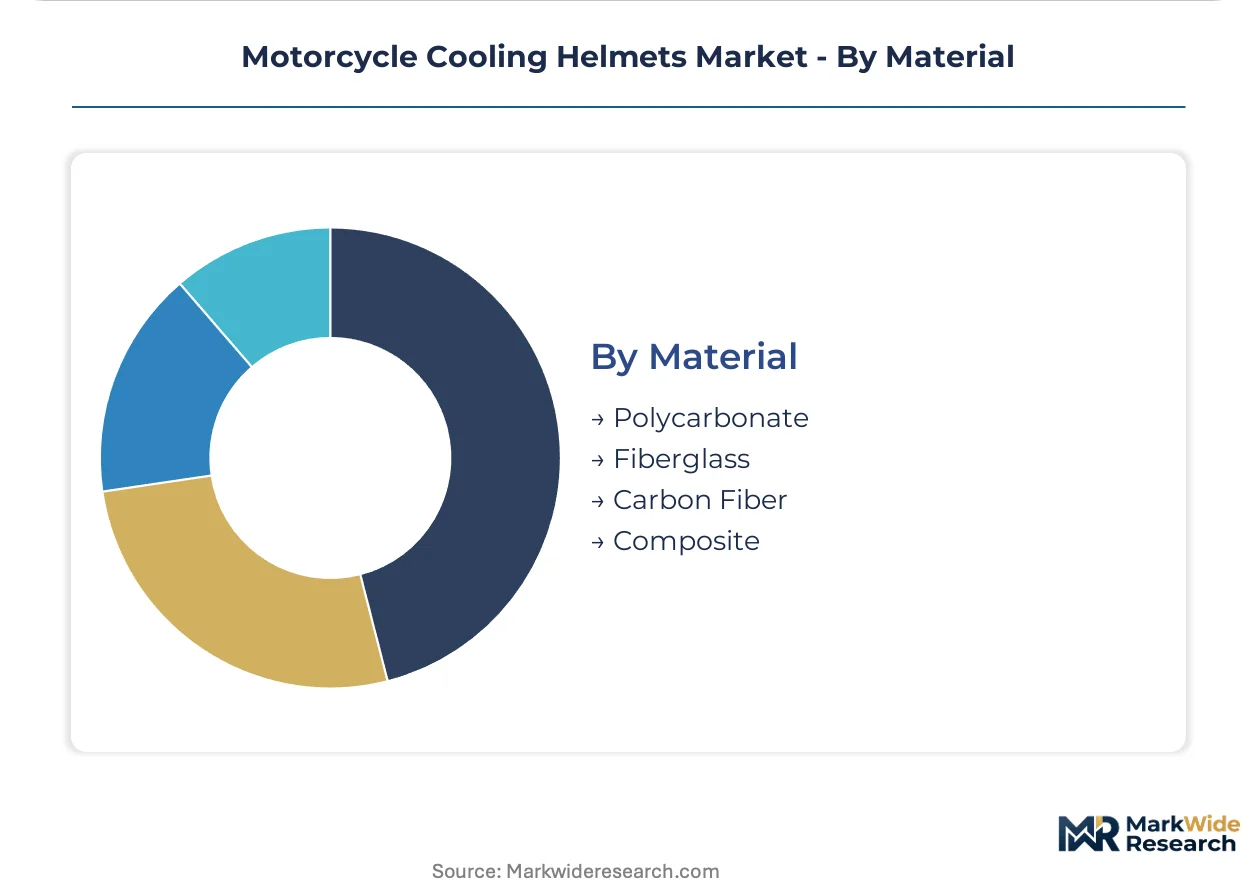
Margin structure inverts between material cost and cooling efficiency, as composite shells enable superior thermal conductivity at premium price points while polycarbonate captures unit economics.
- Polycarbonate:Thermoplastic injection molding enabling high-volume production with integrated ventilation port geometry. Indian manufacturing scaling has compressed entry pricing for cooling-equipped helmets previously confined to premium segments, with Mumbai and Chennai production bases supplying Southeast Asian export demand.
- Carbon Fiber:Aerospace-grade pre-preg layup delivering weight reduction that amplifies active cooling efficiency by reducing thermal mass. Sport and touring categories in Japanese and Italian markets concentrate here, though supply concentration in Toray and Hexcel fiber allocations exposes producers to aerospace demand competition.
- Fiberglass:Hand-laminated composite shells accommodating aftermarket ventilation modules without structural compromise. Arai Helmet Ltd specializes in this format for premium touring configurations.
- Composite:Hybrid fiber matrices combining aramid, glass, and carbon layers for optimized strength-to-weight ratios. Emerging in European modular designs facing REACH substance restrictions on halogenated flame retardants.
Unit volume concentrates in Polycarbonate. Carbon Fiber captures the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The motorcycle cooling helmets industry traces its manufacturing lineage to Japanese precision engineering traditions established in the 1970s, with Italian and German producers subsequently developing thermal management specializations that shaped modern certification standards.
India
Two-wheeler commuter volumes exceeding twenty million annual registrations and severe summer heat exposure on National Highway corridors sustain replacement cycles for cooling-equipped helmets. BIS ISI certification mandates under India's Bureau of Indian Standards are evaluating heat-stress metrics for future inclusion, with Mumbai and Chennai production bases supplying polycarbonate shell units to Southeast Asian export channels.
Germany
ECE 22.06 thermal comfort clauses now incorporate heat-stress thresholds alongside traditional impact criteria, forcing simultaneous redesign of ventilation geometry and shell structures. KBA oversight ensures compliance verification through in-house testing laboratory accreditation, with Bavaria-based manufacturing clusters advancing Peltier-enabled thermoelectric designs for premium touring segments.
Vietnam
Gig-economy logistics networks in Ho Chi Minh City and Hanoi are standardizing ventilated headgear procurement as urban delivery density intensifies. Fleet managers negotiate direct manufacturer contracts bypassing traditional retail distributors, specifying modular helmet configurations with detachable cooling inserts for climate adaptability across variable tropical trip durations.
Indonesia
Jakarta-based logistics aggregators specify thermoelectric-equipped units in annual volume agreements covering thousands of helmets, drawn to precise heat-stress management for rider retention during peak summer months. The national standards body is monitoring ECE 22.06 thermal metric developments for potential domestic adoption, with Jababeka industrial estates hosting assembly operations for regional distribution.
United States
DOT certification requirements constrain ventilation port geometry design freedom while creating compliance-based differentiation for manufacturers with captive testing infrastructure. NHTSA regulatory frameworks focus on impact resistance rather than thermal comfort, positioning the market toward passive ventilation optimization in carbon fiber sport segments concentrated in California and Arizona riding corridors.
Motorcycle Cooling Helmets Market Vendor Landscape
The competitive structure tilts toward integrated protective-gear specialists with captive electronics assembly capability rather than pure shell fabricators. Market concentration remains moderate, with tiered differentiation separating premium thermoelectric system suppliers from commodity passive-ventilation producers. Three archetypes dominate: motorsport-heritage brands leveraging racing credibility for thermal management positioning, precision-engineering Japanese specialists with multi-decade R&D intensity, and Asian volume manufacturers scaling polycarbonate economics for fleet procurement channels. Dominant competitive moves include direct-to-fleet contracting platforms bypassing traditional distributor intermediaries, and backward integration into thermoelectric component assembly to compress UN 38.3 lithium-cell certification timelines.
Among heritage-protective-gear specialists, Bell Helmets and Arai Helmet Ltd exemplify divergent material philosophies within the premium tier, while Shoei Co Ltd occupies a position representing Japanese precision-engineering continuity. Bell Helmets anchors motorsport-derived credibility in North American markets. Arai Helmet Ltd exemplifies handcrafted fiberglass shell traditions accommodating aftermarket ventilation modules. Shoei Co Ltd represents sustained R&D investment intensity around integrated airflow channel architectures. These three entities collectively illustrate how manufacturing lineage translates into distinct thermal management positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| Bell Helmets |
| Shoei Co Ltd |
| Arai Helmet Ltd |
| HJC Helmets |
| AGV |
| Scorpion Sports Inc |
| Nolan Helmets |
| LS2 Helmets |
| Shark SAS |
| Others |
Supply Flow & Price Mechanics
Thermoelectric Peltier integration into crown liners simultaneously compresses manufacturing cost curves and concentrates supply among captive electronics assemblers, rewiring pricing power toward thermal engineering specialists and away from legacy shell fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates thermoelectric-equipped units with UN 38.3 certification from active-ventilation mid-tiers and passive-ventilation commodity helmets. Price differentiation hinges on ECE 22.06 thermal compliance grade and polycarbonate versus carbon fiber shell material. Pricing pressure stems from Indian polycarbonate scaling lowering entry barriers for cooling-equipped categories. Delivery personnel fleets exhibit lowest price sensitivity due to heat-stress liability concerns, while individual commuters in Southeast Asian informal channels drive hardest bargain.
Supply Chain Analysis
Freight cost escalation from Jababeka industrial estates to Jakarta distribution hubs and Chennai-to-Mumbai corridors is compressing margin pools for polycarbonate shell producers serving Southeast Asian export demand. Manufacturing concentrates in India, Vietnam, and Indonesia assembly operations. Raw material flows draw from Toray and Hexcel carbon fiber allocations, lithium-cell suppliers facing UN 38.3 certification bottlenecks, and polycarbonate resin producers. Single-source vulnerability in aerospace-grade fiber exposes producers to automotive and aviation demand competition. Distribution runs through direct-to-fleet procurement platforms displacing traditional helmet specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into sustained demand expansion, with ECE 22.06 thermal comfort clauses in Europe forcing material upgrades that cascade through global certification benchmarks.
For Market Incumbents: Deploy captive thermoelectric assembly capacity to compress UN 38.3 lithium-cell certification timelines and defend against modular retrofit substitution threatening integrated-system revenue. Accelerate backward integration into Peltier element sourcing to secure supply continuity against semiconductor demand competition. Fortify direct-to-fleet contracting relationships with Jakarta and Bangkok logistics aggregators before channel displacement completes. For New Entrants and Emerging Players: BIS thermal comfort mandate expansion in India opens a window for first-mover positioning in Mumbai and Bangalore distribution channels ahead of formal heat-stress metric adoption. Target Vietnamese delivery fleet procurement where modular helmet configurations with detachable cooling inserts reduce inventory complexity for climate-adaptable specifications. Pursue Gogoro and Sun Mobility battery swap network integration as a go-to-market angle eliminating onboard cell certification burdens. For Investors and Strategic Acquirers: Valuations sit cheapest among polycarbonate volume manufacturers scaling commuter-grade production without captive electronics assembly capability. Long-term viability favors integrated protective-gear specialists with thermal engineering R&D intensity and in-house testing laboratory accreditation. Watch for BIS formal adoption of heat-stress metrics as the inflection signal triggering acquisition premiums for thermoelectric-equipped suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoelectric System Integration | ECE 22.06 thermal compliance in Germany and Italy accelerates factory-embedded Peltier specifications. |
| Direct-to-Fleet Procurement Platform | Jakarta and Bangkok logistics aggregators bypass traditional distributors for annual volume agreements. |
| Swappable Battery Ecosystem Convergence | Gogoro and Sun Mobility networks enable helmet power draw without UN 38.3 onboard cell certification. |
| Multi-Physics Simulation Capability Buildout | CFD expertise scarcity in automotive and aerospace hiring pools rewards captive talent acquisition. |
| Dual Certification Laboratory Investment | Parallel DOT and ECE 22.06 testing tracks strain capacity and reward in-house accreditation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with helmet R&D directors, fleet procurement managers at Jakarta and Bangkok logistics aggregators, BIS certification officers, and polycarbonate manufacturing plant heads with secondary validation against ECE 22.06 regulatory filings, UN 38.3 lithium-cell certification databases, and Indian two-wheeler registration statistics. Bottom-up segment sizing and top-down market reconciliation provided cross-verification.
Segment-weighting across product type, cooling technology, end user, material, and geography dimensions shaped the analytical framework over the projection horizon. CAGRs derived from logistic adoption curves for thermoelectric systems and polycarbonate cost curve trajectories in Indian manufacturing. Industry-specific inputs incorporated ECE 22.06 thermal clause implementation timelines and Gogoro network expansion patterns.
Revisions become necessary when BIS formalizes heat-stress metrics ahead of projected adoption curves, when aerospace fiber allocation competition intensifies beyond modeled scenarios, or when modular retrofit penetration exceeds integrated-system displacement thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
GPS Bike Computers Market