
 Bass Guitar Market | 2026-2036
Bass Guitar Market Size, Share, and Industry Trends Forecast 2026-2036
Bass Guitar Market Analysis
Professional-grade specification tiers is rotating the Bass Guitar Market toward higher-margin instruments. Fender leverages its American Professional II line to anchor premium positioning in North American retail channels. Yamaha competes through vertical integration of its wood-drying facilities and in-house pickup manufacturing in Japan. Warwick sustains artisan-grade credibility with its German-built Thumb and Streamer series.
A bass guitar is a stringed instrument tuned to lower registers than standard guitars, typically featuring four to six strings with scale lengths between 30 and 35 inches and solid-body or hollow-body construction designed for amplified low-frequency reproduction in ensemble settings. Electric bass variants dominate volume sales, while fretless bass commands disproportionate margin pools among jazz and session specialists. Amateur players represent the broadest addressable base, though professional musicians concentrate value through repeat purchases of custom-shop instruments and limited editions.
RoHS and REACH frameworks in Europe restrict hazardous substances in electronic components and finishes, compelling manufacturers to reformulate solder alloys and lacquer systems for export compliance. The EPA governs volatile organic compound emissions from coating operations in United States production facilities. Stakeholders must monitor evolving timber certification requirements under CITES for rosewood and mahogany, as supply chain documentation standards tighten instrument market access.
Market Dynamics
RoHS compliance in the European Union and CITES timber restrictions are forcing manufacturers to requalify electronics suppliers and document sustainable tonewood sourcing, compressing margin structures while professional musicians demand higher-specification instruments.
Growth Catalysts
- Professional touring expansion:Session musicians in Nashville and Los Angeles studio hubs are expanding instrument collections for tonal versatility across recording projects.
- REACH framework reformulation:European finish and solder alloy requirements are accelerating lead-free electronics adoption among export-oriented manufacturers.
- Fretless premiumization:Jazz specialists and studio contractors command disproportionate margins through custom-shop and limited-edition acquisitions.
Market Restraints
- Rosewood supply documentation:CITES Appendix II permitting requirements for Dalbergia species create procurement friction and inventory holding costs.
- Pickup magnet material volatility:Neodymium and alnico price swings concentrate in Chinese processing facilities, squeezing component budgets.
- Amplifier substitution:Software-based amp modeling and direct-injection recording setups reduce hardware bass amplifier demand among home-studio operators.
Strategic Opportunities
- India emerging demand:Urban music education expansion in Mumbai and Bangalore creates entry points for mid-tier electric bass distribution.
- Short-scale segment:Travel musicians and younger players with smaller physical statures represent an underserved specification tier.
- Modular electronics architecture:Swappable preamp modules allow players to reconfigure tone circuits without full instrument replacement.
Industry Challenges
- Luthier skill scarcity:Fretless fingerboard dressing and compound-radius neck finishing require specialized craft training that vocational programs undersupply.
- Compliance timeline compression:Dual certification requirements for EPA VOC emissions and EU RoHS solder standards strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bass Guitar Market |
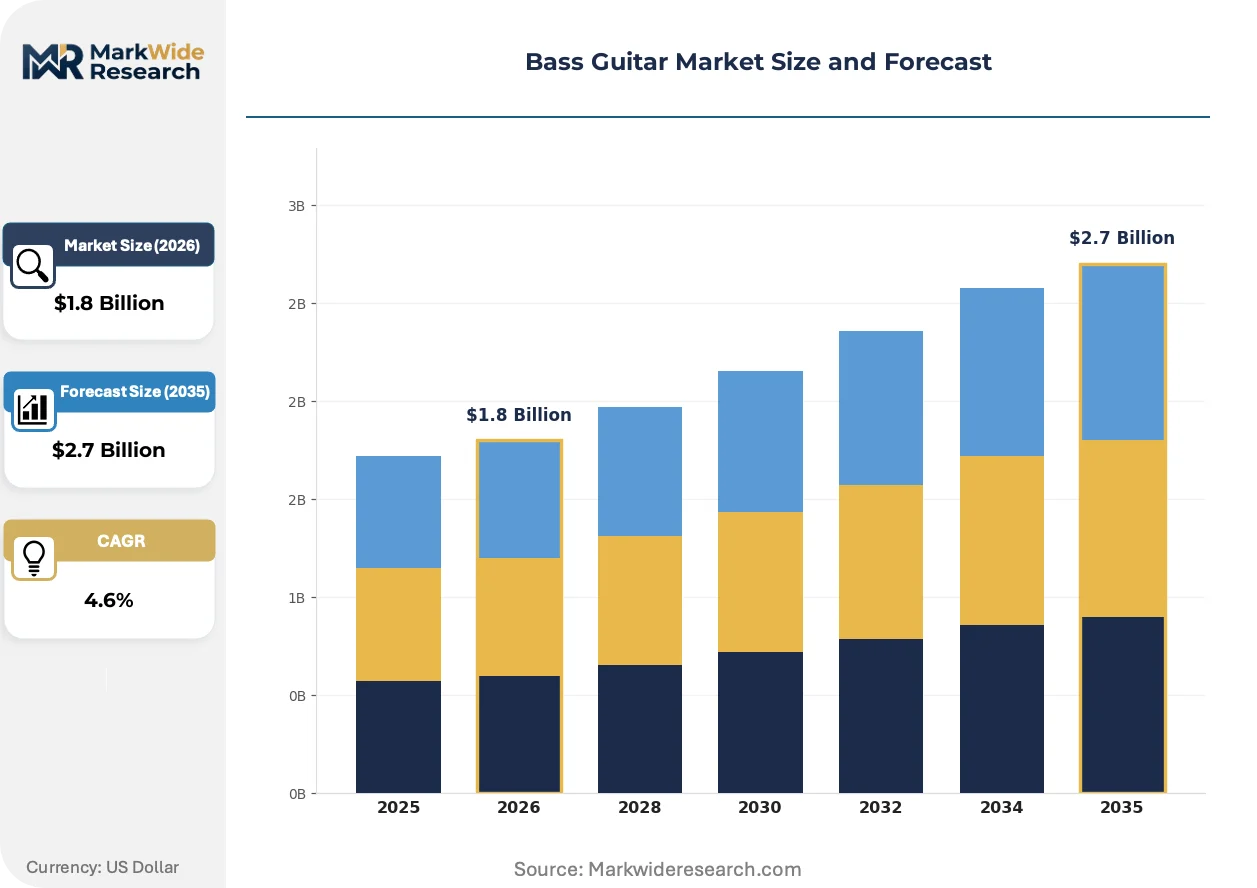
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Bass, Acoustic Bass, Double Bass, Fretless Bass End User: Professional Musicians, Amateur Players, Schools, Studios Material: Mahogany, Alder, Ash, Maple Feature: Active Pickups, Passive Pickups, Custom Colors, Built-in Effects |
| Companies Covered | Yamaha, Warwick, Fender, ESP, Schecter, Ibanez, Gibson, Rickenbacker, Music Man, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bass Guitar Market Emerging Trajectories
Active electronics and alternative tonewoods are restructuring competitive differentiation in bass guitar manufacturing, with sustainability credentials and signal-chain integration emerging as parallel value axes.
Multi-scale (fan-fret) neck construction is bifurcating the extended-range bass segment. Progressive metal and technical death metal bassists adopt 5-string and 6-string configurations with compound scale lengths for improved low-B clarity and high-string tension balance. This specification is compressing demand for traditional parallel-fret extended-range instruments below the $1,500 retail threshold.
EPA volatile organic compound regulations governing nitrocellulose lacquer application in United States finishing facilities are forcing coating system transitions. Manufacturers reformulate with waterborne and UV-cured alternatives that alter final appearance and aging characteristics. Vintage-reissue product lines face the steepest reformulation burden as authenticity expectations clash with emissions compliance.
Direct-to-consumer channel expansion is fragmenting traditional dealer networks. Independent luthiers and mid-tier brands bypass distributor markups through configured-to-order web platforms with video demonstration content. This pattern concentrates in North American metropolitan markets where players prioritize specification control over immediate physical trial.
Bass Guitar Market Segmentation
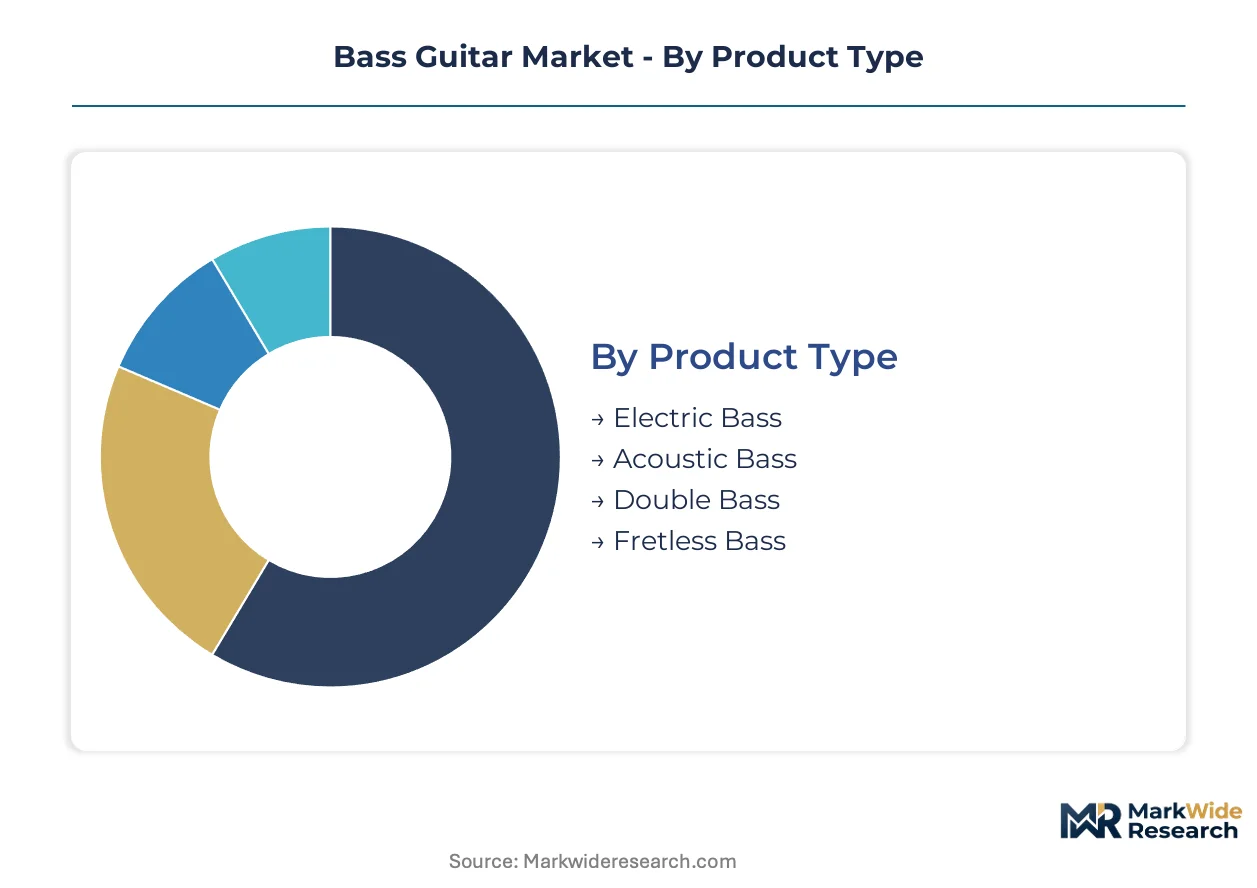
Bass guitar segmentation reveals how substitute technologies and compliance costs reshape procurement priorities across player categories. Specification tiers diverge sharply between touring professionals seeking signal-chain integration and education buyers prioritizing durability.
Product Type:
Software amp modeling and direct-injection recording setups exert substitution pressure most acutely on standard electric bass configurations, while acoustic and fretless variants retain irreplaceable tonal signatures.
- Electric Bass:Solid-body construction with magnetic pickups dominates volume sales across retail channels. Nashville and Los Angeles studio contractors drive repeat purchases of American-built instruments for session versatility, though home-studio operators increasingly bypass hardware amplifiers.
- Fretless Bass:Smooth fingerboard surfaces enable microtonal expression and sliding articulation unavailable on fretted equivalents. Jazz specialists and orchestral contractors in German and Japanese metropolitan markets sustain premium pricing through custom-shop acquisitions.
- Acoustic Bass:Hollow-body designs with piezoelectric pickups serve unplugged performance contexts and singer-songwriter ensembles.
- Double Bass:Upright acoustic construction with orchestral tuning anchors classical and jazz upright traditions.
Electric bass retains volume leadership; fretless bass holds the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement from individual acquisition patterns, with schools and studios facing compressed budgets against professional musician specification demands.
- Professional Musicians:Touring artists and session contractors maintain instrument collections spanning multiple scale lengths and electronics configurations. Repeat purchase cycles concentrate in Nashville, Los Angeles, and Tokyo metropolitan clusters where recording density supports specialized tool requirements.
- Amateur Players:Entry-level and intermediate instruments constitute the broadest addressable base through mass retail and direct-to-consumer channels. Price sensitivity dominates selection criteria, with younger players in Indian urban education markets representing emerging volume.
- Schools:Bulk procurement programs prioritize durability and standardized maintenance protocols over tonal refinement.
- Studios:Rental and house instrument pools require versatile passive electronics for broad compatibility.
Amateur players anchor volume scale; professional musicians concentrate margin capture.
Material:
Supply concentration for certified sustainable tonewoods is reconfiguring manufacturer sourcing strategies as CITES documentation requirements tighten market access.
- Alder:Lightweight closed-grain hardwood delivers balanced frequency response with minimal finishing requirements. Pacific Northwest suppliers in the United States face EPA VOC compliance burdens that increase processing costs for export-oriented manufacturers.
- Mahogany:Dense interlocking grain structure provides warm low-mid resonance prized in premium instrument lines. Dalbergia species documentation under CITES Appendix II creates procurement friction and extended lead times for European and North American builders.
- Ash:Open-pore grain character produces pronounced high-end articulation in solid-body construction.
- Maple:Hard, dense tonewood employed for neck construction and bright-toned bodies.
Alder sustains volume dominance in electric bass bodies; mahogany faces supply constraint pressure.
Feature:
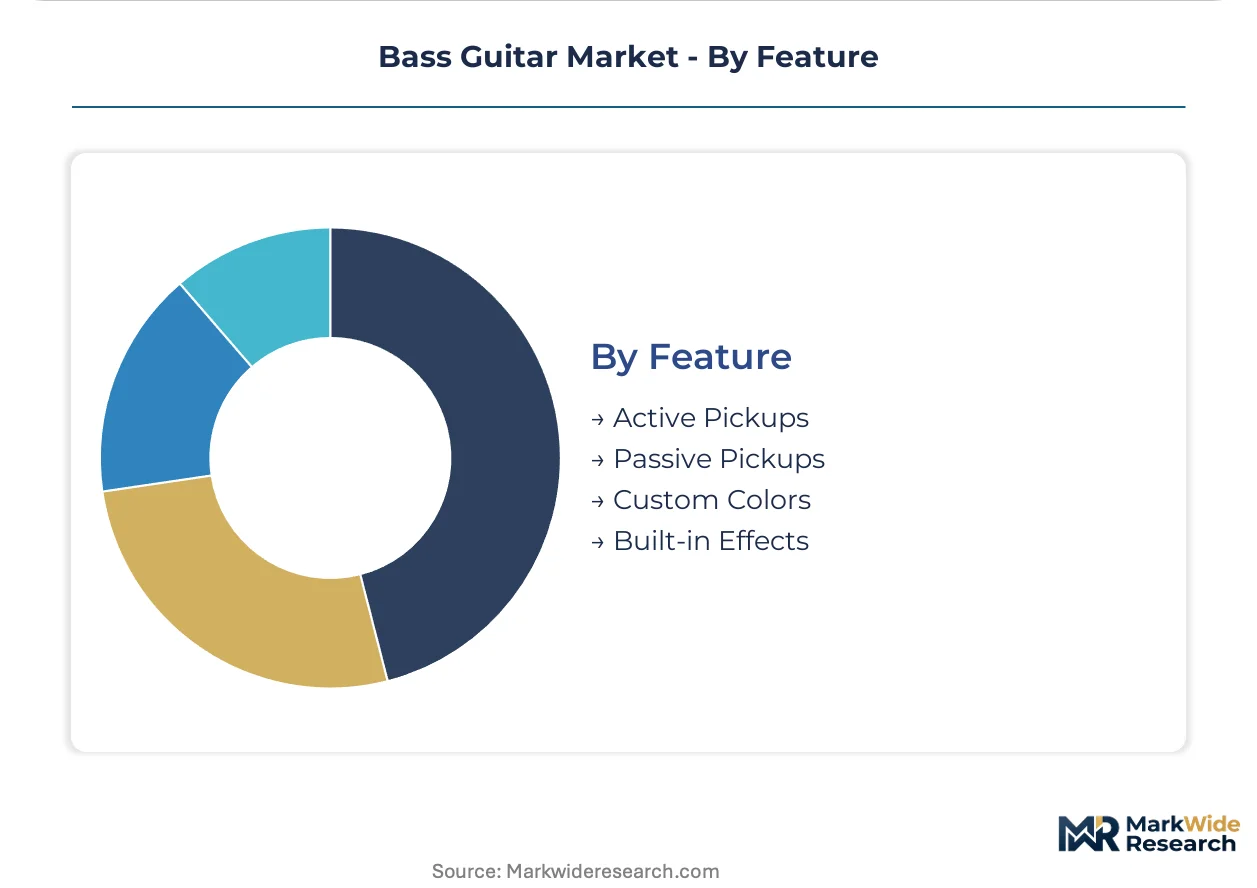
Electronics architecture differentiation separates signal-chain integration capabilities from baseline passive configurations, with active systems commanding specification premiums in professional segments.
- Active Pickups:Onboard preamplification with EQ shaping enables extended frequency control and low-impedance output for long cable runs. Metal and progressive genres in technical playing communities drive adoption for extended-range instruments requiring precise low-B articulation.
- Passive Pickups:Direct magnetic induction without battery dependency offers reliability and vintage tonal character. Traditional rock and blues player communities in United States and European markets sustain demand for simplified signal chains.
- Custom Colors:Specialized finish formulations including metallic, burst, and opaque lacquer systems.
- Built-in Effects:Integrated compression, overdrive, or octave circuits in instrument electronics.
Passive pickups retain installed base scale; active pickups gain share fastest among extended-range adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing clusters in the United States, Germany, Japan, India, and China concentrate distinct competitive advantages across tonewood processing, electronics integration, and artisan craft traditions. Each geography shapes procurement and compliance requirements differently.
United States
Nashville session contractors and Los Angeles studio musicians drive repeat purchases of premium instruments for recording versatility. EPA volatile organic compound regulations govern nitrocellulose lacquer application in finishing facilities, forcing coating system transitions. California and Tennessee host the densest concentrations of custom-shop builders and major brand distribution centers.
Germany
Jazz specialists and orchestral contractors in Berlin and Hamburg sustain demand for fretless and artisan-grade instruments. REACH framework requirements restrict hazardous substances in electronic components and finishes, compelling reformulation of solder alloys. Markneukirchen in Saxony anchors centuries-old lutherie traditions with specialized vocational training pipelines.
Japan
Tokyo metropolitan recording density supports professional musician specification demands for extended-range and active electronics configurations. METI industrial standards govern electronics manufacturing quality protocols. Nagoya and Hamamatsu clusters concentrate wood-drying facilities and in-house pickup production capabilities.
India
Urban music education expansion in Mumbai and Bangalore creates entry points for mid-tier electric bass distribution. BIS certification requirements apply to imported electronics and finished instruments. Maharashtra and Karnataka host emerging retail networks and institutional procurement programs for schools.
China
Processing concentration for neodymium and alnico magnet materials supplies global pickup manufacturers, though price volatility squeezes component budgets. MIIT standards govern industrial emissions from coating and electronics assembly operations. Guangdong and Zhejiang provinces concentrate OEM manufacturing and export-oriented assembly facilities.
Bass Guitar Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the bass guitar market. Premium positioning concentrates among heritage brands with artisan manufacturing credentials, while scale-driven competitors optimize electronics integration and supply chain efficiency. Two strategic archetypes dominate: vertically integrated manufacturers controlling wood-drying and pickup production, and configured-to-order specialists leveraging direct-to-consumer channels. Competitive moves center on portfolio diversification across extended-range specifications and geographic expansion into emerging education markets.
Within the heritage-brand tier, Fender and Yamaha exemplify contrasting operational models. Fender anchors premium positioning through North American retail channel presence and American-built product lines. Yamaha represents vertical integration advantages with captive wood-drying facilities and in-house electronics manufacturing. Warwick occupies the artisan-grade position with German-built specialty instruments for professional segments. These three players illustrate how manufacturing geography and supply chain control differentiate competitive positioning across specification tiers.
| Leading Market Players |
|---|
| Yamaha |
| Warwick |
| Fender |
| ESP |
| Schecter |
| Ibanez |
| Gibson |
| Rickenbacker |
| Music Man |
| Others |
Supply Flow & Price Mechanics
Alnico and neodymium magnet substitution in pickup manufacturing simultaneously redraws procurement geography toward Chinese processing facilities and compresses component budgets across premium and standard instrument tiers. This input shift forces manufacturers to requalify electronics suppliers while professional musicians demand higher-specification active systems, creating divergent cost pressures across product lines.
Pricing Analysis
RoHS and REACH compliance dictates the pricing tier structure across European export markets, compelling lead-free solder and reformulated finish systems that elevate processing costs. Three-tier pricing structure across premium artisan, professional-grade, and entry-level instruments separates German-built custom shops from Asian-manufactured volume lines. Pricing pressure stems from CITES documentation requirements for rosewood and mahogany, which extend lead times and inflate procurement overhead. Amateur players in education markets exhibit highest price sensitivity, while session musicians in Nashville and Los Angeles absorb premiums for signal-chain versatility.
Supply Chain Analysis
China and Japan anchor global pickup magnet processing and precision electronics manufacturing respectively, with Guangdong Province concentrating neodymium refinement and Nagoya hosting in-house winding operations. Tonewood supply draws from Pacific Northwest alder forests and Southeast Asian mahogany plantations, both subject to tightening certification protocols. Single-source vulnerability concentrates in Chinese rare-earth processing, where export quota fluctuations transmit directly to component pricing. Distribution runs through North American retail dealer networks, though direct-to-consumer web platforms fragment traditional channel control in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active electronics integration and multi-scale neck architecture are disrupting traditional specification hierarchies, with REACH and RoHS compliance timelines accelerating manufacturer differentiation investments.
For Market Incumbents: Shield market position through backward integration into wood-drying facilities and captive pickup manufacturing, mirroring Yamaha's Nagoya cluster model. Secure CITES-compliant tonewood inventories ahead of documentation requirement tightening. Prioritize modular electronics architectures that allow player reconfiguration without full instrument replacement, defending against software amp modeling substitution.
For New Entrants and Emerging Players: Configured-to-order service layers where heritage brands under-serve present immediate white-space opportunity, particularly for extended-range and short-scale specifications. Target India's emerging urban education markets in Mumbai and Bangalore with mid-tier electric bass distribution. Leverage video demonstration content and specification control platforms to bypass established dealer markups.
For Investors and Strategic Acquirers: REACH framework implementation reshapes the acquisition landscape toward manufacturers with certified sustainable sourcing and lead-free electronics capabilities. Five-to-ten year viability favors vertically integrated mid-cap specialists with wood-drying and in-house pickup production. Monitor CITES Appendix II expansion deliberations as inflection signal for timber-dependent valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Electronics Architecture | Swappable preamp modules enable tone reconfiguration without instrument replacement, extending product lifecycle. |
| Sustainable Tonewood Certification | CITES-compliant documentation secures market access for rosewood and mahogany-dependent premium lines. |
| Direct-to-Consumer Platform Launch | Video demonstration content and configuration tools bypass distributor markups in North American metropolitan markets. |
| Short-Scale Product Line Extension | Travel musicians and younger players with smaller physical statures represent underserved specification tier. |
| India Distribution Partnership | Urban music education expansion in Mumbai and Bangalore creates mid-tier volume entry points. |
Methodological Framework
Initial hypotheses were tested against primary input from instrument manufacturing executives, tonewood procurement specialists, session musicians, and retail channel managers and refined through secondary validation. Primary fieldwork encompassed luthier craft training programs in Markneukirchen and Nagoya, dealer network interviews in Nashville and Los Angeles, and electronics supplier assessments in Guangdong. Secondary sources included CITES permit databases, EPA VOC emission filings, REACH substance restriction updates, and customs trade records for tonewood imports. Bottom-up instrument shipment data triangulated against top-down market value estimates.
Variance decomposition across the projection horizon isolates volume growth from price-mix effects and regulatory cost pass-through. Segmentation dimensions encompass product type, end-user category, material specification, and electronics architecture, with geographic regulatory clusters modeled separately. CAGRs derive from instrument replacement cycle analysis, education market penetration curves, and professional musician collection expansion patterns. Forecast inputs incorporate CITES documentation timeline assumptions and REACH substance restriction phase-in schedules.
Underlying assumptions cover stable rare-earth magnet pricing, gradual REACH compliance adoption curves, and sustained urban music education funding in emerging markets, with deviation risk concentrated in timber certification expansion and electronics component tariff volatility. Recalibration cycles align with material shifts in regulatory enforcement intensity and substitution technology adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Guitar Market
Musical Instruments
Violin Market
Musical Instruments
Digital Piano Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Electric Violin Market
Musical Instruments
Drum Sets Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Global Piano Market