
 Canada Accounting Software Market | 2026-2036
Canada Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Accounting Software Market Insights
The price-performance gap between premium enterprise suites and commodity bookkeeping tools is hardening in the Canadian market. QuickBooks leverages its brand recognition and channel density to anchor the small-business segment across suburban and rural postal codes. Sage Intacct competes through specialized multi-entity consolidation features that appeal to mid-market manufacturers with cross-provincial operations. FreshBooks differentiates by occupying the freelancer and service-contractor niche with simplified project-based billing workflows.
Canada accounting software encompasses applications that automate financial record-keeping, reporting, and compliance through configurable general ledgers, chart-of-accounts architectures, and real-time bank-feed reconciliation engines, serving primarily to reduce manual entry error and accelerate statutory filing timelines. Cloud-based deployment leads absolute subscriber growth as Canadian firms prioritize remote accessibility and automatic security patching over capital-intensive server ownership. The payroll functionality segment carries concentrated margin pools because provincial remittance rules vary across Quebec, Ontario, and Alberta, creating complexity that justifies premium pricing for compliant automation.
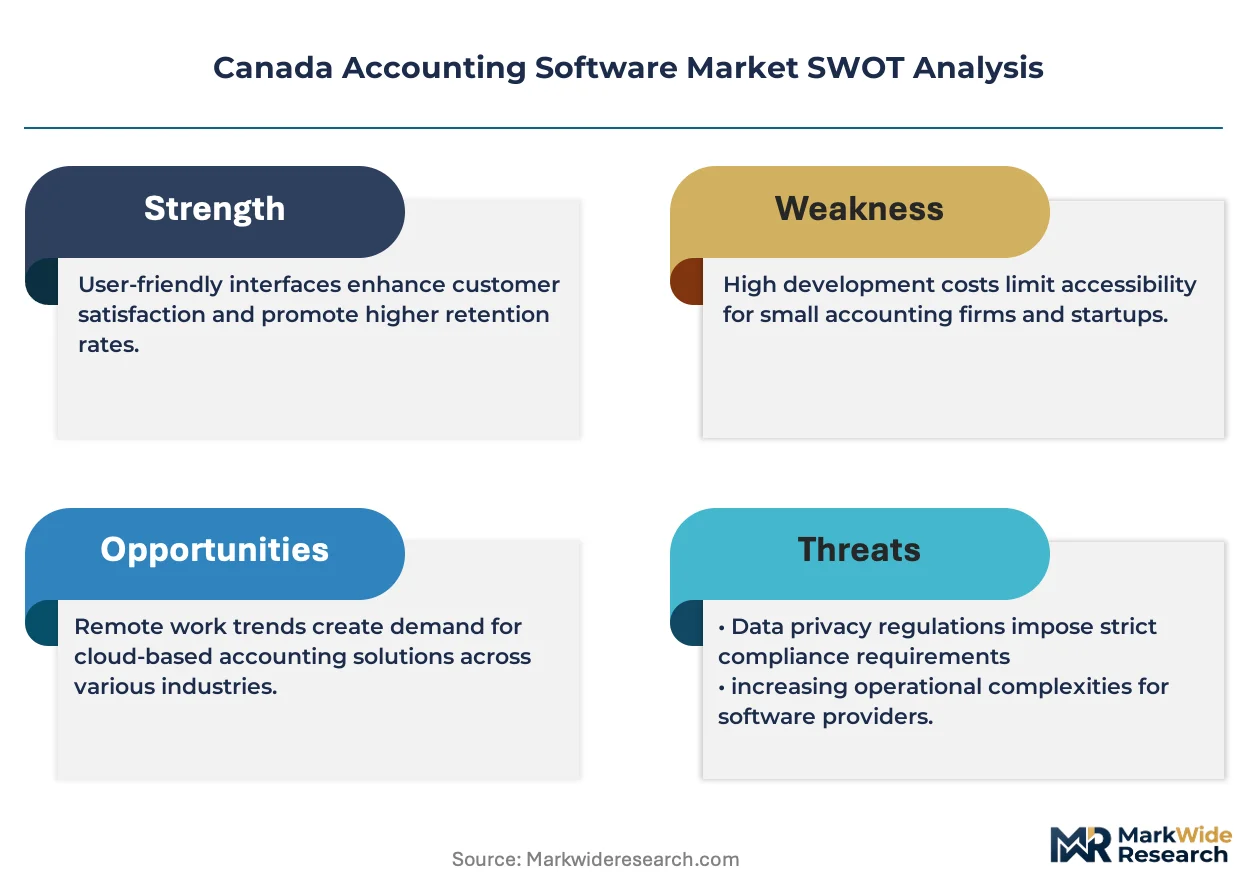
Health Canada's data residency expectations for sensitive financial information, alongside PIPEDA privacy obligations and CRA electronic-filing mandates, collectively elevate compliance burdens that favor vendors with certified Canadian data centers and audit-trail documentation. The Canadian Securities Administrators' evolving guidance on financial software governance adds scrutiny for enterprise buyers in regulated industries. Stakeholders must weigh whether to consolidate around vendors with proven provincial tax-rule accuracy or maintain multi-platform stacks that fragment compliance risk.
Market Dynamics
The Canada Revenue Agency's mandatory digital reporting timeline is compressing adoption cycles for cloud-native platforms while fragmenting legacy on-premise installed bases. Provincial tax-rule heterogeneity—particularly Quebec's distinct remittance architecture—creates compliance complexity that favors specialized automation over generic bookkeeping tools.
Growth Catalysts
- Open Banking API Framework:The federal government's consumer-directed finance regulations are unlocking real-time bank-feed reconciliation capabilities that reduce manual entry workloads for Ontario-based professional services firms.
- Mid-Market Manufacturers:Cross-provincial entities with operations spanning Alberta, Ontario, and British Columbia are consolidating multi-entity financials through automated consolidation engines that eliminate spreadsheet-dependent close processes.
- Freelancer Economy Density:Vancouver and Toronto metropolitan areas host concentrated populations of independent contractors demanding project-based billing workflows with integrated time-tracking and client-portal functionality.
Market Restraints
- Data Residency Compliance Costs:Health Canada's sensitive financial information guidelines and PIPEDA obligations mandate certified Canadian data center infrastructure that elevates operational overhead for foreign platform providers.
- Provincial Tax-Rule Fragmentation:Quebec's distinct payroll remittance schedules and Alberta's unique corporate filing requirements force vendors to maintain parallel compliance codebases that inflate development and maintenance expenditure.
- Substitution by Embedded Finance:Vertical SaaS platforms in construction and professional services are absorbing core accounting functions into industry-specific operational software, compressing standalone tool addressable markets.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick small-business segments exhibit lower cloud-accounting penetration relative to Ontario benchmarks, creating whitespace for localized channel partnerships and province-specific onboarding workflows.
- AI-Assisted Audit Preparation:Machine learning models trained on CRA electronic-filing validation patterns can automate documentation assembly and anomaly flagging before submission, reducing accountant review hours.
- Indigenous Enterprise Segment:First Nations economic development corporations and band-administered enterprises require specialized trust-accounting and grant-compliance modules that incumbent platforms have not configured.
Industry Challenges
- Provincial Tax-Rule Engineering Talent:Vendors struggle to recruit software engineers with depth in Quebec payroll logic and Alberta corporate tax depreciation schedules, creating product-development bottlenecks.
- Legacy ERP Integration Friction:Mid-market manufacturers running on-premise systems from the 2000s face costly middleware requirements to synchronize inventory and cost-accounting data with modern cloud platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Accounting Software Market |
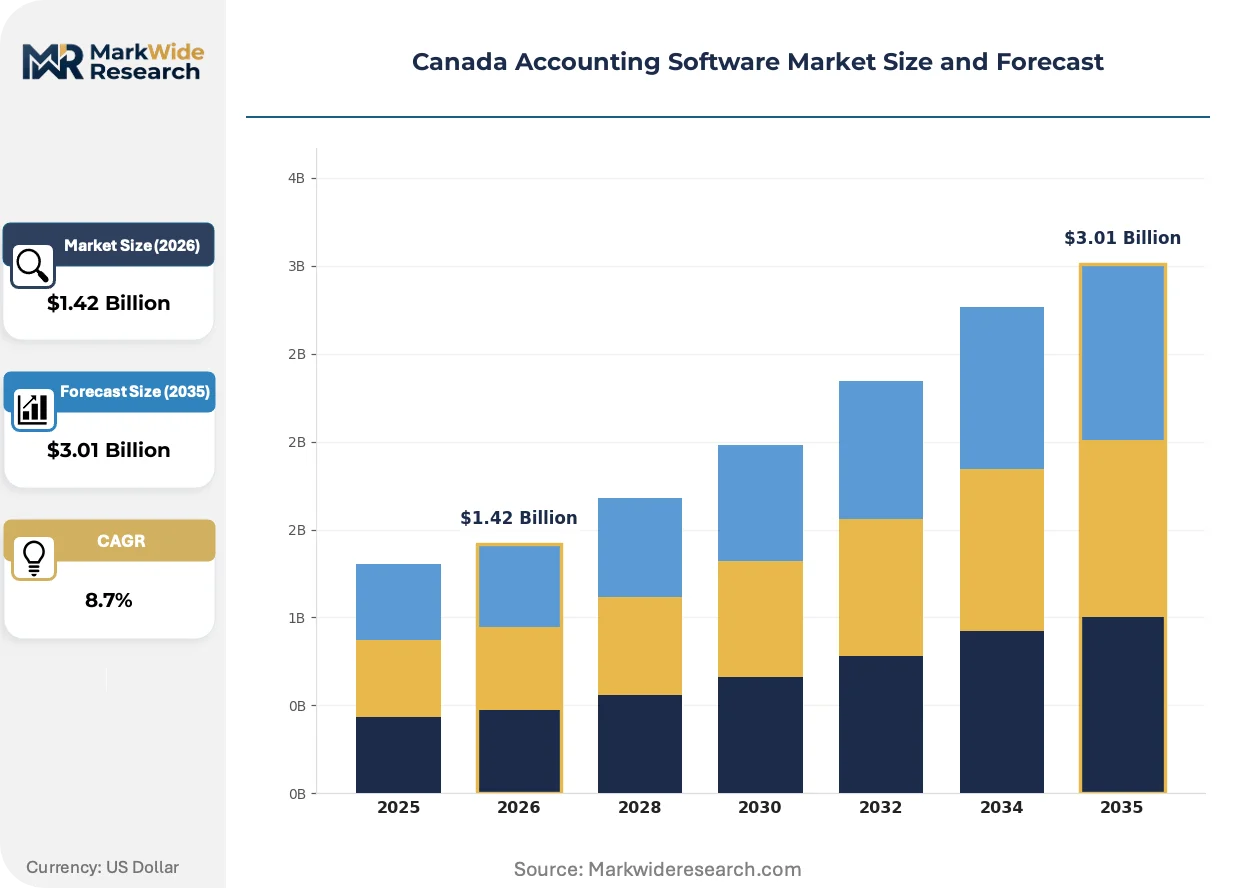
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile Target Audience: Small Businesses, Enterprises, Freelancers, Nonprofits Functionality: Bookkeeping, Invoicing, Payroll, Tax Management Deployment Model: Single-Tenancy, Multi-Tenancy, SaaS, Desktop |
| Companies Covered | FreshBooks, Sage Intacct, QuickBooks, Deskera, Wave Accounting, Xero, Zoho Books, Tipalti, Sage 50cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Accounting Software Market Trends and Innovations
Canadian accounting software is absorbing machine-learning capabilities that automate anomaly detection and predictive cash-flow modeling, compressing the value proposition of traditional bookkeeper-intermediated services. Three forces are actively restructuring competitive positioning and buyer expectations.
Embedded artificial intelligence is absorbing routine reconciliation and categorization tasks that previously required human judgment. Mid-market finance teams in Toronto and Vancouver are deploying these tools to accelerate month-end close timelines from weeks to days. The technology is absorbing hourly work from staff accountants and redirecting talent toward strategic analysis and variance investigation.
Health Canada's evolving guidance on financial software governance for regulated industries is elevating documentation and audit-trail requirements. Enterprise buyers in pharmaceuticals and medical devices must now demonstrate systematic controls over financial data integrity and access logging. Vendors with pre-certified compliance frameworks are capturing disproportionate share of RFP processes in these verticals.
Subscription fatigue among Canadian small-business owners is compressing willingness to maintain separate tools for invoicing, expense management, and payroll. Buyers are consolidating around platforms that unify these functions, displacing point solutions. This consolidation pattern is most visible in British Columbia's technology sector, where founder-operated firms prioritize administrative time reduction over feature depth.
Canada Accounting Software Market Segmentation
Canadian accounting software buyers exhibit sharply divergent technical requirements based on organizational scale, regulatory exposure, and workforce mobility patterns. Understanding these fault lines enables vendors to align product architecture with specific compliance burdens and operational workflows rather than pursuing undifferentiated feature breadth.
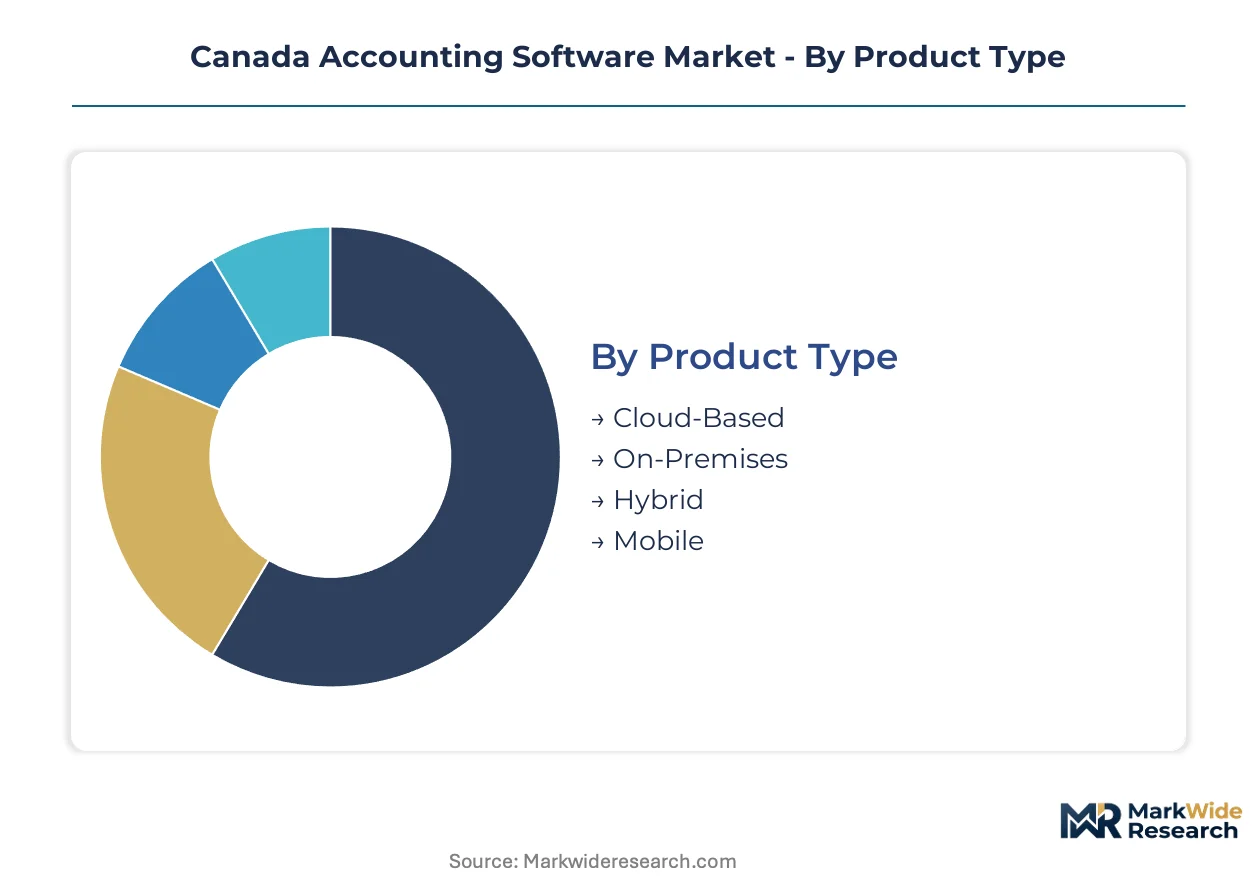
Product Type:
Deployment preference correlates directly with IT staff availability and data sovereignty risk tolerance across Canadian provinces.
- Cloud-Based:Browser-accessible platforms with automatic security patching and remote collaboration features dominate subscriber growth. Ontario professional services firms and British Columbia technology startups prioritize these solutions to support distributed teams while meeting CRA electronic-filing mandates without on-premise infrastructure.
- On-Premises:Installed software running on local servers persists among Quebec manufacturers and Alberta resource-sector enterprises with legacy ERP dependencies. These buyers accept higher capital expenditure to maintain direct control over sensitive financial data amid Health Canada data residency expectations.
- Hybrid:Mixed deployments synchronize core ledgers on-premise with cloud-based reporting layers. Mid-market manufacturers with cross-provincial operations use this architecture to consolidate multi-entity financials without exposing proprietary cost-accounting data to external hosting.
- Mobile:Smartphone-optimized applications with receipt capture and expense categorization serve field-based contractors and traveling sales teams. Demand concentrates in metropolitan Vancouver and Toronto where independent professionals require real-time invoice generation between client sites.
Cloud-Based leads volumes today; Mobile is gaining share fastest.
Target Audience:
Revenue concentration and pricing power vary dramatically by buyer sophistication and procurement process formality.
- Small Businesses:Owner-operated firms with 1-50 employees prioritize intuitive interfaces and rapid onboarding over advanced functionality. These buyers drive volume in suburban Ontario and Atlantic Canada where administrative staff time constraints outweigh feature depth requirements.
- Enterprises:Large organizations demand multi-entity consolidation, role-based access controls, and audit-trail documentation for regulatory examinations. Pharmaceutical and medical device manufacturers under Canadian Securities Administrators scrutiny represent the highest-value accounts for certified compliance frameworks.
- Freelancers:Independent contractors require project-based billing with integrated time-tracking and simplified tax preparation. Toronto and Vancouver metropolitan areas host concentrated populations of designers, consultants, and creative professionals driving this segment.
- Nonprofits:Charitable organizations and social enterprises need fund-accounting modules that separate restricted and unrestricted grant revenue. These buyers prioritize donor-reporting capabilities and board-level financial transparency over commercial profitability metrics.
Small Businesses anchor current revenue; Enterprises command the steepest expansion trajectory.
Functionality:
Module selection reflects the regulatory complexity and transaction velocity of specific operational contexts.
- Bookkeeping:Core general ledger, chart-of-accounts management, and bank-feed reconciliation form the foundational layer. Every Canadian firm requires this capability, though automation sophistication separates premium platforms from commodity tools.
- Invoicing:Client billing workflows with payment processing integration and automated reminders reduce days-sales-outstanding for service-based businesses. Freelancers and professional services firms in urban centers prioritize branded invoice templates and client portal access.
- Payroll:Compensation calculation with provincial remittance compliance carries concentrated margin pools due to Quebec's distinct schedules and Alberta's unique requirements. Vendors maintaining accurate parallel codebases capture premium pricing for this complexity.
- Tax Management:CRA electronic-filing preparation, sales tax calculation across provincial boundaries, and audit documentation assembly serve compliance-intensive buyers. Manufacturing and healthcare enterprises facing regulatory scrutiny invest most heavily here.
Bookkeeping maintains universal penetration; Tax Management shows the strongest pricing power growth.
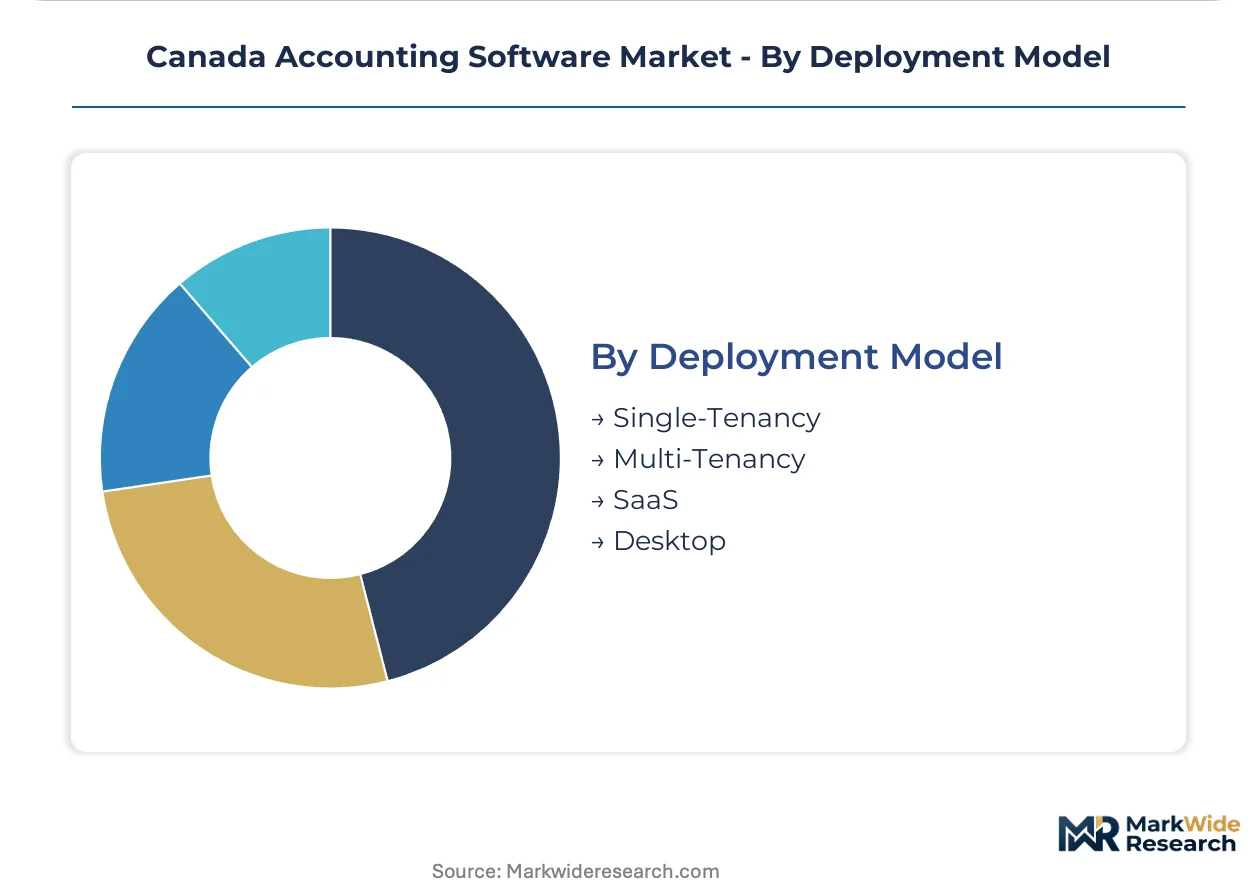
Deployment Model:
Technical architecture decisions determine scalability economics and vendor operational overhead.
- Single-Tenancy:Dedicated infrastructure for individual clients satisfies stringent data isolation requirements. Regulated industries and privacy-conscious Alberta energy firms prefer this model despite higher per-subscriber costs.
- Multi-Tenancy:Shared resource pools with logical separation enable vendor efficiency and lower pricing for price-sensitive small-business segments. This architecture supports the rapid scaling required by Ontario's dense startup ecosystem.
- SaaS:Subscription-based delivery with automatic updates and usage-based pricing dominates new customer acquisition. The model aligns vendor incentives with ongoing customer success rather than perpetual license maintenance.
- Desktop:Perpetually licensed software installed on local machines persists among rural accountants and legacy-dependent enterprises resisting cloud migration. This model captures minimal new subscriber growth but retains stable maintenance revenue.
Multi-Tenancy carries the heaviest volume load; Single-Tenancy is climbing fastest among compliance-intensive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finance technology talent concentrates in Toronto and Vancouver, anchoring Canada's accounting software development and enterprise adoption patterns. These metropolitan clusters generate specialized demand for multi-entity consolidation and automated compliance workflows.
Ontario
Professional services firms and technology startups drive cloud-native platform adoption across the Greater Toronto Area. The Canada Revenue Agency's mandatory digital reporting timeline compresses procurement cycles for CRA-compliant electronic-filing solutions. Kitchener-Waterloo's fintech corridor hosts emerging vendors developing AI-assisted audit preparation tools for mid-market manufacturers.
Quebec
Distinct provincial remittance schedules and French-language interface requirements create specialized demand for localized payroll automation. The Autorité des marchés financiers oversees financial software governance standards that elevate documentation requirements for Montreal-based enterprises. Quebec City's manufacturing base sustains demand for hybrid deployment models that synchronize on-premise legacy systems with cloud reporting layers.
British Columbia
Technology sector density in Vancouver generates sophisticated requirements for project-based billing and real-time bank-feed reconciliation through open banking APIs. Health Canada's data residency guidelines for sensitive financial information influence vendor selection among pharmaceutical enterprises in Burnaby and Richmond. The province's freelancer economy density drives adoption of mobile-optimized expense capture and client-portal functionality.
Alberta
Resource-sector enterprises and energy services firms prioritize data sovereignty controls amid Health Canada privacy expectations for sensitive operational information. The province's unique corporate tax depreciation schedules and filing requirements sustain demand for specialized compliance automation. Calgary's mid-market manufacturers with cross-provincial operations invest in multi-entity consolidation engines to eliminate spreadsheet-dependent close processes.
Atlantic Canada
Nova Scotia and New Brunswick small-business segments exhibit lower cloud-accounting penetration relative to Ontario benchmarks, creating whitespace for localized channel partnerships. Provincial economic development programs support technology adoption among owner-operated firms with constrained administrative staff. Halifax's emerging professional services cluster generates nascent demand for automated invoicing and payment processing integration.
Canada Accounting Software Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light platform developers across deployment models and customer segments. The Canadian market exhibits tiered concentration with dominant incumbents anchoring small-business volumes while specialized vendors capture mid-market complexity premiums. Three strategic archetypes define competitive positioning: brand-recognized mass-market platforms, multi-entity consolidation specialists, and freelancer-focused simplified workflows. M&A activity targets provincial tax-rule engineering capabilities, while strategic partnerships with Canadian data center operators address residency compliance requirements.
Within the brand-recognized tier, QuickBooks and FreshBooks exemplify divergent approaches to customer acquisition across suburban and metropolitan postal codes. Sage Intacct occupies a position representing multi-entity consolidation specialization for cross-provincial manufacturers. These three anchors demonstrate how vendor origin—American platform economics, Canadian freelancer focus, and British enterprise heritage—shapes product architecture and channel strategy within the same regulatory environment.
| Leading Market Players |
|---|
| FreshBooks |
| Sage Intacct |
| QuickBooks |
| Deskera |
| Wave Accounting |
| Xero |
| Zoho Books |
| Tipalti |
| Sage 50cloud |
| Others |
Pricing and Supply Chain Analysis
Health Canada's data residency guidelines for sensitive financial information gate both qualified supply and premium-tier pricing access, as vendors lacking certified Canadian data center infrastructure cannot serve enterprise buyers in pharmaceuticals and medical devices while foreign platforms absorb compliance overhead costs into elevated subscription tiers.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription-based platforms with unified payroll, invoicing, and tax modules from point solutions requiring separate procurement. Pricing stratifies across premium, standard, and economy tiers based on provincial tax-rule automation depth and CRA electronic-filing certification status. Cost compression in the mid-market tier is intensifying because embedded finance features in vertical SaaS platforms absorb core accounting functions. Small businesses in Atlantic Canada exhibit highest price sensitivity, while pharmaceutical enterprises under Canadian Securities Administrators scrutiny accept premium pricing for audit-trail documentation.
Supply Chain Analysis
Certification and qualification gating through PIPEDA compliance and Health Canada data center standards concentrates qualified vendor supply among platforms with Canadian infrastructure investments. Software engineering talent for Quebec payroll logic and Alberta corporate tax schedules draws from Toronto, Vancouver, and Montreal metropolitan clusters. Cloud hosting dependencies rest on hyperscaler capacity in Canadian availability zones. Single-source vulnerability exists in provincial tax-rule engineering expertise. Distribution runs through channel partnerships with accounting firms and CPA networks across suburban and rural postal codes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, as mid-market manufacturers shift demand toward premium specifications with multi-entity consolidation and AI-assisted audit preparation capabilities.
For Market Incumbents: Extend platform stickiness through deeper integration with open banking APIs and automated CRA validation workflows. Consolidate position by acquiring specialized provincial tax-rule engineering teams to defend against vertical SaaS substitution. Channel control through CPA firm partnerships remains a critical lever for rural and suburban penetration. For New Entrants and Emerging Players: The Canada Revenue Agency's mandatory digital reporting timeline in Canada opens a window for cloud-native platforms with pre-certified compliance frameworks. Atlantic Canada small-business segments and Indigenous enterprise trust-accounting requirements represent the most penetrable white spaces. A localized channel partnership strategy with province-specific onboarding workflows offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier cloud-accounting specialists because provincial tax-rule fragmentation prevents pure platform consolidation. Five-to-ten-year viability hinges on acquiring vendors with Quebec payroll automation and Alberta corporate filing accuracy. Watch for inflection in mid-market manufacturer RFP volume for multi-entity consolidation engines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies payroll, invoicing, and tax modules to reduce subscription fatigue among Canadian small-business owners. |
| Acquisition of Specialist Firm | Captures Quebec payroll logic expertise that incumbent platforms struggle to replicate internally. |
| Strategic Partnership | Aligns with Canadian data center operators to satisfy Health Canada residency expectations for enterprise buyers. |
| Product Launch | Introduces AI-assisted audit preparation tools trained on CRA electronic-filing validation patterns. |
| Geographic Expansion | Establishes localized channel presence in Nova Scotia and New Brunswick to capture underpenetrated small-business demand. |
Research Methodology
Direct dialogue with CFOs at mid-market manufacturers, platform engineers at cloud-accounting vendors, channel partners at CPA firms, and integration specialists at open banking API providers combined with secondary validation from Canada Revenue Agency electronic-filing disclosures, Canadian Securities Administrators guidance documents, hyperscaler Canadian region capex announcements, and provincial economic development program databases. Bottom-up subscriber estimates and top-down market sizing triangulate volume and value outputs.
Market projections across the analysis window derive from segmentation modeling across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs emerge from historical trajectory analysis adjusted for regulatory catalyst velocity and technology substitution rates. Forecast inputs incorporate open banking API adoption curves and CRA digital mandate compliance timelines.
Revisions become necessary when Health Canada data residency guidance tightens, provincial tax-rule heterogeneity accelerates, or embedded finance substitution exceeds modeled rates. Deviation in mid-market manufacturer cloud migration velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Asia-Pacific Accounting & Budgeting Software Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
UAE Forensic Accounting Market
Accounting and Taxation Services
Global Artificial Intelligence for Accounting Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Accounting Services Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
France Forensic Accounting Market