
 Asia-Pacific Immersive Entertainment Market | 2026-2036
Asia-Pacific Immersive Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Immersive Entertainment Market Insights
South Korea's metaverse infrastructure build-out is reconfiguring content delivery pipelines across the Asia-Pacific immersive entertainment landscape. Samsung Electronics leverages its display semiconductor vertical to dominate headset component supply for regional OEMs. HTC Corporation anchors its position through specialized location-based VR arcade systems deployed across Japanese entertainment districts. Sony Group Corporation competes by controlling premium cinematic VR content pipelines through its entertainment division synergies.
Asia-Pacific immersive entertainment encompasses digitally rendered sensory environments that merge real-world spatial contexts with computer-generated visual, auditory, and haptic stimuli, typically requiring refresh rates above 90Hz and sub-20ms motion-to-photon latency to prevent user disorientation. These systems serve commercial purposes ranging from consumer leisure to enterprise training simulations and educational visualization. Virtual Reality experiences currently occupy the largest revenue share within experience type segmentation, while Mixed Reality installations represent the fastest-growing category as hardware costs decline and spatial computing capabilities mature. Cloud platform delivery is displacing console-dependent distribution in Southeast Asian markets where capital expenditure constraints limit hardware penetration among price-sensitive consumers.
China's SAMR enforces digital content licensing and data localization requirements that foreign operators must satisfy before commercial deployment. South Korea's metaverse ethics standards and Japan's JIS certification frameworks for head-mounted displays create multi-layered compliance obligations for cross-border service providers. Australia's TGA and Singapore's IMDA are developing complementary guidelines for health-related immersive applications and broadcast content classification. Stakeholders must monitor regulatory divergence between national frameworks when designing unified content architectures for multi-country deployment strategies.
Market Dynamics
Cloud-based delivery architectures are compressing hardware dependency cycles across Asia-Pacific immersive entertainment, enabling operators to bypass capital-intensive console ecosystems while SAMR licensing requirements force content localization investments that reshape profit pools for foreign entrants.
Growth Catalysts
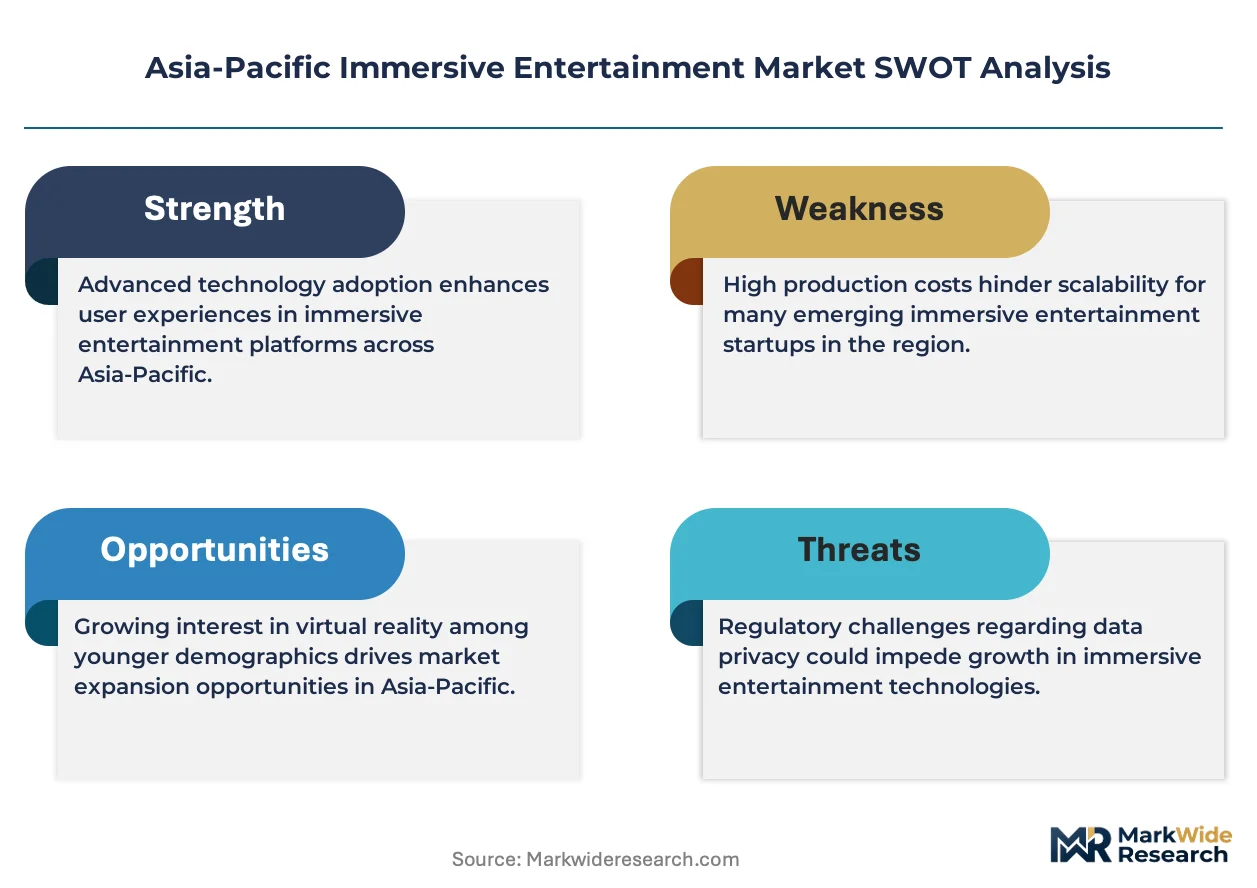
- China's SAMR digital content licensing:Foreign operators must establish local data infrastructure, creating captive demand for domestic cloud service providers and compliance consultancies.
- Location-based entertainment venues:Shopping mall operators in Shanghai, Beijing, and Shenzhen are retrofitting retail footprints with mixed reality installations to capture experiential consumer spending.
- Spatial computing maturation:Sub-20ms motion-to-photon latency thresholds are now achievable at declining hardware cost curves, removing a primary barrier to mass adoption.
Market Restraints
- Display semiconductor supply concentration:Regional OEMs depend heavily on Korean and Taiwanese component fabricators, creating vulnerability to geopolitical trade friction.
- South Korea's metaverse ethics standards:Cross-border content providers face multi-layered compliance audits that extend deployment timelines by 8-14 months.
- Substitution from conventional entertainment:Cinemas and live performance venues in Japan retain consumer loyalty through premium pricing power and established distribution.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Southeast Asian markets exhibit minimal location-based VR infrastructure despite rising disposable income cohorts in Ho Chi Minh City and Jakarta.
- Enterprise training convergence:Industrial safety simulation demand from Korean shipbuilding and Japanese automotive manufacturers creates B2B revenue streams distinct from consumer leisure.
- Australia's TGA health application guidelines:Therapeutic VR for pain management and rehabilitation represents a regulated pathway with reimbursement tailwinds.
Industry Challenges
- Motion sickness mitigation engineering:Refresh rate optimization and predictive head-tracking algorithms require specialized talent pools concentrated in Tokyo, Seoul, and Shenzhen.
- Multi-jurisdiction content certification:Operators deploying across China, Japan, and South Korea must maintain parallel compliance teams due to divergent classification frameworks.
- Legacy arcade infrastructure retrofit costs:Japanese pachinko and Korean PC bang operators face write-downs on depreciated hardware when transitioning to immersive systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Immersive Entertainment Market |
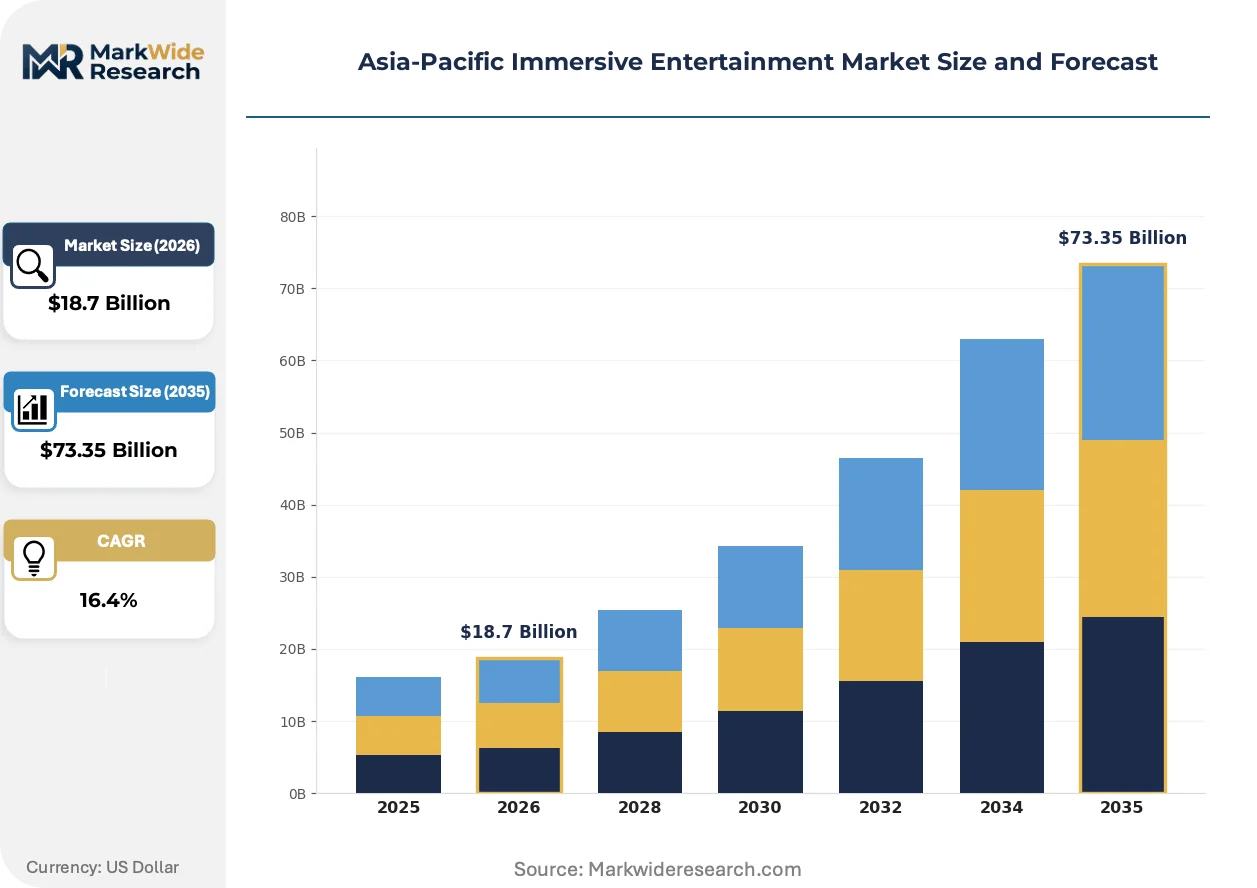
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Experience Type: Virtual Reality, Augmented Reality, Mixed Reality, 360-Degree Video Platform: Mobile, PC, Console, Cloud Content Type: Gaming, Education, Simulation, Social Interaction End User: Individuals, Enterprises, Educational Institutions, Developers |
| Companies Covered | Samsung Electronics, HTC Corporation, Meta Platforms Inc, iQIYI, teamLab, Microsoft Corporation, Apple Inc, Qualcomm Incorporated, Sony Group Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Immersive Entertainment Market Trends and Innovations
Edge computing architectures are redistributing processing loads away from centralized data centers, while regulatory fragmentation between national metaverse frameworks forces operators toward modular content architectures. These shifts are compressing traditional hardware refresh cycles and reconfiguring competitive advantage toward software-layer differentiation.
Light field display technology is digitizing volumetric image reproduction without requiring headset wearables. Japanese museum operators and Chinese retail landlords are piloting walk-through holographic installations that eliminate hygiene concerns and accommodation discomfort associated with shared head-mounted devices. This architecture is digitizing the boundary between physical space and rendered content, collapsing the distinction between spectator and participant.
South Korea's metaverse ethics standards and Japan's JIS head-mounted display certification are creating compliance moats that favor incumbent operators with established legal teams. Foreign entrants must navigate sequential approval processes that vary in stringency between Seoul's content moderation requirements and Tokyo's hardware safety testing. Location-based entertainment chains with cross-border ambitions are consolidating compliance functions in Singapore to manage this regulatory divergence.
Consumption patterns in China's tier-one cities are rotating from hardware ownership toward subscription-based venue access. Young professionals in Shanghai and Beijing prefer time-billed immersive experiences in commercial installations rather than purchasing home VR systems. Mall operators are responding by converting vacant department store footprints into ticketed mixed reality attractions, capturing foot traffic that e-commerce has displaced from traditional retail.
Asia-Pacific Immersive Entertainment Market Segmentation
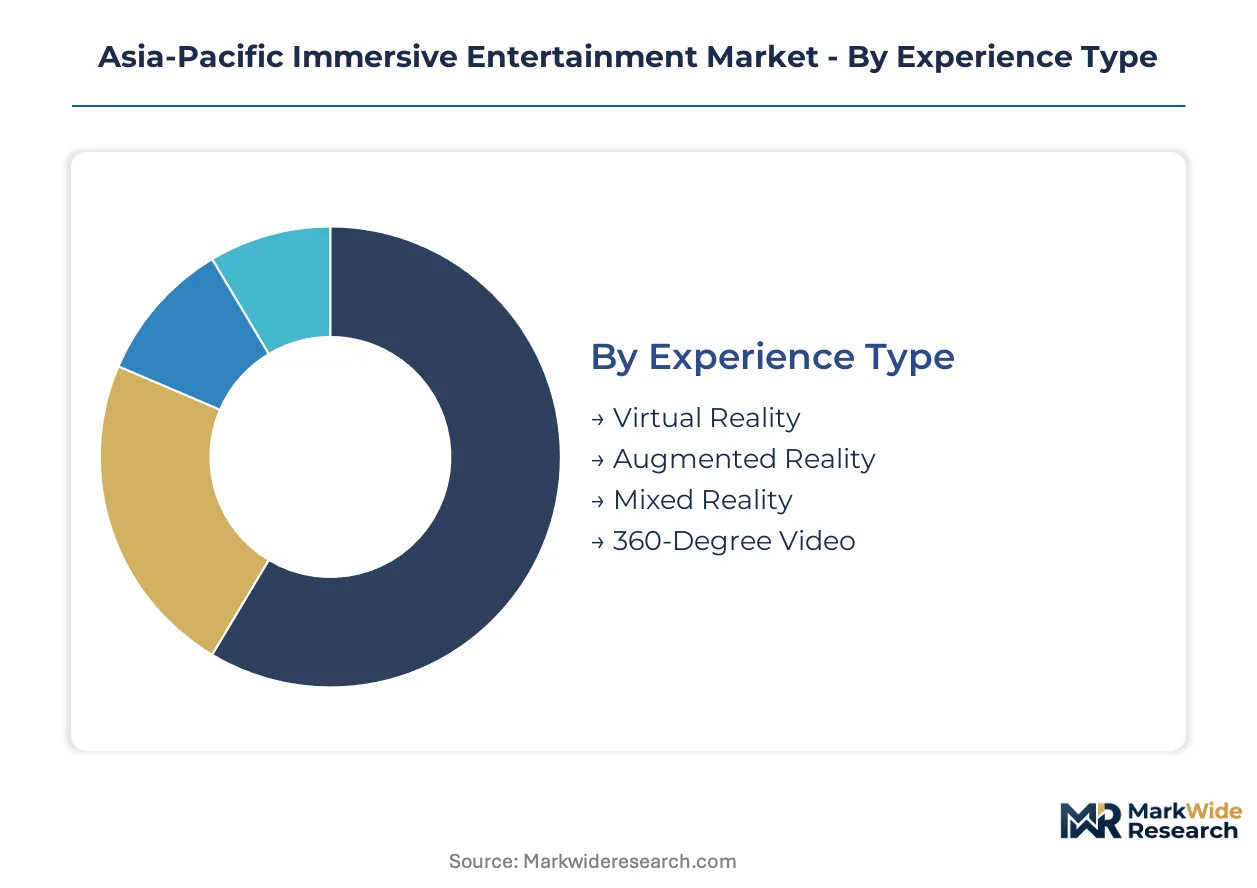
Segmentation across the Asia-Pacific immersive entertainment market reveals how hardware capabilities, content delivery architectures, and end-use applications create distinct competitive arenas. Each dimension carries unique regulatory footprints and capital requirements that reshape operator strategies across China, Japan, and South Korea.
Experience Type:
Cost tier and hardware dependency differentiate how sensory environments reach consumers across the region.
- Virtual Reality:Fully enclosed headset-based environments with refresh rates above 90Hz and sub-20ms motion-to-photon latency. Demand concentrates in China's tier-one cities where shopping mall installations attract experiential consumer spending from young professionals avoiding home hardware purchases.
- Mixed Reality:Spatial computing systems merging physical and digital environments through passthrough cameras and depth sensors. South Korea's metaverse platform build-out accelerates deployment across Seoul's entertainment districts as hardware costs decline.
- Augmented Reality:Overlay displays projecting digital content onto physical environments through smartphone cameras or lightweight glasses.
- 360-Degree Video:Spherical video capture enabling passive immersive viewing without interactive navigation.
Virtual Reality commands the established base. The steepest expansion runs through Mixed Reality.
Platform:
Application context and infrastructure maturity determine how content reaches end users across national markets.
- Cloud:Streaming architectures processing rendering workloads at edge nodes to deliver high-fidelity experiences to low-specification client devices. Southeast Asian markets in Vietnam and Indonesia adopt this pathway to bypass capital-intensive console ecosystems where disposable income constraints limit hardware penetration.
- Console:Dedicated gaming hardware with standardized performance specifications enabling premium experiences. Japan's established console culture sustains demand despite cloud migration pressures elsewhere in the region.
- Mobile:Smartphone-dependent delivery leveraging existing device penetration across mass-market demographics.
- PC:High-performance computing platforms serving enthusiast segments and enterprise training applications.
Console platforms anchor revenue in Japan. Cloud delivery gains share fastest across Southeast Asian underpenetrated markets.
Content Type:
Volume concentration and margin structure vary sharply between consumer leisure and enterprise applications.
- Gaming:Interactive entertainment experiences dominating consumer spending across location-based venues and home installations. China's SAMR licensing requirements force localization investments that reshape profit pools for foreign operators entering Shanghai and Beijing markets.
- Simulation:Task-replicating environments for skill acquisition and procedure rehearsal. Korean shipbuilding and Japanese automotive manufacturers generate B2B demand for industrial safety training distinct from consumer leisure revenue streams.
- Education:Curriculum-integrated immersive visualization for institutional deployment.
- Social Interaction:Multi-user virtual spaces enabling presence-based communication and shared activities.
Gaming captures the consumer revenue base. Simulation demonstrates the steepest trajectory as enterprise training budgets expand.
End User:
Customer type and procurement authority create divergent sales cycles and compliance obligations across the region.
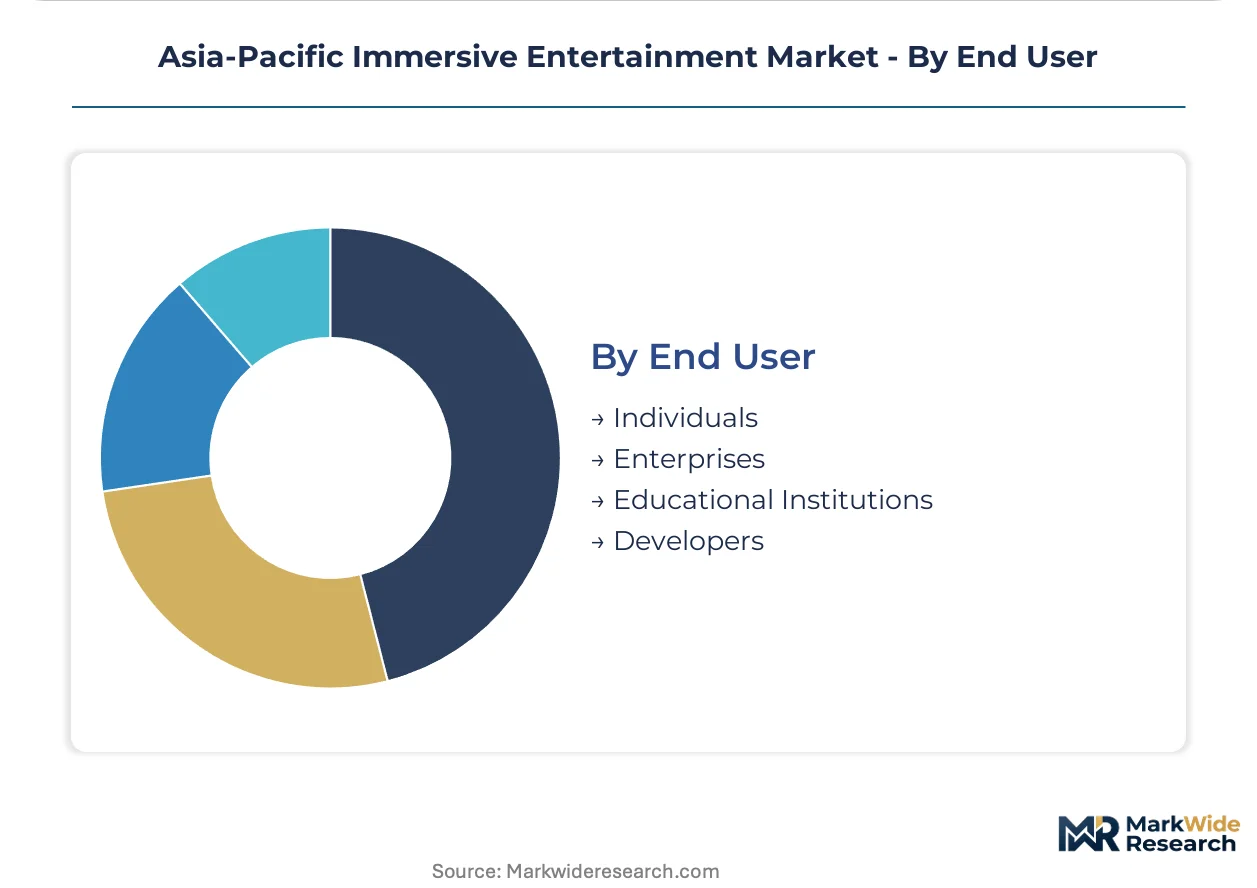
- Enterprises:Organizations deploying immersive systems for training, design visualization, and operational simulation. Australia's TGA health application guidelines open regulated pathways for therapeutic VR in pain management and rehabilitation with reimbursement tailwinds.
- Individuals:Consumers accessing experiences through venue-based ticketing or home hardware ownership. China's tier-one cities show pronounced rotation toward subscription-based mall installations rather than purchase.
- Educational Institutions:Schools and universities integrating immersive content into formal curricula.
- Developers:Content creators and technical studios building applications for downstream distribution.
Individuals represent the volume foundation. Enterprises climb fastest as industrial safety mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication clusters in South Korea and Taiwan concentrate display semiconductor supply for regional headset manufacturers. Japan's precision optics sector and China's software engineering pools complete a geographically distributed value chain. National regulators impose divergent compliance burdens that reshape cross-border deployment economics.
China
Shanghai and Beijing shopping mall operators are converting vacant retail footprints into ticketed mixed reality attractions. SAMR enforces digital content licensing and data localization requirements that foreign operators must satisfy before commercial deployment. Shenzhen's hardware engineering clusters supply sub-20ms motion-to-photon latency components to regional OEMs.
Japan
Tokyo's entertainment districts sustain demand for location-based VR arcade systems through established console culture and premium pricing power. METI and JIS certification frameworks for head-mounted displays create hardware safety testing obligations. Osaka's precision manufacturing base produces optical components for headset fabricators.
South Korea
Seoul's metaverse platform build-out accelerates mixed reality deployment across entertainment districts as hardware costs decline. Metaverse ethics standards impose multi-layered compliance audits that extend deployment timelines by 8-14 months. Busan-Ulsan industrial corridors generate B2B demand for shipbuilding safety simulations.
Australia
Sydney and Melbourne healthcare providers are piloting therapeutic VR applications for pain management and rehabilitation. TGA guidelines for health-related immersive applications create regulated pathways with reimbursement tailwinds. New South Wales and Victoria host the region's primary medical technology evaluation clusters.
Vietnam
Ho Chi Minh City exhibits minimal location-based VR infrastructure despite rising disposable income cohorts. Cloud platform delivery enables operators to bypass capital-intensive console ecosystems where hardware penetration remains limited. Local telecom infrastructure investments are compressing latency for edge-rendered experiences.
Asia-Pacific Immersive Entertainment Market Competitive Landscape
Display technology specialists and content-integrated platform operators split the market along hardware-versus-software fault lines. Samsung Electronics leverages captive semiconductor fabrication to dominate headset component supply, while Sony Group Corporation exploits entertainment division synergies to control premium cinematic VR pipelines. Three archetypes define competitive positioning: vertically integrated component suppliers, specialized location-based system deployers, and cloud-platform aggregators. Capacity expansion in display foundries and strategic content licensing partnerships represent the dominant competitive moves.
Within the component supply tier, Samsung Electronics and Qualcomm Incorporated anchor regional OEM dependency relationships through display semiconductor and mobile processing architectures. HTC Corporation exemplifies the location-based specialization archetype with arcade system deployments. Meta Platforms Inc occupies a position bridging consumer hardware and social platform aggregation. Sony Group Corporation represents the content-integrated model through entertainment division coordination.
| Leading Market Players |
|---|
| Samsung Electronics |
| HTC Corporation |
| Meta Platforms Inc |
| iQIYI |
| teamLab |
| Microsoft Corporation |
| Apple Inc |
| Qualcomm Incorporated |
| Sony Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Korean and Taiwanese display semiconductor fabricators compresses margin flexibility across headset OEM tiers while simultaneously forcing tiered pricing stratification that separates premium latency-optimized systems from standard refresh-rate configurations. SAMR licensing overhead and JIS certification testing costs embed fixed compliance burdens that widen spreads between domestic and foreign operator pricing architectures.
Pricing Analysis
SAMR digital content licensing dictates the pricing tier structure across China's immersive entertainment landscape, forcing foreign operators to absorb localization infrastructure costs that stratify offerings across premium full-compliance, standard partial-localization, and economy domestic-only tiers. Price differentiation hinges on motion-to-photon latency certification grade and after-sales service bundling, with sub-20ms systems commanding substantial premiums. Cost compression in the economy tier is intensifying because cloud delivery architectures displace hardware ownership models. Mall-based venue operators exhibit the highest price sensitivity, while enterprise training buyers in Korean shipbuilding and Japanese automotive sectors demonstrate minimal elasticity.
Supply Chain Analysis
Display panel feedstock flows predominantly from South Korean and Taiwanese fabrication clusters, with Chinese Shenzhen-based engineering pools supplying motion-tracking sensor arrays and Japanese Osaka precision manufacturers producing optical lens assemblies. Raw material dependencies center on gallium nitride substrates, rare-earth phosphors, and high-purity silicon wafers. Single-source vulnerability concentrates in Korean OLED driver IC supply, where geopolitical trade friction threatens component availability. Distribution runs through regional OEM assembly hubs before reaching location-based entertainment venue operators and cloud platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent pools capable of sub-20ms latency engineering and predictive head-tracking algorithm development remain concentrated in Tokyo, Seoul, and Shenzhen, creating acute capability gaps for operators outside these clusters. This scarcity reshapes competitive advantage toward software-layer differentiation rather than hardware scale.
For Market Incumbents: Harden defensive moats by deepening backward integration into display semiconductor supply relationships and accelerating SAMR compliance team consolidation in Singapore to manage multi-jurisdiction certification divergence. Threat substitution from light field holographic installations demands immediate R&D allocation toward passthrough camera spatial computing architectures. Capacity addition in Vietnamese cloud edge nodes offers geographic diversification against Korean supply concentration risk. For New Entrants and Emerging Players: Build out white-space presence in Ho Chi Minh City and Jakarta location-based entertainment infrastructure, where rising disposable income cohorts encounter minimal incumbent VR arcade penetration. Cloud platform delivery enables bypass of capital-intensive console ecosystems in these markets. Partner with local telecom operators compressing latency for edge-rendered experiences as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a hardware commoditization phase that favors content-integrated platform operators with established entertainment division synergies. Long-term viability across the analysis window hinges on software-layer differentiation and regulatory compliance scale rather than component supply dominance. Acquisition target archetypes include specialized location-based system deployers with cross-border venue footprints. Monitor South Korea's metaverse ethics standard enforcement velocity as the critical inflection signal for compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Enables Southeast Asian market entry without hardware ownership barriers in Vietnam and Indonesia. |
| Regulatory Compliance Consolidation | Singapore-based legal teams reduce deployment timeline friction across SAMR, JIS, and metaverse ethics frameworks. |
| Spatial Computing R&D Investment | Passthrough camera architectures defend against light field holographic substitution threats in Japanese museum segments. |
| Enterprise Training Partnership | Korean shipbuilding and Japanese automotive safety mandates open B2B revenue streams distinct from consumer leisure volatility. |
| Edge Computing Infrastructure | Local telecom partnerships compress latency for cloud-rendered experiences in underpenetrated Southeast Asian markets. |
Research Methodology
Initial hypotheses were tested against primary input from location-based entertainment venue operators, headset OEM procurement leads, cloud platform engineers, and SAMR compliance consultants, then refined through secondary validation against SAMR licensing databases, JIS certification registries, Korean metaverse ethics standard filings, and regional trade flow customs records. Bottom-up demand modeling across China's tier-one city mall installations and top-down supply assessment of Korean-Taiwanese display fabrication capacity were triangulated to anchor projections.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across experience type, platform architecture, content category, and end-user procurement authority, with particular weighting on cloud delivery migration rates in Southeast Asian markets and enterprise training budget expansion in Korean-Japanese industrial corridors. CAGRs were derived from installed base growth trajectories and average revenue per venue calculations, incorporating hardware cost decline curves and spatial computing capability maturation timelines as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese cloud service providers or accelerated light field display commercialization would shift outcomes substantially. Cross-checking against TGA therapeutic VR reimbursement approval velocity and South Korean metaverse ethics enforcement case volume is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market