
 Digital Avatar Market | 2026-2036
Digital Avatar Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Avatar Market Analytics
Generative AI diffusion across rendering pipelines is reconfiguring how digital avatars move from concept to deployment. Soul Machines leverages proprietary autonomic animation systems to sustain emotional fidelity in human-machine interfaces. Synthesia anchors enterprise video production through templated synthetic presenter workflows. Inworld AI competes on real-time conversational intelligence embedded into gaming and training environments.
A digital avatar constitutes a computationally rendered humanoid or stylized character representation, typically constructed through polygonal mesh modeling, neural radiance fields, or parametric deformation rigs, and designed to execute visual communication, identity proxy, or interactive agent functions across screen-based or immersive displays. The 3D Avatars and Virtual Reality Avatars product categories capture premium engineering investment as headset penetration deepens and spatial computing platforms mature. Artificial Intelligence and Motion Capture technologies dominate capability differentiation, with machine learning inferencing now displacing manual keyframe labor in lip-sync and gesture generation pipelines.
The EU AI Act, GDPR, and emerging FTC guidance on synthetic media collectively shape disclosure mandates, biometric data handling, and consumer protection frameworks that determine product legality and market access across jurisdictions. China's SAMR and NMPA enforce parallel algorithmic recommendation and deep synthesis provisions that constrain cross-border avatar service architecture. Stakeholders must monitor regulatory divergence between privacy-first European frameworks and innovation-permissive Asian enforcement postures when calibrating platform governance and data residency strategies.
Market Dynamics
Generative AI pipelines are compressing avatar production cycles from months to days, forcing studios to restructure animation teams and licensing models around neural rendering rather than manual rigging labor.
Growth Catalysts
- EU AI Act transparency mandates:Synthetic media disclosure requirements legitimize commercial avatar deployments by establishing clear compliance baselines for enterprise buyers across European markets.
- Motion capture hardware democratization:Inertial suit and markerless camera systems slash entry costs for independent creators, expanding the addressable creator base beyond AAA studios.
- Japan's virtual idol infrastructure:Entertainment conglomerates monetize persistent avatar personalities through merchandise, live events, and fan subscription platforms.
Market Restraints
- GPU compute cost volatility:Real-time neural rendering demands strain cloud infrastructure budgets, particularly for mid-tier service providers without long-term silicon contracts.
- Facial geometry dataset concentration:High-fidelity emotion training data aggregates among three commercial biometric libraries, creating licensing bottlenecks.
- Cross-border data residency friction:China's SAMR algorithmic recommendation rules and GDPR biometric restrictions force redundant infrastructure builds for multi-territory deployments.
Strategic Opportunities
- South Korean gaming integration:Real-time conversational NPCs represent underexploited white space as publishers seek differentiation beyond graphical fidelity.
- Healthcare patient-facing avatars:FDA-cleared therapeutic agents for cognitive behavioral interventions open reimbursement pathways previously closed to synthetic media.
- Neural radiance field + large language model convergence:Unified pipelines enabling photorealistic appearance with contextual dialogue reduce vendor fragmentation.
Industry Challenges
- Character rigging talent scarcity:Traditional animation expertise fails to translate directly to neural deformation workflows, creating retraining burdens.
- Biometric consent architecture complexity:Voice and likeness licensing across deceased estates, living celebrities, and synthetic originals generates legal uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Avatar Market |
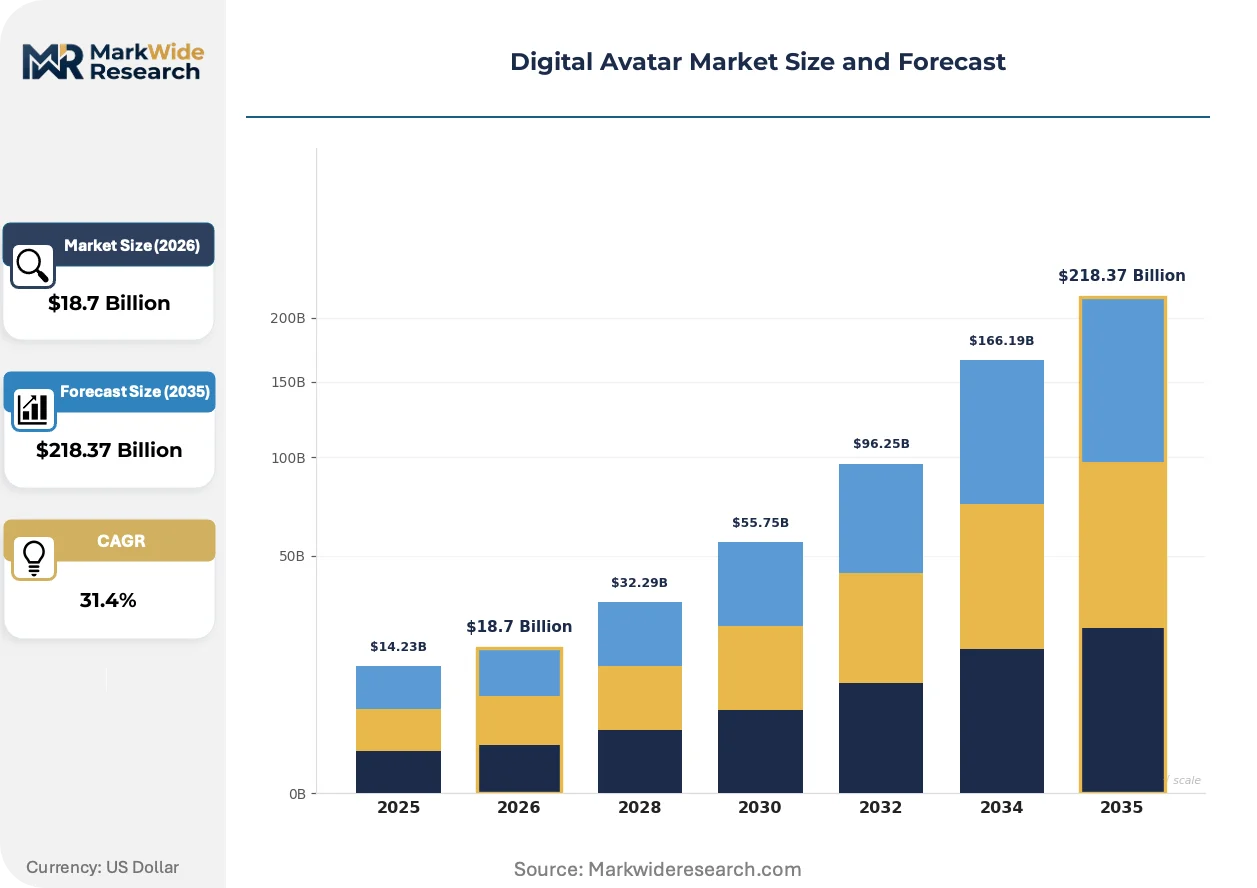
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $218.37 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Avatars, 3D Avatars, Animated Avatars, Virtual Reality Avatars Technology: Artificial Intelligence, Augmented Reality, Motion Capture, Machine Learning Application: Gaming, Social Media, E-Learning, Virtual Conferencing End User: Enterprises, Individual Consumers, Education Institutions, Healthcare Providers |
| Companies Covered | VEED.io, Soul Machines, Synthesia, Character AI, Genies, HeyGen, Vyond, Inworld AI, D-ID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Avatar Market Evolving Landscape
Neural rendering architectures are collapsing the boundary between pre-rendered cinematic quality and real-time interactive performance, forcing pipeline investments that prioritize inference speed over polygon count.
Diffusion-based texture synthesis is hybridizing conventional UV mapping workflows. Character artists at interactive entertainment studios now generate material layers from text prompts before manual refinement. This compression of concept-to-asset timelines enables weekly content drops for live-service platforms previously constrained by month-long production schedules.
The EU AI Act's synthetic media disclosure requirements are reshaping platform liability structures. Social media distributors must implement provenance tagging for algorithmically generated avatars or face penalty exposure. Japanese entertainment conglomerates are responding fastest, embedding cryptographic signatures in virtual idol broadcasts to preempt enforcement friction.
Enterprise procurement of avatar services is fragmenting from annual studio contracts toward per-minute synthetic presenter licensing. Financial services compliance teams in London and Singapore now source templated video generation through self-serve platforms rather than traditional production houses. This unbundling compresses approval cycles from weeks to hours for routine investor communications.
Digital Avatar Market Segmentation
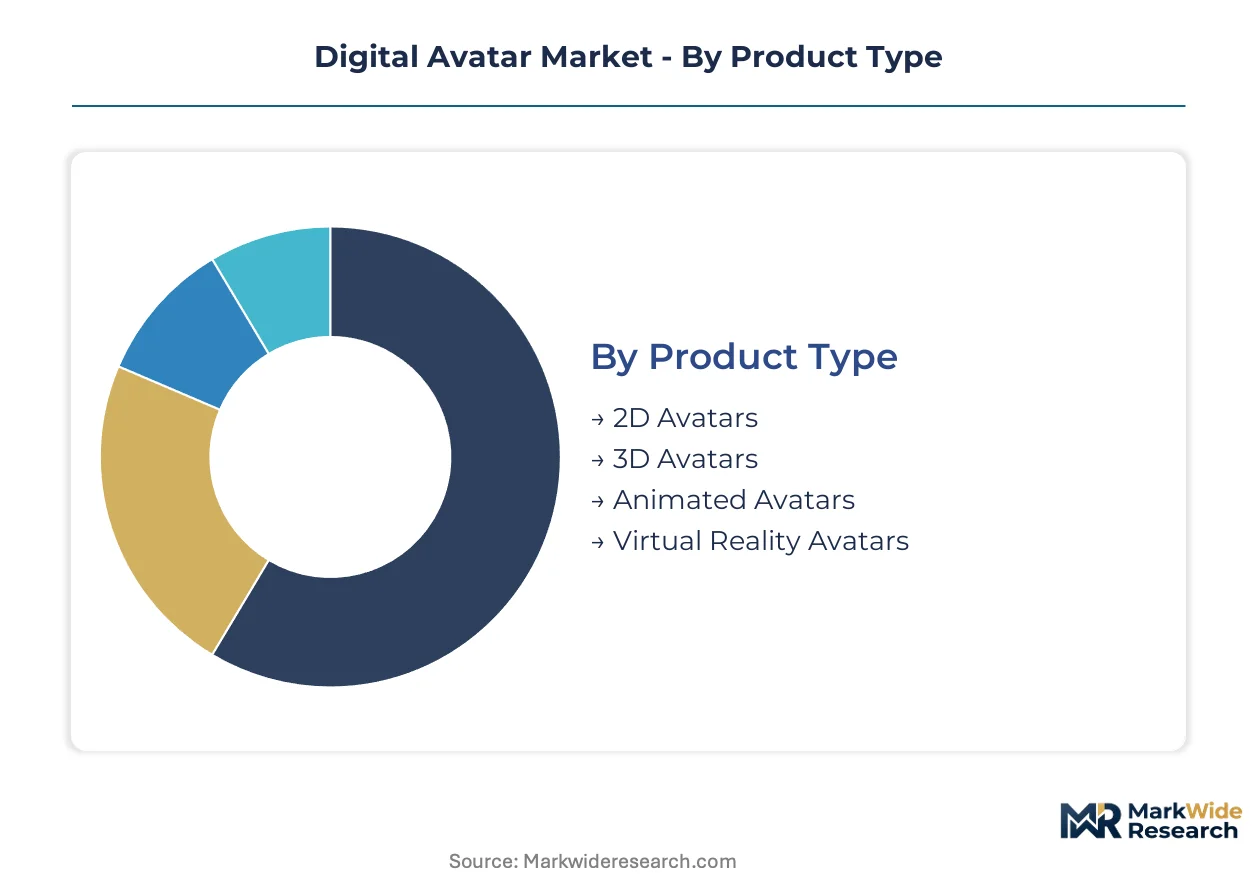
Product architecture and deployment context determine pricing power and technical requirements across avatar services. Rendering fidelity, real-time constraints, and hardware dependencies fragment the addressable market into distinct procurement categories with divergent margin profiles.
Product Type:
Cost tier structures the competitive landscape, with premium engineering investment concentrating where spatial computing adoption accelerates.
- 3D Avatars:Polygonal mesh and neural radiance field constructions enable volumetric presence across screen and immersive displays. Gaming studios in South Korea and Japan's virtual idol producers drive procurement volumes as headset penetration deepens.
- Virtual Reality Avatars:Full-body rigs with six-degrees-of-freedom tracking demand specialized deformation pipelines and low-latency networking. Enterprise training deployments in Germany and healthcare simulation centers in the US sustain premium pricing.
- 2D Avatars:Vector-based or sprite-driven representations serve cost-sensitive social media and messaging applications.
- Animated Avatars:Pre-rendered or procedurally animated characters dominate legacy broadcast and advertising workflows.
3D Avatars holds installed capacity. Virtual Reality Avatars is rotating up the share rankings.
Technology:
Application requirements dictate capability stacking, with inference speed and biometric fidelity determining competitive differentiation.
- Artificial Intelligence:Generative pipelines compress lip-sync, gesture synthesis, and emotional expression from manual keyframe labor to neural inference. EU AI Act disclosure mandates and FDA therapeutic agent pathways in the US expand addressable use cases.
- Motion Capture:Inertial suits, optical marker systems, and markerless camera arrays capture human performance for retargeting. Independent creators in the UK and France leverage democratized hardware to bypass AAA studio infrastructure.
- Machine Learning:Supervised training on facial geometry datasets enables real-time expression mapping.
- Augmented Reality:Spatial anchoring and occlusion handling integrate avatars into physical environments through mobile and wearable displays.
Motion Capture commands legacy deployment share. Artificial Intelligence is gaining share fastest.
Application:
Customer type concentration varies sharply, with enterprise procurement cycles diverging from consumer platform economics.
- Gaming:Real-time conversational NPCs and persistent player representations demand server-side inference and client-side rendering optimization. South Korean publishers integrate Inworld AI and similar engines for differentiation beyond graphical fidelity.
- E-Learning:Synthetic presenter workflows reduce video production costs for compliance training and language instruction. Synthesia's templated enterprise licensing in Singapore and London financial services compresses approval cycles.
- Social Media:Consumer-facing avatar creation tools prioritize ease of use over fidelity.
- Virtual Conferencing:Fatigue mitigation and presence enhancement drive enterprise pilot programs.
Gaming anchors current revenue concentration. E-Learning shows steepest expansion trajectory.
End User:
Volume scale and contract structure differentiate procurement patterns across institutional buyer categories.
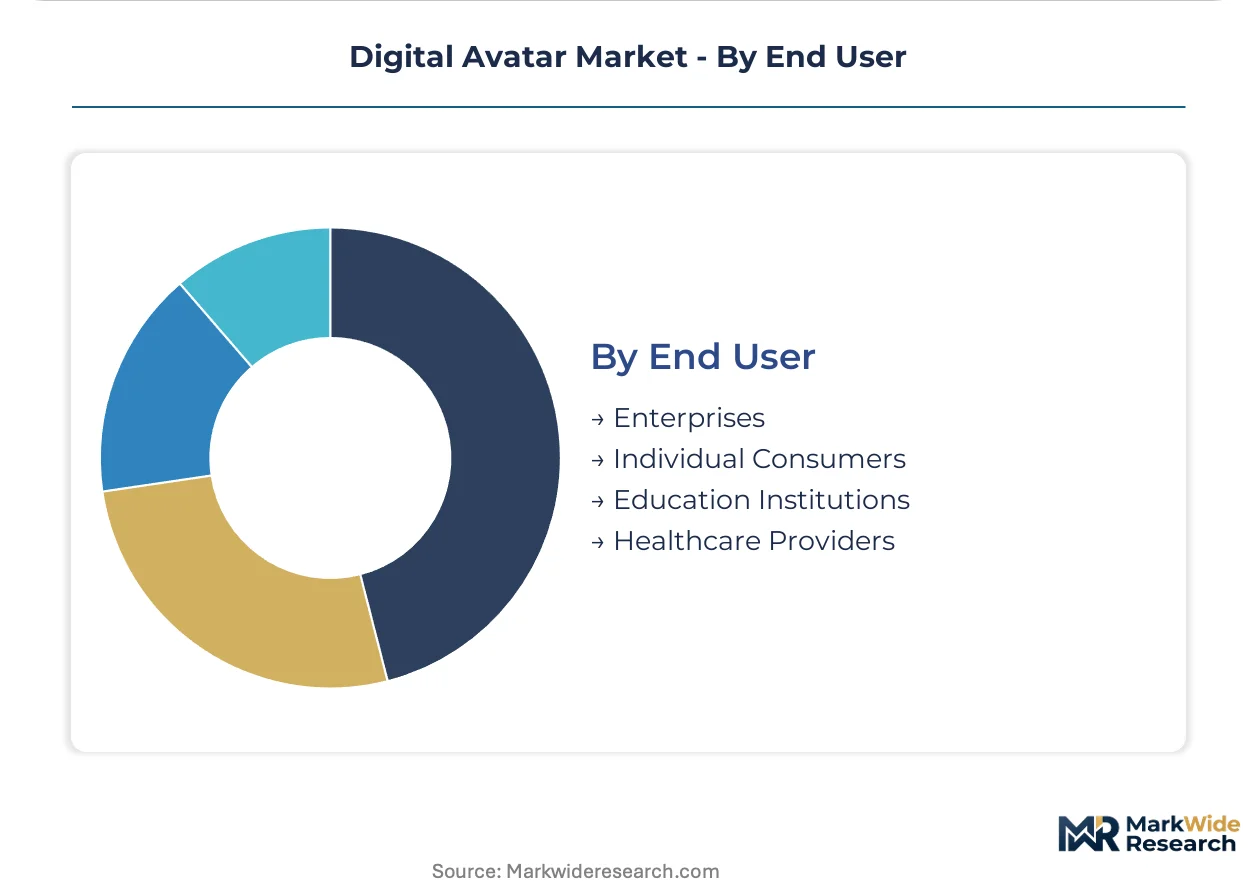
- Enterprises:Annual studio contracts fragment toward per-minute synthetic presenter licensing as self-serve platforms mature. Financial services compliance teams in London and Singapore now source routine investor communications through templated workflows.
- Healthcare Providers:FDA-cleared therapeutic avatars for cognitive behavioral interventions open reimbursement pathways. Patient-facing agents in US mental health systems and Japanese eldercare facilities validate clinical utility.
- Education Institutions:Budget constraints favor lower-fidelity solutions with scalable licensing.
- Individual Consumers:Subscription and freemium models dominate, with platform stickiness tied to social graph integration.
Enterprises maintain contract value leadership. Healthcare Providers is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in London, Singapore, and Seoul dominate contract value for synthetic presenter and conversational agent deployments. Healthcare systems in the US and Japan pilot FDA-cleared and PMDA-reviewed therapeutic avatars for cognitive behavioral interventions. Gaming publishers in South Korea integrate real-time NPC engines to differentiate beyond graphical fidelity.
United States
FDA-cleared therapeutic avatars for mental health interventions open reimbursement pathways in US healthcare systems. The FTC's emerging synthetic media guidance shapes disclosure mandates for commercial avatar deployments. Silicon Valley studios and Boston healthcare simulation centers sustain premium engineering investment for patient-facing agent development.
Japan
Entertainment conglomerates monetize persistent virtual idol personalities through merchandise, live events, and fan subscription platforms. METI standards for synthetic media interoperability constrain cross-platform avatar portability. Tokyo-based production houses embed cryptographic signatures in broadcasts to preempt EU AI Act enforcement friction.
South Korea
Gaming publishers deploy AI-driven avatars for real-time player interaction and conversational NPC differentiation. The country's national broadcasting regulator enforces algorithmic transparency for synthetic media distribution. Seoul Capital Area studios concentrate motion capture infrastructure and neural rendering talent for AAA production pipelines.
Germany
Enterprise training deployments in automotive and industrial sectors sustain demand for six-degrees-of-freedom VR avatar rigs. GDPR biometric restrictions and EU AI Act disclosure mandates force redundant consent architecture for multi-territory deployments. Bavaria healthcare simulation centers validate clinical utility for surgical training applications.
United Kingdom
Independent creators leverage democratized inertial suit and markerless camera systems to bypass traditional studio infrastructure. The Information Commissioner's Office guidance on biometric data handling shapes voice and likeness licensing frameworks. London financial services compliance teams source templated synthetic presenter workflows through self-serve platforms.
Digital Avatar Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement categories. Consolidation pressure concentrates among neural rendering engine providers, while avatar creation tools remain crowded with venture-backed entrants. Three archetypes dominate: autonomic animation specialists, enterprise video production platforms, and real-time conversational intelligence engines. Strategic moves center on technology licensing partnerships and backward integration into proprietary training datasets.
Within the autonomic animation tier, Soul Machines exemplifies human-machine interface fidelity investment. Synthesia anchors enterprise templated video workflows for financial services compliance teams. Inworld AI occupies the real-time conversational NPC position for gaming publisher differentiation. These three represent divergent capability stacking strategies rather than direct feature competition.
| Leading Market Players |
|---|
| VEED.io |
| Soul Machines |
| Synthesia |
| Character AI |
| Genies |
| HeyGen |
| Vyond |
| Inworld AI |
| D-ID |
| Others |
Value Network & Pricing Analysis
Trans-Pacific fiber routes connecting Seoul and Los Angeles carry motion-capture data and neural model weights between South Korean gaming studios and California cloud regions, with bandwidth costs feeding directly into SaaS pricing tiers and reinforcing concentration among avatar platforms with captive infrastructure.
Pricing Analysis
Cost-plus contracts with GPU compute indexation dominate enterprise avatar licensing, tying subscription fees to cloud infrastructure spot rates. Price differentiation rests on biometric fidelity tiers and EU AI Act compliance certification. Cost compression in mid-tier synthetic presenter services is intensifying because hyperscaler GPU allocation constraints squeeze margin. Individual consumers exhibit highest price sensitivity; healthcare systems demonstrate lowest sensitivity due to FDA-cleared therapeutic reimbursement pathways.
Supply Chain Analysis
Contract manufacturing for motion-capture hardware concentrates in Taiwan and South Korea, with Shenzhen assembly plants handling consumer-grade inertial suits. Neural rendering pipelines draw from NVIDIA and AMD silicon, facial geometry datasets, and cloud inference capacity. Single-source vulnerability in GPU foundry supply creates structural risk. Distribution runs through direct SaaS platforms for enterprise buyers and app-store channels for consumer tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural deformation engineering talent pools remain thinner than pipeline demand, compressing execution timelines for studios attempting generative AI transitions and widening the gap between capitalized incumbents and resource-constrained entrants.
For Market Incumbents: Harden proprietary dataset moats through exclusive biometric licensing agreements with talent estates and entertainment conglomerates. Consolidate motion-capture infrastructure in Seoul and Los Angeles to defend against cloud-rendering substitutes. Priority investment targets autonomic animation R&D to outpace real-time conversational AI commoditization. For New Entrants and Emerging Players: Build out FDA-cleared therapeutic avatar verticals in US mental health systems, where reimbursement infrastructure reduces customer acquisition friction versus enterprise SaaS sales. Target South Korean gaming publishers seeking conversational NPC differentiation beyond graphical fidelity. Go-to-market leverage: per-minute pricing transparency against incumbent annual contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified media conglomerates with undermonetized virtual idol IP and captive fan subscription platforms. Five-to-ten-year viability hinges on neural radiance field and large language model convergence reducing vendor fragmentation. Signal to watch: FDA 510(k) clearance velocity for patient-facing cognitive behavioral intervention avatars.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Training Dataset Acquisition | Exclusive biometric libraries from Japanese entertainment conglomerates lock in emotion fidelity differentiation. |
| Neural Rendering Engine Partnership | South Korean gaming publishers integrate real-time inference to bypass traditional animation labor. |
| Regulatory Certification Investment | FDA-cleared therapeutic pathways in US healthcare systems open closed reimbursement channels. |
| Cloud Infrastructure Backward Integration | Captive GPU allocation agreements insulate margin from hyperscaler spot rate volatility. |
| Cross-Border Data Residency Architecture | Redundant EU and China-compliant deployments satisfy GDPR and SAMR algorithmic recommendation rules. |
Research Methodology
A spread of perspectives from gaming studio technical directors, healthcare simulation center administrators, financial services compliance officers, and cloud infrastructure procurement leads converged on the working assumptions. Primary interview data combined with secondary validation against SEC filings of publicly traded avatar platforms, hyperscaler capex disclosures, FDA 510(k) clearance databases, and EU AI Act implementation guidance. Bottom-up segment sizing triangulated against top-down market envelope calculations.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, technology stack, application vertical, and end-user procurement category. CAGRs derived from fitted growth curves applied to disclosed customer counts and average contract values. Industry-specific forecast inputs encompass headset penetration trajectories and regulatory clearance timelines for therapeutic avatars.
Sensitivities concentrate around GPU supply allocation shifts, EU AI Act enforcement stringency evolution, and biometric consent litigation outcomes. Forecasts reflect documented assumptions on technology adoption curves and reimbursement pathway expansion. Quarterly review of FDA therapeutic avatar clearance velocity and hyperscaler infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market