
 AR Gaming Market | 2026-2036
AR Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
AR Gaming Market Analysis
Mobile entertainment is realigning how AR gaming reaches mass audiences, shifting developer priorities from headset-exclusive titles toward smartphone-native experiences. Meta Platforms leverages its Quest ecosystem and social graph to anchor immersive multiplayer formats. Niantic competes through location-based AR infrastructure that sustains persistent real-world game layers. Apple positions its Vision Pro toolkit to dominate premium spatial computing development.
Augmented Reality Gaming fuses computer-generated imagery with real-world environments via camera feeds, spatial mapping, and motion tracking, requiring sub-20ms motion-to-photon latency to prevent user disorientation. Its primary purpose is delivering interactive entertainment that overlays persistent digital objects onto physical spaces. Smartphone-based AR gaming leads volume adoption due to zero hardware friction, while headset-dependent experiences capture the highest margin pools from enthusiast segments. Freemium monetization dominates revenue generation through incremental in-app purchase architectures, though subscription models for exclusive AR content are gaining traction among professional users.
The FCC governs wireless spectrum essential for cloud-rendered AR streaming, while the FTC scrutinizes in-app purchase disclosures and child-targeted advertising mechanics. GDPR compliance obligations in Europe force publishers to localize data processing for location-based AR titles. Stakeholders must monitor evolving biometric privacy statutes that could restrict facial mapping and gaze tracking deployed in next-generation AR gaming interfaces.
Market Dynamics
5G mmWave spectrum allocation by the FCC is compressing motion-to-photon latency below 20ms, enabling cloud-rendered multiplayer AR that smartphone-native developers are exploiting to displace headset-dependent experiences. This infrastructure shift is redrawing competitive boundaries between location-based persistent layers and social-graph anchored immersive formats.
Growth Catalysts
- FCC Spectrum Policy:The FCC's 5G mmWave band allocation creates dedicated low-latency channels for real-time spatial mapping, directly supporting persistent multiplayer AR worlds.
- Smartphone Camera Arrays:Advanced depth-sensing lenses in mass-market handsets are democratizing AR development without hardware friction for consumers.
- San Francisco Developer Density:Venture capital concentration in California's Bay Area accelerates prototype-to-scale pipelines for location-based gaming infrastructure.
Market Restraints
- GDPR Localization Mandates:European data residency requirements force costly infrastructure duplication for location-based titles capturing biometric gaze data.
- Lithium-Ion Supply Bottlenecks:Battery chemistry constraints limit sustained AR processing on untethered headsets, compressing session durations.
- Facial Mapping Statutes:Emerging biometric privacy laws in multiple US states threaten deployment of gaze-tracking interfaces for next-generation gameplay.
Strategic Opportunities
- India Mobile-First Penetration:India's TRAI digital infrastructure investments and 800 million smartphone users represent an underexploited geography for lightweight AR entertainment.
- AI-Generated Asset Pipelines:Convergence of generative diffusion models with real-time 3D engines is automating persistent world content creation at fractional artist-hour costs.
- Subscription AR Content:Professional user segments are migrating toward recurring revenue models for exclusive spatial computing experiences beyond freemium architectures.
Industry Challenges
- Spatial Computing Talent Scarcity:The shortage of engineers proficient in simultaneous localization and mapping (SLAM) algorithms delays product pipelines.
- Multi-Jurisdiction Compliance:Fragmented biometric consent frameworks across US state lines force redundant legal review cycles for gaze-tracking features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR Gaming Market |
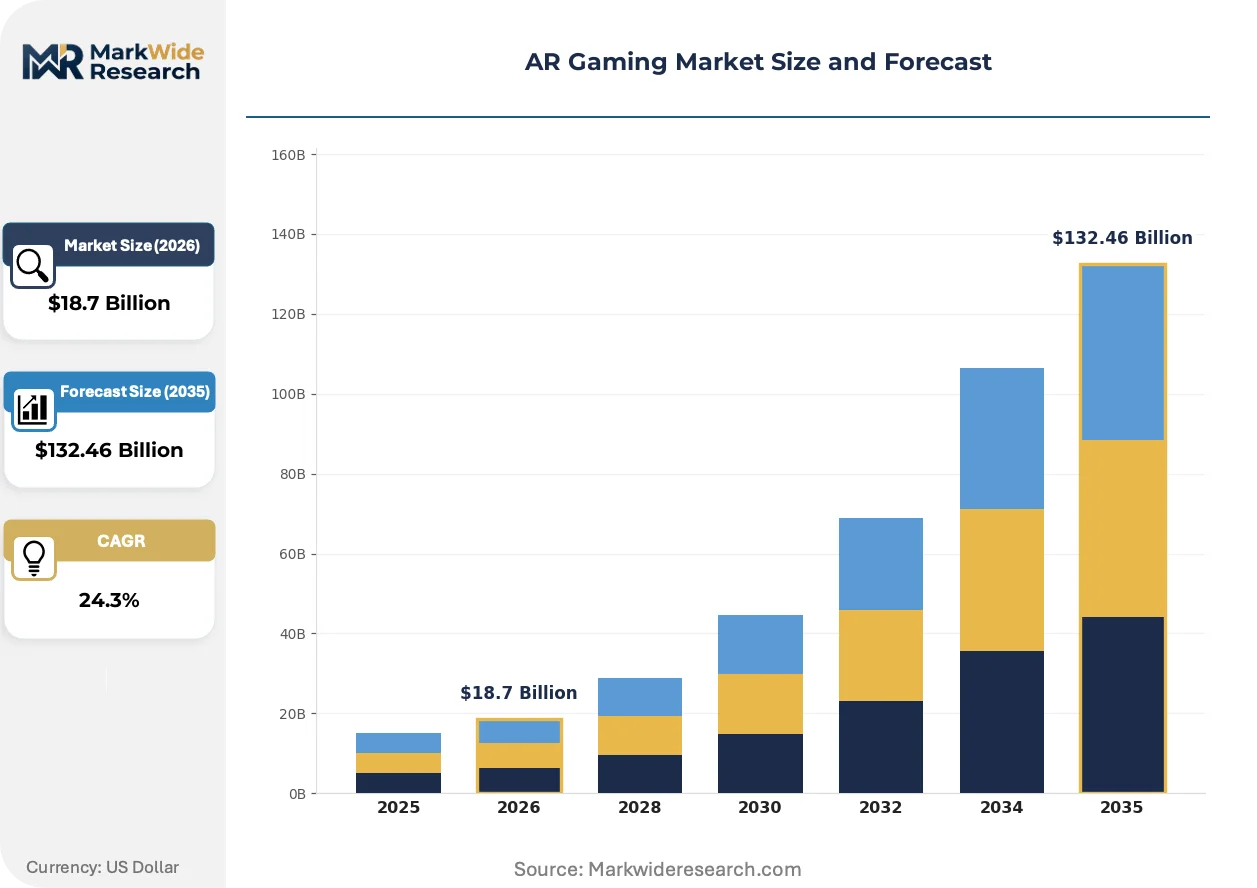
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $132.46 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartphones, Tablets, Headsets, Wearables Content Type: Games, Apps, Experiences, Education End User: Casual Gamers, Professionals, Educators, Developers Monetization Model: In-App Purchases, Subscriptions, Ads, Freemium |
| Companies Covered | Meta Platforms Inc., Apple Inc., Microsoft Corporation, Sony Group Corporation, Google LLC, Niantic Inc., Qualcomm Incorporated, Samsung Electronics Co., Ltd., HTC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR Gaming Market Emerging Trajectories
Real-time neural rendering is compressing asset production cycles while regulatory pressure on biometric data is forcing architectural pivots in interface design. These forces are simultaneously expanding creative possibility and constraining deployment velocity.
Cloud-native neural rendering is automating the generation of photorealistic 3D environments from 2D source imagery, collapsing traditional modeling pipelines from weeks to hours. Mid-tier studios are adopting these tools fastest, enabling competitive parity with well-capitalized incumbents. This compression is democratizing persistent world creation but intensifying content saturation risks.
The EU AI Act's risk classification system is imposing documentation burdens on AR systems deploying emotion recognition or biometric inference. Publishers targeting European audiences must now maintain algorithmic audit trails for gaze-tracking and facial analysis features. This regulatory friction is diverting engineering resources toward compliance tooling and away from core gameplay innovation.
Freemium fatigue among enthusiast segments is driving experimentation with subscription tiers for exclusive spatial content and ad-free persistent worlds. Platform holders are responding with revenue-share incentives for developers adopting recurring billing. This behavioral pivot is most visible in the United States, where venture-backed studios are testing hybrid monetization before geographic expansion.
AR Gaming Market Segmentation
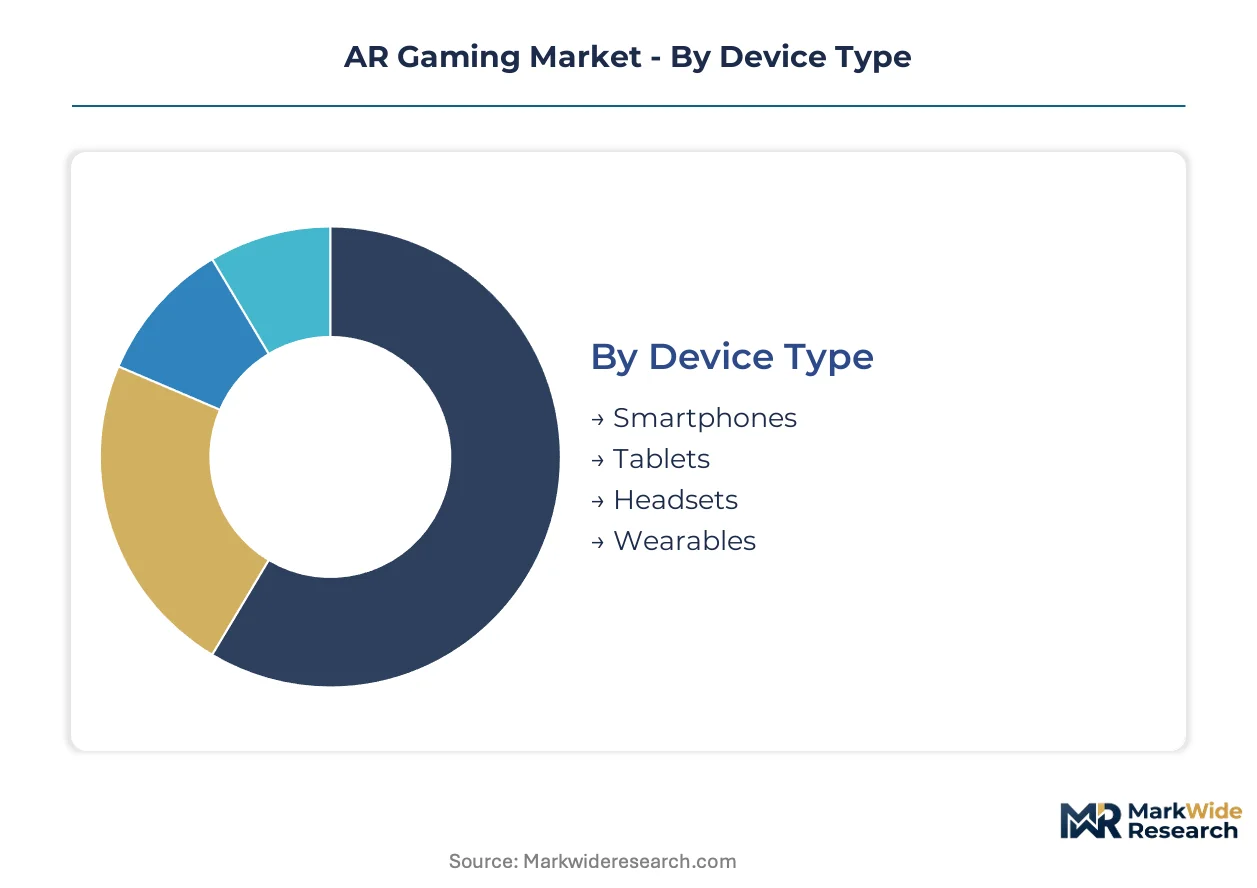
AR gaming segmentation reveals divergent hardware investment thresholds and content consumption patterns across user archetypes. Device fragmentation between smartphone-native and headset-dependent experiences creates distinct margin pools and development priorities for publishers targeting mass versus enthusiast segments.
Device Type:
Customization spans from zero-friction smartphone deployments to bespoke industrial headset configurations, with standardization concentrated in mid-tier tablet formats.
- Smartphones:Camera-array SLAM processing leverages existing consumer hardware without incremental purchase barriers. Demand concentrates in India and Southeast Asia where TRAI infrastructure investments support cloud-rendered lightweight experiences. FCC 5G mmWave allocation enables sub-20ms latency for persistent multiplayer layers on these devices.
- Headsets:Untethered spatial computing platforms deliver the highest fidelity immersion through dedicated depth sensors and eye-tracking arrays. Enthusiast segments in San Francisco and Los Angeles drive revenue concentration, though lithium-ion supply constraints compress session durations.
- Tablets:Mid-format screens balance portability with display real estate for collaborative AR experiences.
- Wearables:Spectacle-form factors and wrist-mounted controllers enable glanceable AR interactions during physical activity.
Leading the category by volume: Smartphones. Expanding most quickly: Headsets.
Content Type:
Application maturity varies from established game mechanics to experimental spatial computing formats, with cost tiers separating mass-market entertainment from enterprise-grade training simulations.
- Games:Location-based persistent worlds anchor consumer engagement through real-world spatial mapping. Niantic's infrastructure sustains multiplayer layers across urban densities in the United States, while GDPR localization mandates force architectural pivots for European deployments.
- Experiences:Immersive narrative and artistic installations exploit headset capabilities for premium pricing. Museums and cultural institutions in Los Angeles commission bespoke spatial storytelling that pushes motion-to-photon latency requirements.
- Apps:Utility-focused overlays for navigation and social interaction dominate smartphone sessions.
- Education:Curriculum-aligned spatial content targets institutional procurement cycles with extended validation timelines.
Dominating by revenue: Games. Steepest expansion trajectory: Experiences.
End User:
Customer sophistication separates freemium-tolerant casual audiences from professional segments demanding subscription-grade reliability and developer ecosystems requiring open toolchains.
- Casual Gamers:Smartphone-native audiences engage with location-based titles during commute and social contexts. Zero hardware friction drives volume adoption across India's 800 million smartphone users, with TRAI digital infrastructure enabling lightweight cloud-rendered experiences.
- Developers:Toolchain access and spatial computing APIs determine platform commitment. San Francisco's venture-backed studios concentrate prototype-to-scale pipelines around Meta's Quest SDK and Apple's Vision Pro frameworks.
- Professionals:Enterprise training and simulation users prioritize session reliability over content breadth.
- Educators:Curriculum integration requirements extend sales cycles but secure multi-year institutional contracts.
Largest addressable base: Casual Gamers. Gaining share fastest: Developers.
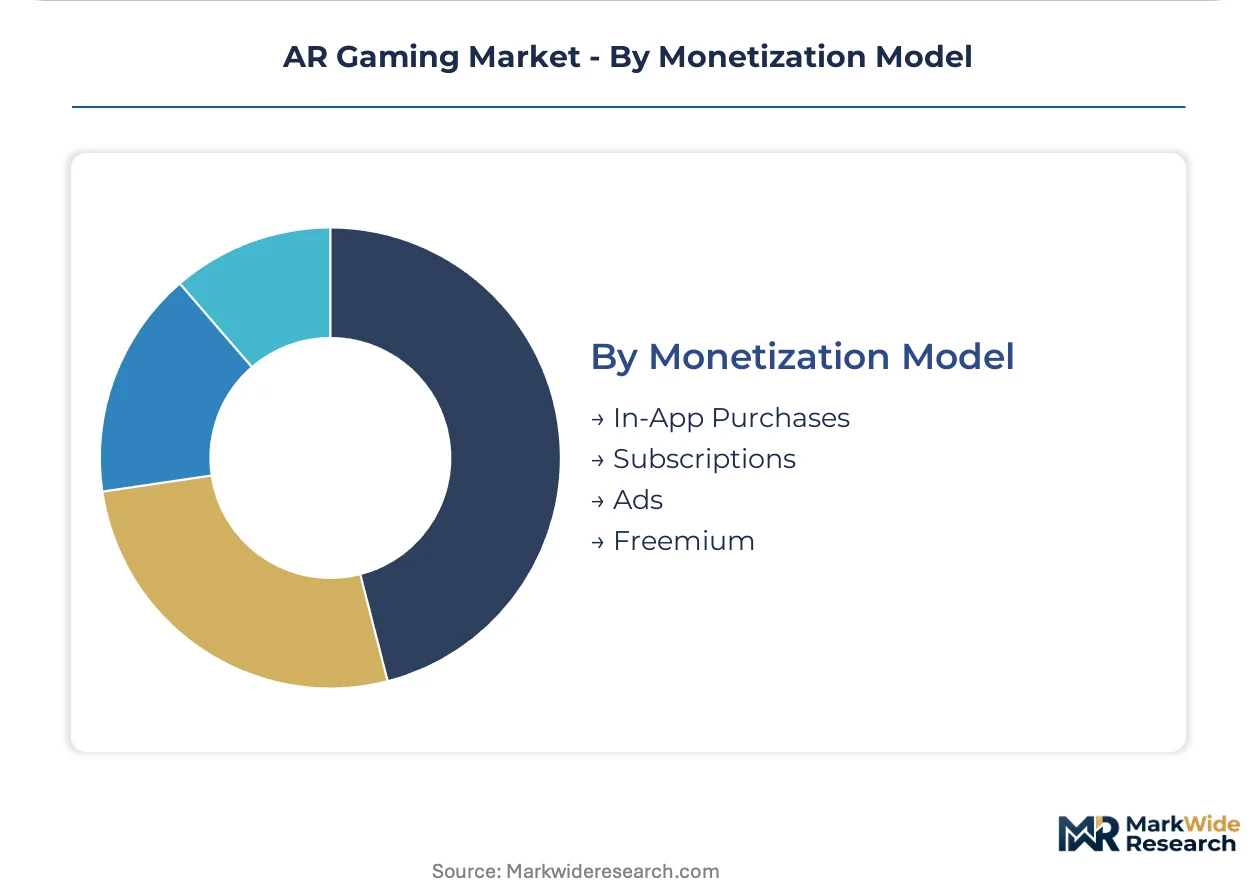
Monetization Model:
Revenue architecture spans impulse-driven microtransactions to predictable recurring billing, with margin profiles inversely correlated with customer acquisition friction.
- Freemium:Base-zero entry with gated progression mechanics dominates smartphone AR titles. In-app purchase disclosure scrutiny by the FTC shapes conversion funnel design for child-accessible content in the United States.
- Subscriptions:Recurring revenue models gain traction among professional users seeking ad-free persistent worlds and exclusive spatial content. Platform holders in San Francisco test revenue-share incentives before geographic expansion.
- In-App Purchases:Cosmetic and functional microtransactions sustain free-to-play economics.
- Ads:Sponsored location overlays and rewarded video integrate with casual session patterns.
Highest volume: Freemium. Climbing the fastest: Subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of AR gaming hardware and infrastructure concentrates in coastal technology corridors, while consumption spreads through smartphone-native populations across emerging digital economies. Developer talent clusters in venture capital-rich metros, creating geographic asymmetry between where AR experiences are built and where they are played.
United States
San Francisco and Los Angeles anchor the highest density of AR gaming venture capital and spatial computing engineering talent. The FCC's 5G mmWave spectrum allocation enables sub-20ms latency for cloud-rendered multiplayer experiences. California's Bay Area hosts prototype-to-scale pipelines for location-based persistent world infrastructure.
China
MIIT's industrial policy accelerates domestic AR chipset and display manufacturing capacity expansion. Shenzhen and Shanghai concentration of hardware OEMs supplies global headset assembly lines. The country's dual carbon goals are pressuring battery chemistry innovation for untethered spatial computing devices.
India
TRAI digital infrastructure investments support cloud-rendered lightweight AR entertainment across 800 million smartphone users. Maharashtra and Karnataka host emerging developer studios targeting mobile-first AR deployment. Mumbai and Bangalore clusters are attracting venture funding for location-based gaming adaptations.
Germany
GDPR localization mandates force architectural pivots for publishers capturing biometric gaze data from European audiences. Bavaria and Berlin-Brandenburg concentration of automotive and industrial AR applications creates technology spillover into consumer gaming. The country's national data protection authority enforces strict consent frameworks for facial mapping features.
Japan
METI funding programs support spatial computing R&D for next-generation entertainment formats. Tokyo and Osaka metropolitan areas sustain console-gaming heritage transitioning toward AR headset experiences. Japanese consumer electronics manufacturers supply critical depth-sensing camera components to global smartphone OEMs.
AR Gaming Market Vendor Landscape
Top-tier vendors anchor platform ecosystems, while mid-tier studios specialize in persistent world content and location-based mechanics. The competitive structure stratifies between hardware-integrated platform holders and software-native developers dependent on third-party distribution. Three archetypes dominate: social-graph anchored immersive platforms, location-based real-world layer specialists, and premium spatial computing toolkit providers. Dominant competitive moves include strategic partnerships for cloud rendering infrastructure and portfolio diversification into subscription content tiers.
Within the platform-holder tier, Meta Platforms Inc. and Apple Inc. exemplify divergent hardware strategies, while Niantic Inc. occupies a position as the archetypal location-based infrastructure specialist. Meta leverages its Quest ecosystem and accumulated social graph data to anchor multiplayer immersive formats. Apple positions its Vision Pro framework to capture premium spatial computing development workflows. Niantic sustains persistent real-world game layers through proprietary mapping infrastructure deployed across urban densities.
| Leading Market Players |
|---|
| Meta Platforms Inc. |
| Apple Inc. |
| Microsoft Corporation |
| Sony Group Corporation |
| Google LLC |
| Niantic Inc. |
| Qualcomm Incorporated |
| Samsung Electronics Co., Ltd. |
| HTC Corporation |
| Others |
Supply Flow & Price Mechanics
Venture-backed studios in San Francisco and Los Angeles concentrate procurement power for spatial computing hardware, anchoring subscription-tier pricing for premium AR experiences while squeezing margin pools for mid-tier smartphone-native developers competing on freemium economics.
Pricing Analysis
Margin tightening in headset-dependent tiers reflects lithium-ion supply bottlenecks and dedicated depth-sensor component costs. Pricing stratifies across premium spatial computing subscriptions, standard freemium mobile layers, and economy ad-supported smartphone sessions. Cost compression accelerates in mid-tier tablet formats as AI-generated asset pipelines collapse artist-hour requirements. Casual gamers in India exhibit highest price sensitivity, while enterprise training segments absorb premium hardware bundles with minimal elasticity.
Supply Chain Analysis
Spatial computing engineering talent scarcity in Shenzhen and Taipei constrains headset assembly line expansion despite MIIT industrial policy support. Critical inputs draw from Chinese rare-earth magnet suppliers for depth-sensing arrays, South Korean OLED panel manufacturers for microdisplays, and Japanese precision optics houses for waveguide components. Single-source vulnerability concentrates in Qualcomm Snapdragon AR chipsets. Distribution runs through direct-to-developer SDK portals and carrier-bundled smartphone preloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SLAM algorithm engineer scarcity props pricing power for studios commanding persistent world infrastructure, creating supply-constrained entry barriers for mid-tier competitors.
For Market Incumbents: Anticipate regulatory fragmentation across US state biometric consent frameworks by pre-emptively architecting gaze-tracking features for modular compliance. Fortify location-based data infrastructure in California's Bay Area against GDPR-mandated European localization costs. Prioritize vertical integration into cloud rendering capacity to offset FCC spectrum dependency for low-latency multiplayer layers. For New Entrants and Emerging Players: Direct-to-developer toolkit distribution bypasses platform-holder revenue share extraction for studios building on Meta Quest SDK and Apple Vision Pro frameworks. White-space concentration sits in India's TRAI-supported mobile-first AR entertainment across 800 million smartphone users. Target Maharashtra and Karnataka developer clusters with lightweight cloud-rendered experiences before geographic expansion. For Investors and Strategic Acquirers: The window for entry favors mid-tier studios with operationalized AI-generated asset pipelines and proven location-based persistent world mechanics. Long-term viability hinges on subscription revenue migration beyond freemium architectures. Monitor EU AI Act enforcement patterns on emotion recognition documentation burdens as inflection signal for European deployment cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Infrastructure Partnership | FCC 5G mmWave allocation enables sub-20ms latency for persistent multiplayer AR worlds. |
| AI-Generated Asset Pipeline Integration | Generative diffusion models collapse 3D environment production from weeks to hours for mid-tier studios. |
| Subscription Tier Launch | Professional user segments migrate toward recurring billing for exclusive spatial computing experiences. |
| GDPR-Compliant Data Localization | European data residency requirements force architectural pivots for biometric gaze data capture. |
| India Mobile-First Market Entry | TRAI digital infrastructure investments support lightweight AR entertainment across 800 million smartphones. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with spatial computing CTOs, AR studio technical directors, platform SDK product managers, and venture capital partners tracking gaming infrastructure. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level projections. FCC spectrum allocation records, MIIT industrial policy disclosures, and TRAI infrastructure investment reports supplied regulatory context. SEC filings from headset OEMs and hyperscaler capex disclosures informed hardware supply chain modeling.
Data-stream reconciliation across device type, content category, end user archetype, and monetization model dimensions shaped the analytical framework over the projection horizon. CAGRs derived from historical trajectory analysis and technology adoption curve positioning. Industry-specific forecast inputs incorporated 5G mmWave deployment timelines and lithium-ion battery chemistry innovation cycles.
The model holds under stable FCC spectrum policy and continued TRAI infrastructure investment; deviation in EU AI Act enforcement intensity or US state biometric privacy statute proliferation would shift deployment cost assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market