
 Metaverse in Entertainment Market | 2026-2036
Metaverse in Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Metaverse in Entertainment Market Outlook
Asset-light cloud rendering partnerships are reshaping competitive entry in immersive entertainment, allowing studios to bypass capital-intensive server farms. Epic Games leverages its Unreal Engine ecosystem to anchor high-fidelity virtual production pipelines for film and broadcast clients. NVIDIA sustains technology leadership through GPU architectures that power real-time ray tracing in metaverse environments. Roblox competes by controlling a creator-driven platform where user-generated games generate recurring engagement without studio-level production budgets.
The metaverse in entertainment denotes persistent, shared virtual environments where real-time 3D rendering, spatial audio, and networked avatars enable synchronous audience participation across concerts, gaming tournaments, and interactive narratives. These systems rely on sub-20 millisecond latency thresholds and volumetric capture pipelines to deliver presence-based experiences that traditional streaming cannot replicate. Virtual Reality and Social Experiences dominate current platform investment, while Blockchain-enabled ownership layers are capturing expanding margin pools from digital collectibles and ticketing. Gaming Tournaments and Virtual Concerts within the Application dimension show the steepest audience growth curves as brands seek measurable engagement metrics beyond passive viewership.
The Federal Communications Commission shapes infrastructure competition through spectrum allocation rules that determine 5G density for untethered XR streaming. The European Union's AI Act and GDPR impose algorithmic transparency and biometric data constraints on emotion-tracking features deployed in immersive venues. South Korea's Ministry of Science and ICT enforces national metaverse standards that accelerate domestic platform interoperability. Stakeholders must weigh regulatory fragmentation against the technical cost of building compliant architectures for each jurisdiction they enter.
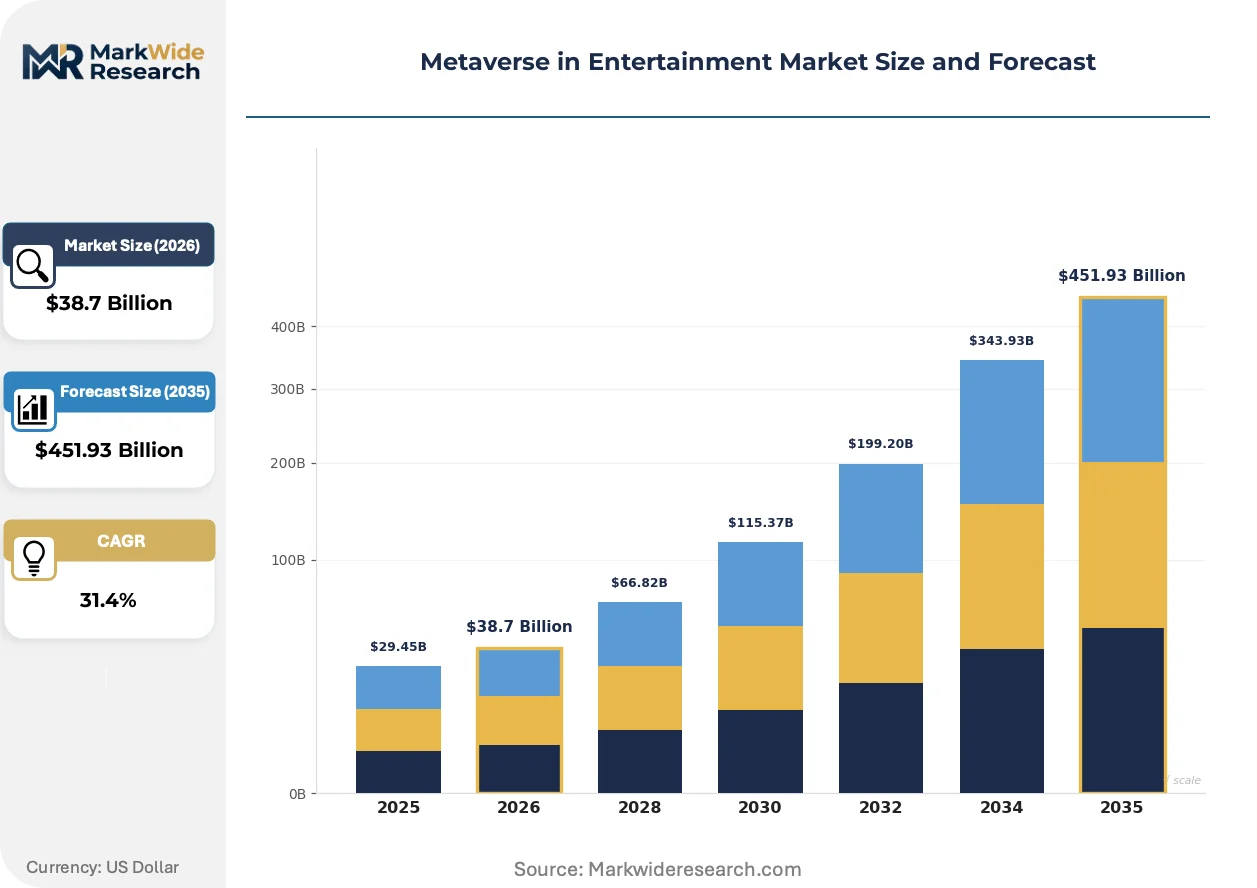
Market Dynamics
Cloud rendering partnerships are compressing capital requirements for immersive content studios, allowing mid-tier producers to access real-time ray-tracing infrastructure previously reserved for major platform holders. This shift redistributes competitive leverage toward IP owners and away from hardware-dependent gatekeepers.
Growth Catalysts
- 5G spectrum allocation:The FCC's mid-band auction decisions in the United States enable sub-20 millisecond latency for untethered XR streaming at scale.
- Volumetric capture pipelines:Film studios and broadcasters deploy spatial video systems for synchronous avatar-based concerts, reducing location production costs.
- South Korea's metaverse standards:The Ministry of Science and ICT mandates domestic platform interoperability, accelerating creator-economy tool adoption.
Market Restraints
- GPU supply concentration:Foundry capacity constraints in Taiwan create bottlenecks for real-time rendering hardware procurement.
- Biometric data friction:The EU's GDPR and AI Act impose algorithmic transparency requirements on emotion-tracking features in immersive venues.
- Edge infrastructure capex:Distributed server deployment for low-latency streaming demands sustained capital commitment without guaranteed audience monetization.
Strategic Opportunities
- United Kingdom creator tooling:London's concentration of broadcast engineering talent supports platform localization for English-language markets.
- Blockchain ticketing layers:Secondary market control through programmable smart contracts captures margin pools from digital collectibles and access rights.
- AI-driven NPC generation:Large language model integration with real-time 3D engines enables persistent narrative worlds without scripted content pipelines.
Industry Challenges
- Volumetric video post-production:The shortage of technicians trained in spatial editing software delays immersive content release schedules.
- Cross-platform avatar portability:Proprietary rigging standards force studios to rebuild character assets for each distribution environment.
- Legacy broadcast integration:Traditional linear networks face technical debt when inserting real-time rendered segments into established transmission workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metaverse in Entertainment Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $451.93 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Social Experiences, Games Application: Live Events, Interactive Storytelling, Gaming Tournaments, Virtual Concerts Technology: Blockchain, 3D Modeling, AI Integration, Streaming Services End User: Gamers, Content Creators, Event Organizers, Casual Users |
| Companies Covered | Epic Games, NVIDIA, Roblox, AmazeVR, Gamefam, The Sandbox, Unity, Fortnite, Decentraland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metaverse in Entertainment Market Strategic Shifts
Real-time 3D engines are migrating from pre-rendered visualization tools to live production infrastructure, compressing post-production timelines and enabling audience co-creation during broadcast events. This shift demands new skill profiles at the intersection of game development and traditional media workflows.
Neural radiance fields (NeRFs) are virtualizing location scouting and set construction for film and live entertainment producers. Streaming platforms adopt these lightweight 3D representations to generate immersive backdrops without physical stage builds. The technology is virtualizing asset creation pipelines, reducing location permits and travel logistics for virtual concert tours.
The EU AI Act's emotion recognition restrictions are forcing immersive venue operators to rearchitect biometric data collection in European deployments. Compliance teams must document algorithmic decision pathways for audience sentiment analysis tools. Germany's regional data protection authorities are already enforcing these provisions against virtual event platforms using facial expression tracking for engagement metrics.
Audience participation models are shifting from passive viewership to synchronous avatar-based co-presence at scale. Virtual concert promoters now sell tiered access based on proximity to performers and interaction depth rather than seat location. South Korea's gaming-originated platforms demonstrate this behavioral shift most visibly, where fans expect real-time influence over setlists and visual effects during livestreams.
Metaverse in Entertainment Market Segmentation
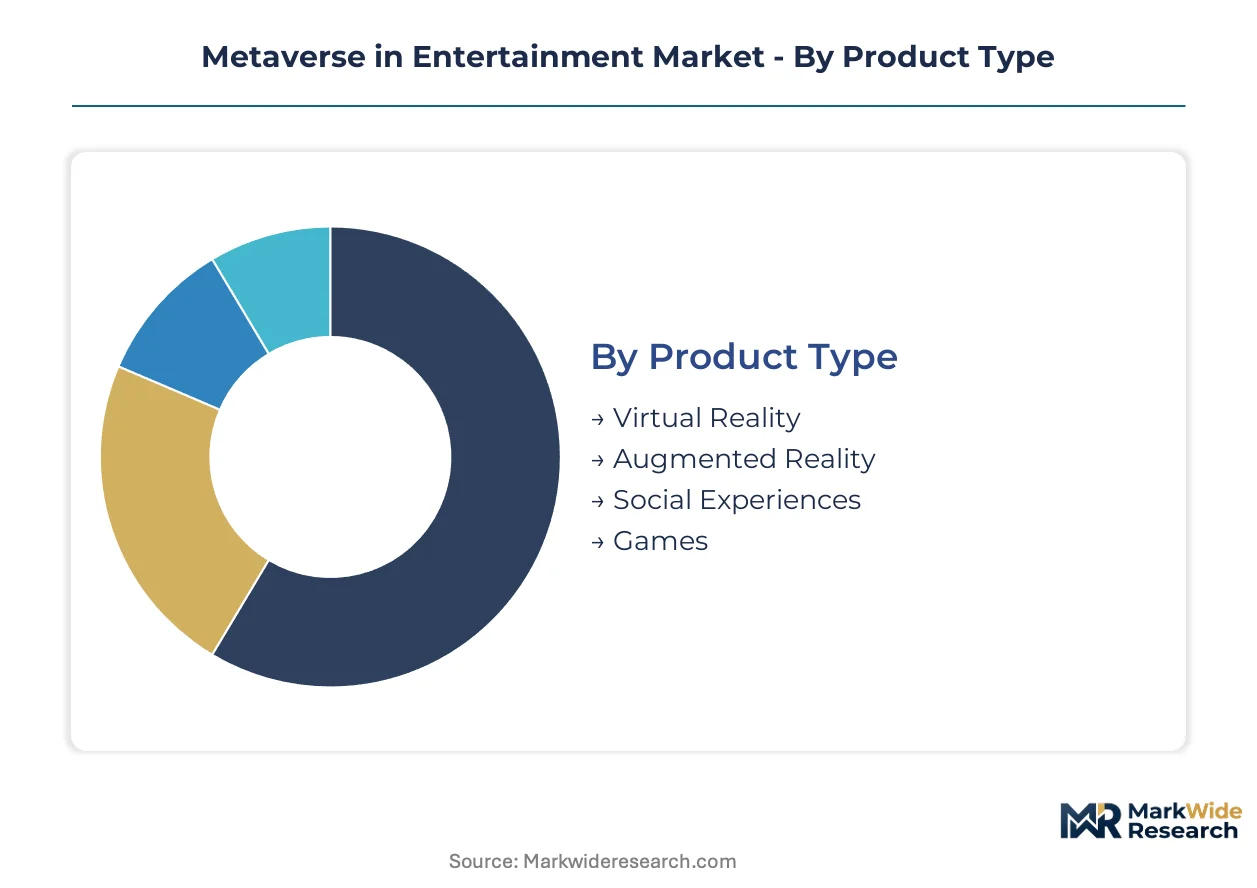
Metaverse entertainment platforms require distinct technical architectures, monetization models, and user acquisition strategies for each segment. Product type determines hardware dependencies and development costs. Application focus shapes latency requirements and synchronous capacity. Technology stack choices lock in interoperability constraints. End user profiles drive pricing elasticity and engagement depth.
Product Type:
After-sales service intensity varies dramatically across immersive hardware and software categories, with tethered systems demanding ongoing technical support while cloud-native platforms shift maintenance burdens to vendors.
- Virtual Reality:Head-mounted displays with six-degrees-of-freedom tracking and haptic feedback controllers deliver full sensory immersion. Demand concentrates in South Korea and the United States where 5G density supports untethered streaming; GPU supply bottlenecks from Taiwan foundries constrain headset production scaling.
- Social Experiences:Persistent avatar-based environments prioritize synchronous interaction over graphical fidelity. Platforms in the United Kingdom leverage London's broadcast engineering talent for real-time moderation tools; the EU AI Act's biometric restrictions force emotion-tracking feature redesigns for European deployments.
- Augmented Reality:Smartphone and glasses-based overlays blend digital content with physical spaces.
- Games:Interactive rule-based environments span casual mobile titles to competitive esports infrastructure.
Social Experiences holds the largest share; momentum sits with Virtual Reality.
Application:
Cost tier differentiation separates location-based productions requiring physical venue partnerships from purely virtual deployments with minimal marginal cost per additional attendee.
- Gaming Tournaments:Competitive esports events with real-time spectator interaction and prize pool mechanics. South Korean platforms demonstrate steepest audience growth curves where fans expect direct influence over match conditions; edge infrastructure capex demands sustained capital commitment without guaranteed monetization.
- Virtual Concerts:Synchronous avatar-based performances with tiered proximity access replacing traditional seat location pricing. Volumetric capture pipelines reduce location production costs for film studios and broadcasters; the shortage of spatial editing technicians delays content release schedules.
- Live Events:Real-time conferences, product launches, and ceremonial gatherings in persistent environments.
- Interactive Storytelling:Branching narrative experiences where audience choices reshape plot progression.
Gaming Tournaments holds the largest share; Virtual Concerts are climbing the fastest.
Technology:
Volume concentration favors infrastructure layers with network effects, where early platform adoption creates de facto standards that subsequent entrants must support.
- Blockchain:Distributed ledger systems enabling programmable ownership, secondary market royalties, and verifiable scarcity for digital collectibles. Smart contract ticketing layers capture margin pools from access rights; the EU's GDPR imposes algorithmic transparency requirements on wallet-linked identity verification.
- AI Integration:Large language model-driven NPC generation and real-time content personalization. Persistent narrative worlds deploy without scripted content pipelines; compliance teams must document decision pathways for European sentiment analysis tools.
- 3D Modeling:Asset creation pipelines for environments, characters, and objects.
- Streaming Services:Cloud-based content delivery with adaptive bitrate management.
AI Integration holds the largest share; Blockchain is gaining share fastest.
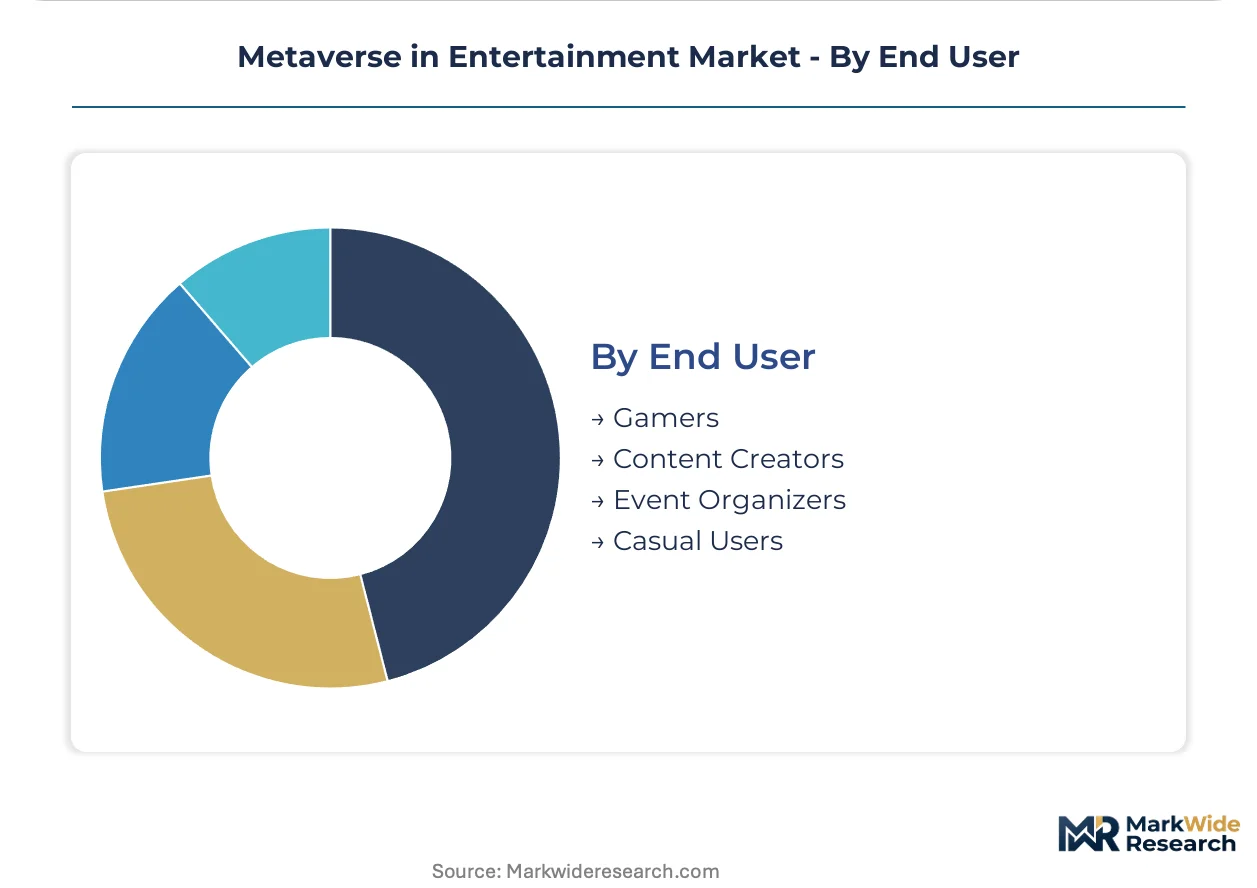
End User:
Customer type segmentation reveals divergent willingness-to-pay curves, with professional creators investing in production tools while casual audiences prioritize low-friction access.
- Content Creators:Professional and semi-professional producers building immersive experiences for monetized distribution. South Korea's metaverse standards accelerate creator-economy tool adoption; cross-platform avatar portability forces asset rebuilds for each distribution environment.
- Event Organizers:Venues, promoters, and brands commissioning bespoke virtual productions. London's broadcast engineering concentration supports platform localization; legacy broadcast networks face technical debt inserting real-time rendered segments into established workflows.
- Gamers:Competitive and recreational players seeking interactive entertainment.
- Casual Users:Episodic visitors prioritizing social presence over skill-based engagement.
Content Creators holds the largest share; momentum sits with Event Organizers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Ministry of Science and ICT metaverse standards program accelerates domestic platform interoperability and creator-economy tool adoption. The United States FCC mid-band spectrum auctions enable sub-20 millisecond latency for untethered XR streaming at scale. The United Kingdom leverages London's broadcast engineering concentration for real-time moderation and localization infrastructure.
United States
Cloud rendering partnerships and volumetric capture pipelines drive studio investment in virtual production infrastructure. The FCC shapes competitive dynamics through 5G spectrum allocation rules that determine untethered XR streaming density. Los Angeles anchors film industry virtual production adoption, while Austin and Seattle clusters concentrate real-time engine development talent.
South Korea
Gaming-originated platforms demonstrate steepest audience growth curves where fans expect real-time influence over setlists and visual effects. The Ministry of Science and ICT enforces national metaverse standards that accelerate domestic platform interoperability. Seoul Capital Area hosts the densest concentration of creator-economy platforms and synchronous avatar-based concert infrastructure.
United Kingdom
Broadcast engineering talent concentration supports platform localization for English-language markets and real-time moderation tool development. The EU AI Act and GDPR impose algorithmic transparency requirements on emotion-tracking features in immersive venues. London's Soho and Shoreditch clusters house volumetric capture studios serving virtual concert and interactive narrative producers.
Japan
METI industrial policy frameworks support cross-industry collaboration between entertainment platforms and telecommunications infrastructure providers. The country's national standards body coordinates with ISO and IEC on immersive content interoperability specifications. Tokyo's Akihabara and Shibuya districts concentrate location-based VR entertainment venues and virtual idol production studios.
Germany
Regional data protection authorities enforce GDPR and EU AI Act provisions against virtual event platforms using facial expression tracking. The country's national media regulator oversees compliance requirements for biometric data collection in immersive venues. Bavaria's Munich media cluster and Berlin's startup ecosystem host spatial audio and haptic feedback R&D facilities.
Metaverse in Entertainment Market Competitive Environment
Channel-controlling players compete with product-specialist players for leverage over immersive content distribution and real-time rendering infrastructure. The market exhibits tiered concentration where engine-technology holders, platform operators, and content studios occupy distinct competitive positions. Three archetypes dominate: infrastructure-anchored technology providers, creator-economy platform operators, and virtual production service specialists. Dominant competitive moves include cloud rendering partnership formations and volumetric capture pipeline integrations that compress capital requirements for mid-tier producers.
Within the infrastructure-anchored tier, Epic Games and NVIDIA exemplify technology-ecosystem strategies that underpin real-time 3D rendering for film and broadcast clients. Roblox occupies a position representing creator-economy platform models where user-generated content drives recurring engagement without studio-level production budgets. These three companies anchor distinct competitive vectors: engine licensing, hardware acceleration, and participatory platform economics.
| Leading Market Players |
|---|
| Epic Games |
| NVIDIA |
| Roblox |
| AmazeVR |
| Gamefam |
| The Sandbox |
| Unity |
| Fortnite |
| Decentraland |
| Others |
Value Chain & Pricing Dynamics
GPU foundry concentration in Taiwan funnels margin capture toward cloud rendering vendors who bundle compute cycles with creative tools, compressing what immersive studios retain from end-client contracts. This upstream bottleneck reshapes where value accrues across virtual production pipelines.
Pricing Analysis
Certification level for volumetric capture workflows creates the primary spread between premium virtual concert productions and standard social experience deployments. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling real-time ray-tracing infrastructure and dedicated edge nodes. Cost compression in mid-tier immersive content is intensifying because cloud rendering partnerships democratize access to previously capital-intensive tools. Event organizers show the least price sensitivity given client-facing deliverable requirements, while casual users gravitate toward ad-supported or freemium entry points.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for headset manufacturers dependent on rare earth magnet assemblies. Taiwan, South Korea, and the United States anchor GPU and advanced semiconductor supply for real-time rendering hardware. The ecosystem draws from volumetric camera arrays, haptic feedback actuators, and photonics components for spatial audio systems. Single-source vulnerability concentrates in Taiwan foundry capacity for high-performance compute chips. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales to broadcast studios and venue operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards early platform scale with durable defensive moats rooted in creator-side network effects and multi-homing costs for established virtual production pipelines.
For Market Incumbents: Pre-empt displacement from asset-light cloud rendering entrants by deepening captive supply of edge infrastructure in the United States and South Korea. Lock in exclusive volumetric capture studio partnerships before mid-tier producers achieve independent pipeline competence. Prioritize certification investment for EU AI Act-compliant emotion-tracking architectures to forestall regulatory arbitrage by emerging platforms.
For New Entrants and Emerging Players: Pursue white-space opportunity in United Kingdom broadcast localization services and German spatial audio R&D facilities where incumbent platform presence remains thin. The most penetrable segment sits with event organizers seeking modular virtual concert tooling without long-term engine licensing commitments. A direct-to-studio go-to-market angle bypasses platform gatekeeper economics entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed virtual production service specialists holding long-term broadcast network contracts but lacking proprietary rendering infrastructure. Five-to-ten year viability hinges on whether target platforms can migrate from project-based revenue to recurring SaaS-like creator tool subscriptions. The signal to watch is hyperscaler cloud marketplace placement as an indicator of distribution leverage and customer acquisition cost efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Partnership Formation | Epic Games and NVIDIA anchor real-time ray-tracing infrastructure for film and broadcast clients. |
| Volumetric Capture Pipeline Integration | AmazeVR and London-based studios reduce location production costs for synchronous avatar concerts. |
| Creator-Economy Platform Standardization | Roblox demonstrates user-generated content economics without studio-level production budgets. |
| 5G Edge Infrastructure Deployment | South Korea's Ministry of Science and ICT accelerates domestic platform interoperability through national standards. |
| Blockchain Ticketing Layer Development | Smart contract implementations capture secondary market margin pools from digital collectibles. |
Study Parameters
Operator-level perspectives from virtual production directors, broadcast technology officers, cloud infrastructure procurement leads, and immersive content studio founders anchored the qualitative base. Primary interview insights combined with secondary validation from FCC spectrum auction records, EU AI Act regulatory filings, South Korean Ministry of Science and ICT policy documents, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked projections across product type, application, technology stack, and end-user dimensions.
Scenario-bracketing around 5G deployment velocity, GPU supply elasticity, and regulatory enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include immersion hardware tier, synchronous capacity requirements, real-time rendering dependency, and regional creator-economy maturity. CAGRs derived from installed base growth curves, content production volume trajectories, and platform revenue per active user trends. Industry-specific inputs encompassed volumetric capture adoption rates and cloud rendering partnership formation velocity.
Sensitivities concentrate around Taiwan foundry capacity disruptions, EU biometric data enforcement escalations, and mid-band spectrum auction delays in the United States. Forecasts reflect documented assumptions about infrastructure deployment timelines and platform interoperability progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market