
 Europe and Benelux Volumetric Video Market | 2026-2036
Europe and Benelux Volumetric Video Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and Benelux Volumetric Video Market Analysis
A shortage of volumetric capture technicians and photogrammetry specialists is redrawing competitive boundaries across the region. Microsoft Corporation leverages its Azure cloud infrastructure to anchor volumetric streaming services for enterprise clients in Northern Europe. Dimension competes through its London-based capture stages, specializing in high-fidelity human performance digitization for film and broadcast applications.
Volumetric video captures three-dimensional spatial data from multiple synchronized camera arrays to generate free-viewpoint 3D assets, typically processing 50-200 gigabytes per minute of raw capture into compressed mesh sequences for real-time rendering engines. Capture Devices dominate current hardware revenue as studios in Belgium and the Netherlands invest in permanent multi-camera installations. Cloud Rendering represents the fastest-expanding technology segment, driven by Entertainment Studios and Gaming Companies seeking distributed processing for real-time volumetric streaming without on-site render farms.
The EU AI Act and GDPR impose strict biometric data handling requirements on volumetric capture operations involving human subjects, while the EU Green Deal pushes studios toward energy-efficient capture stages and low-power edge processing. EMA guidelines on medical imaging interoperability create secondary demand pathways for RealView Imaging Ltd and clinical volumetric visualization applications. Stakeholders must weigh cloud rendering migration timelines against emerging edge-AI deployment models before committing to fixed infrastructure investments.
Market Dynamics
The EU AI Act's biometric data classification rules are forcing studios to reengineer capture workflows, splitting volumetric pipelines between compliant human-digitization stages and unrestricted object-capture operations.
Growth Catalysts
- GDPR-compliant edge processing:Studios in the Netherlands are deploying localized render nodes to keep raw biometric data within jurisdictional boundaries, accelerating hardware refresh cycles for on-premise infrastructure.
- Entertainment studio expansion:German broadcasters are commissioning permanent volumetric stages for live sports free-viewpoint replay systems, creating sustained equipment demand.
- EMA imaging interoperability:Medical visualization standards are opening secondary demand pathways for clinical volumetric capture in surgical planning and radiology departments across Belgium and France.
Market Restraints
- Specialized labor scarcity:The shortage of photogrammetry technicians and multi-camera calibration specialists concentrates technical capability in Amsterdam and London, inflating project costs for Benelux studios.
- High-fidelity storage costs:Raw capture volumes of 50-200 gigabytes per minute strain archival budgets, particularly for independent production houses without cloud rendering contracts.
- GPU supply concentration:Dependence on NVIDIA and AMD accelerator cards for real-time mesh processing creates vulnerability to semiconductor allocation disruptions.
Strategic Opportunities
- Underpenetrated French regions:Outside Paris, Lyon and Marseille lack permanent volumetric facilities, presenting first-mover advantages for stage operators targeting regional advertising and corporate training markets.
- EU Green Deal incentives:Energy-efficient capture stage certifications unlock public co-funding for studios retrofitting LED lighting and liquid-cooled rendering clusters in the Netherlands.
- Neural compression convergence:Integration of AI-based mesh encoding with traditional photogrammetry promises tenfold bandwidth reduction for real-time streaming applications.
Industry Challenges
- Biometric consent workflow complexity:GDPR Article 9 special category data rules require granular actor permissions for each capture session, extending pre-production timelines and legal review costs.
- Legacy broadcast integration:SDI infrastructure and traditional 2D production pipelines resist seamless volumetric asset incorporation, demanding custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and Benelux Volumetric Video Market |
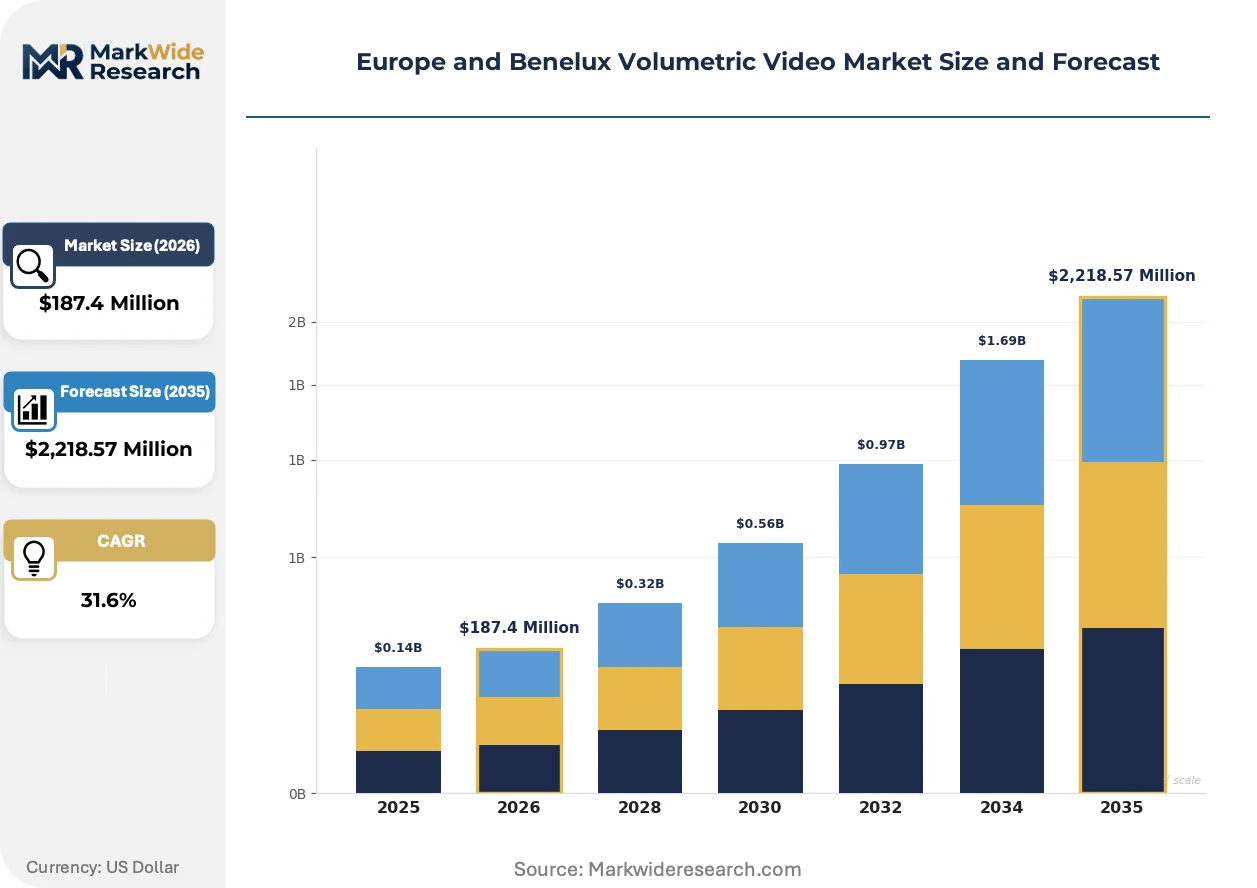
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Playback Solutions, Capture Devices, Editing Software, Streaming Platforms End User: Entertainment Studios, Gaming Companies, Educational Institutions, Advertising Agencies Technology: Depth Sensors, Projection Mapping, Cloud Rendering, Real-Time Processing Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Microsoft Corporation, Google LLC, Dimension, RealView Imaging Ltd, 4Dviews, Imverse SA, Sense of Space, Canon Inc., EF EVE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and Benelux Volumetric Video Market Emerging Trajectories
Real-time neural rendering is compressing the gap between capture and distribution, enabling live volumetric broadcasts without the multi-hour processing delays that constrained earlier deployments.
Neural radiance fields (NeRFs) and Gaussian splatting techniques are displacing traditional polygon mesh workflows in previsualization and virtual production stages. French gaming studios are adopting these methods for rapid environment prototyping, cutting asset iteration cycles from weeks to hours. The shift is compressing hardware requirements for mid-fidelity applications while pushing premium capture toward hybrid pipelines.
The EU AI Act's biometric data classification framework is redefining operational boundaries for studios handling human performance capture. Productions must now segment pipelines between high-risk biometric processing subject to conformity assessment and lower-risk object digitization exempt from audit. German facilities are responding by architecting physically separated capture stages with distinct data governance protocols.
Subscription-based rendering capacity is supplanting capital-intensive on-premise farm investments among mid-tier production houses. Dutch content creators are accessing distributed cloud mesh processing through usage-tiered contracts, converting fixed infrastructure costs to variable production budgets. This model is most visible in Amsterdam's media cluster, where studios prioritize operational flexibility over asset ownership.
Europe and Benelux Volumetric Video Market Segmentation
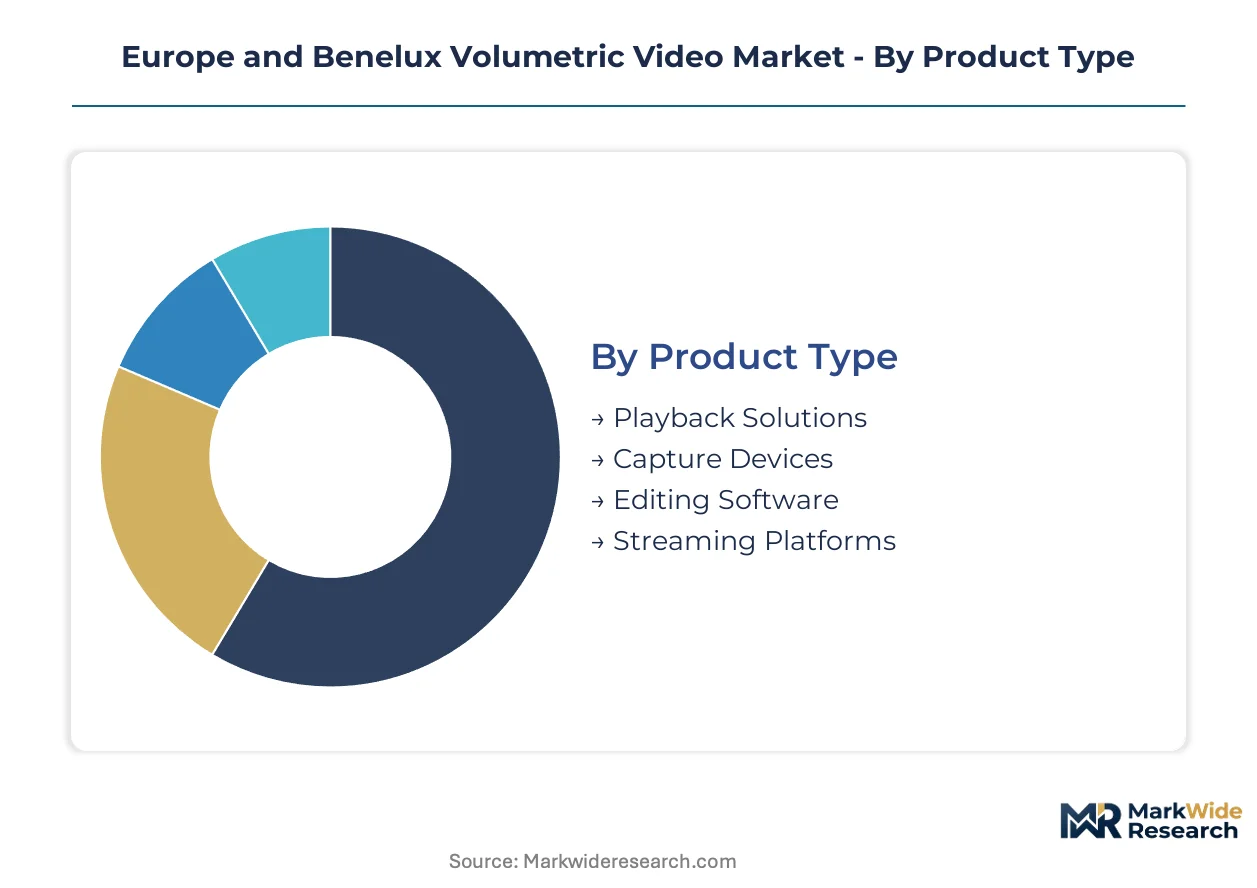
Volumetric video workflows fragment across specialized hardware, software, and service layers. Each segment carries distinct compliance obligations under the EU AI Act and GDPR, particularly for biometric data handling.
Product Type:
GDPR Article 9 special category data rules impose divergent certification requirements across hardware and software categories, with biometric-capable capture equipment facing stricter conformity assessment than playback-only solutions.
- Capture Devices:Multi-camera arrays and synchronized sensor rigs generate raw volumetric data at 50-200 gigabytes per minute. German broadcasters and Dutch studio operators are deploying permanent installations for live sports free-viewpoint replay systems, driving sustained equipment procurement despite high capital intensity.
- Streaming Platforms:Distributed mesh delivery infrastructure enables real-time volumetric broadcasting without on-premise render farms. Amsterdam's media technology cluster hosts the densest concentration of platform deployments, with Dutch content creators prioritizing operational flexibility through subscription-based capacity.
- Playback Solutions:Compressed mesh sequence decoders for real-time rendering engines.
- Editing Software:Photogrammetry pipeline tools for mesh refinement and sequence compression.
Capture Devices handles the majority of throughput; Streaming Platforms is the fastest mover on share.
End User:
Cost tier differentiation separates capital-intensive permanent stage operators from variable-budget production houses accessing cloud rendering.
- Entertainment Studios:Film and broadcast producers operating permanent volumetric stages in London, Amsterdam, and Berlin. French facilities are architecting physically separated capture stages with distinct data governance protocols to segment biometric from object-digitization pipelines under EU AI Act requirements.
- Gaming Companies:Interactive entertainment developers leveraging neural radiance fields and Gaussian splatting for rapid environment prototyping. French studios are cutting asset iteration cycles from weeks to hours, compressing hardware requirements for mid-fidelity applications.
- Advertising Agencies:Campaign producers sourcing regional stage capacity for short-duration commercial shoots.
- Educational Institutions:Universities and research centers deploying capture systems for digital preservation and medical visualization training.
Entertainment Studios commands the largest share of fixed infrastructure investment; Gaming Companies is expanding most quickly as neural rendering adoption accelerates.
Technology:
Application maturity separates established photogrammetry methods from emerging AI-driven compression techniques.
- Cloud Rendering:Distributed GPU clusters processing raw capture into compressed mesh sequences without on-site render farms. Dutch mid-tier production houses are converting fixed infrastructure costs to variable production budgets through usage-tiered contracts.
- Real-Time Processing:Edge-AI deployment models enabling live volumetric broadcasts without multi-hour processing delays. German facilities are retrofitting liquid-cooled rendering clusters to meet EU Green Deal energy-efficiency certifications.
- Depth Sensors:Structured light and time-of-flight cameras for spatial data acquisition.
- Projection Mapping:Calibrated display systems for volumetric content presentation.
Cloud Rendering dominates current migration timelines; Real-Time Processing is climbing the fastest as edge deployment models mature.
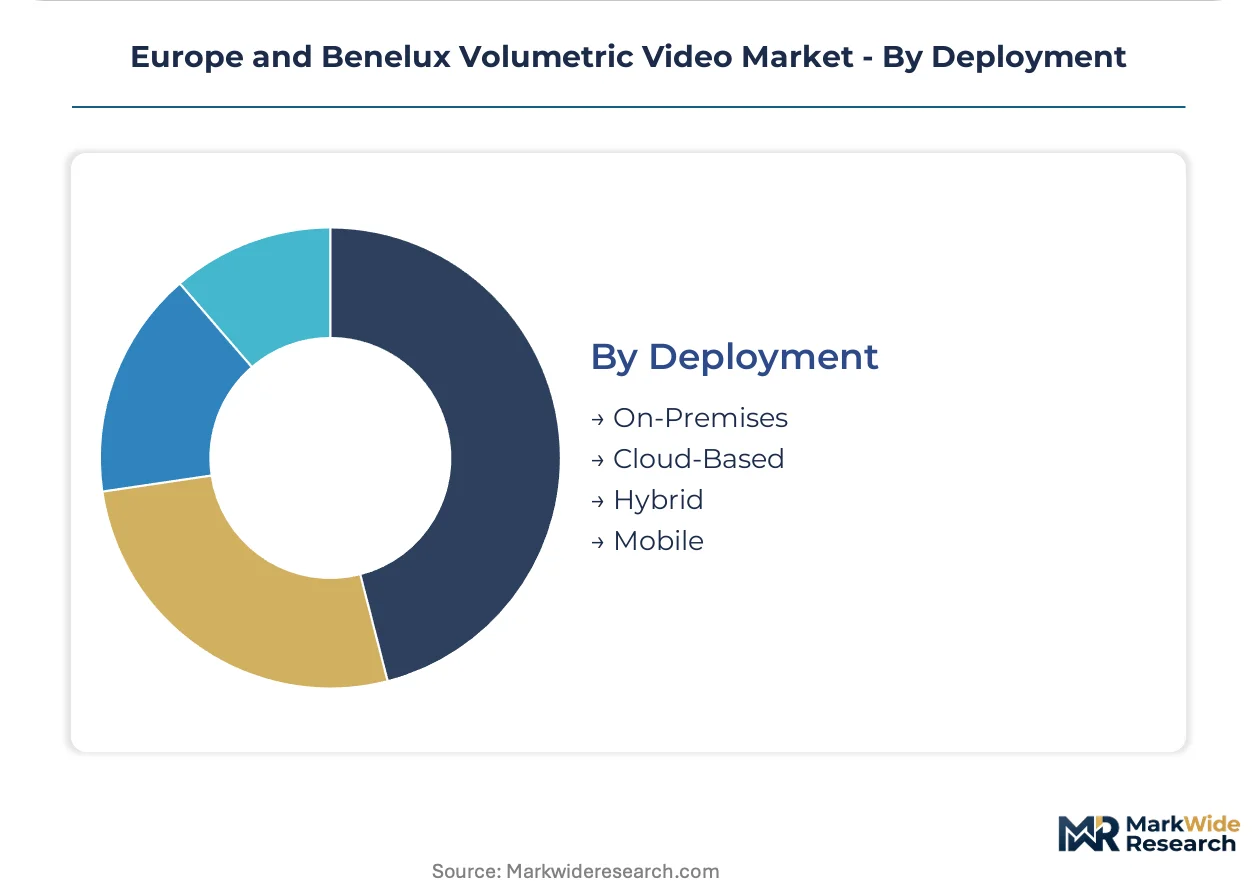
Deployment:
Volume concentration reflects jurisdictional data sovereignty requirements and infrastructure ownership preferences.
- On-Premises:Permanent capture stages with localized render nodes keeping raw biometric data within GDPR jurisdictional boundaries. Netherlands-based studios are accelerating hardware refresh cycles to maintain compliance.
- Hybrid:Split pipelines combining edge capture with cloud finishing, allowing segmentation of high-risk biometric processing from lower-risk object digitization. German operators are pioneering this architecture to satisfy EU AI Act conformity assessment requirements.
- Cloud-Based:Fully distributed processing with no local infrastructure ownership.
- Mobile:Transportable capture rigs for location-based production.
On-Premises retains the largest installed base; Hybrid is gaining share fastest as regulatory complexity demands architectural flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns split sharply across the region: Dutch studios prioritize permanent capture infrastructure for broadcast applications, while French operators favor mobile deployments for commercial production, and German facilities invest heavily in regulatory-compliant biometric processing architectures.
Netherlands
Amsterdam's media technology cluster hosts the densest concentration of volumetric production facilities in Europe, with broadcasters commissioning live sports free-viewpoint replay systems. GDPR Article 9 compliance requirements are accelerating hardware refresh cycles for localized render nodes that keep raw biometric data within Dutch jurisdictional boundaries. Rotterdam and Eindhoven are emerging as secondary hubs for cloud rendering capacity serving mid-tier production houses.
Germany
German entertainment studios are architecting physically separated capture stages to segment biometric from object-digitization pipelines under EU AI Act conformity assessment rules. The KBA and national data protection authorities are enforcing strict audit requirements for human performance digitization operations. Berlin and Munich anchor the permanent stage investment wave, with broadcasters deploying multi-camera arrays for live volumetric broadcasting infrastructure.
France
French gaming studios are displacing traditional polygon mesh workflows with neural radiance fields and Gaussian splatting for rapid environment prototyping, compressing asset iteration cycles from weeks to hours. ANSM and CNIL guidelines on biometric data handling are reshaping consent workflows for human capture operations. Outside Paris, Lyon and Marseille lack permanent volumetric facilities, presenting expansion opportunities for regional advertising and corporate training markets.
Belgium
Belgian medical visualization demand is climbing under EMA imaging interoperability guidelines, with clinical volumetric capture penetrating surgical planning and radiology departments in Brussels and Antwerp. The EU Green Deal is pushing studios toward energy-efficient LED lighting and liquid-cooled rendering clusters to unlock public co-funding. Brabant's technology corridor is attracting edge-AI deployment models for real-time processing applications.
Europe and Benelux Volumetric Video Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud infrastructure providers and dedicated capture stage operators occupying distinct competitive positions. The market structure reflects dual concentration: hyperscale technology platforms anchor streaming and rendering services, while boutique studios compete on photogrammetry fidelity and regulatory compliance expertise. Two strategic archetypes dominate: vertically integrated cloud-to-capture pipeline operators, and specialized stage-as-a-service providers. Competitive moves center on M&A activity targeting photogrammetry talent pools, and strategic partnerships bridging hardware procurement with compliance consulting.
Among integrated technology platforms, Microsoft Corporation anchors enterprise volumetric streaming through Azure cloud infrastructure deployments across Northern Europe. Dimension exemplifies the specialized capture stage archetype, operating high-fidelity human performance digitization facilities from its London base. RealView Imaging Ltd occupies a clinical visualization position, serving medical imaging interoperability requirements under EMA guidelines. These three represent the competitive spectrum: hyperscale cloud, premium capture services, and regulated healthcare applications.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Dimension |
| RealView Imaging Ltd |
| 4Dviews |
| Imverse SA |
| Sense of Space |
| Canon Inc. |
| EF EVE |
| Others |
Supply Flow & Price Mechanics
Permanent multi-camera installations in Amsterdam and Berlin generate scale economies that compress per-minute capture costs while concentrating procurement power among Dutch and German broadcasters. This capacity utilization dynamic establishes price floors for mid-tier production houses and shapes supplier tiering across the region.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement, with German broadcasters locking multi-year capacity commitments for live sports free-viewpoint replay systems. Price differentiation hinges on GDPR compliance certification tier and real-time processing capability, with biometric-capable stages commanding premium positioning. Cost compression in mid-fidelity cloud rendering tiers is intensifying because Dutch studios are converting fixed infrastructure to subscription-based variable budgets. Independent production houses exhibit highest price sensitivity, while national broadcasters prioritize regulatory assurance over unit economics.
Supply Chain Analysis
NVIDIA and AMD GPU allocation bottlenecks in Taiwan and the United States tether real-time mesh processing capacity to semiconductor foundry scheduling. Capture hardware draws from Japanese precision optics, German sensor engineering, and Chinese LED array manufacturing. Single-source vulnerability concentrates in AI accelerator supply, where allocation disruptions propagate directly into studio deployment timelines. Distribution runs through Amsterdam's media technology cluster for platform services and direct manufacturer relationships for permanent stage installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around neural compression interoperability, as AI-based mesh encoding convergence demands ecosystem coordination between capture hardware vendors and cloud rendering providers.
For Market Incumbents: Consolidate photogrammetry talent pools through targeted acquisition of Amsterdam and London calibration specialists to defend against cloud-native entrants eroding premium capture margins. Anchor backward integration into edge-AI silicon partnerships to secure GPU allocation priority as NVIDIA supply constraints persist. Prioritize GDPR Article 9 compliance consulting capabilities as a channel control lever against mid-tier competitors. For New Entrants and Emerging Players: Anchor in Lyon and Marseille's regional advertising markets, where permanent volumetric facility absence creates immediate white-space access. Target corporate training applications in French regions outside Paris, where mobile deployment flexibility outweighs broadcast-grade fidelity requirements. Pursue EU Green Deal certification co-funding as a go-to-market differentiator for energy-efficient LED capture stage offerings. For Investors and Strategic Acquirers: Clinical visualization specialists with EMA imaging interoperability positioning represent the most defensible acquisition archetype, as medical volumetric demand decouples from entertainment cyclicality. Frame long-term viability around 5-10 year regulatory compliance service attach rates rather than hardware depreciation cycles. Monitor neural radiance field adoption velocity in French gaming studios as the signal indicating traditional photogrammetry obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Edge Infrastructure Deployment | Localized render nodes in Netherlands satisfy Article 9 biometric data sovereignty requirements. |
| Neural Compression R&D Partnership | AI-based mesh encoding integration promises tenfold bandwidth reduction for real-time streaming. |
| Regional Stage Network Expansion | Lyon and Marseille facilities capture underpenetrated French advertising and corporate training demand. |
| EU Green Deal Certification Program | Energy-efficient LED and liquid-cooled clusters unlock public co-funding for Dutch retrofit investments. |
| Hybrid Pipeline Architecture Development | Split biometric-object capture workflows satisfy EU AI Act conformity assessment segmentation rules. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EMA imaging interoperability guidelines, EU AI Act biometric classification frameworks, and hyperscaler cloud infrastructure disclosures. Primary interviews engaged volumetric capture stage operators, broadcast technology procurement leads, photogrammetry specialists, and medical visualization software engineers. Secondary sources included GDPR enforcement precedent databases, Dutch media technology cluster investment filings, and German broadcaster equipment procurement records. Bottom-up equipment deployment counts triangulate against top-down entertainment studio capital expenditure estimates.
Segmentation dimensions modeled span capture device type, deployment architecture, end-user vertical, and technology layer across the analysis window. Cloud rendering migration timelines, neural radiance field adoption curves, and biometric consent workflow complexity indices inform growth trajectory derivation. Value projections incorporate hardware procurement cycles, subscription-based capacity conversion rates, and regulatory compliance service attach modeling.
Decision-makers should treat outputs as directional under stable EU AI Act enforcement intensity and continued GPU supply allocation continuity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EMA medical imaging standard evolution and French gaming studio neural rendering adoption rates shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Augmented Reality Gaming Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market