
 Augmented Reality Gaming Market | 2026-2036
Augmented Reality Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality Gaming Market Intelligence
Enterprise training departments is reorganizing demand alongside individual gamers as corporations adopt AR simulations for workforce upskilling and safety protocols. Meta leverages its Reality Labs division to anchor hardware-software integration across consumer and commercial verticals. Niantic sustains location-based AR expertise through persistent world-mapping infrastructure that powers both entertainment and enterprise applications. Epic Games differentiates via Unreal Engine's real-time rendering capabilities that reduce development cycles for immersive titles.
Augmented Reality Gaming overlays digital content onto physical environments through camera-fed spatial computing, typically requiring sub-20 millisecond motion-to-photon latency to prevent simulator sickness and maintain immersion. The technology fuses computer vision, simultaneous localization and mapping, and gesture recognition to create persistent mixed-reality experiences for entertainment and skill development. Headset games currently occupy the highest-margin tier as dedicated hardware commands premium pricing and longer session engagement. Mobile games leads volume throughput because smartphone penetration eliminates dedicated hardware barriers for casual users. Markerless technology is displacing marker-based systems as depth-sensing cameras and neural scene understanding mature across iOS and Android flagships.
The Federal Communications Commission governs spectrum allocation for low-latency multiplayer AR streaming in the United States, while the EU AI Act imposes transparency requirements on algorithmic content generation within immersive environments. China's Ministry of Industry and Information Technology enforces content review protocols for AR applications distributed through domestic app stores. Stakeholders must monitor evolving data localization mandates and hardware certification standards as these frameworks determine market access timelines and development cost structures.
Market Dynamics
Markerless spatial mapping is compressing hardware friction for immersive gameplay, while enterprise training departments emerge as a parallel demand archetype alongside individual consumers. This dual-track demand structure is redrawing competitive positioning across hardware-software integration layers.
Growth Catalysts
- 5G Infrastructure Deployment:United States, China, and Germany are building out low-latency networks that enable real-time multiplayer AR streaming without local processing bottlenecks. FCC spectrum allocation and MIIT network standards are accelerating rollout timelines.
- Enterprise Workforce Upskilling:Safety-critical industries are adopting AR simulations for hazard training and procedural certification. Corporate training budgets are shifting from classroom modules to persistent mixed-reality environments.
- Neural Scene Understanding:Depth-sensing cameras on iOS and Android flagships are enabling markerless tracking without dedicated peripherals. Consumer smartphone penetration eliminates hardware barriers for casual gameplay entry.
Market Restraints
- Simulator Sickness Threshold:Sub-20 millisecond motion-to-photon latency requirements demand expensive edge computing infrastructure. Latency violations degrade user retention regardless of content quality.
- Content Review Protocols:China's MIIT enforces pre-distribution approval for AR applications, extending time-to-market for foreign developers. Localization mandates add compliance overhead without revenue certainty.
- Input Cost Volatility:Specialized optical waveguide components for AR headsets concentrate among Asian precision manufacturers. Supply tightness for micro-displays and LiDAR sensors squeezes hardware margins.
Strategic Opportunities
- Location-Based Entertainment:Persistent world-mapping infrastructure enables venue-scale immersive experiences beyond home use. Theme parks and retail installations represent underpenetrated deployment channels.
- EU AI Act Alignment:Transparency requirements for algorithmic content generation create compliance-as-a-service opportunities. Developers embedding explainable AI into procedural content gain regulatory pre-approval advantages.
- Gesture Recognition Convergence:Computer vision fusion with haptic feedback hardware enables controller-free interaction paradigms. Sports training and rehabilitation applications are adopting these input methods for motor skill development.
Industry Challenges
- SLAM Engineering Talent Scarcity:Simultaneous localization and mapping expertise concentrates among computer vision specialists with robotics backgrounds. Compensation premiums for this skill set inflate development costs.
- Hardware Certification Timelines:FCC equipment authorization and CE marking processes for head-worn displays extend 8-14 months. Certification delays misalign product launches with content release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality Gaming Market |
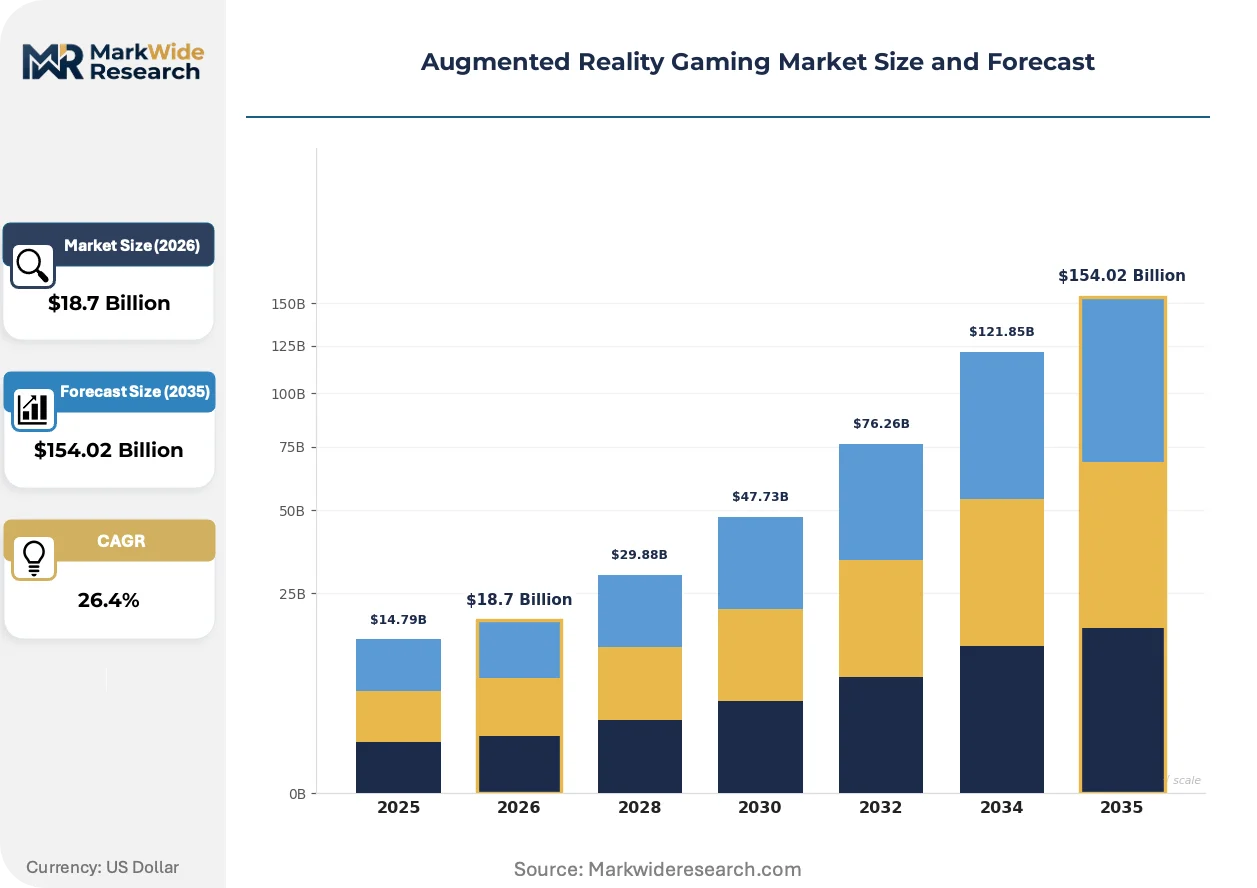
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Games, Console Games, PC Games, Headset Games End User: Individual Gamers, Educational Institutions, Gaming Cafes, Corporations Technology: Marker-Based, Markerless, Projection-Based, Superimposition Distribution Channel: Online Stores, Retail Outlets, Subscription Services, Direct Download |
| Companies Covered | Unity Technologies, Magic Leap, Niantic, Kevuru Games, Juego Studio, Meta, Epic Games, Wildnet Edge, Resolution Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality Gaming Market Strategic Shifts & Innovations
Spatial computing architectures are bifurcating between dedicated headsets and smartphone-mediated experiences, with software abstraction layers bridging hardware heterogeneity. This divergence is forcing content studios to optimize for divergent performance envelopes simultaneously.
Cloud-rendering pipelines are fragmenting the traditional compute boundary between device and edge. Developers are offloading heavy physics and lighting calculations to 5G-connected servers, enabling photorealistic scenes on lightweight hardware. Enterprise training simulations are adopting this architecture first, given their tolerance for infrastructure dependency and lower mobility requirements.
The EU AI Act's transparency mandates for algorithmic content generation are reshaping development workflows for procedural environments. Studios must now document training data provenance and decision logic for AI-generated assets. Location-based entertainment operators in Germany and France are front-running compliance to secure venue licensing advantages.
Subscription monetization is displacing upfront purchase models across mobile AR distribution channels. Freemium gameplay with cosmetic microtransactions dominates smartphone platforms, while enterprise buyers negotiate seat-based licenses for training modules. This bifurcation is most visible in the United States, where corporate procurement departments prefer predictable opex structures over hardware capex cycles.
Augmented Reality Gaming Market Segmentation
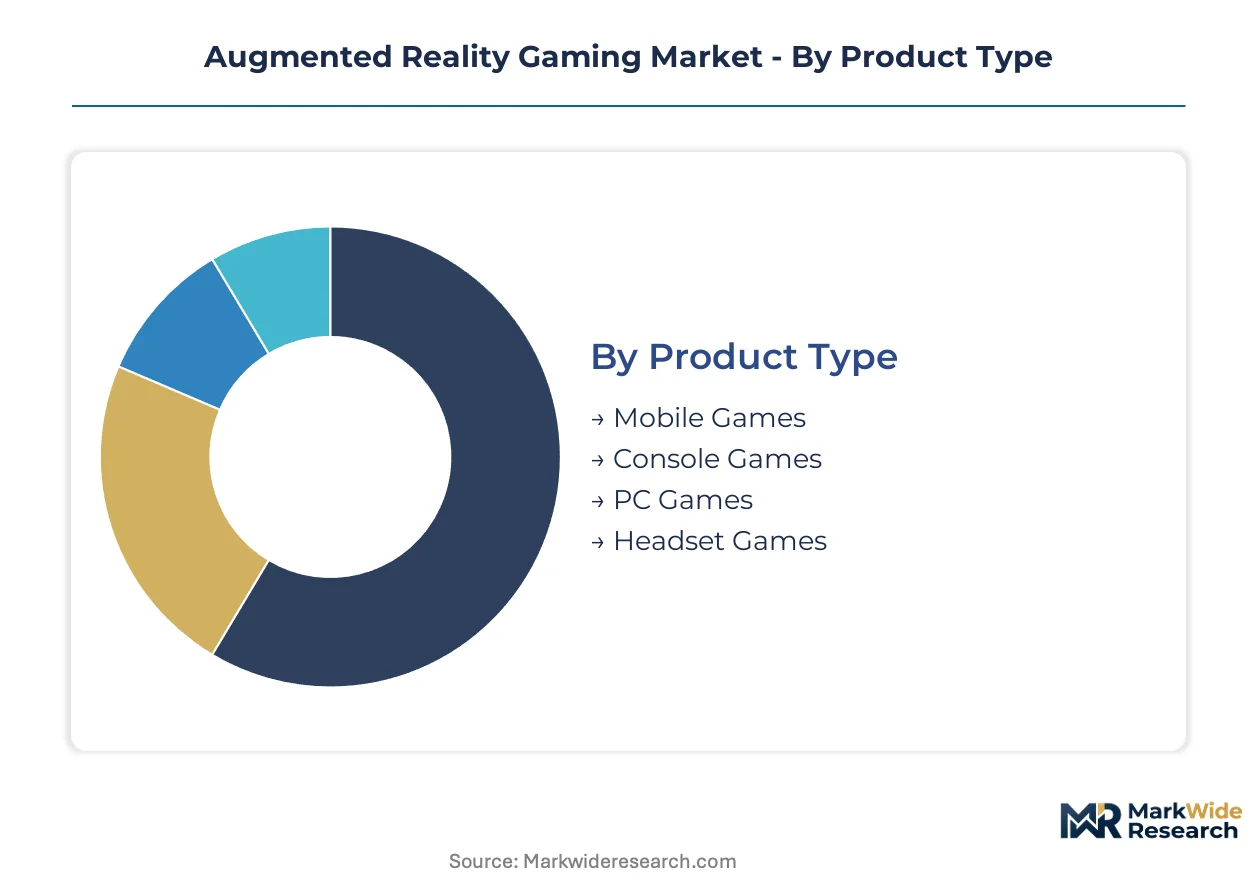
Segmentation reveals divergent hardware requirements and monetization models across AR gaming. Product architecture, end-user procurement patterns, and distribution economics create distinct competitive arenas with non-overlapping margin profiles.
Product Type:
FCC equipment authorization timelines and CE marking requirements for head-worn displays create 8-14 month certification gaps that advantage software-only product categories.
- Headset Games:Dedicated optical waveguide hardware commands premium pricing through immersive field-of-view and sub-20 millisecond latency compliance. Enterprise training departments in Germany and the United States absorb seat-based licensing for safety-critical simulations despite hardware capex cycles.
- Mobile Games:Depth-sensing camera penetration across iOS and Android flagships eliminates peripheral costs for casual entry. Volume concentrates in China where MIIT network standards accelerate 5G-enabled multiplayer streaming without local processing bottlenecks.
- Console Games:Living-room tethering limits spatial mobility but leverages existing controller familiarity. Sony and Microsoft ecosystem lock-in creates distribution friction for independent AR studios.
- PC Games:External camera and GPU upgrade requirements segment demand toward enthusiast hardware builders. Steam distribution reduces platform gatekeeping versus console certification.
Established volume favors mobile; emerging adoption favors headset.
End User:
Procurement authority separates consumer impulse purchases from corporate budget cycles with 12-18 month sales horizons.
- Corporations:Safety-critical industries deploy persistent mixed-reality environments for hazard certification and procedural upskilling. FCC-regulated spectrum allocation enables real-time multi-user training across distributed facilities in the United States.
- Individual Gamers:Smartphone-mediated casual gameplay dominates session frequency through freemium monetization. Niantic's persistent world-mapping infrastructure sustains location-based engagement in urban clusters.
- Educational Institutions:K-12 and university labs adopt markerless tracking for STEM visualization without dedicated hardware procurement. Budget constraints favor mobile-first deployment over headset investments.
- Gaming Cafes:Venue-scale installations require persistent spatial mapping for multiplayer arena experiences. Location-based entertainment in Germany front-runs EU AI Act compliance for procedural content transparency.
Seat-based licensing climbs fastest in corporate; transaction volume concentrates with individual gamers.
Technology:
Computer vision maturity is compressing the cost gap between marker-dependent and markerless spatial computing.
- Markerless:Neural scene understanding through depth-sensing cameras eliminates physical target placement. iOS and Android flagship penetration enables immediate consumer adoption without supply chain dependencies on printed markers.
- Marker-Based:Visual fiducial tracking retains relevance for controlled educational and industrial environments requiring absolute positional stability. Lower computational overhead extends battery life on mid-tier hardware.
- Projection-Based:Spatial light modulation projects interactive surfaces onto physical geometry without wearable hardware. Retail installations and museum exhibits adopt this for shared spectator experiences.
- Superimposition:Object recognition overlays digital twins onto specific physical items for maintenance and assembly guidance. Industrial AR in China integrates with MIIT-mandated content review protocols for factory-floor deployment.
Hardware friction favors markerless; precision requirements sustain marker-based in enterprise niches.
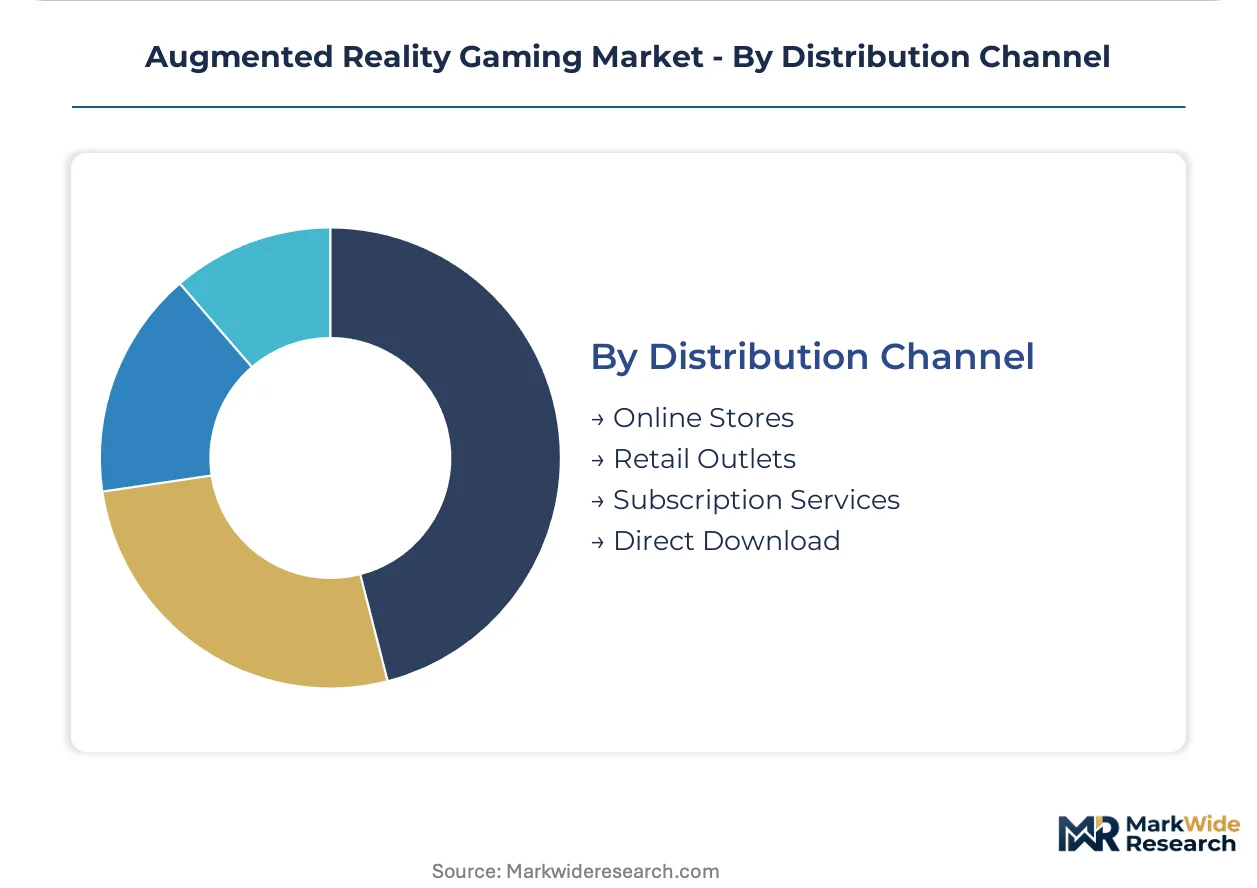
Distribution Channel:
Revenue recognition timing and platform economics vary dramatically between upfront purchase and recurring subscription models.
- Subscription Services:Predictable opex structures align with corporate procurement preferences in the United States. Cloud-rendering pipelines offload physics calculations to 5G edge infrastructure.
- Online Stores:Apple App Store and Google Play commission structures extract 15-30% of microtransaction revenue. Freemium cosmetic monetization dominates smartphone AR monetization.
- Direct Download:Developer-controlled distribution bypasses platform fees but sacrifices discoverability algorithms. PC gaming ecosystems tolerate this tradeoff for modding community access.
- Retail Outlets:Physical packaging and shelf placement sustain headset accessory sales through Best Buy and specialist gaming retailers. Boxed software margins collapse against digital distribution efficiency.
Recurring revenue expands fastest through subscription; volume throughput concentrates in online stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine fiber optic cables and 5G backbone networks underwriting real-time spatial computing traffic concentrate AR gaming infrastructure investment across three continents. Low-latency edge computing nodes cluster near these transmission assets to meet sub-20 millisecond motion-to-photon thresholds.
United States
Enterprise training departments in Texas and California drive B2B demand for persistent mixed-reality simulations. FCC spectrum allocation for millimeter-wave bands accelerates venue-scale multiplayer deployment. Los Angeles and Seattle anchor content studio clusters developing cloud-rendering pipelines for location-based entertainment.
China
MIIT network standards prioritize 5G standalone architecture that eliminates local processing bottlenecks for smartphone-mediated AR. Content review protocols enforce pre-distribution approval, extending foreign developer time-to-market. Shenzhen and Shanghai concentrate hardware manufacturing for depth-sensing camera modules and optical waveguide components.
Germany
EU AI Act transparency requirements for algorithmic content generation reshape procedural environment development workflows. Industrial AR adoption in Bavaria and Baden-Württemberg integrates factory-floor safety training with markerless spatial mapping. Berlin hosts venue-scale immersive entertainment operators front-running compliance for licensing advantages.
Japan
METI funding for spatial computing ecosystems supports consumer headset adoption alongside smartphone-flagship depth-sensing penetration. Tokyo and Osaka clusters fuse computer vision expertise with robotics SLAM engineering for gesture recognition convergence. Corporate training budgets shift toward persistent mixed-reality certification modules.
South Korea
Seoul Capital Area infrastructure supports real-time multiplayer streaming through government-backed 5G network densification. Busan-Ulsan industrial zones adopt AR simulations for shipbuilding safety protocols. MFDS-equivalent content frameworks for immersive applications remain under development, creating regulatory uncertainty for foreign studios.
Augmented Reality Gaming Market Key Industry Players
Listed leaders compete with private specialists across hardware-software integration layers, creating a bifurcated structure where scale-driven platforms coexist with focused tool vendors. The vendor base segments into three strategic archetypes: engine providers anchoring developer ecosystems, hardware-integrated platforms controlling distribution, and specialized studios monetizing location-based intellectual property. Dominant competitive moves include strategic partnerships bridging content and infrastructure gaps, plus technology licensing that abstracts hardware heterogeneity for cross-platform deployment.
Within the engine-provider tier, Unity Technologies and Epic Games exemplify divergent approaches to real-time rendering and developer tooling. Meta occupies a position spanning hardware-software integration through its Reality Labs division. Niantic sits within the location-based specialist archetype, leveraging persistent world-mapping infrastructure that powers both entertainment and enterprise applications. These three anchors represent distinct competitive vectors rather than direct substitutes, with each archetype capturing value at different layers of the spatial computing stack.
| Leading Market Players |
|---|
| Unity Technologies |
| Magic Leap |
| Niantic |
| Kevuru Games |
| Juego Studio |
| Meta |
| Epic Games |
| Wildnet Edge |
| Resolution Games |
| Others |
Cost & Logistics Intelligence
Markerless spatial mapping displaces printed fiducial targets across iOS and Android flagships, simultaneously shifting component sourcing from Asian precision manufacturers of optical markers to depth-sensing camera module suppliers in Shenzhen and Seoul while compressing per-unit hardware costs for casual gameplay entry.
Pricing Analysis
Volume-discount tiering separates enterprise seat-based licensing from individual freemium microtransactions. Premium headset hardware commands upfront capex cycles with extended service bundling, while smartphone-mediated casual gameplay monetizes through cosmetic in-app purchases. Pricing pressure stems from 5G infrastructure buildout costs passed through cloud-rendering subscription models. Corporate training departments in Germany and the United States exhibit lowest price sensitivity given safety-critical compliance requirements; individual smartphone gamers face highest elasticity.
Supply Chain Analysis
Shenzhen-Shanghai corridor chokepoints concentrate optical waveguide and LiDAR sensor production for AR headsets. Micro-display manufacturing draws from South Korean OLED fabs and Taiwanese semiconductor foundries. Supply chain risk centers on single-source vulnerability for precision optical components amid export control tightening. Distribution runs through Apple App Store and Google Play commission structures for mobile volumes, with direct enterprise licensing bypassing platform fees for corporate training deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through persistent world-mapping infrastructure that locks in location-based content ecosystems and raises switching costs for rival platforms.
For Market Incumbents: Consolidate SLAM engineering talent pools through targeted acquisition of computer vision specialists with robotics backgrounds. Deepen backward integration into depth-sensing camera module production to offset Asian precision manufacturer supply tightness. FCC equipment authorization timelines create certification bottlenecks that favor early movers with established regulatory affairs infrastructure. For New Entrants and Emerging Players: CE marking fast-track for head-worn displays opens regulatory pre-approval advantages in Germany and France under EU AI Act transparency mandates. White-space concentrates in location-based entertainment venue installations and gesture recognition convergence for sports rehabilitation applications. Go-to-market through gaming cafe channel partnerships bypasses platform commission extraction. For Investors and Strategic Acquirers: The market sits at an infrastructure-deployment phase that favors engine providers with developer ecosystem lock-in. Long-term viability hinges on cloud-rendering pipeline adoption across enterprise training verticals. Acquisition targets with persistent spatial mapping databases and explainable AI compliance tooling signal inflection readiness. Watch for 5G standalone architecture maturation in China as capacity utilization indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Engine providers embedding SLAM SDKs into Unity and Unreal workflows capture developer mindshare. |
| Strategic Partnership | Telecom operators bundling 5G subscriptions with cloud-rendering access accelerate consumer hardware adoption. |
| Acquisition of Specialist Firm | Location-based entertainment operators buying gesture recognition startups secure controller-free input patents. |
| Geographic Expansion | German venue operators front-running EU AI Act compliance gain licensing advantages in France and Netherlands. |
| Product Launch | Markerless tracking deployment on mid-tier Android hardware expands addressable market beyond flagship penetration. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings from spatial computing hardware vendors, MIIT network standard disclosures, and App Store analytics platforms. Interviews with AR studio technical directors, enterprise training procurement officers, FCC regulatory consultants, and 5G infrastructure planners inform demand-side validation. Bottom-up sizing of headset and mobile install bases triangulates against top-down TAM estimates from cloud-rendering capacity buildout disclosures.
Segmentation dimensions modeled span product architecture, end-user procurement authority, spatial computing technology maturity, and distribution channel economics across the projection horizon. CAGRs derive from hardware shipment trajectories, enterprise training budget reallocation patterns, and 5G network densification curves. Neural scene understanding penetration rates and SLAM engineering compensation inflation feed industry-specific forecast sensitivity.
Decision-makers should treat outputs as directional under assumptions of sustained 5G infrastructure investment and stable FCC spectrum allocation; material deviation in regulatory timelines or optical component supply would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and China content review protocol stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Augmented Reality (AR) in Entertainment
Metaverse in Entertainment Market
Augmented Reality (AR) in Entertainment
Digital Avatar Market
Augmented Reality (AR) in Entertainment
Europe Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Europe and Benelux Volumetric Video Market
Augmented Reality (AR) in Entertainment
AR Gaming Market
Augmented Reality (AR) in Entertainment
North America Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
AI in Media and Entertainment Market
Augmented Reality (AR) in Entertainment
Asia-Pacific Immersive Entertainment Market
Augmented Reality (AR) in Entertainment
Latin America Immersive Entertainment Market